
 Americas Analog IC Market | 2026-2036
Americas Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Analog IC Market Insights
Automotive OEMs is collapsing the legacy consumer-electronics-centric demand model that long governed Americas Analog IC procurement. Texas Instruments Incorporated leverages its 300-mm Richardson fab to sustain cost leadership in voltage regulators for EV powertrains. Analog Devices Inc. anchors high-performance signal processing portfolios across industrial automation and aerospace defense channels. NXP Semiconductors NV competes through automotive-qualified BiCMOS process expertise in sensor interfacing and battery monitoring systems.
Americas Analog IC refers to integrated circuits processing continuous electrical signals through transistor-level architectures, typically fabricated on 180-nm to 40-nm nodes using CMOS, BiCMOS, or SiGe processes for voltage regulation, amplification, and signal conditioning in power-limited environments. Voltage Regulators command the deepest margin pools as electrification applications multiply across automotive and industrial end users. Operational Amplifiers retain mature, high-volume positions in industrial equipment, while Sensor Interfacing grows fastest as IoT deployment and edge AI drive multi-channel precision acquisition requirements. Power Management applications concentrate design wins where thermal efficiency and quiescent current specifications determine socket access.
The U.S. CHIPS Act and Inflation Reduction Act together reshape demand by conditioning federal subsidies on domestic wafer fabrication and clean-energy supply chain localization. Mexico's Ministry of Economy and U.S. OSHA semiconductor safety frameworks further influence cross-border facility standards and workforce qualification protocols. Stakeholders must monitor how evolving EPA per- and polyfluoroalkyl substance restrictions and anticipated SEC climate disclosure rules alter material sourcing and foundry qualification timelines across the Americas supply base.
Market Dynamics
The U.S. CHIPS Act's domestic content mandates are restructuring foundry qualification timelines and supplier certification protocols across the Americas Analog IC supply base. Automotive electrification is compressing design-in cycles for precision signal chain components as OEMs consolidate voltage regulator and battery management sourcing.
Growth Catalysts
- Inflation Reduction Act:Clean-energy semiconductor procurement rules are conditioning federal incentive eligibility on North American wafer fabrication, redirecting analog IC demand toward domestic qualified sources.
- Guadalajara electronics corridor:Nearshoring momentum is concentrating precision manufacturing capacity in Mexico's Jalisco state, reducing lead times for U.S. industrial automation customers.
- BiCMOS process evolution:Automotive-qualified sensor interfacing architectures are enabling multi-channel battery monitoring at higher voltage tolerances for electric drivetrain applications.
Market Restraints
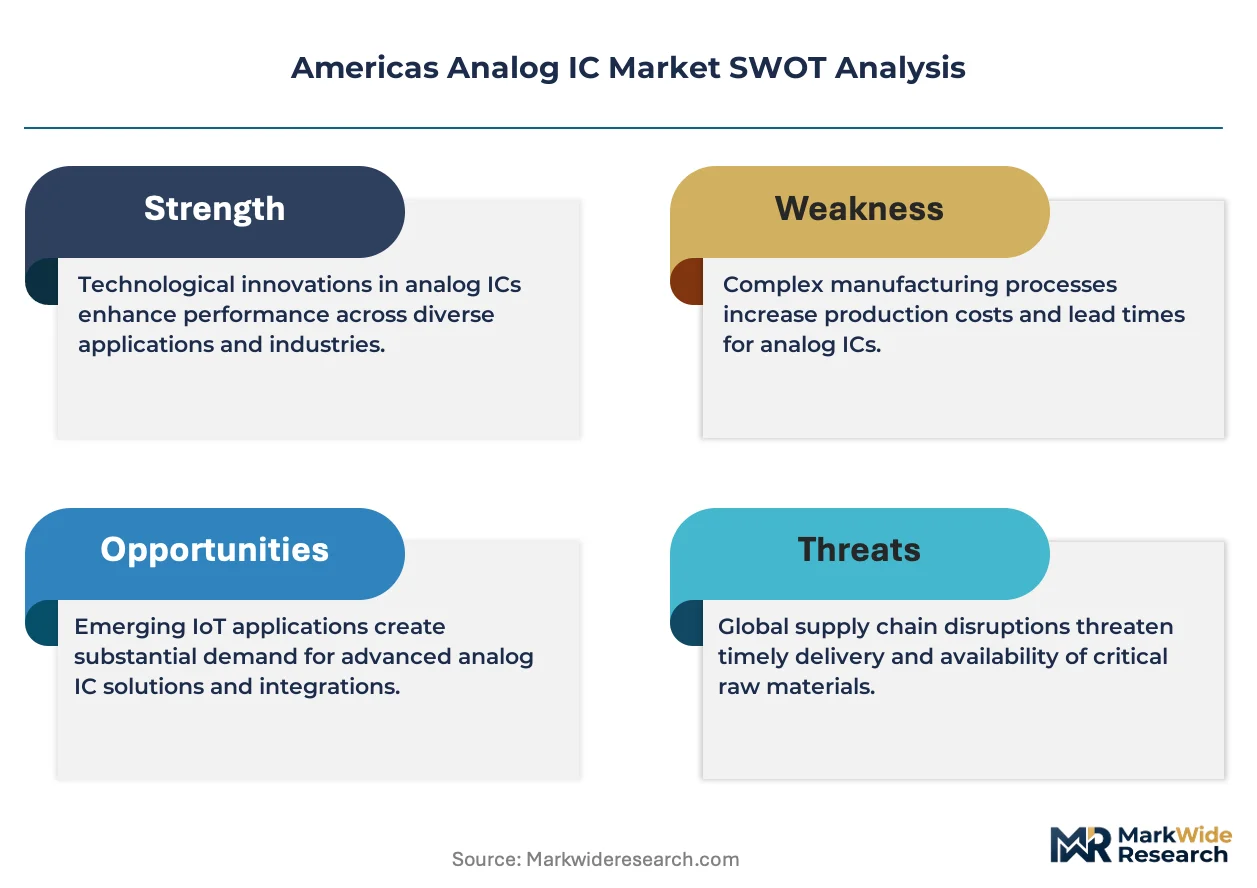
- 180-nm node capacity concentration:Legacy analog process availability is tightening as foundries prioritize advanced digital CMOS, extending lead times for voltage regulator and amplifier wafers.
- EPA PFAS restrictions:Anticipated per- and polyfluoroalkyl substance regulations are complicating fluoropolymer-based packaging material qualification across the Americas supply base.
- Gallium nitride displacement:GaN power devices are capturing socket share in high-frequency power management applications above 100 kHz, pressuring silicon-based analog IC margins.
Strategic Opportunities
- Edge AI sensor fusion:Multi-channel precision acquisition requirements in industrial IoT deployments are expanding operational amplifier and data converter attach rates per node.
- OSHA semiconductor safety frameworks:Cross-border workforce qualification protocols are creating certification-advantaged positions for suppliers with integrated Mexico-U.S. training programs.
- Brazil industrial automation:Underpenetrated factory modernization programs are opening design-in opportunities for signal conditioning components in process control equipment.
Industry Challenges
- AEC-Q100 certification timelines:Extended automotive reliability qualification cycles are delaying revenue recognition for new voltage regulator and battery management IC introductions.
- 300-mm analog process migration:Capital intensity for fab equipment compatible with precision analog geometries is concentrating R&D budgets among scale players, compressing mid-tier design house viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Analog IC Market |
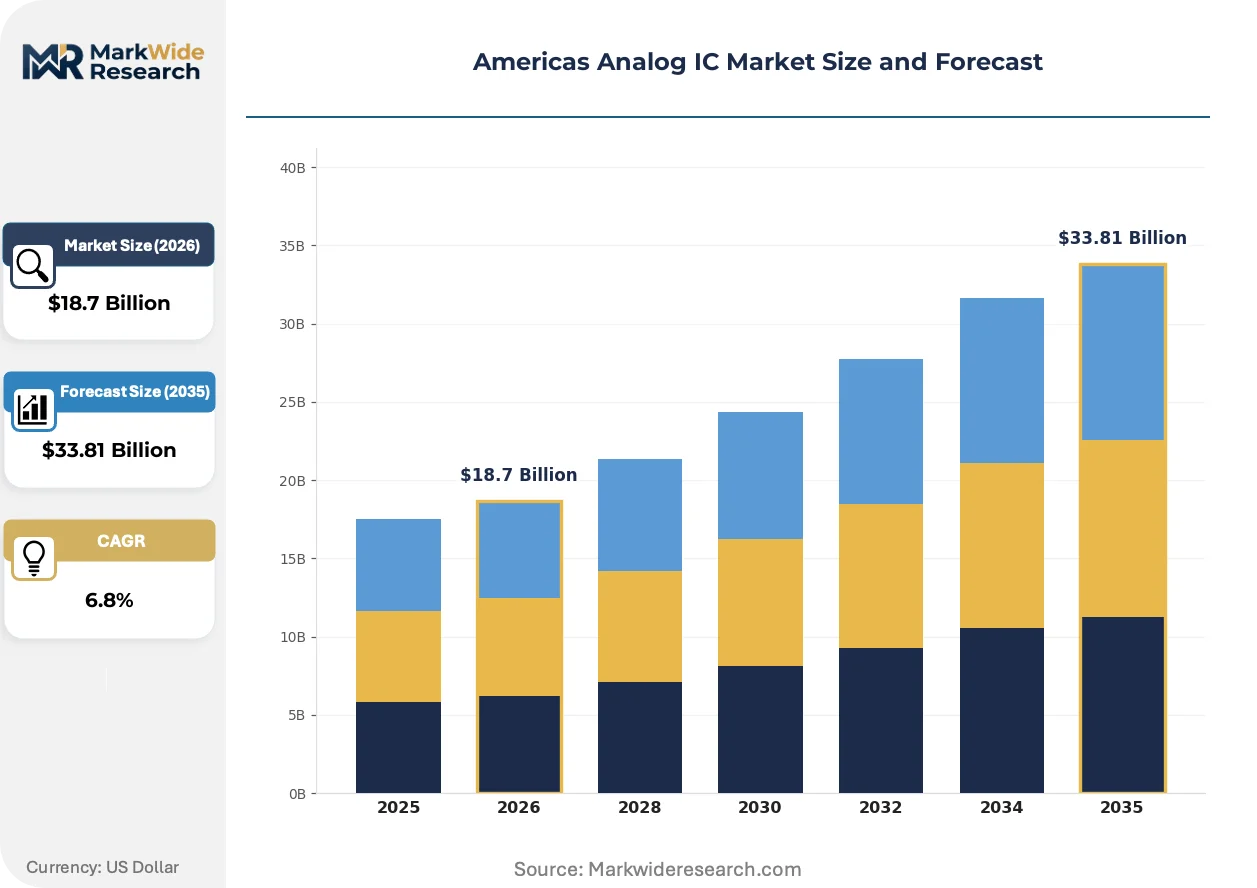
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Amplifiers End User: Consumer Electronics, Automotive OEMs, Industrial Equipment, Telecommunications Technology: CMOS, BiCMOS, BJT, SiGe Application: Signal Processing, Audio Processing, Power Management, Sensor Interfacing |
| Companies Covered | Texas Instruments Incorporated, Analog Devices Inc., Infineon Technologies AG, NXP Semiconductors NV, ON Semiconductor, Microchip Technology Inc., Renesas Electronics Corporation, Skyworks Solutions Inc., STMicroelectronics NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Analog IC Market Trends and Innovations
Silicon-germanium and advanced BiCMOS architectures are fragmenting the traditional CMOS-dominated landscape for high-frequency signal processing. Foundry process roadmaps now emphasize thermal efficiency and quiescent current specifications over pure density scaling.
SiGe HBT processes are fragmenting the RF and millimeter-wave signal chain component market by enabling integrated transceiver architectures at frequencies previously requiring discrete GaAs solutions. Aerospace defense contractors are accelerating adoption for radar and satellite communication payloads. This technology compression is reducing board-level component counts while elevating foundry process specialization barriers.
SEC climate disclosure rules are mandating Scope 3 emissions reporting across semiconductor supply chains, forcing analog IC vendors to document foundry energy intensity and material provenance. Industrial automation and automotive OEMs are conditioning supplier qualification on verified carbon accounting. Voltage regulator and power management segments face the steepest compliance curve due to energy-intensive wafer fabrication steps.
Consolidated procurement models are displacing fragmented distributor relationships as automotive OEMs and industrial equipment manufacturers centralize analog IC sourcing through direct foundry agreements. Tier-one suppliers are capturing volume commitments that previously flowed through broadline distribution. This concentration is most visible in Texas and Michigan manufacturing corridors, where EV powertrain and battery system integrators are locking in multi-year voltage regulator supply arrangements.
Americas Analog IC Market Segmentation
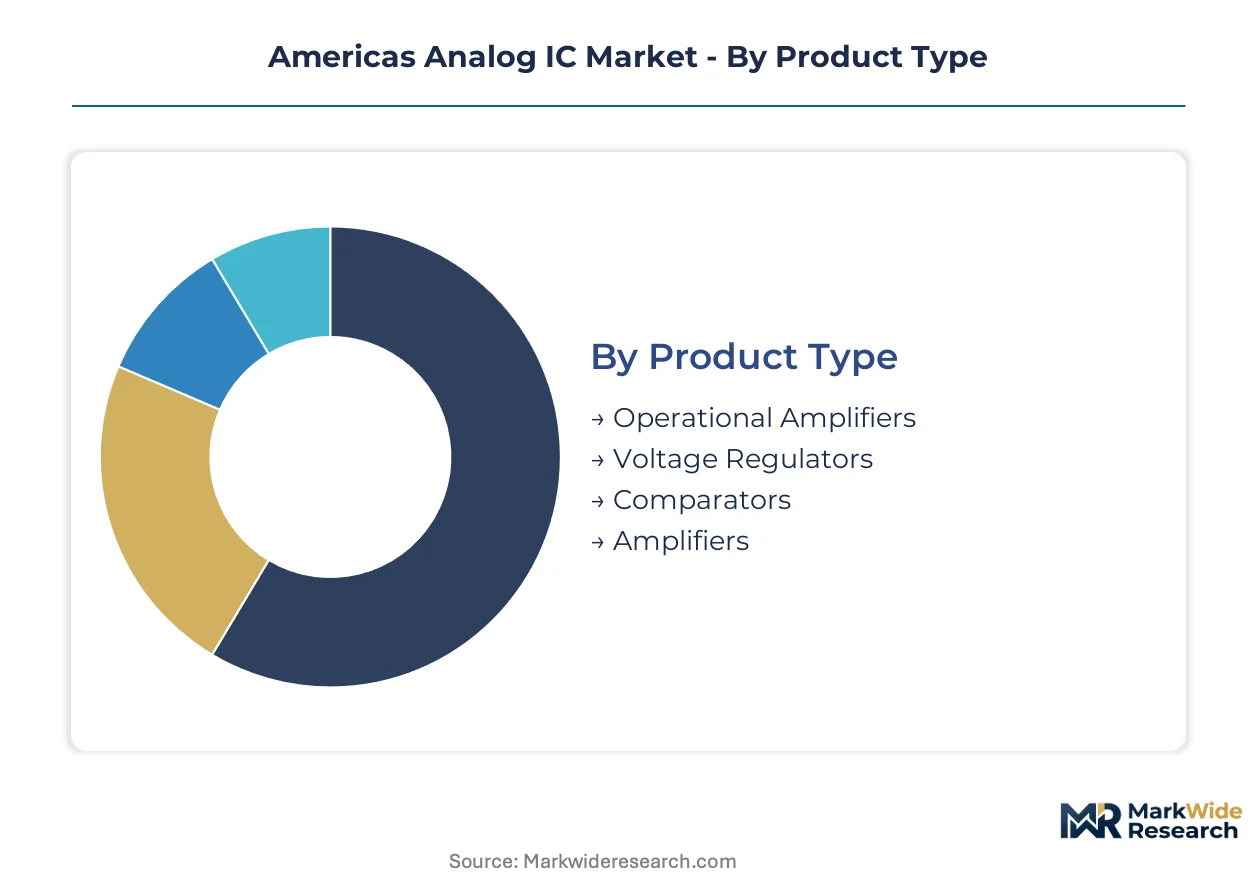
Channel configuration varies sharply across segment boundaries in the Americas Analog IC market. Procurement pathways for automotive-qualified components diverge from consumer electronics distribution, creating distinct margin and qualification requirements.
Product Type:
Voltage Regulators flow predominantly through direct foundry agreements with automotive OEMs, while Operational Amplifiers sustain broader distribution through industrial automation channels.
- Voltage Regulators:Linear and switching architectures fabricated on 180-nm to 40-nm nodes deliver stable output voltage across load variations. Demand concentrates in Michigan and Texas manufacturing corridors where EV powertrain integrators lock in multi-year supply arrangements for battery management systems.
- Operational Amplifiers:Differential input stages with high open-loop gain perform signal conditioning in sensor acquisition chains. Industrial equipment manufacturers in the U.S. Midwest and Mexico's Guadalajara corridor drive procurement for precision measurement applications.
- Comparators:High-speed voltage-level detection circuits enable threshold monitoring in power-limited embedded systems.
- Amplifiers:General-purpose gain stages support audio and instrumentation signal chains across consumer and industrial end uses.
Voltage Regulators dominate installed base. Operational Amplifiers are where expansion concentrates for industrial IoT deployment.
End User:
Cost tier stratification separates automotive OEM procurement—with its AEC-Q100 certification premiums—from consumer electronics volume pricing.
- Automotive OEMs:Electrification programs in Detroit and Austin manufacturing hubs require automotive-qualified BiCMOS processes for battery monitoring and drivetrain control. EPA vehicle emissions standards and NHTSA safety mandates condition design-in timelines.
- Industrial Equipment:Factory automation OEMs specify extended temperature ranges and isolation ratings for process control systems. OSHA semiconductor safety frameworks govern workforce qualification protocols for U.S.-Mexico cross-border facilities.
- Consumer Electronics:Portable device manufacturers prioritize quiescent current specifications and compact packaging for mobile power management.
- Telecommunications:Base station and data center operators demand thermal efficiency in high-density power delivery architectures.
Automotive OEMs command premium pricing tiers. Industrial Equipment is climbing the fastest as nearshoring accelerates precision manufacturing investment.
Technology:
Process maturity curves create supply concentration, with 180-nm node availability tightening as foundries prioritize advanced digital CMOS.
- BiCMOS:Combined bipolar and CMOS structures enable high-voltage sensor interfacing with digital control integration. Automotive battery management systems in the U.S. Southwest specify BiCMOS for 60V+ tolerance requirements.
- SiGe:Silicon-germanium heterojunction bipolar transistors extend frequency response for RF and millimeter-wave signal chains. Aerospace defense contractors accelerate adoption for radar payloads.
- CMOS:Standard complementary metal-oxide-semiconductor processes dominate cost-sensitive voltage regulation and low-frequency amplification.
- BJT:Bipolar junction transistor architectures retain niche positions in precision analog circuits requiring low noise figures.
CMOS holds the broadest installed base. BiCMOS is where technology investment concentrates for automotive electrification.
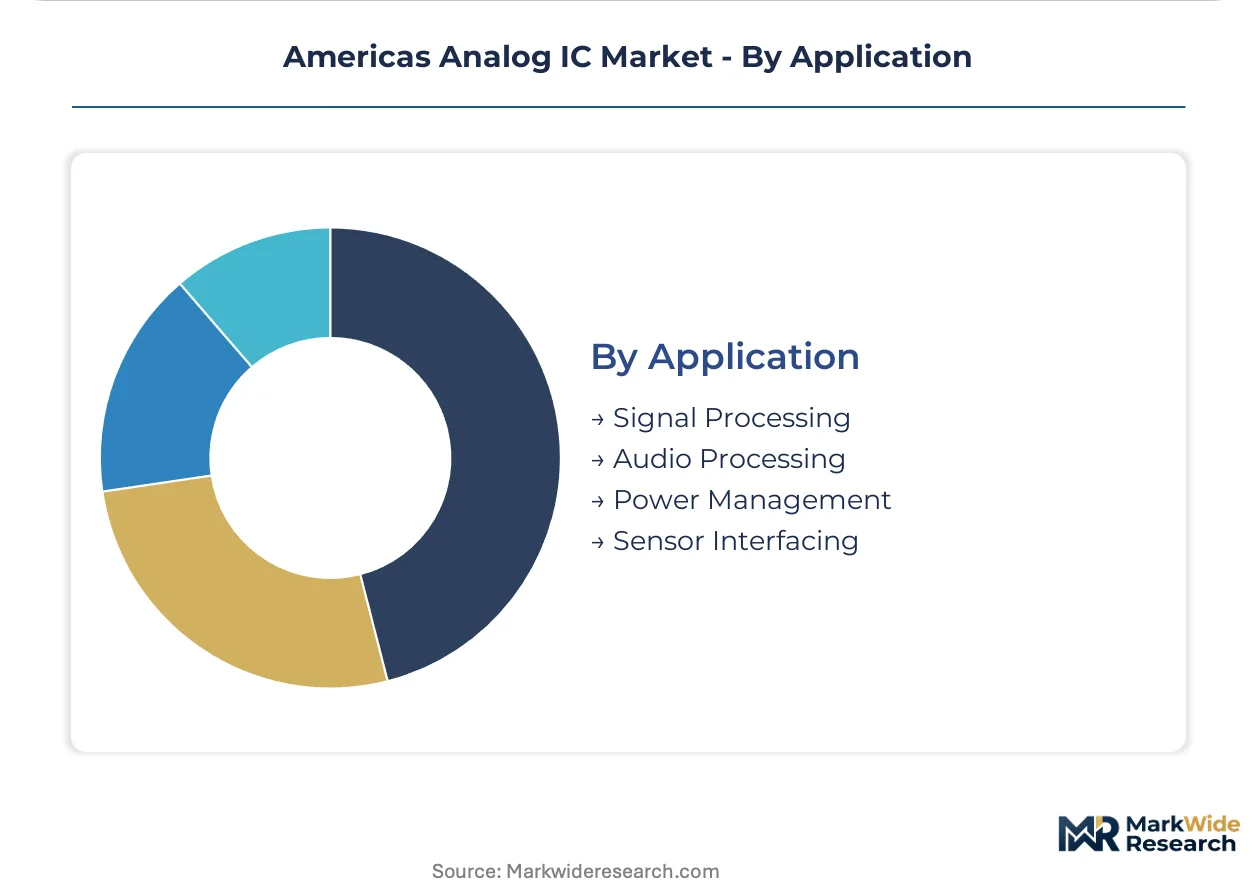
Application:
Volume concentration in Power Management contrasts with margin expansion in Sensor Interfacing as edge AI multiplies channel requirements per node.
- Sensor Interfacing:Multi-channel precision acquisition with programmable gain amplifiers and delta-sigma converters supports distributed sensing networks. Industrial IoT deployments across the U.S. Manufacturing Belt and Brazilian factory modernization programs drive design-in activity.
- Power Management:Thermal efficiency and quiescent current specifications determine socket access in battery-operated and energy-harvesting systems. CHIPS Act domestic content incentives redirect procurement toward North American qualified sources.
- Signal Processing:Active filters, mixers, and modulators condition analog information for digital conversion in communications and instrumentation.
- Audio Processing:Low-distortion amplification and codec interfaces serve consumer electronics and professional sound reinforcement markets.
Power Management dominates shipment volumes. Sensor Interfacing is where application expansion concentrates for precision measurement deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports precision-manufactured analog IC assemblies to U.S. automotive OEMs and industrial automation buyers through the Guadalajara electronics corridor. Cross-border trade flows concentrate in Jalisco state foundries serving Detroit and Austin manufacturing hubs.
United States
Automotive electrification in Michigan and Texas drives voltage regulator demand for battery management systems. The CHIPS Act conditions federal subsidies on domestic wafer fabrication, redirecting procurement toward Richardson, Texas and other qualified fabs. Austin and Detroit manufacturing corridors lock in multi-year supply arrangements for EV powertrain components.
Mexico
Nearshoring momentum concentrates precision manufacturing capacity in Jalisco state's Guadalajara electronics corridor. OSHA semiconductor safety frameworks govern cross-border workforce qualification protocols for U.S.-Mexico integrated facilities. Jalisco state reduces lead times for Midwest industrial automation customers while expanding BiCMOS process capacity.
Canada
Industrial equipment OEMs in Ontario specify extended temperature ranges for process control systems. Health Canada and provincial environmental regulators align with EPA frameworks on per- and polyfluoroalkyl substance restrictions affecting packaging materials. Ontario's manufacturing belt sources signal conditioning components for factory modernization programs.
Brazil
Underpenetrated factory modernization programs open design-in opportunities for sensor interfacing components in process control equipment. ANVISA and national industrial regulators govern equipment certification timelines for imported analog ICs. São Paulo state anchors demand concentration for industrial automation signal chains.
Americas Analog IC Market Competitive Landscape
Player mix skews toward diversified semiconductor conglomerates with captive fabrication capacity. Consolidation around scale players with 300-mm analog process capability has compressed mid-tier design house viability. Two strategic archetypes dominate: integrated IDMs with automotive-qualified BiCMOS expertise, and fabless specialists leveraging foundry partnerships for sensor interfacing. Competitive moves concentrate on domestic fab expansion under CHIPS Act incentives and multi-year direct agreements with automotive OEMs.
Within the integrated IDM tier, Texas Instruments Incorporated and Analog Devices Inc. exemplify scale-driven positions, while NXP Semiconductors NV occupies a specialist position in automotive-qualified sensor interfacing. Texas Instruments anchors cost leadership through captive 300-mm fabrication. Analog Devices represents high-performance signal processing concentration across industrial and aerospace channels. NXP Semiconductors sits within the automotive BiCMOS specialization vector.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices Inc. |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| ON Semiconductor |
| Microchip Technology Inc. |
| Renesas Electronics Corporation |
| Skyworks Solutions Inc. |
| STMicroelectronics NV |
| Others |
Pricing and Supply Chain Analysis
300-mm wafer scale economies at Texas Instruments' Richardson fab anchor cost floors across voltage regulator tiers, compressing margin headroom for mid-tier competitors while elevating price discipline among automotive-qualified BiCMOS suppliers. This concentration simultaneously tightens supply availability and hardens pricing power for process nodes below 180-nm.
Pricing Analysis
Current-generation 40-nm BiCMOS architectures command 25-40% premiums over legacy 180-nm CMOS equivalents, while next-generation SiGe HBT processes for RF signal chains sit at prototype pricing tiers. Three-tier pricing structure across automotive-grade, industrial-extended, and commercial-standard certification levels segments buyer tiers. Cost compression in commercial-grade voltage regulators is intensifying because GaN power devices capture socket share above 100 kHz. Automotive OEMs exhibit lowest price sensitivity due to AEC-Q100 qualification barriers, while consumer electronics manufacturers drive hardest unit-cost negotiations.
Supply Chain Analysis
Container availability constraints on Asia-Pacific to North America trade lanes elevate inbound logistics costs for silicon wafer substrates and specialty chemical precursors. Foundry capacity concentrates in Taiwan, South Korea, and the United States for advanced analog processes. Raw material dependencies include high-purity silicon wafers, fluoropolymer packaging compounds, and noble metal sputtering targets. Single-source vulnerability around 180-nm legacy node availability extends lead times for voltage regulator wafers. Distribution runs through direct foundry agreements with automotive OEMs and industrial broadline distributors for smaller-volume industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive-qualified BiCMOS process expertise represents the critical scarcity layer, with fewer than five foundries globally capable of 60V+ battery management tolerances at volume. This capability gap separates viable competitors from design-house aspirants.
For Market Incumbents: Consolidate around 300-mm analog process migration to defend cost leadership against GaN displacement in power management above 100 kHz. Lock multi-year direct supply agreements with Detroit and Austin EV powertrain integrators to preempt channel consolidation. Prioritize AEC-Q100 certification investment for sensor interfacing portfolios as battery monitoring channel requirements multiply. For New Entrants and Emerging Players: Custom sensor fusion firmware services represent an under-served layer where incumbents lack vertical software integration. Target Brazil's factory modernization programs for process control signal conditioning components, where ANVISA certification timelines deter established players. Pursue foundry partnership models with Jalisco state facilities to bypass capital intensity barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-qualified fabless specialists with proven BiCMOS design wins over commodity voltage regulator players. Five-to-ten-year viability hinges on securing socket access before platform standardization locks. Watch EPA PFAS restriction implementation timelines as inflection indicator for packaging material cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fab Expansion | CHIPS Act subsidies condition federal incentive eligibility on North American wafer fabrication capacity. |
| Automotive Direct Supply Agreements | Multi-year contracts with Detroit and Austin EV integrators preempt distributor channel consolidation. |
| BiCMOS Process Investment | 60V+ tolerance capability opens battery management system design wins in electrification programs. |
| Cross-Border Workforce Certification | OSHA semiconductor safety frameworks create moats for suppliers with integrated Mexico-U.S. training. |
| Edge AI Sensor Fusion Development | Multi-channel precision acquisition requirements expand operational amplifier attach rates per industrial IoT node. |
Research Methodology
Operator-level perspectives from analog IC design engineers, automotive Tier 1 procurement directors, foundry process technologists, and industrial automation OEMs anchored the qualitative base. Primary interviews combined with secondary validation against SEC 10-K filings, CHIPS Act implementation guidance, EPA regulatory dockets, and customs trade data. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates.
Sensitivity analysis around CHIPS Act subsidy disbursement timelines and EPA PFAS restriction implementation shaped scenario-weighted outputs across the projection horizon. Segmentation dimensions modeled include product type, end user vertical, process technology node, and application function. CAGRs derived from historical shipment trajectories, foundry capacity expansion announcements, and OEM platform rollout schedules. Forecast inputs incorporated AEC-Q100 certification pipeline visibility and nearshoring momentum indices for Jalisco state capacity.
Forecasts assume regulatory continuity in U.S. EPA, SEC climate disclosure, and Mexico Ministry of Economy frameworks; material policy shifts would require re-modeling. Semiconductor supply chain disruptions, automotive platform demand volatility, or gallium nitride technology acceleration could revise trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
3D Integrated Circuit Market