
 Digital IC Market | 2026-2036
Digital IC Market Size, Share, and Industry Trends Forecast 2026-2036
Digital IC Market Analysis
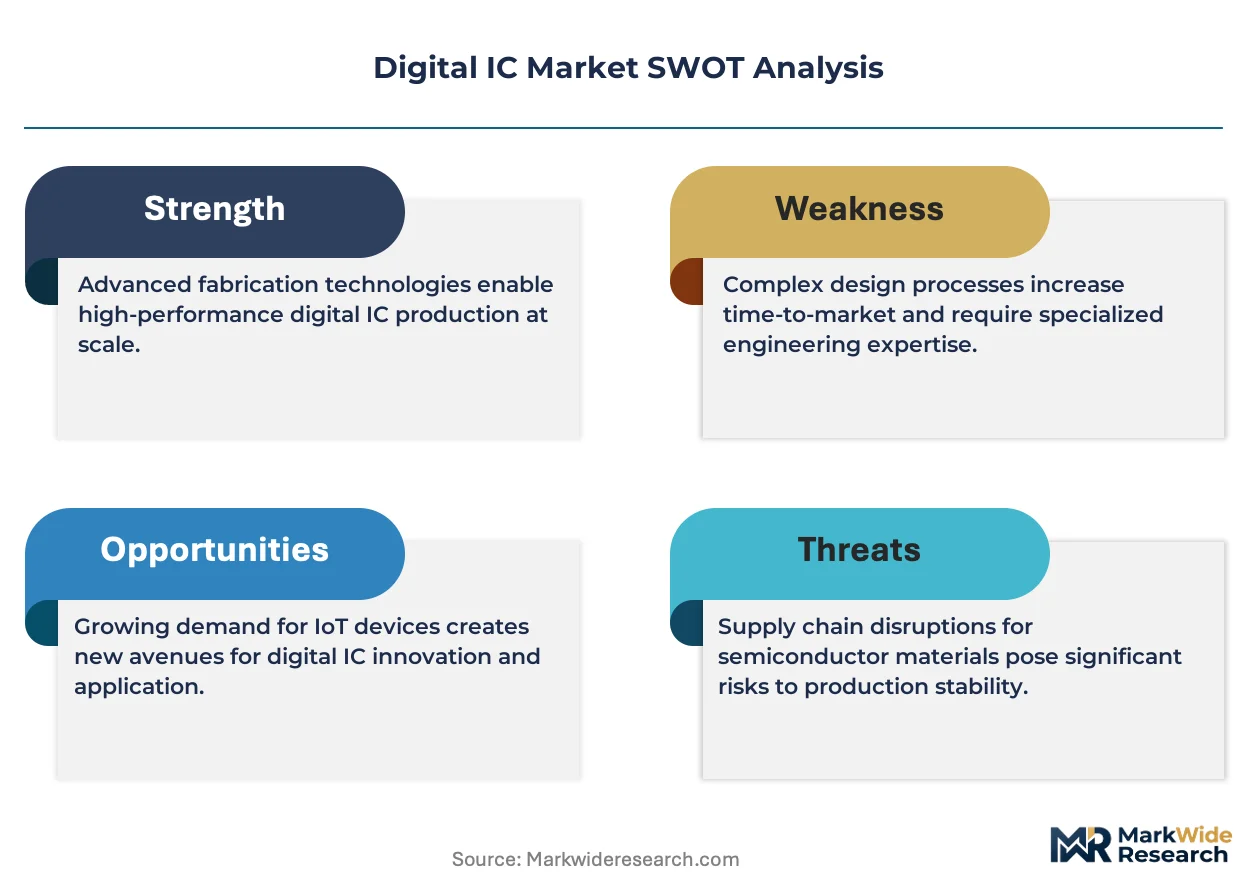
The divergence between premium and commodity tiers is hardening as leading-edge nodes below 5nm command exclusive foundry access while mature-node digital ICs face price compression. NVIDIA leverages its CUDA software ecosystem to dominate AI training silicon. TSMC sustains process leadership through massive R&D outlays. Samsung Electronics anchors memory-adjacent logic production in South Korea.
Digital integrated circuits are semiconductor devices composed of transistors fabricated on silicon wafers using lithographic processes, typically implementing logic functions through CMOS technology with gate lengths measured in nanometers. They serve as the computational substrate for electronic systems ranging from smartphones to autonomous vehicles. Processors capture the highest absolute revenue within product type segmentation due to datacenter and AI inference demand. Automotive electronics within application segmentation is expanding fastest as software-defined vehicles require more domain controllers. OEMs as end users concentrate negotiation power through long-term supply agreements directly with foundries.
Regulators including the US Department of Commerce through export control frameworks, the European Commission via the EU Chips Act, and China's Ministry of Industry and Information Technology through domestic subsidy programs are all reshaping where digital ICs may be designed, manufactured, and shipped. These frameworks fragment market access and inflate compliance costs for cross-border supply chains. Stakeholders must monitor which jurisdictions secure trailing-edge capacity versus leading-edge access, as this bifurcation determines competitive positioning for the next process generation.
Market Dynamics
Leading-edge lithography access below 3nm is concentrating capital among three foundry operators while mature-node capacity faces margin compression from Chinese capacity expansion.
Growth Catalysts
- AI Accelerator Deployment:Hyperscale datacenter operators in the United States are procuring specialized training silicon at volumes that absorb foundry output for advanced nodes. This demand pull is reallocating wafer starts from smartphone SoCs toward AI compute dies.
- EU Chips Act Subsidies:The European Commission's €43 billion facility incentive program is attracting front-end investment into Dresden and Leuven, creating new captive supply for automotive OEMs seeking regional sourcing assurances.
- Automotive Domain Consolidation:Software-defined vehicle architectures are displacing distributed ECUs with centralized compute platforms, multiplying silicon content per vehicle and demanding automotive-grade process qualifications.
Market Restraints
- EUV Tool Scarcity:ASML's extreme ultraviolet lithography equipment lead times extend beyond 18 months, capping expansion velocity for sub-7nm logic regardless of capital availability.
- Geographic Concentration Risk:Over 90 percent of leading-edge wafer fabrication occurs within 100 kilometers of Taipei, exposing supply continuity to seismic and geopolitical contingencies without near-term diversification pathways.
- Raw Material Purity Requirements:Semiconductor-grade neon and xenon supply from Ukrainian and Russian sources remains disrupted, forcing fabs to qualify alternative gas suppliers at elevated purification costs.
Strategic Opportunities
- India Fab Incentives:The country's PLI scheme for semiconductor manufacturing is attracting assembly and test investments that could mature into front-end foundry operations serving domestic electronics demand.
- Chiplets and Advanced Packaging:Die disaggregation using 2.5D and 3D integration is enabling performance scaling without sole reliance on monolithic process shrinks, opening packaging specialists to value capture previously held by fabs.
- Edge AI Inference:Low-power neural network accelerators for industrial automation and smart city infrastructure represent an underpenetrated volume tier between datacenter training and mobile inference.
Industry Challenges
- Process Engineering Talent Gap:Experienced lithography and yield engineers are concentrated among incumbent fabs, constraining new entrant ramp speeds and inflating compensation for specialists capable of sub-5nm production.
- Legacy Node Certification Overhead:Automotive and aerospace qualification cycles for mature process nodes extend 24-36 months, delaying revenue recognition for capacity expansions targeting these end-uses.
- Cross-Border IP Enforcement:Trade secret litigation across US, Taiwan, and South Korean jurisdictions creates uncertainty for process technology licensing and joint development agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital IC Market |
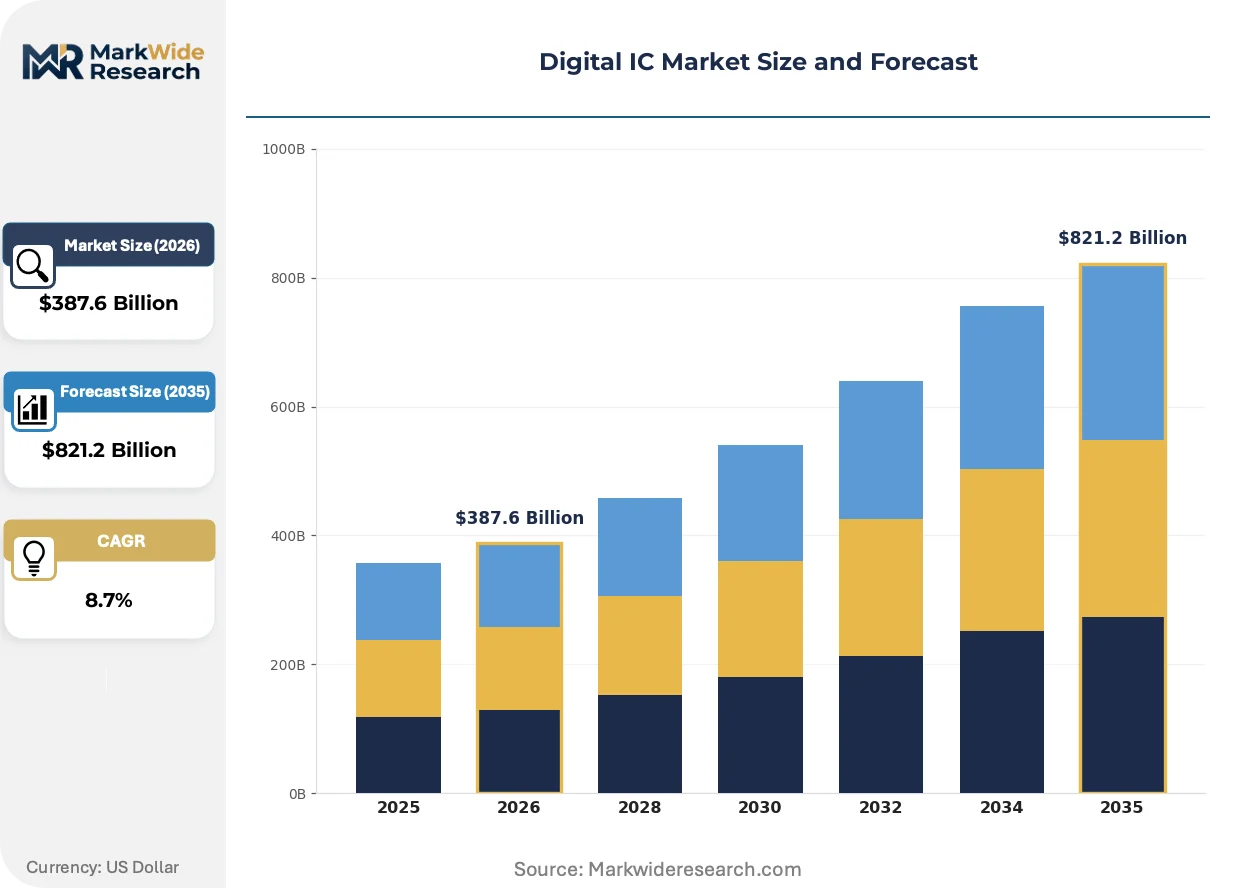
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
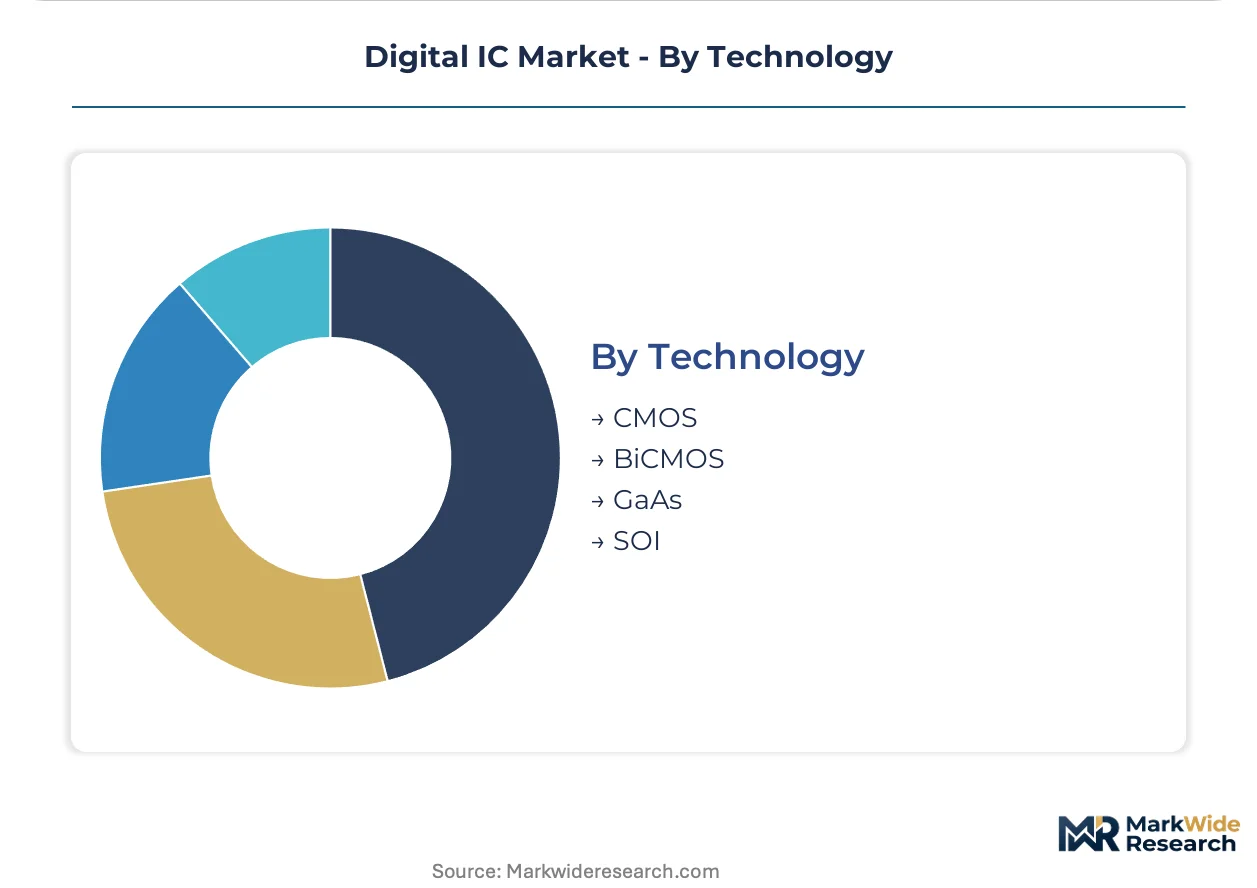
| Segmentation | Product Type: Microcontrollers, Processors, FPGAs, Digital Signal Processors Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Automation End User: OEMs, Tier-1 Suppliers, Distributors, System Integrators Technology: CMOS, BiCMOS, GaAs, SOI |
| Companies Covered | NVIDIA, Arm, Intel, Cadence Design Systems, Synopsys, Samsung Electronics, AMD, GlobalFoundries, TSMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital IC Market Emerging Trajectories
Silicon photonics integration and heterogeneous packaging are fragmenting the monolithic scaling model that dominated semiconductor economics for four decades.
Chiplet-based system-in-package architectures are decentralizing the historical foundry monopoly on performance scaling. AMD and Intel are disaggregating CPU and accelerator dies across multiple process nodes within single packages. This approach compresses time-to-market for new product generations while reducing dependency on bleeding-edge lithography availability.
The US Department of Commerce export control framework is bifurcating equipment and design tool access based on destination country and performance thresholds. Chinese foundries are accelerating domestic equipment qualification to circumvent these restrictions. European and Japanese tool vendors are capturing incremental share as US-origin equipment faces deployment constraints in certain markets.
Hyperscale buyers are consolidating negotiation leverage through multi-year foundry prepayment agreements that secure wafer allocation at fixed pricing. This behavior is displacing the spot-market wafer purchasing that characterized the 2015-2020 period. Taiwan and South Korean foundries are most exposed to this buyer concentration, with contract structures now spanning 3-5 year horizons.
Digital IC Market Segmentation
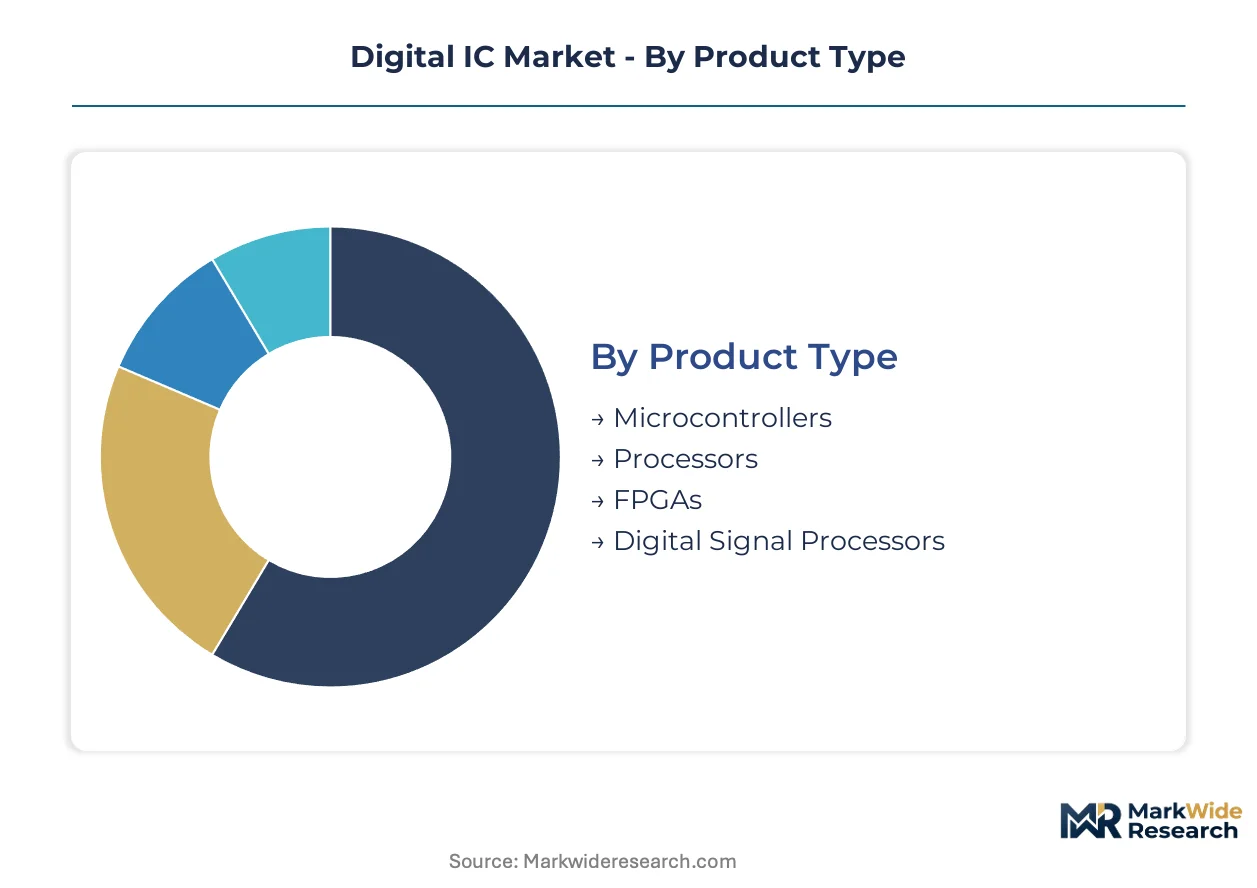
Digital IC procurement patterns diverge sharply across technical specifications, with automotive-grade components demanding AEC-Q100 qualification cycles that extend 24-36 months while consumer processors prioritize rapid node migration. Foundry allocation strategies now weight certification overhead as heavily as die yield in capacity planning decisions.
Product Type:
Automotive qualification burdens concentrate on microcontrollers and processors, where AEC-Q100 Grade 0 certification mandates temperature cycling from -40°C to 150°C across million-unit production lots. FPGAs and DSPs face less stringent industrial-grade requirements unless deployed in safety-critical chassis systems.
- Microcontrollers:Embedded control units integrate CPU cores with memory and peripherals on monolithic dies, typically fabricated at 40-90nm nodes for cost optimization. Automotive domain controllers in Germany and Japan absorb the highest volume, constrained by foundry capacity allocation shifting toward AI accelerators.
- Processors:General-purpose and application-specific compute engines implement complex instruction pipelines at leading-edge nodes below 5nm. Hyperscale datacenter operators in the United States command priority wafer allocation, displacing smartphone SoC production schedules.
- FPGAs:Field-programmable gate arrays enable post-fabrication logic reconfiguration through SRAM-based lookup tables. Industrial automation in South Korea and Taiwan represents concentrated demand.
- Digital Signal Processors:Specialized architectures optimized for multiply-accumulate operations support real-time audio and video processing. Telecommunications infrastructure in India and Brazil drives replacement cycles.
Leading the category by volume: Processors. Growing fastest: Microcontrollers.
Application:
Cost tier stratification separates automotive electronics—where silicon content per vehicle now exceeds $1,000 in premium platforms—from consumer electronics operating on 12-18 month product lifecycles with minimal qualification overhead.
- Consumer Electronics:Smartphones, tablets, and wearables demand annual process node advances for power efficiency gains. TSMC N3E allocation in Taiwan concentrates supply for Apple and Qualcomm flagship launches.
- Telecommunications:Baseband processors and RF transceivers for 5G infrastructure require extended temperature reliability. China's MIIT domestic substitution mandates are reshaping vendor qualification lists for state-owned carrier procurement.
- Automotive Electronics:Domain controllers, ADAS compute, and powertrain management systems multiply silicon content per vehicle. Bosch and Continental in Germany negotiate directly with foundries for regional supply assurances under EU Chips Act incentives.
- Industrial Automation:Programmable logic controllers and motor drives prioritize 10-15 year supply continuity over node advancement. Siemens and Rockwell Automation in the United States lock in mature-node foundry agreements.
Volume concentration: Consumer Electronics. Steepest expansion trajectory: Automotive Electronics.
End User:
Customer type determines contract structure, with OEMs extracting multi-year fixed-price agreements while distributors absorb inventory risk for fragmented industrial accounts.
- OEMs:Original equipment manufacturers in automotive and consumer electronics consolidate procurement through direct foundry relationships. Tesla and Apple prepay billions in wafer deposits to secure N3 capacity allocation.
- Tier-1 Suppliers:Delphi and Denso intermediate between semiconductor vendors and vehicle assembly lines, managing qualification documentation and buffer inventory.
- Distributors:Arrow Electronics and Avnet aggregate demand across thousands of small and mid-sized electronics manufacturers, bearing price volatility risk on commodity digital ICs.
- System Integrators:Foxconn and Jabil assemble finished systems, procuring digital ICs as consigned materials from OEM customers or through authorized distribution.
Negotiation leverage concentrates with: OEMs. Fastest-growing procurement role: Tier-1 Suppliers.
Technology:
Process maturity and substrate material divide manufacturing economics, with CMOS dominating volume production while SOI and GaAs command premium pricing for specialized radio-frequency and radiation-hardened applications.
- CMOS:Complementary metal-oxide-semiconductor technology implements logic through paired NMOS and PMOS transistors, scaling from 350nm legacy nodes to 2nm production. Taiwan and South Korea foundries concentrate capital deployment here.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with dense CMOS logic for mixed-signal applications. RF front-end modules in 5G smartphones drive selective adoption.
- GaAs:Gallium arsenide substrates enable electron mobility exceeding silicon limits, supporting millimeter-wave power amplifiers. Defense and satellite communications in the United States maintain captive supply chains.
- SOI:Silicon-on-insulator architectures reduce parasitic capacitance through buried oxide layers, improving power efficiency for IoT edge devices. STMicroelectronics in France and GlobalFoundries in the United States specialize here.
Volume leader: CMOS. Fastest technology transition: SOI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's most concentrated leading-edge foundry capacity, with TSMC's fabs absorbing the majority of global sub-5nm wafer starts. This geographic reality shapes procurement strategies across every downstream electronics sector.
United States
Hyperscale datacenter operators in California and Washington state command priority allocation for AI training silicon through multi-year prepayment agreements. The Department of Commerce export control framework restricts equipment access to Chinese foundries, redirecting tool vendor relationships toward domestic expansion projects. Intel's manufacturing complex in Arizona and planned fabs in Ohio represent the largest capital deployment toward trailing-edge reshoring.
Taiwan
TSMC's foundry network in Hsinchu and Tainan produces over ninety percent of the world's most advanced logic chips, concentrating seismic and geopolitical risk exposure. The National Development Council's subsidy programs under the Taiwan Chips Act sustain R&D outlays for 2nm process development. Southern Taiwan Science Park expansion in Kaohsiung is absorbing the largest share of regional capital deployment for advanced packaging capacity.
South Korea
Samsung Electronics anchors memory-adjacent logic production in Pyeongtaek and Hwaseong, competing for leading-edge lithography tools against Taiwanese rivals. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative channels subsidies toward Yongin cluster development. Seoul's Gangnam district hosts the headquarters of fabless design houses specializing in AI accelerator architectures.
China
Domestic foundries in Shanghai and Beijing are accelerating equipment qualification to circumvent US-origin tool restrictions, prioritizing mature-node capacity expansion. The Ministry of Industry and Information Technology's domestic substitution mandates reshape vendor qualification lists for state-owned carrier procurement. Zhangjiang Hi-Tech Park in Shanghai concentrates the largest cluster of indigenous lithography and deposition tool development.
Germany
Bosch and Continental in Stuttgart negotiate directly with foundries for regional supply assurances under EU Chips Act incentives targeting automotive-grade silicon. The European Commission's €43 billion facility incentive program is attracting front-end investment into Dresden's Silicon Saxony cluster. Infineon's manufacturing footprint in Regensburg specializes in power semiconductors for electric vehicle drivetrains.
Digital IC Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where three foundry operators control leading-edge lithography access while dozens of fabless houses specialize in architecture and software. The market consolidates around process technology leadership on the supply side and ecosystem lock-in on the design side. Dominant archetypes include vertically integrated IDMs, pure-play foundries, and IP-licensing specialists. Competitive moves center on multi-year capacity reservation agreements and strategic partnerships for advanced packaging access.
Among US-based designers, NVIDIA and AMD occupy positions at the AI compute frontier, while Taiwan-based TSMC anchors the foundry tier that manufactures their silicon. These three names exemplify the separation between architecture innovation and process technology execution that defines contemporary competitive dynamics.
| Leading Market Players |
|---|
| NVIDIA |
| Arm |
| Intel |
| Cadence Design Systems |
| Synopsys |
| Samsung Electronics |
| AMD |
| GlobalFoundries |
| TSMC |
| Others |
Supply Flow & Price Mechanics
Semiconductor-grade neon pricing volatility from Ukrainian supply disruptions cascades through foundry cost structures into three distinct procurement tiers: hyperscale prepayment agreements, automotive long-term contracts, and spot-market commodity purchases.
Pricing Analysis
Throughput-based pricing anchors AI accelerator procurement, with hyperscale datacenter operators contracting die yield per wafer rather than per-unit costs. Pricing stratifies across leading-edge nodes below 3nm, mature automotive-qualified nodes at 28-90nm, and legacy industrial-grade production. Cost compression in mature-node microcontrollers is intensifying because Chinese capacity expansion absorbs regional demand. Tier-1 automotive suppliers exhibit lowest price sensitivity due to qualification lock-in, while consumer electronics OEMs arbitrage aggressively across foundry quotes.
Supply Chain Analysis
Process engineering talent scarcity in Hsinchu, Pyeongtaek, and Chandler constrains new fab ramp speeds regardless of capital availability. The supply chain draws from ASML lithography systems, specialty gas purification infrastructure, and silicon wafer substrates. Single-source vulnerability concentrates in extreme ultraviolet tool dependency. Distribution runs through direct foundry relationships for volume buyers and authorized distribution for fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around process technology leadership, with EUV tool scarcity and R&D concentration forcing marginal players toward acquisition or exit.
For Market Incumbents: Cement foundry allocation priority through multi-year prepayment structures with hyperscale AI customers. Secure captive advanced packaging capacity in Kaohsiung or Yongin to defend against disaggregation threats from OSAT competitors. Vertical integration into silicon photonics substrates addresses emerging interconnect demand from training cluster deployments.
For New Entrants and Emerging Players: The EU Chips Act in Germany opens a window for automotive-qualified foundry capacity serving Bosch and Continental regional sourcing mandates. Target edge AI inference accelerators for industrial automation in India, where domestic electronics demand outpaces indigenous supply. Qualify as second-source for mature-node microcontrollers under automotive AEC-Q100 Grade 0 certification to bypass leading-edge capital barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty SOI foundries with established IoT customer relationships in France and the United States. Long-term viability hinges on 5-10 year supply continuity contracts with industrial automation OEMs seeking qualification stability. Watch for MIIT domestic substitution mandates in China as inflection signal for equipment vendor geographic realignment.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Prepayment Agreement | TSMC and Samsung secure wafer allocation priority from NVIDIA and AMD through billions in advance deposits. |
| Advanced Packaging Capacity Expansion | Southern Taiwan Science Park absorbs capital for 2.5D and 3D integration serving chiplet-based CPU architectures. |
| Automotive Qualification Investment | AEC-Q100 Grade 0 certification in Dresden enables Infineon and Bosch to lock in 24-36 month supply contracts. |
| Domestic Equipment Qualification | Shanghai foundries accelerate indigenous lithography development to circumvent US Department of Commerce restrictions. |
| Silicon Photonics Integration | STMicroelectronics in Crolles captures value from heterogeneous packaging replacing monolithic scaling economics. |
Methodological Framework
Independent corroboration across foundry capital expenditure disclosures, hyperscaler procurement announcements, and equipment vendor order backlogs underwrites the qualitative findings. Primary interviews engaged fab operations directors, fabless design house CTOs, automotive Tier-1 procurement leads, and lithography process engineers across Taiwan, South Korea, Germany, and the United States. Secondary validation drew from SEC 10-K filings, EU Chips Act implementation reports, MIIT domestic substitution mandates, and ASML quarterly order disclosures. Bottom-up wafer start projections and top-down semiconductor equipment spending patterns were triangulated against regional incentive program allocations.
Rate-of-change decomposition across process node migration timelines, foundry utilization rates, and design win conversion intervals structured the analytical framework. Segmentation dimensions modeled include product type, application vertical, end-user procurement structure, and technology node maturity. CAGRs were derived from supply-side capacity expansion schedules cross-referenced with demand-side silicon content per system trajectories. Forecast inputs incorporated EUV tool delivery lead times, automotive qualification cycle durations, and export control framework evolution.
Caveats apply where ASML equipment delivery delays, seismic events in Hsinchu, or abrupt export control expansion could materially shift the outlook. Forecasts reflect assumptions regarding sustained hyperscale AI capital deployment and continued automotive electronics silicon content growth. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market