
 China Logic Integrated Circuits Market | 2026-2036
China Logic Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
China Logic Integrated Circuits Market Insights
Domestic foundry expansion in the Yangtze River Delta is realigning supply dynamics for China logic integrated circuits. SMIC leverages advanced node development to reduce import dependence for critical digital processing chips. HiSilicon sustains design leadership in telecommunications-optimized logic architectures despite external equipment constraints. Hua Hong Semiconductor anchors trailing-node capacity for industrial and automotive-grade mixed-signal logic devices.
China logic integrated circuits comprise semiconductor devices performing Boolean operations, arithmetic processing, and data routing through transistor networks fabricated at process nodes ranging from mature 28nm to leading-edge 7nm and below, with CMOS serving as the dominant technology platform for power-efficient digital computation. These devices enable computational control across consumer electronics, telecommunications infrastructure, and automotive systems. Digital ICs occupy the largest value share as processors and controllers penetrate electric vehicle powertrain management and 5G baseband processing. Mixed-Signal ICs represent the fastest-expanding category as sensor fusion and analog-to-digital interfaces proliferate in smart manufacturing equipment. CMOS technology dominates fabrication economics, while GaN-on-silicon logic variants emerge for high-frequency power switching applications.
MIIT's integrated circuit industry guidelines and GB standards for semiconductor reliability shape domestic product certification requirements, while SAMR enforces antitrust and pricing oversight across the semiconductor supply chain. NMPA-aligned quality protocols extend into automotive logic components through functional safety mandates. Stakeholders must monitor foundry-utilization rates, equipment import licensing timelines, and provincial subsidy program shifts to calibrate capacity commitments against actual demand signals.
Market Dynamics
Domestic foundry capacity expansion in the Yangtze River Delta is compressing import dependence while MIIT's semiconductor self-sufficiency mandates restructure procurement flows across automotive and telecommunications end-uses.
Growth Catalysts
- MIIT Integrated Circuit Guidelines:Domestic procurement quotas for logic devices in 5G infrastructure and electric vehicle powertrain systems are redirecting demand toward certified local suppliers.
- Automotive Electronics Clustering:Shanghai-Jiangsu-Zhejiang manufacturing corridors concentrate electric vehicle controller demand, pulling trailing-node logic capacity toward functional safety-certified production.
- GaN-on-Silicon Process Maturation:High-frequency power switching applications in telecommunications base stations are diversifying beyond pure CMOS fabrication economics.
Market Restraints
- Equipment Import Licensing Friction:Advanced lithography tool procurement timelines from Dutch and Japanese suppliers extend node migration schedules beyond planned capacity ramps.
- Silicon Wafer Input Concentration:Domestic 300mm substrate supply remains insufficient for leading-edge logic demand, forcing reliance on Taiwanese and Korean material sources.
- Functional Safety Certification Burden:NMPA-aligned automotive logic qualification protocols extend product validation cycles by twelve to eighteen months versus consumer-grade timelines.
Strategic Opportunities
- Central China Capacity Migration:Hubei and Sichuan provinces offer land and power cost arbitrage for mature-node logic fabrication serving industrial automation markets.
- Sensor Fusion Interface Demand:Mixed-signal logic architectures integrating analog-to-digital conversion are penetrating smart manufacturing equipment at triple the rate of pure digital controllers.
- Dual Carbon Policy Tailwinds:MEE energy-efficiency mandates for data center infrastructure are accelerating adoption of low-power logic devices in server and edge computing deployments.
Industry Challenges
- Compound Semiconductor Talent Scarcity:GaN device physics and RF circuit design expertise pools remain concentrated in coastal research institutes, constraining interior foundry staffing.
- Legacy Industrial Controller Integration:Mixed-signal logic replacement cycles in installed manufacturing bases face protocol compatibility barriers with existing programmable logic controller architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Logic Integrated Circuits Market |
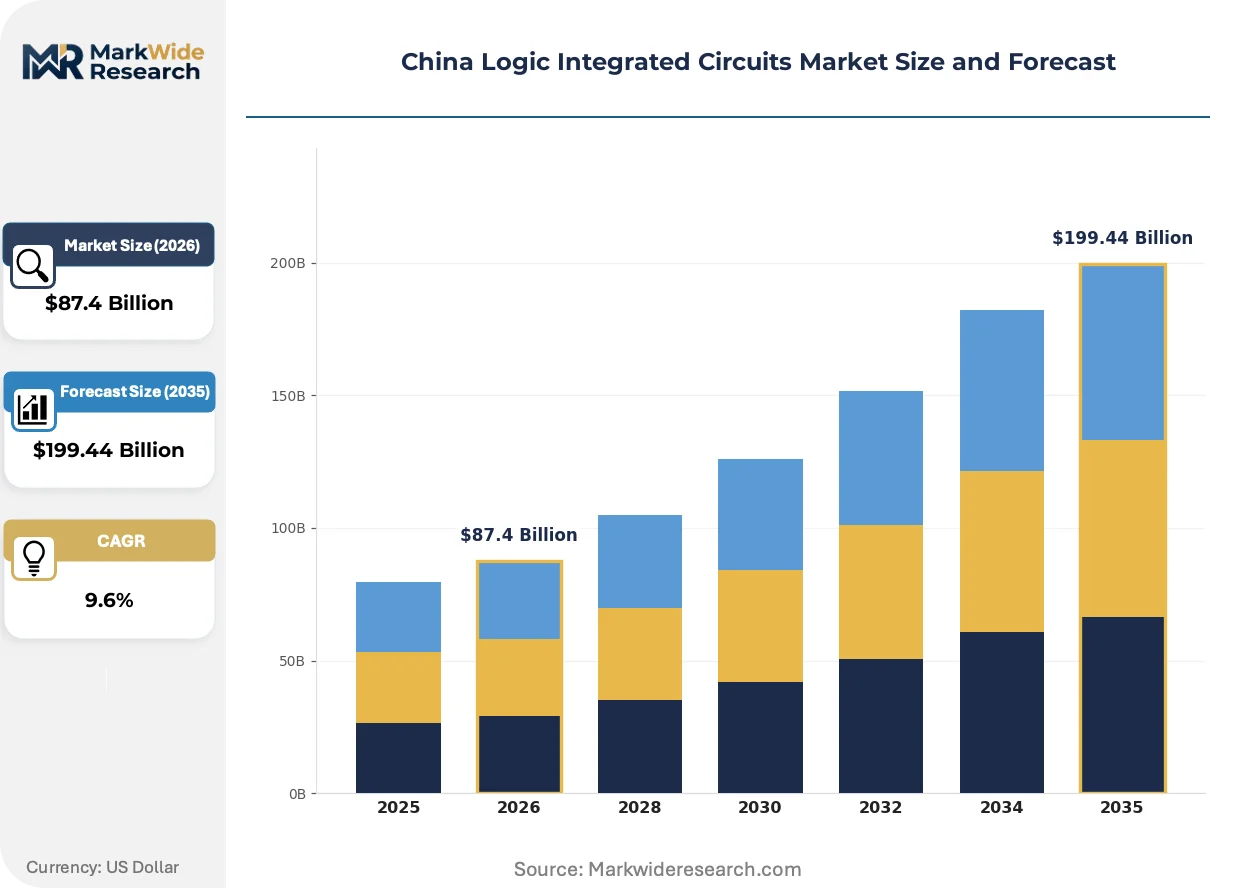
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $199.44 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power ICs End User: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment Technology: CMOS, BiCMOS, Bipolar, GaN Application: Signal Processing, Data Conversion, Power Management, Logic Operations |
| Companies Covered | SMIC, HiSilicon, Hua Hong Semiconductor, UNISOC, GigaDevice Semiconductor, Loongson Technology, Allwinner Technology, Rockchip Electronics, Silan Microelectronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Logic Integrated Circuits Market Trends and Innovations
Process node diversification and packaging integration are compressing traditional boundaries between logic, memory, and analog functions. Foundry service models are fragmenting to capture design-to-silicon margins previously retained by integrated device manufacturers.
Chiplet-based modular architectures are rewriting competitive economics for advanced logic design. Telecommunications equipment vendors and high-performance computing integrators are adopting disaggregated die configurations to bypass yield limitations at sub-7nm nodes. This approach is compressing time-to-market for complex system-on-chip products while redistributing value capture toward packaging and interconnect specialists.
GB standards for semiconductor reliability are tightening qualification thresholds for automotive-grade logic components. SAMR enforcement of antitrust oversight across the semiconductor supply chain is constraining vertical pricing coordination between foundries and design houses. Automotive electronics suppliers in the Yangtze River Delta are responding by building captive reliability testing capacity to accelerate NMPA-aligned certification timelines.
Direct foundry engagement models are displacing traditional distribution channels for logic procurement in industrial and automotive segments. Tier-one electric vehicle manufacturers and telecommunications infrastructure deployers are establishing engineering partnerships with domestic foundries to secure capacity allocation. This pattern is most visible in Shanghai and Jiangsu province, where procurement teams co-locate design-for-manufacturing engineers at foundry sites to compress iteration cycles.
China Logic Integrated Circuits Market Segmentation
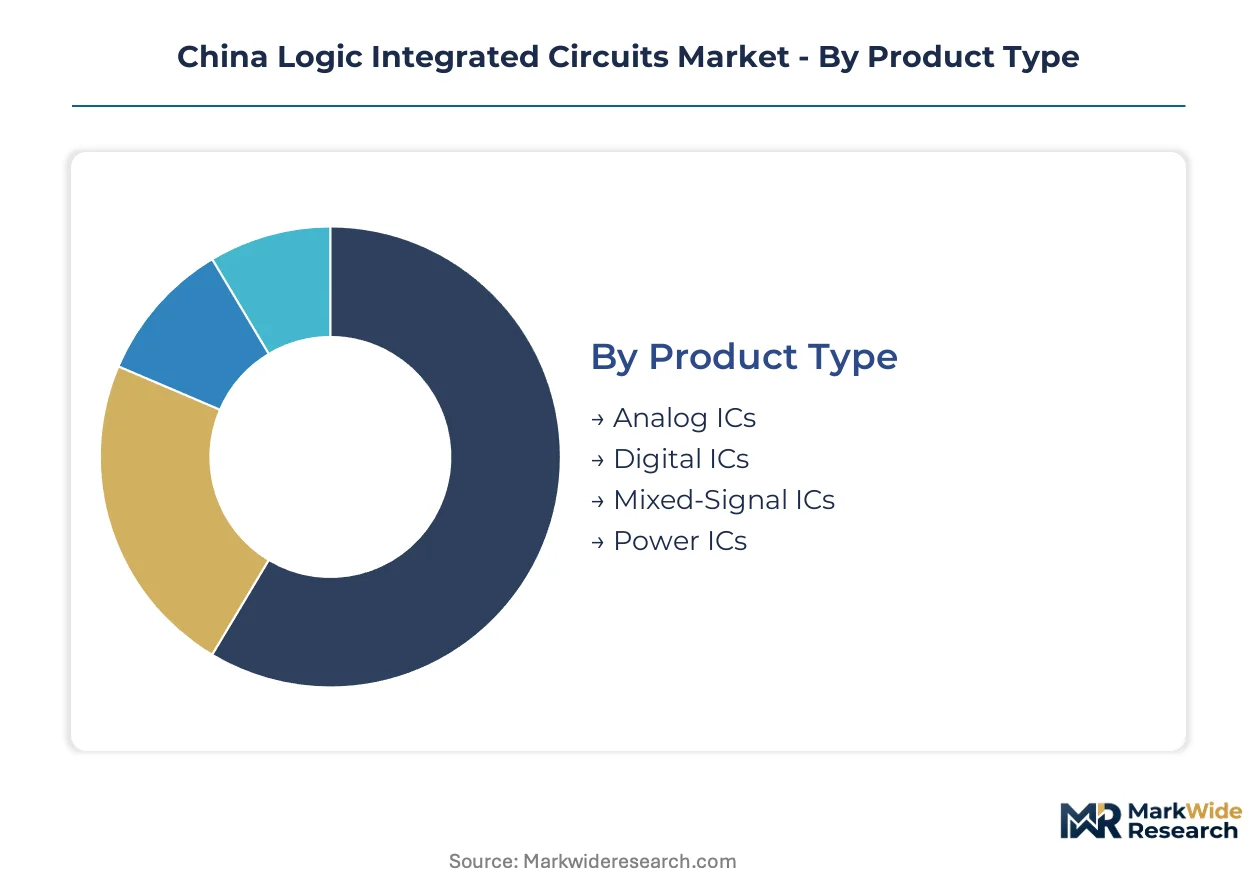
Logic IC segmentation in China reflects divergent capital requirements across process nodes and packaging complexity. Procurement patterns vary sharply between automotive functional safety mandates and consumer electronics cost optimization.
Product Type:
Capital intensity escalates with digital precision requirements, from mature analog architectures to leading-edge mixed-signal integration.
- Digital ICs:Boolean processors and memory controllers fabricated at nodes from 28nm to 7nm and below. Yangtze River Delta foundries concentrate capacity for 5G baseband and electric vehicle powertrain controllers under MIIT procurement quotas.
- Mixed-Signal ICs:Architectures merging analog-to-digital conversion with digital signal processing on unified die. Sensor fusion interfaces for smart manufacturing equipment in Jiangsu and Zhejiang provinces are expanding at triple the rate of pure digital alternatives.
- Analog ICs:Continuous signal amplifiers and voltage regulators requiring less lithography precision but specialized device physics expertise.
- Power ICs:Voltage regulators and motor drivers for industrial automation and automotive subsystems, typically fabricated at trailing nodes with thick-oxide options.
Most installed capacity flows through Digital ICs. Expansion is steepest in Mixed-Signal ICs.
End User:
Customer concentration determines margin structure, with automotive qualification premiums separating safety-critical procurement from consumer-grade volume plays.
- Automotive:Functional safety-certified logic for electric vehicle powertrain management and ADAS sensor fusion. Shanghai-based electric vehicle manufacturers are co-locating engineers at Yangtze River Delta foundries to compress NMPA-aligned validation cycles.
- Telecommunications:Baseband processors and routing fabric for 5G infrastructure deployment. MIIT domestic procurement mandates are redirecting demand toward certified local suppliers for base station controllers.
- Consumer Electronics:Smartphone application processors and wearable device controllers facing intense cost pressure and shorter product lifecycles.
- Industrial Equipment:Programmable logic controllers and motor drive interfaces requiring extended temperature ranges and protocol compatibility with legacy installed bases.
Automotive commands the highest unit margins. Consumer Electronics delivers the greatest volume throughput.
Technology:
Process platform selection locks in equipment depreciation schedules and talent acquisition strategies for multi-year fab commitments.
- CMOS:Dominant complementary metal-oxide-semiconductor platform for power-efficient digital computation at nodes from 28nm to advanced geometries. SMIC and Hua Hong Semiconductor anchor capacity across trailing and leading-edge variants in Shanghai and Jiangsu.
- GaN:Gallium nitride-on-silicon processes for high-frequency power switching in telecommunications base stations. Equipment import licensing friction from Dutch and Japanese suppliers constrains node migration timelines for domestic foundries.
- BiCMOS:Bipolar-CMOS integration for precision analog-to-digital conversion in industrial sensor interfaces.
- Bipolar:Legacy junction transistor architectures persisting in high-voltage industrial and automotive applications.
CMOS absorbs the majority of capital expenditure. GaN attracts the most aggressive capacity expansion timelines.
Application:
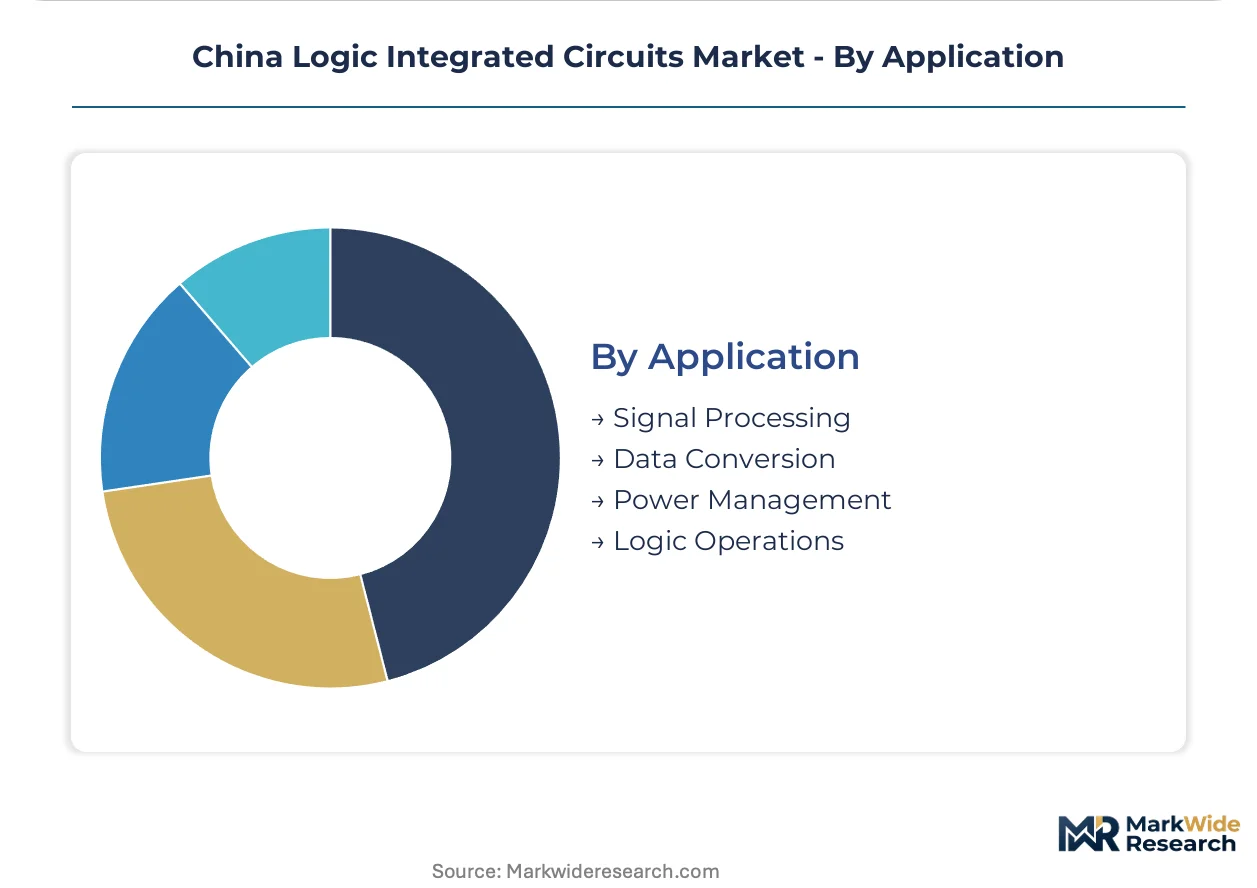
Functional specialization dictates packaging complexity and test handler requirements, separating commodity logic from precision signal chain integration.
- Signal Processing:Digital filter banks and Fourier transform accelerators for telecommunications and audio systems. 5G infrastructure rollout in eastern provinces is concentrating demand for high-throughput baseband logic.
- Power Management:Voltage regulation and battery charging controllers for portable electronics and electric vehicles. Dual Carbon Policy energy-efficiency mandates from MEE are accelerating low-power logic adoption in data center edge deployments.
- Data Conversion:Analog-to-digital and digital-to-analog interfaces for sensor acquisition and audio reproduction.
- Logic Operations:General-purpose Boolean computation for microcontrollers and peripheral controllers in embedded systems.
Signal Processing claims the largest design engineering headcount. Power Management is gaining share fastest under energy-efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing logic IC production toward provinces offering land and power cost advantages under MIIT's self-sufficiency mandates, compressing the traditional Yangtze River Delta dominance.
Shanghai-Jiangsu-Zhejiang Cluster
Electric vehicle powertrain controllers and 5G baseband processors concentrate demand in this corridor. MIIT procurement quotas redirect public infrastructure tenders toward certified domestic suppliers. SMIC and Hua Hong Semiconductor anchor foundry capacity across trailing and leading-edge nodes in Shanghai and Wuxi.
Beijing-Tianjin-Hebei Corridor
Telecommunications infrastructure and high-performance computing integration drive logic demand for state-backed cloud deployments. GB standards for semiconductor reliability shape product qualification requirements for government procurement. Design houses cluster in Zhongguancun technology parks to co-locate with state-owned enterprise engineering teams.
Sichuan-Chongqing
Industrial automation and automotive electronics manufacturing pull mature-node logic capacity inland. Provincial subsidy programs under western development initiatives offset equipment import licensing delays. Chengdu and Chongqing foundry zones attract trailing-node fabrication serving programmable logic controller replacement cycles.
Hubei
Wuhan-based memory-logic integration projects target data center and edge computing deployments. MEE energy-efficiency mandates for server infrastructure accelerate low-power logic adoption. Yangtze River storage and Wuhan Xinxin anchor captive capacity for state-backed semiconductor self-sufficiency programs.
Guangdong
Consumer electronics assembly concentration in Shenzhen and Dongguan generates demand for smartphone application processors and wearable controllers. SAMR antitrust enforcement constrains vertical pricing coordination between foundries and design houses. Pearl River Delta procurement teams establish direct foundry engagement models to compress iteration cycles.
China Logic Integrated Circuits Market Competitive Landscape
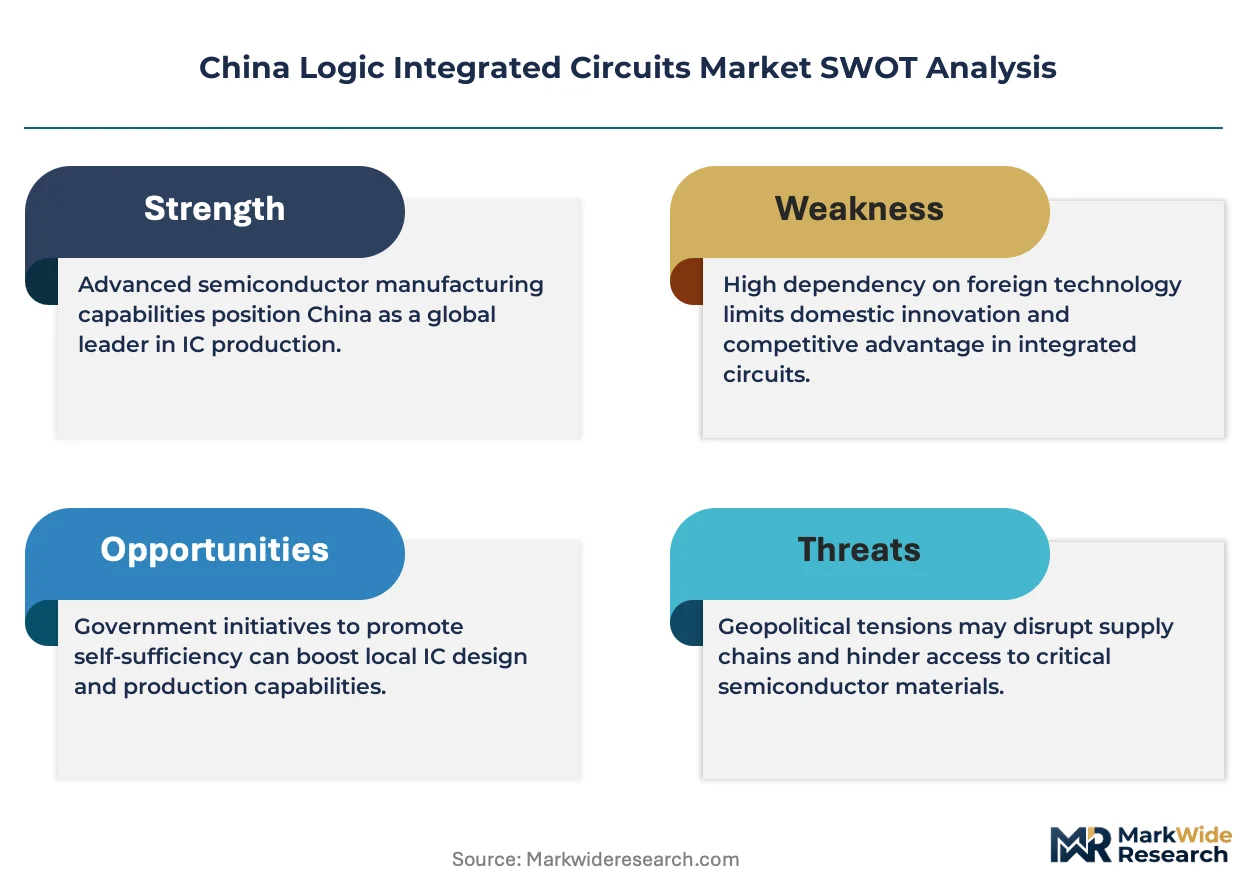
Yangtze River Delta producers anchor the scale-driven tier; Beijing-Tianjin specialists hold design-intensive positions. The vendor base organizes around foundry service providers, fabless design houses, and integrated device manufacturers with captive fabrication. Three strategic archetypes dominate: state-backed champions with policy-protected procurement access, private fabless specialists in telecommunications and consumer verticals, and industrial-grade mixed-signal suppliers. Capacity expansion and direct foundry engagement models constitute the dominant competitive moves, with procurement teams co-locating engineers at fabrication sites.
Among state-backed fabricators, SMIC anchors leading-edge node development despite equipment import constraints. HiSilicon exemplifies the fabless design house archetype, sustaining telecommunications-optimized logic architectures. Hua Hong Semiconductor occupies a position within the trailing-node specialist tier, concentrating on industrial and automotive-grade production.
| Leading Market Players |
|---|
| SMIC |
| HiSilicon |
| Hua Hong Semiconductor |
| UNISOC |
| GigaDevice Semiconductor |
| Loongson Technology |
| Allwinner Technology |
| Rockchip Electronics |
| Silan Microelectronics |
| Others |
Pricing and Supply Chain Analysis
Chiplet-based modular architectures are compressing yield economics and redistributing fabrication value toward packaging specialists, simultaneously fragmenting traditional foundry pricing power while concentrating advanced-interconnect supply in Yangtze River Delta corridors.
Pricing Analysis
Distributor margin compression is accelerating direct foundry engagement as electric vehicle manufacturers and telecommunications deployers negotiate volume offtakes. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates NMPA-aligned functional safety premiums from commodity logic. Pricing pressure stems from SAMR antitrust enforcement constraining vertical coordination between foundries and design houses. Consumer electronics procurement teams exhibit highest price sensitivity, while automotive safety-critical segments absorb certification-driven premiums.
Supply Chain Analysis
Returns and refurbishment flows for trailing-node industrial controllers remain underdeveloped, constraining circular supply development. Wafer supply concentrates in Taiwan, South Korea, and Japan, with domestic 300mm substrate capacity insufficient for leading-edge logic demand. Lithography equipment, specialty gases, and advanced photoresist constitute critical input dependencies. Single-source vulnerability around Dutch and Japanese lithography tool suppliers extends node migration timelines. Distribution runs through direct foundry partnerships displacing traditional component distribution in automotive and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China logic integrated circuits function as a stable compounder under MIIT semiconductor self-sufficiency mandates, with procurement quota structures delivering predictable demand visibility across automotive and telecommunications end-uses.
For Market Incumbents: Anchor trailing-node capacity in Hubei and Sichuan provinces to capture land and power cost arbitrage against Yangtze River Delta concentration. Defend against emerging fabless specialists by deepening captive reliability testing capacity for NMPA-aligned automotive certification acceleration. Prioritize direct procurement team co-location with electric vehicle manufacturers to lock capacity allocation through design-for-manufacturing integration.
For New Entrants and Emerging Players: E-commerce-enabled component marketplaces offer low-friction routes to penetrate industrial automation replacement cycles in Central China. Target mixed-signal logic architectures for smart manufacturing equipment, where sensor fusion interface demand expands at triple the rate of pure digital controllers. Pursue foundry-less design house positioning, leveraging SMIC and Hua Hong Semiconductor capacity access through MIIT certification pathways.
For Investors and Strategic Acquirers: Valuations sit cheapest among trailing-node specialists with automotive-grade certification infrastructure and provincial subsidy access. Five-to-ten-year viability rests on equipment import licensing resolution and domestic lithography tool maturation. Monitor Dutch and Japanese export control policy shifts as inflection indicators for leading-edge node economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Development | SMIC leverages domestic equipment alternatives to reduce lithography tool import dependence. |
| Automotive Certification Investment | NMPA-aligned testing capacity accelerates functional safety qualification timelines for electric vehicle controllers. |
| Chiplet Packaging Integration | Modular architectures bypass sub-7nm yield limitations while redistributing value to interconnect specialists. |
| Central China Capacity Migration | Hubei and Sichuan foundry zones capture cost arbitrage for mature-node industrial logic production. |
| Direct Foundry Engagement | Tier-one manufacturers co-locate procurement engineers to compress design iteration cycles. |
Research Methodology
Multiple input streams — primary interviews with foundry operations executives, fabless design house CTOs, and automotive procurement directors; secondary validation through MIIT policy filings, SAMR antitrust records, and customs trade data; and bottom-up capacity modeling against top-down demand aggregation — were reconciled to construct market estimates.
Historical wafer shipment patterns were cross-referenced against panel input from equipment vendors and substrate suppliers to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type, end user, technology platform, and regional production cluster. CAGRs were derived from node-specific capacity ramps weighted by procurement quota implementation timelines. Forecast inputs incorporated equipment import licensing friction assumptions and provincial subsidy program phase-out schedules.
The model assumes a particular technology adoption path; alternative pathways for domestic lithography tool maturation would alter the outlook. Forecasts reflect assumptions around MIIT procurement quota enforcement intensity and NMPA certification timeline compression. Practitioners should monitor Dutch and Japanese export control policy developments, Yangtze River Delta foundry utilization rates, and central China provincial subsidy renewal signals for early indications of supply-demand rebalancing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market