
 Semiconductor Integrated Circuit Chip Market | 2026-2036
Semiconductor Integrated Circuit Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Integrated Circuit Chip Market Analytics
Japan's $6.8 billion supplementary semiconductor subsidy package is rewriting how East Asian governments compete for trailing-edge and advanced logic capacity. TSMC anchors this regional dynamic through its Kumamoto fab complex, leveraging Japanese equipment vendor relationships to secure process stability. Samsung Electronics competes through its Pyeongtaek line expansions, sustaining memory and foundry output simultaneously. Intel Corporation navigates a costly repositioning, operating Arizona and Ohio fabs while seeking external foundry customers to fill capacity.
A semiconductor integrated circuit chip is a miniaturized electronic circuit fabricated on a monolithic semiconductor substrate, typically silicon, containing interconnected transistors, resistors, and capacitors that perform analog, digital, or mixed-signal processing functions. Fabrication involves photolithography, ion implantation, and chemical vapor deposition to achieve feature sizes measured in nanometers, with current leading-edge production at 3nm and research targeting 2nm gate-all-around architectures. Digital chips dominate value capture in data center and AI accelerator applications, where NVIDIA Corporation and AMD specialize in GPU and CPU architectures respectively. Analog and mixed-signal segments occupy stable margin pools in automotive and industrial equipment, where Texas Instruments controls broad catalog distribution and long product lifecycles insulate against cyclical downturns. Power management chips represent the fastest-growing product category, driven by electrification across consumer electronics and automotive end users where GaN technology displaces silicon in high-frequency switching applications.
US CHIPS and Science Act disbursements through the Department of Commerce shape where domestic fabrication capacity expands, while EU Chips Act funding under the European Commission redirects subsidy eligibility toward 2nm pilot lines and mature-node automotive supply security. Japan's METI coordinates equipment and materials supplier consolidation to protect its lithography and chemical supply chain position. Stakeholders must monitor which regulatory frameworks attach domestic content requirements to defense, automotive, or telecommunications procurement, as these rules determine market access for foundry services and fabless design houses alike.
Market Dynamics
Advanced node lithography costs are concentrating foundry investment among three capital pools, while sovereign subsidy programs redirect where new fabrication capacity physically lands. Equipment lead times now exceed 18 months for EUV systems, locking in geographic winners.
Growth Catalysts
- Automotive electrification:Battery management systems and inverter modules require power semiconductors with higher voltage tolerance. Each electric vehicle integrates 2,000-3,000 discrete chips across drivetrain and cabin electronics.
- EU Chips Act capital allocation:The European Commission's €43 billion framework prioritizes 2nm pilot lines and mature-node automotive supply security, attracting equipment vendors to Dresden and Leuven clusters.
- Gate-all-around transistor architecture:Samsung Electronics and TSMC migration to 3nm GAA processes improves power efficiency for AI accelerators and data center processors.
Market Restraints
- EUV equipment concentration:ASML Holding monopolizes extreme ultraviolet lithography systems, creating single-source dependency for nodes below 7nm.
- Neon gas supply fragility:Ukrainian purification facilities historically supplied 90% of semiconductor-grade neon; conflict-driven disruption forced fabs to qualify alternative Eastern European sources.
- Water intensity at leading nodes:TSMC's Tainan facilities consume 150,000 tons of ultra-pure water daily, exposing output to drought cycles in Taiwan's southern industrial corridor.
Strategic Opportunities
- India's semiconductor assembly and test expansion:The country's PLI scheme for electronics manufacturing incentivizes OSAT investment in Gujarat and Karnataka, capturing backend value from imported wafers.
- Chiplets and advanced packaging:Disaggregating monolithic dies into interconnected tiles reduces yield loss on large AI accelerators while enabling heterogeneous integration of logic and memory.
- GaN-on-silicon power devices:Gallium nitride technology penetrates consumer fast-charging adapters and automotive onboard chargers, displacing silicon MOSFETs above 100kHz switching frequencies.
Industry Challenges
- Process engineer scarcity:Leading-edge fabs require PhD-level expertise in plasma physics and materials science; training pipelines lag capacity expansion timelines in Arizona, Kumamoto, and Dresden.
- Legacy node equipment obsolescence:Automotive and industrial chip demand concentrates at 28nm-90nm nodes where depreciation schedules conflict with 15-20 year product lifecycle requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Integrated Circuit Chip Market |
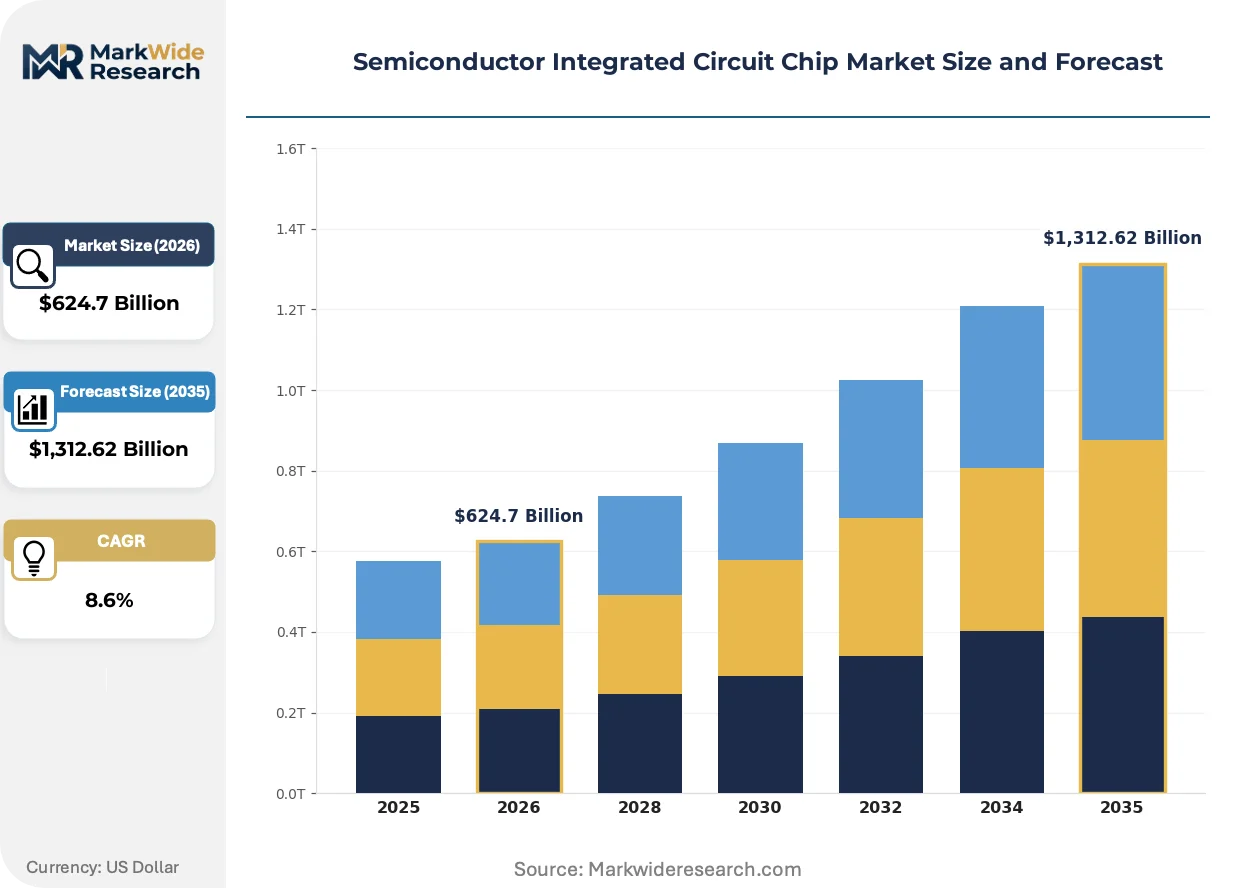
| Market Size in 2026 | $624.7 Billion |
| Market Size in 2035 | $1,312.62 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Chips, Digital Chips, Mixed-Signal Chips, Power Management Chips Technology: CMOS, BiCMOS, GaN, SOI End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Application: Smartphones, Tablets, Laptops, IoT Devices |
| Companies Covered | Samsung Electronics, Qualcomm Incorporated, NVIDIA Corporation, Texas Instruments, Advanced Micro Devices (AMD), Taiwan Semiconductor Manufacturing Company (TSMC), Intel Corporation, Micron Technology, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Integrated Circuit Chip Market Evolving Landscape
Photolithography resolution limits are forcing architectural pivots in transistor design and packaging, while sovereign industrial policy reshapes where capital deploys. Three concurrent developments define the current innovation cycle.
Gate-all-around nanosheet transistors is collapsing the traditional planar-to-FinFET evolution timeline. Samsung's 3nm process adoption by cryptocurrency mining ASIC designers validates power efficiency claims. The technology is collapsing node migration cycles from 24 months toward 18 months for AI-centric foundry customers.
REACH chemical restrictions on per- and polyfluoroalkyl substances are forcing photoresist reformulation across EU-based fabs. Industrial consequence includes qualification delays for new material stacks at IMEC's 2nm research line. Automotive sensor chip suppliers are responding fastest, prioritizing PFAS-free processes to secure CE marking continuity.
Direct foundry contracting by hyperscale cloud operators is displacing traditional merchant silicon procurement through OEM intermediaries. Amazon Web Services and Microsoft Azure now specify custom CPU and AI accelerator tape-outs directly with TSMC and Intel Foundry. This pattern is most visible in US data center buildouts, where captive silicon design teams rival fabless semiconductor houses in headcount scale.
Semiconductor Integrated Circuit Chip Market Segmentation
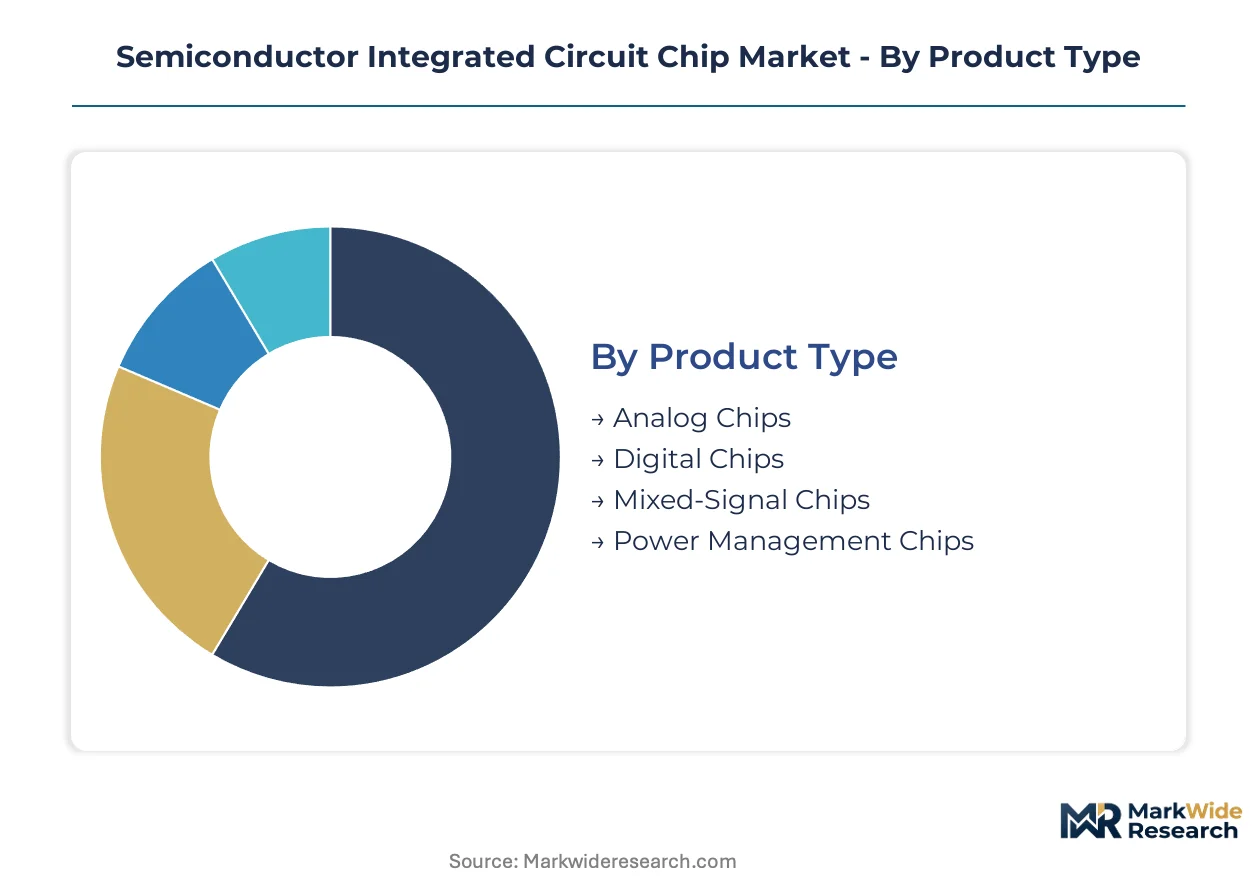
Semiconductor integrated circuit chip segmentation reveals how fabrication complexity, voltage tolerance, and thermal constraints map to divergent margin structures. Each category captures distinct procurement patterns from fabless design houses, captive IDM operations, and systems integrators.
Product Type:
Design complexity and voltage tolerance separate product tiers, with power efficiency requirements driving foundry process selection.
- Digital Chips:Logic gates execute Boolean operations at nanometer-scale feature sizes, with 3nm gate-all-around architectures now entering volume production. Data center AI accelerators and smartphone application processors concentrate demand in Taiwan's foundry cluster, where EUV lithography capacity constrains supply allocation.
- Analog Chips:Continuous signal processing functions require larger feature geometries and specialized doping profiles, insulating margins from leading-edge capex cycles. Texas Instruments and Renesas Electronics dominate catalog distribution for automotive sensor interfaces and industrial control loops, where product lifecycles extend 15-20 years.
- Mixed-Signal Chips:ADCs and DACs bridge analog sensor inputs with digital processing cores in single-die integration. RF front-end modules for 5G base stations and automotive radar systems drive qualification requirements.
- Power Management Chips:Voltage regulators and battery charging circuits integrate wide-bandgap materials for higher switching frequencies. GaN transistors displace silicon MOSFETs in fast-charging adapters above 100kHz.
The dominant share belongs to Digital Chips, while Power Management Chips is closing the gap fastest.
Technology:
Process node economics and substrate material properties determine which technology platforms capture design wins at each voltage-frequency operating point.
- CMOS:Complementary metal-oxide-semiconductor logic dominates digital circuit fabrication through scalable planar and FinFET transistor architectures. TSMC and Samsung Electronics allocate EUV scanner capacity to 5nm and 3nm CMOS flows for high-performance computing and mobile SoC customers.
- GaN:Gallium nitride-on-silicon heterostructures enable breakdown voltages above 600V with superior electron mobility. Onboard chargers and DC-DC converters in electric vehicles drive qualification timelines at tier-1 automotive suppliers.
- BiCMOS:Bipolar-CMOS integration combines high-speed analog performance with dense digital logic for precision timing circuits. Optical transceivers and satellite communication payloads specify BiCMOS for jitter-critical signal paths.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance and leakage current through buried oxide isolation layers. RF switches and low-power IoT edge processors exploit SOI's substrate advantages.
CMOS commands the largest installed capacity base, though GaN is expanding most quickly in power conversion applications.
End User:
Procurement scale and qualification rigor vary sharply across end-user verticals, with automotive and industrial segments imposing the longest certification cycles.
- Automotive:Battery management systems and inverter modules require AEC-Q100 qualification and ISO 26262 functional safety certification. Each electric vehicle integrates 2,000-3,000 discrete chips across powertrain and cabin electronics domains.
- Consumer Electronics:Annual smartphone refresh cycles compress design-to-tapeout timelines to 12-18 months. Apple and Samsung Electronics drive leading-edge node allocation through guaranteed volume commitments.
- Telecommunications:Base station infrastructure and optical transport equipment demand 99.999% reliability over 10-15 year deployment horizons. Huawei and Ericsson specify extended temperature range components for outdoor installations.
- Industrial Equipment:Programmable logic controllers and motor drives prioritize supply continuity over leading-edge performance. Long depreciation schedules align with 28nm-90nm mature node sourcing strategies.
Consumer Electronics absorbs the greatest wafer volume, yet Automotive is gaining share fastest as electrification multiplies chip content per vehicle.
Application:
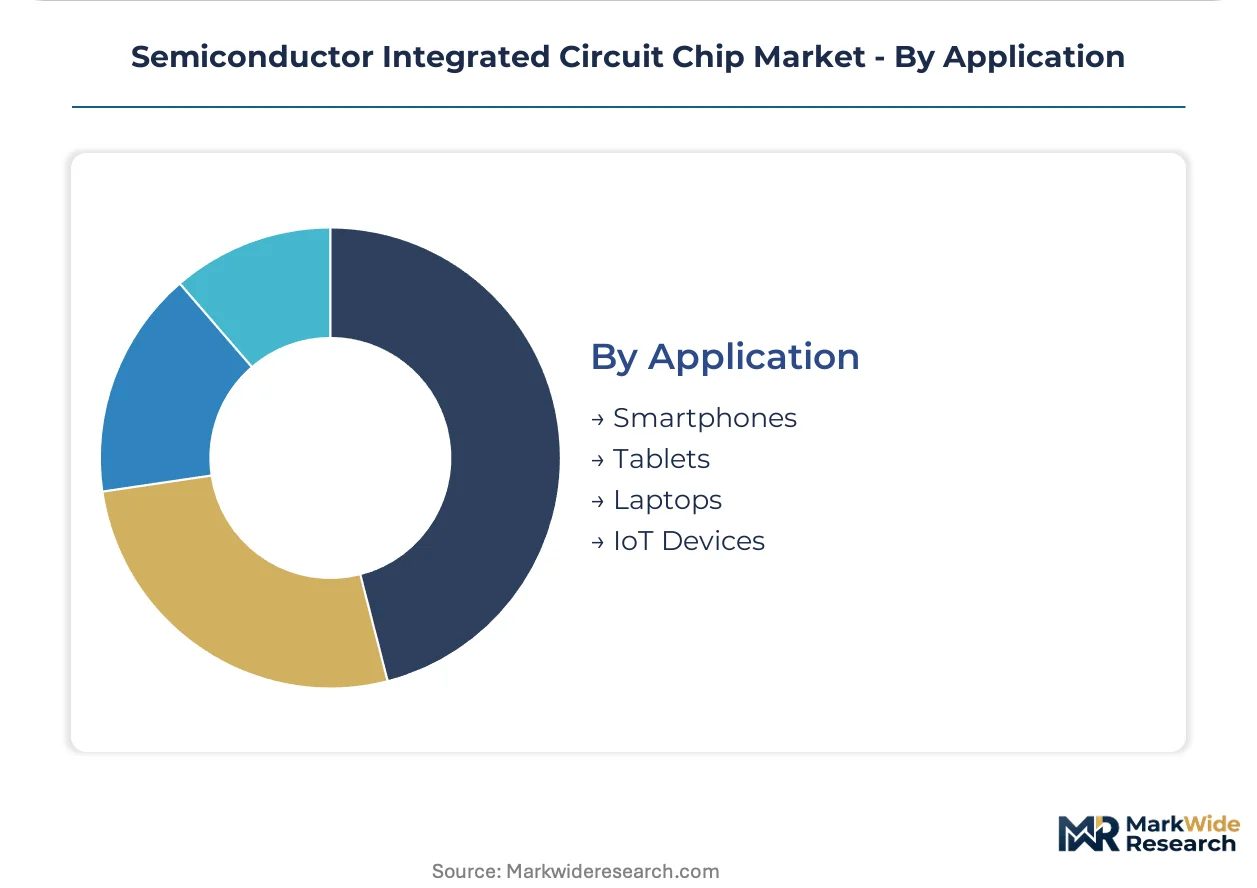
Form factor constraints and thermal budgets segment applications, with mobile devices driving miniaturization and IoT endpoints prioritizing energy harvesting compatibility.
- Smartphones:System-on-chip integration combines CPU, GPU, NPU, and modem functions in sub-100mm² die areas. Qualcomm and MediaTek compete for flagship Android design wins on TSMC 4nm processes.
- IoT Devices:Sub-threshold logic and intermittent computing architectures extend battery life to 10-year maintenance intervals. Smart home sensors and industrial predictive maintenance nodes specify ultra-low-power microcontrollers.
- Laptops:x86 and ARM instruction set architectures compete for thin-and-light form factor dominance. AMD and Apple Silicon designs exploit advanced packaging for memory bandwidth expansion.
- Tablets:Display driver integration and touch controller co-packaging reduce board area in education and enterprise fleet deployments.
Smartphone applications command the dominant revenue pool, while IoT Devices is climbing the fastest as edge AI inference migrates to distributed endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leading-edge fabrication capacity clusters in Taiwan, South Korea, and the United States, while sovereign subsidy programs redirect capital toward Japan, Germany, and India. Equipment lead times exceeding eighteen months for EUV systems lock in geographic winners for nodes below 7nm.
United States
Hyperscale cloud operators and defense contractors drive demand for domestic advanced logic capacity. CHIPS and Science Act disbursements through the Department of Commerce prioritize Arizona and Ohio fab construction. Intel Corporation operates captive fabrication in these states while seeking external foundry customers to fill expanded capacity.
China
Memory and mature-node logic demand from telecommunications infrastructure and industrial equipment sustains wafer consumption. MIIT coordinates domestic equipment vendor development to circumvent lithography tool restrictions. Yangtze Memory Technologies and SMIC anchor production in the Yangtze River Delta and Shanghai clusters.
Japan
Automotive electrification and industrial automation multiply chip content across powertrain and factory equipment. METI's $6.8 billion supplementary subsidy package redirects capital toward trailing-edge and advanced logic capacity. TSMC's Kumamoto fab complex leverages Japanese equipment vendor relationships to secure process stability.
Germany
Automotive OEMs and industrial machinery builders require AEC-Q100 qualified components for electric drivetrains. EU Chips Act funding under the European Commission prioritizes 2nm pilot lines and mature-node automotive supply security. Dresden and Leuven clusters attract equipment vendors for advanced packaging development.
South Korea
Consumer electronics refresh cycles and AI accelerator demand concentrate leading-edge wafer allocation. Samsung Electronics competes through Pyeongtaek line expansions, sustaining memory and foundry output simultaneously. The Seoul Capital Area anchors both design and fabrication activities for export-oriented semiconductor supply.
Semiconductor Integrated Circuit Chip Market Competitive Landscape
Integrated device manufacturers and pure-play foundries split the market between captive fabrication and merchant silicon supply. Memory specialists and logic designers occupy distinct margin pools with limited overlap in capital allocation. Three archetypes dominate: vertically integrated IDMs controlling design-through-fabrication, pure-play foundries monetizing process technology, and fabless design houses capturing value through architecture. Competitive dynamics center on capacity expansion timing and strategic partnerships for advanced packaging access.
Within the foundry tier, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify scale-driven process leadership. NVIDIA Corporation occupies a position as architecture specialist in AI accelerators, while Intel Corporation represents the repositioning IDM archetype navigating merchant foundry entry. Texas Instruments anchors analog and mixed-signal catalog distribution with extended product lifecycles.
| Leading Market Players |
|---|
| Samsung Electronics |
| Qualcomm Incorporated |
| NVIDIA Corporation |
| Texas Instruments |
| Advanced Micro Devices (AMD) |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Intel Corporation |
| Micron Technology |
| Broadcom Inc. |
| Others |
Value Network & Pricing Analysis
ASML Holding's monopoly on EUV lithography systems anchors pricing power for nodes below 7nm, concentrating margin capture among Taiwan's foundry cluster while downstream fabless designers absorb equipment cost pass-through. Contract structures now embed long-term offtake commitments to secure wafer allocation, with automotive OEMs accepting premium pricing for AEC-Q100 qualified capacity.
Pricing Analysis
The EU Chips Act dictates the pricing tier structure for European-sourced wafers, attaching domestic content requirements to defense and automotive procurement. Three-tier pricing structure across premium, standard, and economy levels separates leading-edge AI accelerators from mature-node automotive chips and legacy industrial components. Cost compression in mature-node segments is intensifying because depreciation schedules conflict with 15-20 year product lifecycle requirements. Automotive OEMs exhibit the lowest price sensitivity due to qualification rigor, while consumer electronics brands negotiate aggressively on volume commitments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for equipment vendors and raw material suppliers. Manufacturing concentrates in Taiwan, South Korea, and the United States for advanced logic, while Japan and Germany anchor specialty materials and automotive-grade production. The supply chain draws from Ukrainian neon purification facilities, high-purity silicon wafers, and rare earth elements for magnet components. Single-source vulnerability in EUV scanner availability threatens capacity expansion timelines. Distribution runs through direct foundry contracting with hyperscale cloud operators displacing traditional OEM intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound semiconductors threaten silicon's dominance in power conversion above 100kHz, forcing incumbents to defend process node leadership while qualifying wide-bandgap alternatives.
For Market Incumbents: Insulate trailing-edge margins by securing long-term automotive supply agreements before legacy equipment obsolescence accelerates. Deepen backward integration into silicon carbide and gallium nitride substrate supply to counter compound semiconductor substitution in onboard chargers. METI subsidy coordination in Japan offers a template for sovereign capacity protection. For New Entrants and Emerging Players: Establish a beachhead in India's semiconductor assembly and test expansion, where PLI incentives reduce capital barriers for OSAT operations. Target automotive power management segments where AEC-Q100 qualification gaps create procurement bottlenecks for tier-1 suppliers. Partner with Japanese equipment vendors to leverage existing process stability relationships for faster fab qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 2nm pilot line development, favoring asset-light design houses over captive fabrication strategies. Analog and mixed-signal catalog distributors with 15-20 year product lifecycles present acquisition profiles resilient to cyclical downturns. Watch for gate-all-around yield inflection at Samsung and TSMC as a signal for node migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Substrates | Wolfspeed and Coherent anchor supply security for automotive inverter modules. |
| EUV Equipment Reservation Agreements | ASML order backlocks determine geographic winners in advanced node expansion. |
| Chiplets and Advanced Packaging Partnership | AMD and Intel Foundry exploit heterogeneous integration for AI accelerator yield. |
| GaN-on-Silicon Process Qualification | Navitas and Infineon displace silicon MOSFETs in 100kHz+ switching applications. |
| Automotive Functional Safety Certification | ISO 26262 compliance opens procurement channels to electric drivetrain programs. |
Research Methodology
Desk research of SEC filings, foundry capex disclosures, and EU Chips Act funding allocations preceded structured interviews with fab operations executives, fabless design house CTOs, automotive tier-1 procurement directors, and equipment vendor sales leads. Primary fieldwork captured capacity expansion timelines and qualification protocols, validated against customs data for silicon wafer and specialty chemical trade flows. Bottom-up wafer demand modeling and top-down semiconductor consumption estimates were triangulated to anchor volume projections.
Assumptions held fixed include sovereign subsidy disbursement schedules, EUV equipment delivery timelines, and automotive electrification penetration curves. Segmentation dimensions modeled encompass process node tiers, substrate material platforms, end-user verticals, and geographic production clusters. CAGRs were derived from regression analysis against historical foundry utilization rates and capital intensity trends. Forecast inputs include gate-all-around yield curves and wide-bandgap material cost reduction trajectories across the projection horizon.
Stress conditions across neon supply disruption severity, Taiwan drought cycle frequency, and EU REACH chemical restriction enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding equipment vendor concentration and sovereign industrial policy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
APAC Analog IC Market