
 Global Application Specific Industrial Analog IC Market | 2026-2036
Global Application Specific Industrial Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Specific Industrial Analog IC Market Foresight
Modular power-stage bundling is realigning procurement patterns for industrial motor drives and robotic controllers. Texas Instruments Incorporated leverages its foundry partnerships to sustain broad coverage across voltage regulator families. Infineon Technologies AG anchors its position in isolated gate drivers for factory automation through proprietary trench technologies. Analog Devices, Inc. competes on precision data converter integration, bundling signal conditioning with embedded diagnostics.
Application specific industrial analog ICs are mixed-signal semiconductor devices engineered for targeted industrial functions, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius with enhanced electromagnetic immunity. These devices process continuous voltage and current signals for motor control, sensor interfacing, and power conversion in electrically noisy environments. Power Management ICs dominate value capture because industrial equipment requires multiple isolated rails with tight load regulation. Signal Processors represent the fastest-expanding category as vibration analysis and predictive maintenance algorithms migrate to edge nodes. CMOS technology leads unit shipments while Bipolar processes retain share in high-voltage linear applications where breakdown robustness matters.
FDA oversight of industrial equipment used in pharmaceutical manufacturing shapes isolation and traceability requirements for analog ICs deployed in cleanroom automation. ECHA REACH restrictions on substance content directly affect package molding compounds and lead-frame finishes, forcing redesign cycles across European-qualified product lines. OSHA electrical safety standards in the United States mandate specific creepage and clearance margins that determine die size and package selection for line-powered industrial analog devices. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon rules will reshape foundry energy sourcing and subsequently alter supplier qualification timelines.
Market Dynamics
Modular power-stage bundling is compressing procurement cycles for motor drives and robotic controllers, forcing analog IC suppliers to integrate signal conditioning with embedded diagnostics or risk displacement by turnkey subsystem vendors.
Growth Catalysts
- Factory automation densification:Programmable logic controllers and servo motor drives in smart manufacturing lines demand tighter signal integrity, pulling application-specific analog ICs into edge nodes for real-time vibration analysis.
- ECHA REACH substance restrictions:Lead-free packaging mandates and halogen-free substrate requirements are accelerating redesign cycles, creating qualification windows for European-qualified product lines.
- China domestic substitution:Local equipment makers are qualifying indigenous analog IC sources for smart manufacturing lines, concentrating demand within domestic foundry ecosystems.
Market Restraints
- Raw material volatility:Copper and silicon carbide substrate costs fluctuate with energy-intensive smelting operations, squeezing gross margins on power management IC families.
- Foundry concentration risk:Advanced Bipolar process capacity clusters in Taiwan and South Korea, exposing supply continuity to geopolitical friction and export control escalations.
- Substitution by digital isolators:Magneto-resistive and capacitive isolation technologies encroach on traditional optocoupler strongholds in motor drive feedback loops.
Strategic Opportunities
- India manufacturing localization:PLI scheme incentives for electronic components are opening qualification pathways for industrial analog ICs in process automation and textile machinery.
- Predictive maintenance edge migration:Vibration analysis algorithms moving to sensor nodes create demand for precision data converters with embedded diagnostic capabilities.
- EU Green Deal embodied carbon rules:Foundry energy sourcing transparency requirements will reshape supplier qualification timelines, favoring fabs with renewable power purchase agreements.
Industry Challenges
- Mixed-signal design talent scarcity:Industrial analog IC development requires rare expertise spanning high-voltage Bipolar processes and CMOS precision design, with limited university pipeline output.
- Multi-jurisdiction certification overlap:Simultaneous OSHA electrical safety, FDA pharmaceutical equipment, and ECHA substance compliance extends product launch timelines by twelve to eighteen months.
- Legacy fieldbus integration friction:New signal processors must maintain backward compatibility with PROFIBUS and Modbus installations across brownfield factory floors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Specific Industrial Analog IC Market |
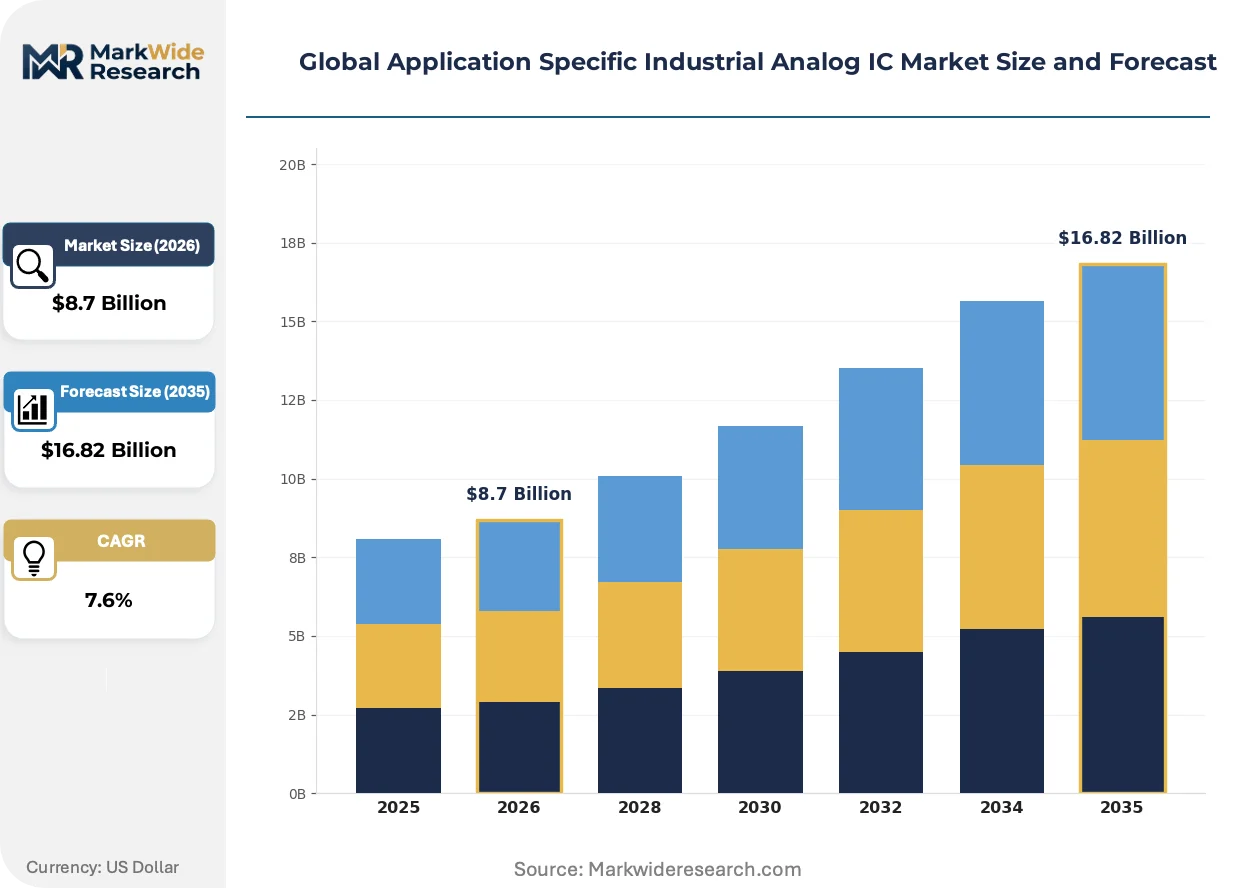
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $16.82 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Converters, Amplifiers, Voltage Regulators, Power Management ICs, Interface ICs, Signal Processors Technology: Bipolar, CMOS, BiCMOS, Silicon-Germanium, Junction Field Effect Transistor, Thin-Film Transistor Application: Factory Automation, Energy Management, Test Measurement, Consumer Electronics, Robotics, Security Systems End User Industry: Semiconductor Manufacturing, Aerospace Equipment, Telecommunications Equipment, Defense Systems, Instrumentation Providers, Renewable Energy Firms |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, Microchip Technology Inc., Renesas Electronics Corporation, ON Semiconductor, Skyworks Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Specific Industrial Analog IC Market Shifts & Advancements
Edge-native signal processing architectures are displacing centralized PLC-based analog chains, compressing latency budgets and rewriting component specification requirements across factory automation tiers.
Time-sensitive networking over standard Ethernet is decentralizing sensor-to-controller communication, eliminating dedicated analog backplanes. Automotive-tier suppliers entering industrial robotics are adopting TSN-enabled signal conditioners at twice the rate of incumbent factory automation vendors. This topology shift is decentralizing the market for isolated analog front-ends previously captive to proprietary fieldbus ecosystems.
EU F-Gas Regulation phase-down schedules are pressuring refrigerant-based cooling systems in power conversion equipment, accelerating adoption of liquid-cooled silicon carbide modules. Industrial motor drive manufacturers must redesign thermal management subsystems, triggering new specifications for high-temperature gate drivers. European-qualified analog IC portfolios face mandatory thermal cycling validation updates to maintain CE marking eligibility.
Equipment-as-a-service contracting is unbundling hardware procurement from maintenance obligations, compressing analog IC selection cycles. German machine tool builders now specify component lifespans in hourly operating contracts rather than calendar years, forcing suppliers to publish accelerated aging data. This model is most visible in packaging machinery and semiconductor capital equipment verticals.
Global Application Specific Industrial Analog IC Market Segmentation
Industrial analog IC procurement hinges on thermal performance, isolation ratings, and compliance breadth. Buyers weigh process node maturity against foundry geographic concentration. Segmentation reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Cost tier determines supplier stickiness, with premium families commanding longer qualification cycles and higher switching costs.
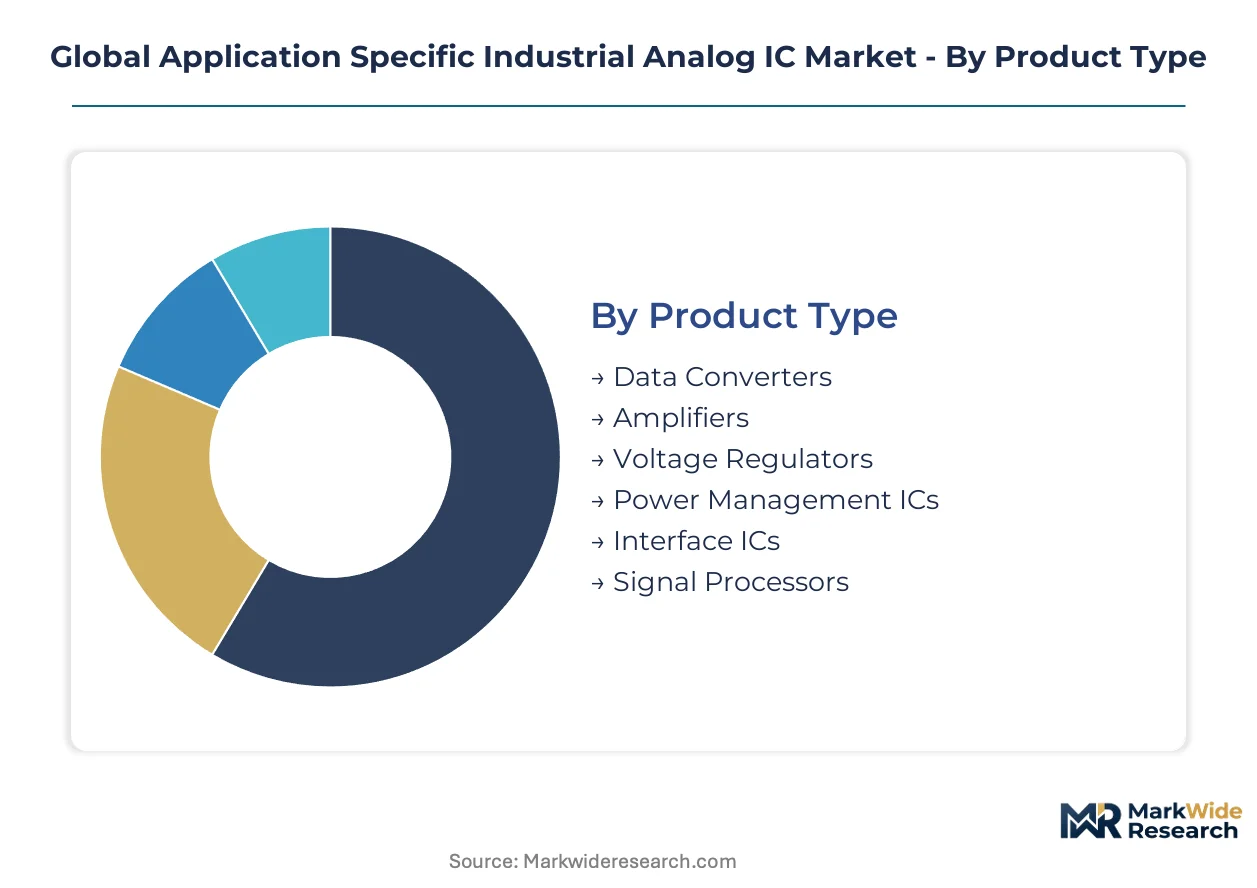
- Power Management ICs:These devices orchestrate multiple isolated voltage rails with load regulation tolerances below one percent. Demand clusters in German machine tool controllers and Chinese smart manufacturing lines where dual carbon mandates favor efficient power conversion architectures.
- Signal Processors:Edge-native architectures integrate vibration analysis and predictive maintenance algorithms at sensor nodes. Japanese automotive-tier suppliers adopt these twice as fast as legacy factory automation vendors for TSN-enabled robotic controllers.
- Data Converters:Precision ADCs and DACs bridge physical signals to digital control loops in semiconductor test equipment.
- Amplifiers:Instrumentation amplifiers with enhanced EMI immunity serve electrically noisy motor drive environments.
- Voltage Regulators:Wide-input-range LDOs and switching regulators stabilize rails for PLCs across brownfield installations.
- Interface ICs:Isolated transceivers translate between legacy fieldbus protocols and modern Ethernet backbones.
Power Management ICs lead on scale; Signal Processors lead on momentum.
Technology:
Process maturity shapes foundry allocation and determines which geometries can absorb REACH-mandated packaging redesigns.
- CMOS:Dominates unit shipments through scalable geometries and digital integration density. Taiwan-based foundry capacity for advanced nodes faces geopolitical friction, compressing allocation timelines for industrial analog designers.
- Bipolar:Retains share in high-voltage linear applications where breakdown robustness exceeds CMOS capabilities. Korean foundries concentrate advanced Bipolar capacity, exposing supply continuity to export control escalations.
- BiCMOS:Merges precision analog with moderate digital complexity for mixed-signal motor controllers.
- Silicon-Germanium:Enables high-frequency signal conditioning in test measurement equipment.
- Junction Field Effect Transistor:Provides low-noise front-ends for sensor interfacing in aerospace applications.
- Thin-Film Transistor:Supports specialized display driver integration for HMI panels in factory floors.
CMOS dominates volume shipments; Bipolar commands pricing power in high-voltage niches.
Application:
Application complexity dictates certification burden and design-in duration, with pharmaceutical and defense verticals imposing the longest timelines.
- Factory Automation:Programmable logic controllers and servo drives absorb the majority of application-specific analog IC value. FDA oversight of pharmaceutical manufacturing equipment shapes isolation and traceability requirements for cleanroom deployments in the United States.
- Robotics:Collaborative and industrial robotic arms demand precision current sensing and torque control loops. Chinese domestic equipment makers are qualifying local analog IC sources for smart manufacturing lines, concentrating demand within indigenous foundry ecosystems.
- Energy Management:Grid-tied inverters and storage systems require isolated gate drivers with extended temperature ratings.
- Test Measurement:Semiconductor capital equipment vendors specify component lifespans in hourly operating contracts rather than calendar years.
- Security Systems:Perimeter sensors and access control panels drive demand for low-power signal conditioning.
- Consumer Electronics:Industrial-grade variants serve ruggedized handhelds and field service equipment.
Factory Automation captures the deepest design-in relationships; Robotics is expanding most quickly.
End User Industry:
Customer concentration varies sharply, with semiconductor manufacturing equipment vendors consolidating procurement while renewable energy remains fragmented.
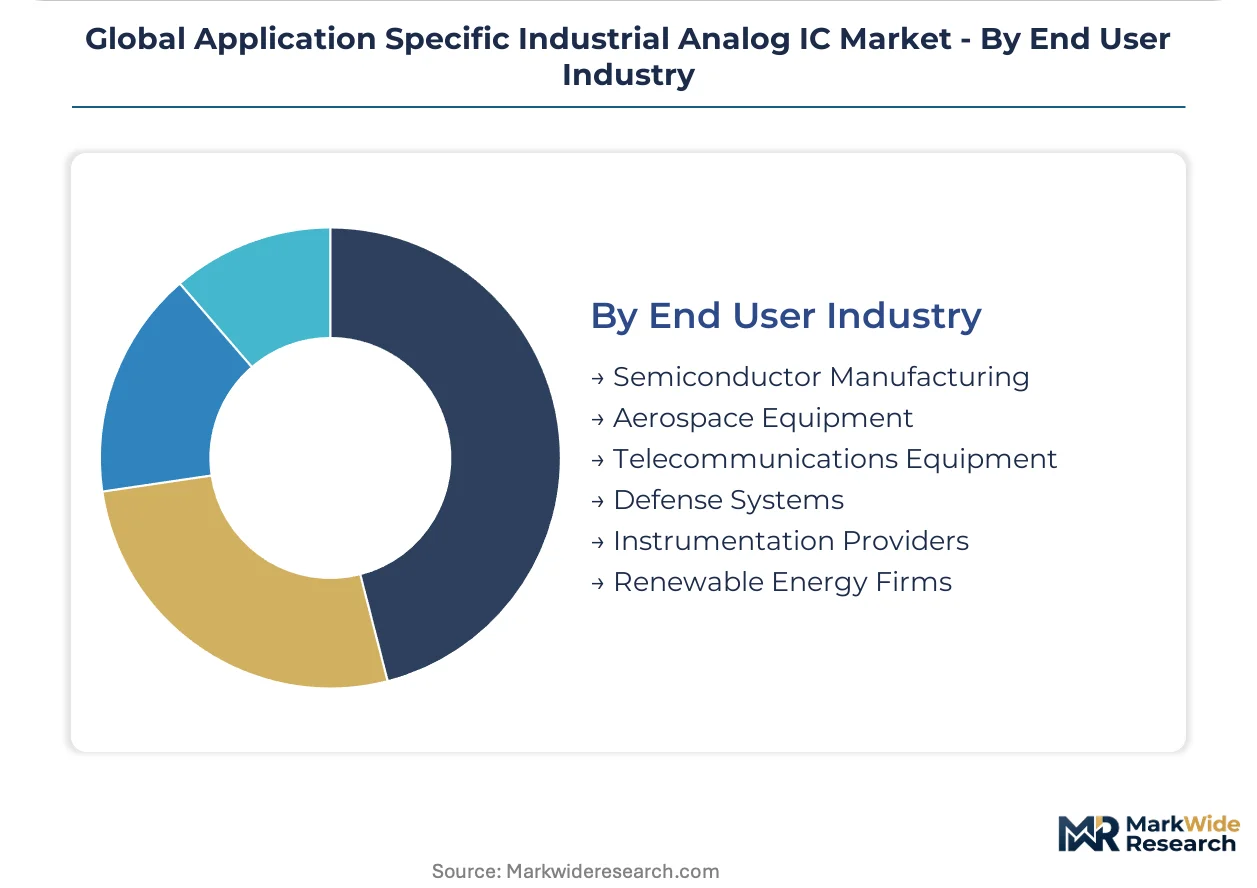
- Semiconductor Manufacturing:Capital equipment builders specify accelerated aging data under equipment-as-a-service contracts. German and Japanese lithography tool makers drive qualification requirements for high-reliability analog IC portfolios.
- Renewable Energy Firms:Solar inverter and wind turbine manufacturers source power management ICs with wide temperature ranges. EU Green Deal embodied carbon rules will reshape foundry energy sourcing transparency requirements for European-qualified product lines.
- Aerospace Equipment:DO-160G and MIL-STD-883 compliance extends development cycles for flight-critical signal chains.
- Defense Systems:ITAR and EAR export controls constrain supplier base for military-grade analog devices.
- Telecommunications Equipment:5G base station power amplifiers demand high-efficiency envelope tracking ICs.
- Instrumentation Providers:Oscilloscope and spectrum analyzer builders prioritize precision data converter integration.
Semiconductor Manufacturing leads on contract value; Renewable Energy Firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial analog IC design and manufacturing first scaled in Germany and the United States during the 1970s and 1980s, establishing precision instrumentation and process automation as foundational demand centers. Today, production and qualification activities span discrete national ecosystems with distinct regulatory and supply chain characteristics.
United States
Semiconductor capital equipment builders in California and Arizona specify accelerated aging data under equipment-as-a-service contracts. FDA oversight of pharmaceutical manufacturing equipment shapes isolation and traceability requirements for cleanroom deployments. Greater Boston hosts precision instrumentation clusters where OSHA electrical safety standards mandate specific creepage and clearance margins.
Germany
Machine tool controllers in Bavaria and Baden-Württemberg absorb power management ICs with sub-one-percent load regulation. ECHA REACH restrictions on substance content directly affect package molding compounds and lead-frame finishes. The Ruhr industrial corridor drives qualification requirements for high-reliability analog IC portfolios in process automation.
China
Domestic equipment makers in the Yangtze River Delta and Pearl River Delta are qualifying indigenous analog IC sources for smart manufacturing lines. MIIT dual carbon goals reshape foundry energy sourcing requirements. Shenzhen and Shanghai clusters concentrate demand within domestic foundry ecosystems for robotic controllers.
Japan
Automotive-tier suppliers in the Chubu region adopt TSN-enabled signal conditioners at twice the rate of legacy factory automation vendors. METI industrial policy supports precision data converter development. The Kansai corridor anchors vibration analysis algorithm migration to edge nodes.
South Korea
Advanced Bipolar process capacity clusters near Seoul and Busan, exposing supply continuity to export control escalations. Korean foundries concentrate high-voltage linear manufacturing where breakdown robustness exceeds CMOS capabilities. The Daejeon-Sejong corridor hosts mixed-signal design centers serving industrial motor drive specifications.
Global Application Specific Industrial Analog IC Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification breadth and thermal performance certification. The vendor base arranges into three tiers: broad-line suppliers with foundry partnerships, process specialists with proprietary trench technologies, and precision integrators bundling signal conditioning with diagnostics. Consolidation pressure favors M&A between complementary technology holders and strategic partnerships spanning European-qualified product lines.
Within the broad-line supplier tier, Texas Instruments Incorporated and Analog Devices, Inc. exemplify archetypes that sustain coverage across voltage regulator families and precision data converter integration respectively. Infineon Technologies AG occupies a position among process specialists leveraging proprietary isolation technologies for factory automation gate drivers. These three entities anchor competitive dynamics around foundry access, certification velocity, and bundled subsystem offerings.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| Microchip Technology Inc. |
| Renesas Electronics Corporation |
| ON Semiconductor |
| Skyworks Solutions |
| Others |
Supply & Pricing Matrix
Captive foundry partnerships anchor supply positioning and pricing power for industrial analog IC suppliers, with Texas Instruments and Infineon leveraging in-house or dedicated wafer capacity to buffer margin erosion from raw material volatility while commanding premium positioning on REACH-compliant European-qualified product lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification breadth and thermal performance grade. Premium tiers capture semiconductor manufacturing equipment and aerospace applications demanding DO-160G validation, while economy tiers serve price-sensitive consumer electronics ruggedization. Pricing pressure stems from copper and silicon carbide substrate cost volatility squeezing power management IC margins. Contract manufacturing buyers in Chinese smart manufacturing lines exhibit highest price sensitivity; FDA-regulated pharmaceutical equipment vendors show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German machine tool builders and Chinese domestic equipment makers, while distribution partners serve fragmented renewable energy inverter manufacturers. Foundry capacity clusters in Taiwan, South Korea, and China, with advanced Bipolar processes concentrated near Seoul and Busan. Raw material dependencies include high-purity silicon wafers, copper lead-frames, and halogen-free substrate compounds. Single-source vulnerability in Taiwan-based CMOS foundry allocation creates tariff exposure and geopolitical risk. Distribution runs through authorized component distributors and direct field application engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe run substantially higher than qualification thresholds in India's PLI scheme, creating margin expansion for suppliers relocating European-qualified product line validation to South Asian manufacturing incentives.
For Market Incumbents: Extend proprietary trench technology portfolios into silicon carbide gate driver modules before automotive-tier suppliers consolidate TSN-enabled signal conditioning share. Deepen backward integration into Bipolar wafer capacity through Korean foundry partnerships or captive expansion. Accelerate thermal cycling validation investments to maintain CE marking eligibility under EU F-Gas Regulation phase-down schedules. For New Entrants and Emerging Players: Industrial robotics distributors in China's Pearl River Delta offer qualified pathway access for indigenous analog IC sources seeking smart manufacturing line qualification. Target predictive maintenance edge migration in Japanese automotive-tier supply chains where vibration analysis algorithm adoption runs twice legacy factory automation rates. Pursue qualification-for-equipment-as-a-service contracting models in German packaging machinery verticals. For Investors and Strategic Acquirers: Roll-up economics work for precision data converter specialists because mixed-signal design talent scarcity limits organic replication of signal-conditioning-plus-diagnostics bundling capabilities. Five-to-ten year viability hinges on foundry energy sourcing transparency alignment with EU Green Deal embodied carbon rules. Monitor MIIT dual carbon goal enforcement as inflection indicator for Chinese domestic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bipolar Wafer Capacity | Reduces exposure to Korean foundry concentration risk and export control escalations. |
| REACH-Compliant Packaging Redesign | Opens qualification windows for European machine tool and pharmaceutical equipment verticals. |
| TSN-Enabled Signal Conditioner Development | Captures automotive-tier supplier adoption rates running twice legacy factory automation benchmarks. |
| Predictive Maintenance Edge Migration | Aligns with vibration analysis algorithm decentralization in Japanese Chubu region robotics clusters. |
| Equipment-as-a-Service Component Lifespan Contracts | Matches German machine tool builder procurement specifications for hourly operating agreements. |
Research Methodology
Multiple input streams — primary interviews with semiconductor capital equipment procurement directors, industrial motor drive design engineers, and foundry account managers; secondary validation through SEC 10-K filings, ECHA substance restriction databases, and MIIT policy circulars; plus customs trade data on analog IC import flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, technology node, application complexity, and end-user industry concentration dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value build-ups cross-checked against macro industrial production indices. Forecast inputs incorporated foundry capacity utilization rates and REACH-mandated redesign cycle frequencies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical friction in Taiwan Strait logistics and EU Green Deal embodied carbon enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market