
 Asia Pacific Logic IC Market | 2026-2036
Asia Pacific Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Logic IC Market Insights
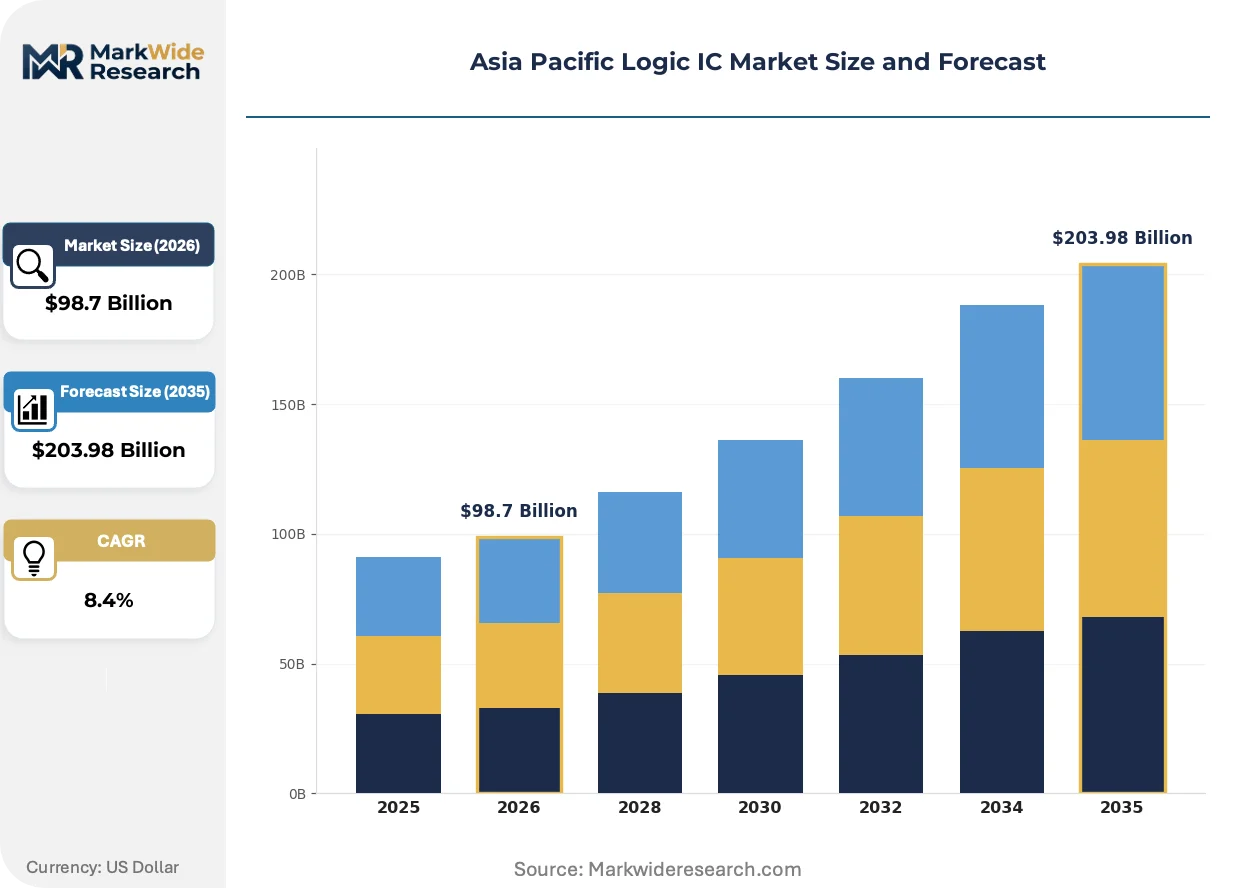
Asset-light fabless licensing models paired with government-backed foundry subsidies is reconfiguring which competitors can sustain leading-edge participation in the Asia Pacific Logic IC Market. TSMC leverages its pure-play foundry scale to anchor advanced node production for fabless designers across the region. Samsung Electronics sustains integrated device manufacturing across memory and logic, competing on captive supply chain control. Qualcomm Incorporated differentiates through modem-to-processor architectural specialization for 5G and automotive sockets.
Asia Pacific Logic ICs comprise integrated circuits performing Boolean operations, signal processing, and data conversion functions, fabricated through photolithography on silicon wafers with feature sizes now reaching sub-3 nanometer nodes for high-performance computing applications. Digital ICs occupy the dominant value position within the product type architecture, while Mixed-Signal ICs capture expanding margin pools as automotive and industrial systems require tighter analog-digital integration. CMOS technology leads the technology segmentation on cost-efficiency and scalability, though SiGe and GaAs variants carve defensible positions in radio-frequency and millimeter-wave telecommunications modules.
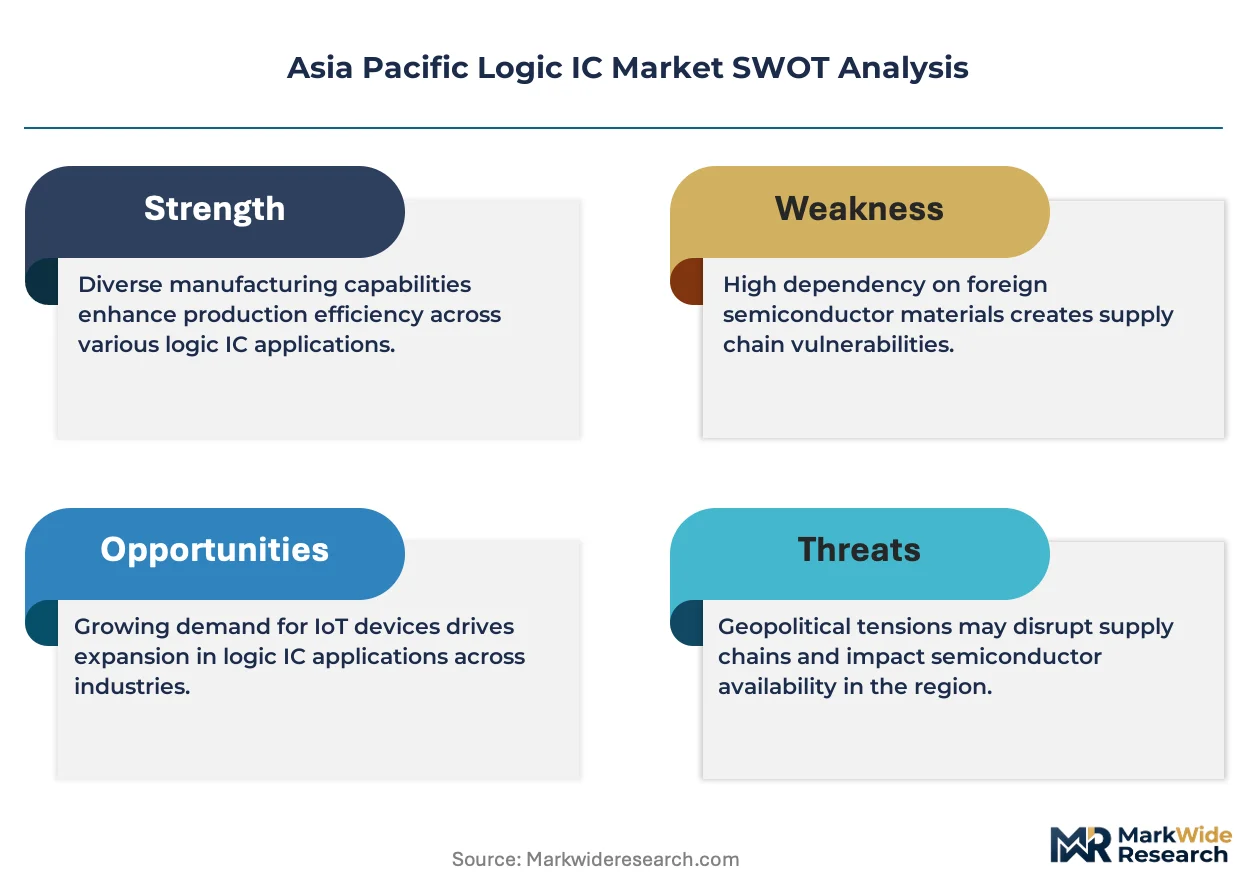
China's MIIT sets domestic semiconductor self-sufficiency targets through GB standards and dual carbon mandates, while Japan's METI channels subsidies toward reshoring advanced logic capacity under revised semiconductor strategy frameworks. South Korea's K-Semiconductor Belt policy coordinates tax incentives and infrastructure for logic foundry clusters around Pyeongtaek and Yongin. Stakeholders must weigh geopolitical export control alignment against localized supply chain incentives when siting new fabrication investments across the region.
Market Dynamics
Foundry capacity concentration in Taiwan and South Korea is forcing fabless designers across Asia Pacific to restructure supply commitments around geopolitical risk buffers and dual-sourcing mandates.
Growth Catalysts
- 5G Base Station Deployment:China's MIIT spectrum allocation mandates are accelerating demand for millimeter-wave RF logic ICs in telecommunications infrastructure across coastal provinces.
- Japan's METI Semiconductor Subsidies:Reshoring incentives under revised strategy frameworks are redirecting capital toward advanced node fabrication facilities in Kyushu and Tohoku.
- South Korea K-Semiconductor Belt:Tax coordination and infrastructure clustering around Pyeongtaek is expanding pure-play foundry output for regional fabless customers.
Market Restraints
- Extreme Ultraviolet Lithography Equipment Concentration:Dutch equipment supplier dependency creates chokepoint vulnerability for sub-5 nanometer node transitions.
- Silicon Wafer Input Volatility:300mm polished wafer pricing fluctuations from Japanese suppliers compress margin predictability for logic fabricators.
- Export Control Alignment Friction:US semiconductor licensing restrictions on China-bound advanced chips fragment design-tool ecosystem compatibility.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and testing are attracting packaging investments in Gujarat and Tamil Nadu.
- Automotive Zonal Architecture Convergence:Domain controller integration of powertrain and ADAS functions is opening socket opportunities for mixed-signal logic suppliers.
- Vietnam Industrial Zone Expansion:Northern province infrastructure development is positioning the country for back-end testing and packaging capacity absorption.
Industry Challenges
- Process Engineer Talent Scarcity:Sub-3 nanometer node expertise concentration in Taiwan and South Korea limits workforce mobility for new fabrication entrants.
- Multi-Die Packaging Integration Complexity:Chiplets and 3D stacking architectures require EDA tool recalibration and thermal management redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Logic IC Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear ICs, Digital ICs, Radio-Frequency ICs, Mixed-Signal ICs End User: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment Technology: CMOS, BiCMOS, SiGe, GaAs Application: Signal Processing, Data Conversion, Power Management, Embedded Systems |
| Companies Covered | Renesas Electronics Corporation, Samsung Electronics, STMicroelectronics NV, Sony Semiconductor, TSMC, Intel Corporation, Toshiba Electronic Devices and Storage Corporation, Qualcomm Incorporated, Texas Instruments Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Logic IC Market Trends and Innovations
Logic IC architecture is pivoting from monolithic scaling toward heterogeneous integration, with packaging technology and design-tool abstraction layers becoming primary competitive differentiators.
Gate-All-Around transistor architecture is hybridizing planar and FinFET design paradigms to extend CMOS scaling beyond physical limits. Samsung Foundry and TSMC are transitioning 3 nanometer production to nanosheet structures for high-performance computing customers. This hybridization is compressing power-performance-area tradeoffs that previously required process node jumps.
China's MIIT dual carbon mandates are imposing energy-intensity caps on semiconductor fabrication facilities operating above specified consumption thresholds. Japanese and South Korean suppliers serving China-based customers must document renewable energy sourcing for GB standard compliance. Memory-logic integrated device manufacturers are most affected, with METI-coordinated facilities securing preferential grid access.
Automotive OEMs are consolidating microcontroller procurement around functional safety-certified suppliers with ISO 26262 ASIL-D documentation. Tier-1 suppliers in Japan and South Korea are displacing multi-vendor strategies with strategic partnership models involving joint roadmap planning. This consolidation is most visible in electric vehicle powertrain controller sourcing from Chinese and South Korean battery-integrated platform manufacturers.
Asia Pacific Logic IC Market Segmentation
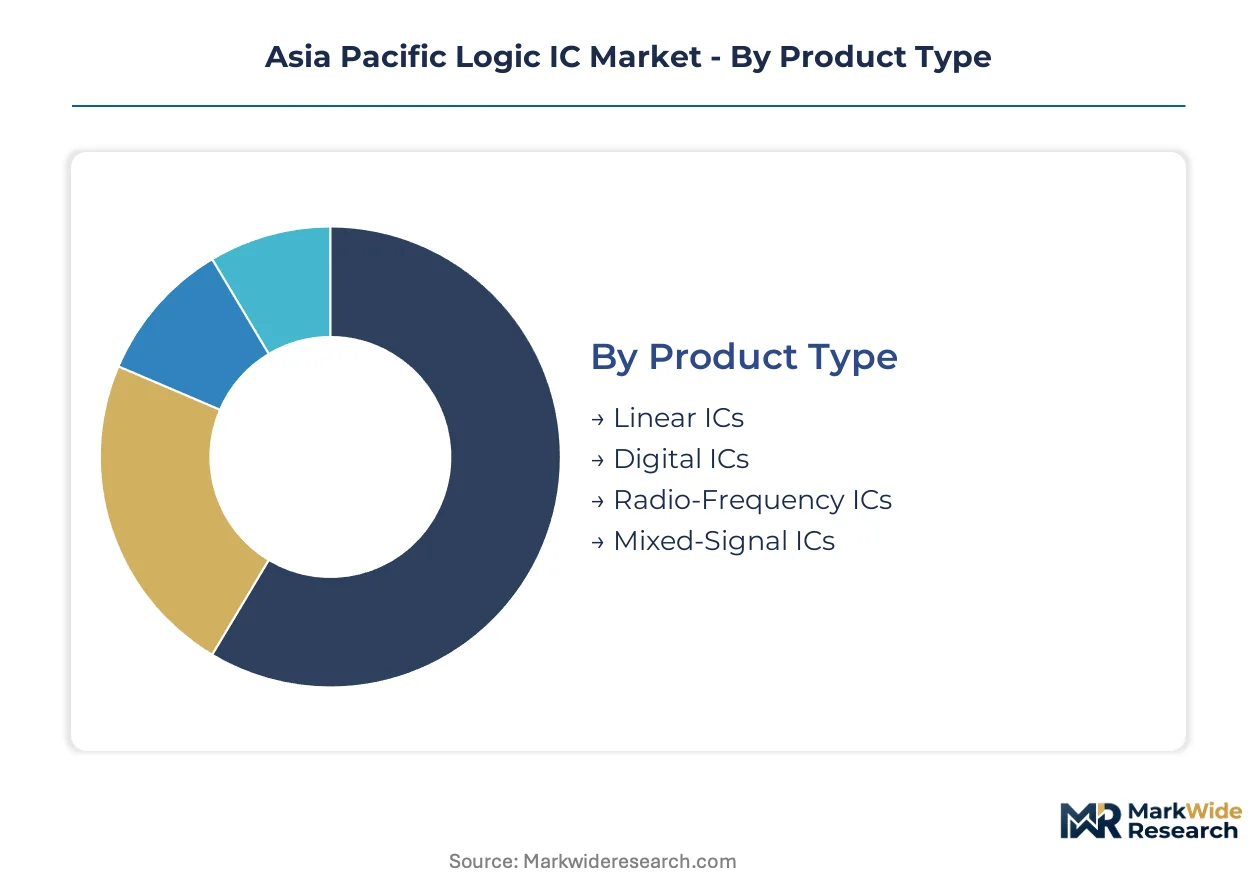
Logic IC segmentation in Asia Pacific reflects divergent technical requirements across telecommunications infrastructure, automotive electrification, and industrial automation. Foundry process specialization and end-use certification standards create distinct margin architectures within each category.
Product Type:
After-sales service intensity varies sharply across product categories, with automotive-grade mixed-signal ICs demanding traceability documentation and field failure analysis that commodity digital ICs rarely require.
- Digital ICs:Boolean logic gates, flip-flops, and multiplexers fabricated at sub-5 nanometer nodes for high-performance computing. Demand concentrates in 5G base station ASICs across China's coastal provinces, driven by MIIT spectrum allocation mandates and domestic cloud infrastructure buildouts.
- Mixed-Signal ICs:Integrated analog-digital converters and sensor interfaces combining precision voltage references with digital signal processing. Automotive zonal architecture adoption in Japan and South Korea is accelerating socket demand for ISO 26262-certified powertrain controllers.
- Linear ICs:Operational amplifiers and voltage regulators serving precision instrumentation requirements.
- Radio-Frequency ICs:Millimeter-wave transceivers and phased-array beamformers for telecommunications infrastructure.
Digital ICs hold the largest share; momentum sits with Mixed-Signal ICs as automotive electrification accelerates across the region.
End User:
Cost tier stratification separates military-specification automotive procurement from high-volume consumer electronics tenders, with telecommunications infrastructure occupying a mid-tier pricing band.
- Telecommunications:Baseband processors, RF front-end modules, and optical transceivers for 5G NR and fiber backhaul networks. China's MIIT infrastructure mandates and South Korea's K-Semiconductor Belt foundry expansion are concentrating demand in millimeter-wave logic for sub-6 GHz and mmWave deployments.
- Automotive:Functional safety-certified microcontrollers and power management ICs for electric vehicle powertrains and ADAS domain controllers. Tier-1 suppliers in Japan and South Korea are consolidating procurement around strategic partnership models with joint roadmap planning.
- Consumer Electronics:Application processors and display driver ICs for smartphones and wearable devices.
- Industrial Equipment:Programmable logic controllers and motor drive ICs for factory automation systems.
Telecommunications commands the largest share; automotive is climbing the fastest as electrification penetrates South Korean and Chinese OEM platforms.
Technology:
Volume concentration favors CMOS for mainstream logic, while compound semiconductor alternatives capture defensible positions where electron mobility requirements exceed silicon limitations.
- CMOS:Complementary metal-oxide-semiconductor logic fabricated through planar, FinFET, and emerging gate-all-around transistor architectures. TSMC and Samsung Foundry capacity expansion in Taiwan and South Korea is anchoring regional supply for fabless designers at 3 nanometer and below.
- SiGe:Silicon-germanium heterojunction bipolar transistors for millimeter-wave and high-speed analog applications. 5G base station deployment across China's eastern provinces is sustaining demand for cost-efficient RF integration below 100 GHz.
- BiCMOS:Bipolar-CMOS process combining high-speed analog with dense digital logic.
- GaAs:Gallium arsenide compound semiconductor for high-frequency power amplifiers and radar modules.
CMOS holds the largest share; SiGe is gaining share fastest as millimeter-wave telecommunications infrastructure expands.
Application:
Customer type differentiation separates military-aerospace procurement with traceability mandates from commercial embedded systems with cost-optimized specifications.
- Signal Processing:Digital signal processors and FPGA-based accelerators for real-time data manipulation. 5G telecommunications infrastructure across Japan, South Korea, and China is concentrating demand for baseband processing with low-latency determinism.
- Power Management:Voltage regulators, battery management ICs, and DC-DC converters for energy-efficient system operation. Electric vehicle platform consolidation by Chinese and South Korean battery-integrated manufacturers is driving ASIC development for 800V architectures.
- Data Conversion:Analog-to-digital and digital-to-analog converters for sensor interfaces.
- Embedded Systems:Microcontrollers and system-on-chip solutions for deterministic control applications.
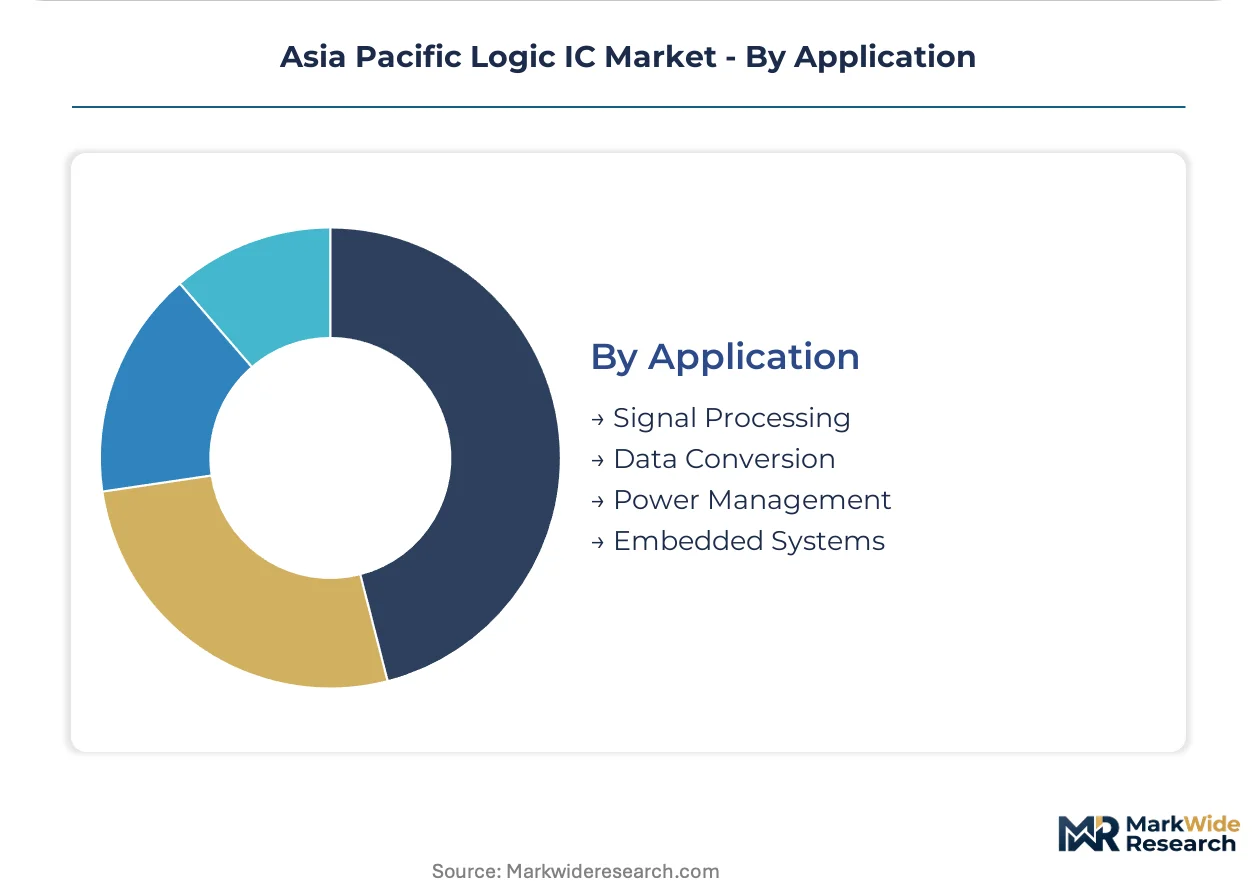
Signal Processing holds the largest share; Power Management shows the steepest expansion trajectory as automotive electrification scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwanese foundry clusters while Chinese domestic fabricators absorb margin compression from equipment access restrictions. This asymmetry redirects capital flows toward South Korean and Japanese capacity expansion as regional customers diversify supply commitments.
China
MIIT spectrum mandates for 5G base stations sustain demand for millimeter-wave RF logic ICs across coastal provinces. Dual carbon goals impose energy-intensity caps on fabrication facilities above specified consumption thresholds. Yangtze River Delta clusters around Shanghai and Suzhou host the densest concentration of domestic logic design houses serving telecommunications infrastructure.
Japan
Automotive zonal architecture adoption accelerates socket demand for ISO 26262-certified mixed-signal controllers. METI semiconductor subsidies under revised strategy frameworks redirect capital toward advanced node fabrication in Kyushu and Tohoku. Kumamoto and Miyagi prefectures are absorbing the majority of reshoring investments for 300mm logic wafer capacity.
South Korea
Electric vehicle platform consolidation by battery-integrated manufacturers drives ASIC development for 800V powertrain architectures. K-Semiconductor Belt policy coordinates tax incentives and infrastructure clustering around Pyeongtaek and Yongin. Samsung Foundry anchors advanced node production for regional fabless designers at 3 nanometer and below.
Taiwan
Pure-play foundry scale commands premium pricing for sub-5 nanometer production reserved for high-performance computing customers. TSMC capacity expansion in Hsinchu and Tainan Science Parks anchors regional supply for fabless designers. Southern Taiwan clusters are absorbing the majority of EUV lithography equipment deployments for gate-all-around transistor transitions.
India
Production-linked incentives for semiconductor assembly and testing attract packaging investments in Gujarat and Tamil Nadu. Central government PLI schemes for electronics manufacturing coordinate state-level infrastructure development. Dholera and Sriperumbudur industrial zones are positioning for back-end testing and packaging capacity absorption from regional logic fabricators.
Asia Pacific Logic IC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The market structures around a consolidated foundry layer with fragmented fabless design competition above it. IDMs compete on captive supply chain control while pure-play foundries scale process specialization. Strategic moves concentrate on dual-sourcing mandates and heterogeneous integration partnerships.
Among Asia-Pacific-based fabricators, TSMC, Samsung Electronics, and Renesas Electronics occupy distinct competitive positions. TSMC exemplifies the pure-play foundry archetype anchoring advanced node production for regional customers. Samsung Electronics represents integrated device manufacturing across memory and logic segments. Renesas Electronics sits within the automotive-certified microcontroller specialist tier serving electrification platforms.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Samsung Electronics |
| STMicroelectronics NV |
| Sony Semiconductor |
| TSMC |
| Intel Corporation |
| Toshiba Electronic Devices and Storage Corporation |
| Qualcomm Incorporated |
| Texas Instruments Incorporated |
| Others |
Pricing and Supply Chain Analysis
EUV lithography equipment concentration in Dutch suppliers determines both the premium commanded by sub-5 nanometer node production and the geographic clustering of advanced fabrication capacity across Taiwan and South Korea.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Asia Pacific Logic IC Market. Automotive-grade mixed-signal ICs with ISO 26262 ASIL-D certification capture premium spreads over commodity digital ICs serving consumer electronics. Cost compression in mature-node digital ICs is intensifying because Chinese domestic fabricators absorb margin pressure from equipment access restrictions. Consumer electronics OEMs exhibit the highest price sensitivity, while automotive Tier-1 suppliers prioritize supply assurance over unit cost.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries to Japanese silicon wafer suppliers illustrate supply-chain finance dependencies that propagate through regional procurement networks. Raw material flows draw from 300mm polished wafer suppliers in Japan, photoresist chemical providers in South Korea, and rare earth processing facilities in China. Single-source vulnerability concentrates in Dutch EUV lithography equipment for sub-3 nanometer transitions. Distribution runs through direct foundry relationships for high-volume fabless designers, with specialized distributors serving mid-tier industrial and automotive customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution threats from heterogeneous integration architectures that displace monolithic logic ICs with chiplet-based alternatives.
For Market Incumbents: Build process-technology moats through gate-all-around transistor transitions at 3 nanometer and below. Anchor capacity expansion in Taiwan and South Korea to maintain EUV equipment access. Defensive patent positioning around multi-die packaging thermal management limits chiplet-based substitute encroachment. For New Entrants and Emerging Players: Pursue automotive power management IC development for 800V electric vehicle platforms where certification barriers filter established competitors. Target India's Gujarat and Tamil Nadu packaging zones for back-end capacity absorption under PLI scheme incentives. Go-to-market through joint development agreements with Chinese battery-integrated platform manufacturers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automotive-certified mixed-signal specialists with ISO 26262 documentation. Long-term viability hinges on heterogeneous integration partnerships rather than monolithic scaling investments. Watch for inflection signals in chiplet standardization announcements from JEDEC and industry consortiums.| Strategic Initiative | Industry Significance |
|---|---|
| Gate-All-Around Process Transition | TSMC and Samsung Foundry anchor 3nm production for high-performance computing customers. |
| Automotive Functional Safety Certification | ISO 26262 ASIL-D documentation opens sockets in electric vehicle powertrain controllers. |
| Heterogeneous Integration Partnership | Multi-die packaging alliances displace monolithic scaling for cost-performance optimization. |
| India Back-End Capacity Investment | Gujarat and Tamil Nadu zones absorb packaging demand from regional logic fabricators. |
| Dual-Sourcing Supply Commitment | Fabless designers restructure procurement around geopolitical risk buffers and foundry diversification. |
Research Methodology
The analysis maps digital ICs, mixed-signal ICs, RF ICs, and linear ICs, each validated through semiconductor design executives, foundry operations managers, automotive Tier-1 procurement leads, and telecommunications infrastructure planners. Primary intelligence combines structured interviews with fabless design house CTOs, TSMC and Samsung Foundry account managers, and MIIT policy researchers. Secondary validation draws from SEMI equipment forecasts, MIIT spectrum allocation filings, METI subsidy disclosure documents, and customs trade data for 300mm wafer flows. Bottom-up die shipment estimates triangulate against top-down foundry revenue aggregation.
Forecasts assume stable EUV equipment access permissions, continued MIIT 5G infrastructure mandates, and METI subsidy disbursement timelines across the projection horizon. Segmentation dimensions include product type, end user, technology node, and application with regional regulatory cluster overlays. CAGRs derive from die shipment volume trajectories applied to blended average selling price evolution. Industry-specific inputs incorporate gate-all-around transistor yield ramp schedules and automotive zonal architecture penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic fabricators beyond equipment access constraints would shift outcomes. Macroeconomic deviation in semiconductor capital expenditure cycles, regulatory restriction tightening on China-bound advanced chips, or breakthroughs in chiplet thermal management would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market