
 3D Integrated Circuit Market | 2026-2036
3D Integrated Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
3D Integrated Circuit Market Outlook
Capital-intensity divergence between foundry-led and OSAT-led players is rotating competitive dynamics toward advanced packaging ecosystems. Taiwan Semiconductor Manufacturing Company leverages proprietary CoWoS capacity to anchor high-bandwidth memory integration. Samsung Electronics Co. Ltd. sustains vertical control from DRAM fabrication through advanced packaging. Intel Corporation differentiates with Foveros direct bonding for logic-on-logic stacking.
3D integrated circuits stack multiple silicon dies vertically using through-silicon vias, micro-bumps, or hybrid bonding to achieve interconnection densities exceeding 10,000 connections per square millimeter, primarily serving applications demanding extreme bandwidth and power efficiency. Memory Devices command the largest product-type volume as HBM3E stacks penetrate AI training clusters, while Processor Chips generate premium margins through logic-on-logy configurations. Through Silicon Via technology leads the process hierarchy, though Monolithic 3D IC approaches attract R&D investment for sub-3nm node extension.
US export controls through BIS and Taiwan's NSTC oversight shape foundry access for Chinese AI chip designers, while REACH and RoHS frameworks in Europe constrain material selections for micro-bump alloys and underfill compounds. Japan's METI subsidizes domestic advanced packaging lines through the Semiconductor Encouragement Act. Stakeholders must monitor how bilateral trade restrictions redirect supply chain investments across Korea's Yongin complex and Arizona's Phoenix semiconductor corridor.
Market Dynamics
CoWoS capacity scarcity at Taiwan Semiconductor Manufacturing Company is forcing AI chip designers into multi-year allocation contracts, fundamentally restructuring how advanced packaging capacity gets contracted and priced across the semiconductor value chain.
Growth Catalysts
- HBM3E penetration in AI training clusters:Memory Devices command volume leadership as through-silicon via stacking enables bandwidth densities required for large language model inference, pulling wafer-level packaging investment from data center operators.
- Japan's Semiconductor Encouragement Act:METI subsidies for domestic advanced packaging lines are attracting foreign capital into Kyushu and Tohoku regions, diversifying supply away from single-geography concentration.
- China's GB standards compliance mandate:NMPA and MIIT packaging regulations are accelerating domestic OSAT capability buildout for AI accelerators subject to US BIS export controls.
Market Restraints
- TSV thermal management complexity:Through Silicon Via architectures face heat dissipation limits below 7nm node stacking, constraining logic-on-logic configurations for high-performance computing.
- Hybrid bonding equipment oligopoly:Sub-10 micron pitch direct bonding tools concentrate among Dutch and Japanese suppliers, creating single-source vulnerability for advanced packaging lines.
- EU REACH substance restrictions:ECHA micro-bump alloy and underfill compound regulations are eliminating established tin-lead formulations, forcing qualification cycles for alternative metallurgies.
Strategic Opportunities
- India's PLI scheme for semiconductor packaging:Subsidized capital expenditure for OSAT facilities in Gujarat and Karnataka targets import substitution for domestic electronics manufacturing.
- Automotive sensor fusion integration:LiDAR and camera processor stacking via Foveros-style bonding is opening volume applications beyond data center AI accelerators.
- Monolithic 3D IC R&D convergence:Sequential processing and layer transfer techniques are attracting foundry investment for sub-3nm node extension without extreme ultraviolet lithography scaling.
Industry Challenges
- Packaging architect talent scarcity:Cross-functional expertise spanning thermal, electrical, and mechanical engineering for 3D integration concentrates among senior engineers at established foundries.
- Cleanroom capex intensity:Class 10 wafer-level packaging facilities require billion-dollar investments with five-year depreciation cycles, compressing returns for mid-cap OSATs.
- IP licensing fragmentation:Hybrid bonding patents distribute across research consortia, equipment vendors, and foundries, complicating freedom-to-operate analysis for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Integrated Circuit Market |
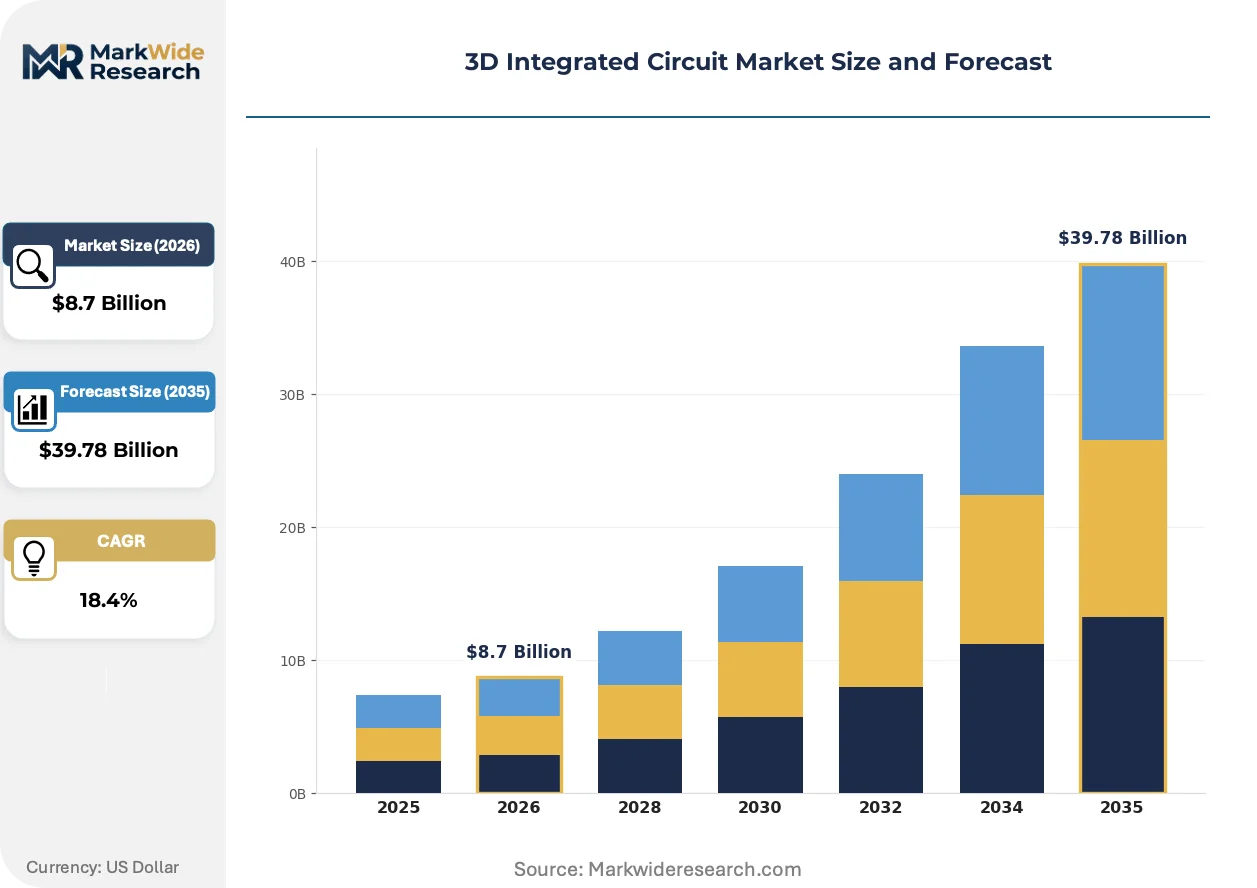
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Through Silicon Via, Wafer Bonding, Micro-bump, Interposer, Monolithic 3D IC, Packaging Product Type: Memory Devices, Processor Chips, Sensors, Logic Devices, Power Devices, RFID Tags Application: Consumer Electronics, Aerospace Systems, Telecommunications, Data Centers, Wearable Devices, Automotive OEMs End User: Fabless Semiconductor Companies, Foundries, Integrated Device Manufacturers, Electronic Manufacturing Services, Original Design Manufacturers |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Samsung Electronics Co. Ltd., Intel Corporation, ASE Technology Holding Co. Ltd., SK Hynix Inc., Micron Technology Inc., Amkor Technology Inc., Broadcom Inc., Advanced Micro Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Integrated Circuit Market Strategic Shifts
Chiplet-based disaggregation is rewriting interposer and substrate specifications, with foundries racing to standardize die-to-die interfaces while OSATs invest in panel-level fan-out capacity.
Hybrid bonding is decomposing the traditional micro-bump hierarchy for sub-10 micron pitch connections. AI accelerator designers at hyperscale data centers are adopting copper-to-copper direct bonding for HBM-to-logic stacking. This technology is decomposing the historical separation between front-end fabrication and back-end packaging, forcing foundries to absorb assembly functions previously outsourced to OSATs.
REACH substance restrictions are eliminating lead-based micro-bump alloys from European-bound electronics. ECHA's revised candidate list is accelerating tin-silver-copper formulation qualification at packaging houses serving automotive and industrial segments. Medical device manufacturers are responding with dedicated material traceability systems to satisfy MDR documentation requirements for implantable electronics.
Hyperscale procurement is consolidating around multi-year CoWoS capacity reservations. Cloud operators are bypassing traditional distributor channels to contract directly with Taiwan-based foundries for AI chip packaging. This pattern is most visible in the Phoenix semiconductor corridor, where Intel's advanced packaging investments are attracting co-location commitments from data center hardware designers seeking geographic supply diversification.
3D Integrated Circuit Market Segmentation
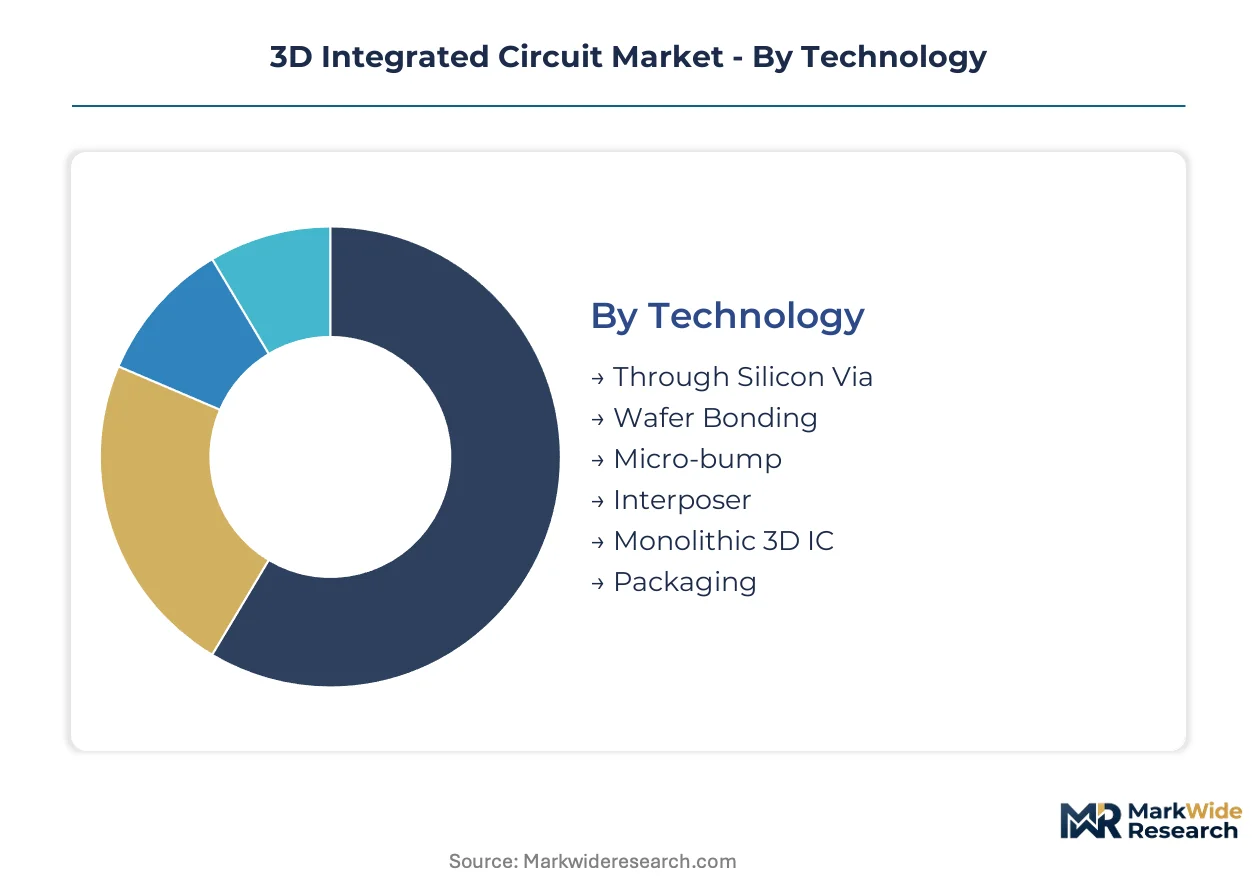
3D IC segmentation reveals how packaging complexity stratifies across customer types and applications. Channel configuration varies sharply between foundry-direct procurement for AI accelerators and OSAT-mediated flows for automotive and consumer volumes.
Technology:
Channel mix splits between foundry-captive capacity for advanced nodes and OSAT-accessible processes for mainstream applications.
- Through Silicon Via:Vertical interconnects drilled through silicon substrates enable die stacking with bandwidth densities exceeding 10,000 connections per square millimeter. Data center operators in Taiwan's Hsinchu cluster and Arizona's Phoenix corridor contract directly for TSV-based HBM integration.
- Wafer Bonding:Direct oxide or metal bonding creates permanent die-to-die attachment without intermediate interconnect layers. Sub-10 micron pitch copper-to-copper bonding is concentrating in Japan's Kyushu region where METI subsidies attract foreign packaging investment.
- Micro-bump:Solder-based interconnects at 20-50 micron pitch serve cost-sensitive applications.
- Interposer:Silicon or organic bridging substrates enable heterogeneous die integration.
- Monolithic 3D IC:Sequential layer processing promises sub-3nm extension without EUV scaling.
- Packaging:Traditional wire-bond and flip-chip encapsulation for legacy node products.
Through Silicon Via dominates installed base. Wafer Bonding is where expansion concentrates.
Product Type:
Cost tiering separates premium logic-on-logic stacks from commodity memory volumes and price-sensitive sensor packaging.
- Memory Devices:HBM3E stacks combine 8-12 DRAM dies using TSV interconnects for AI training bandwidth requirements. Hyperscale data center procurement is locking multi-year capacity allocations for high-bandwidth memory integration.
- Processor Chips:Logic-on-logic stacking via Foveros-style bonding generates premium margins for high-performance computing. Intel's Phoenix investments and TSMC's CoWoS lines compete for AI accelerator packaging contracts.
- Sensors:Image and environmental sensor stacking serves mobile and automotive volumes.
- Logic Devices:FPGA and ASIC integration for telecommunications infrastructure.
- Power Devices:Wide-bandgap semiconductor stacking for electric vehicle inverters.
- RFID Tags:Cost-minimized packaging for supply chain tracking applications.
Memory Devices command volume leadership. Processor Chips capture margin expansion.
Application:
Customer type determines procurement modality, with hyperscale operators bypassing distribution while automotive OEMs enforce multi-tier supplier qualification.
- Data Centers:AI training and inference clusters drive procurement of HBM-integrated accelerators. Cloud operators contract directly with Taiwan-based foundries, bypassing traditional semiconductor distribution channels for advanced packaging capacity.
- Automotive OEMs:Sensor fusion and autonomous driving compute demand Foveros-style logic stacking. LiDAR and camera processor integration is opening volume applications beyond data center AI accelerators.
- Consumer Electronics:Smartphone and tablet form factors constrain z-height budgets.
- Telecommunications:5G baseband and mmWave module integration.
- Aerospace Systems:Radiation-hardened packaging for satellite and defense applications.
- Wearable Devices:Ultra-thin stacking for health monitoring and augmented reality.
Data Centers anchor premium pricing. Automotive OEMs represent the fastest-growing trajectory.
End User:
Supply concentration varies between fabless designers dependent on foundry access and IDMs with captive packaging capability.
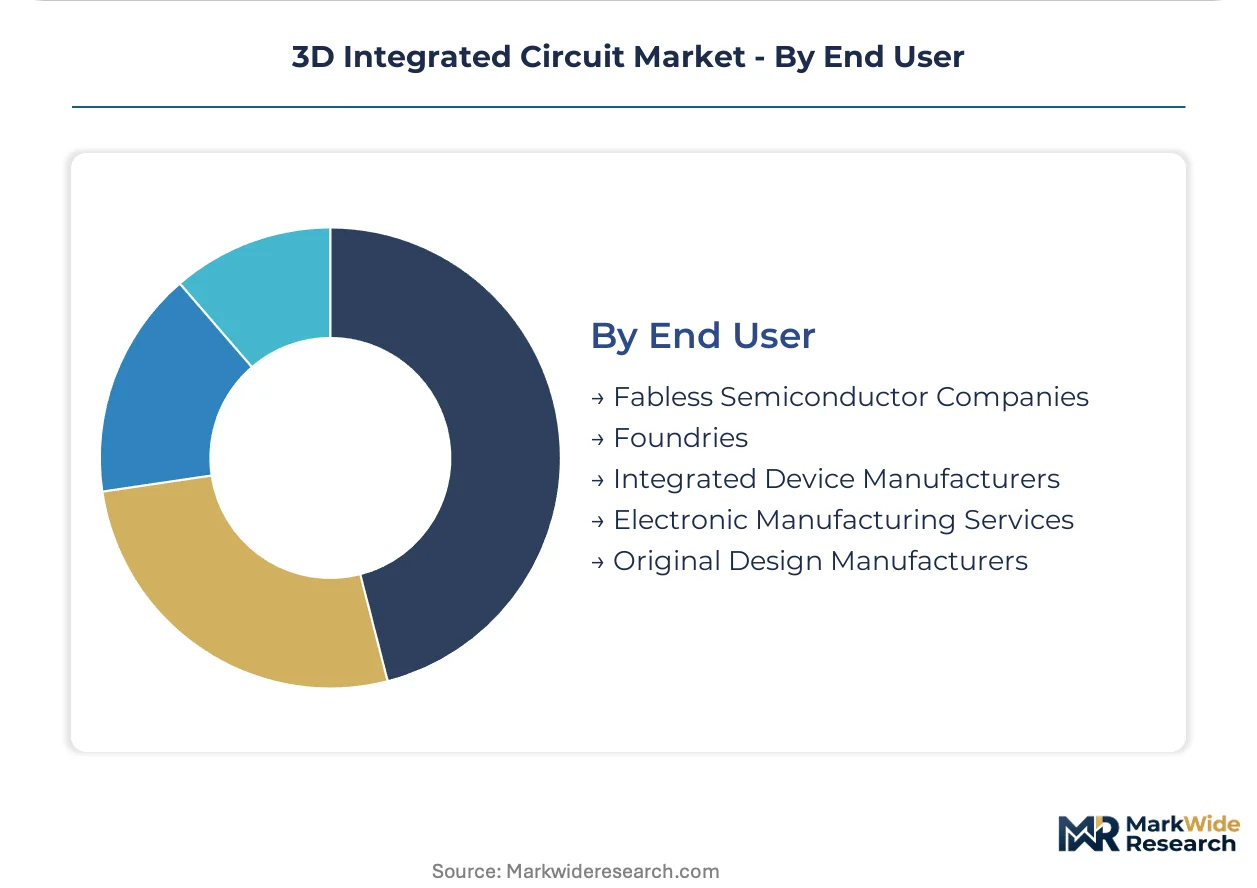
- Fabless Semiconductor Companies:Design-focused firms without fabrication assets rely on foundry CoWoS allocation and OSAT backup capacity. US BIS export controls and Taiwan NSTC oversight constrain foundry access for Chinese AI chip designers.
- Foundries:TSMC and Samsung absorb assembly functions previously outsourced to OSATs through hybrid bonding integration. Cleanroom capex intensity at billion-dollar scale compresses returns for mid-cap competitors.
- Integrated Device Manufacturers:Intel and Samsung maintain vertical control from fabrication through packaging.
- Electronic Manufacturing Services:Foxconn and Jabil mediate system-level integration.
- Original Design Manufacturers:Quanta and Wistron package for notebook and server brands.
Fabless Semiconductor Companies dominate design activity. Foundries capture value chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwan's Hsinchu cluster while the United States absorbs capacity premiums through direct foundry contracts. Geographic diversification investments in Japan and India are redistributing procurement leverage across the value chain.
United States
Hyperscale data center operators drive procurement of HBM-integrated AI accelerators through direct foundry negotiations. CHIPS Act subsidies channel investment toward Arizona's Phoenix semiconductor corridor. Intel's advanced packaging fabs in Chandler anchor domestic logic-on-logic stacking capability.
Taiwan
TSMC's CoWoS capacity scarcity forces multi-year allocation commitments from fabless AI chip designers. NSTC oversight shapes foundry access for Chinese semiconductor firms subject to BIS export controls. Hsinchu Science Park concentrates through-silicon via integration for high-bandwidth memory stacks.
Japan
METI's Semiconductor Encouragement Act attracts foreign capital into Kyushu and Tohoku advanced packaging lines. Domestic equipment vendors supply sub-10 micron pitch direct bonding tools for hybrid bonding expansion. Yokohama and Osaka house R&D consortia pursuing monolithic 3D IC sequential processing.
South Korea
Samsung maintains vertical control from DRAM fabrication through HBM3E packaging for AI training clusters. Yongin complex investments target captive supply of copper-to-copper bonding capacity. MFDS regulatory frameworks govern material traceability for automotive-qualified micro-bump alloys.
China
NMPA and MIIT packaging regulations accelerate domestic OSAT capability buildout for AI accelerators. GB standards compliance mandates reshape material selections for micro-bump metallurgies and underfill compounds. Shanghai and Beijing clusters concentrate fabless design activity seeking foundry alternatives.
3D Integrated Circuit Market Competitive Environment
Concentration sits with foundry-led players possessing captive advanced packaging capability. Taiwan Semiconductor Manufacturing Company and Samsung Electronics absorb assembly functions previously outsourced to OSATs through hybrid bonding integration. Three archetypes define competitive positioning: IDMs with vertical fabrication-to-packaging control, pure-play foundries expanding into wafer-level assembly, and OSATs defending mainstream micro-bump volumes. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with billion-dollar cleanroom investments compressing returns for mid-cap competitors.
Within the foundry-led tier, Taiwan Semiconductor Manufacturing Company anchors high-bandwidth memory integration through proprietary CoWoS capacity. Samsung Electronics exemplifies vertical control spanning DRAM fabrication through advanced packaging. Intel Corporation occupies a position in logic-on-logic stacking via Foveros direct bonding investments in Arizona. These three entities represent the concentration of pricing power and technology access across the 3D IC value chain.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Samsung Electronics Co. Ltd. |
| Intel Corporation |
| ASE Technology Holding Co. Ltd. |
| SK Hynix Inc. |
| Micron Technology Inc. |
| Amkor Technology Inc. |
| Broadcom Inc. |
| Advanced Micro Devices Inc. |
| Others |
Value Chain & Pricing Dynamics
Billion-dollar cleanroom depreciation cycles at Taiwan's Hsinchu cluster compress margin floors for mid-cap OSATs while concentrating pricing power among foundry-led players with captive hybrid bonding capacity. This scale asymmetry forces contract structures toward multi-year allocation commitments with embedded volume floors.
Pricing Analysis
The customization-premium spread separates configured-to-order CoWoS capacity reservations from standard micro-bump packaging tiers. Contract-based long-term offtake dominates AI accelerator procurement, with price differentiation resting on bandwidth density specifications and thermal certification grades. Cost compression in standard micro-bump tiers intensifies because OSATs compete for automotive sensor volumes. Fabless AI chip designers exhibit lowest price sensitivity, while consumer electronics OEMs enforce aggressive spot-market negotiations.
Supply Chain Analysis
Just-in-time wafer-level packaging prevails among hyperscale data center operators, while strategic stockpiling of hybrid bonding equipment concentrates among Japanese and Dutch vendors. Supply concentrates in Taiwan, South Korea, and the United States for advanced node packaging. Raw material dependencies span high-purity copper for TSV filling, specialized underfill compounds, and sub-10 micron pitch bonding tools. Single-source vulnerability for direct bonding equipment creates structural risk. Distribution runs through foundry-direct channels for AI accelerators and OSAT-mediated flows for automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale data center consolidation into six dominant cloud operators has inverted traditional semiconductor procurement leverage, forcing foundries into capacity reservation structures that favor buyer power concentration.
For Market Incumbents: Secure multi-year CoWoS allocation contracts with embedded price escalation clauses to defend against emerging panel-level fan-out competitors from Japan's Kyushu region. Deepen backward integration into hybrid bonding equipment servicing to reduce single-source dependency on Dutch and Japanese tool vendors. For New Entrants and Emerging Players: Anchor in India's Gujarat and Karnataka OSAT corridors where PLI-subsidized capital expenditure lowers entry barriers for automotive-qualified micro-bump capacity. Target sensor fusion packaging for LiDAR and camera processor integration as the most penetrable volume segment beyond data center AI accelerators. Pursue qualification partnerships with domestic Chinese fabless designers seeking foundry alternatives under BIS export controls. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment-light OSATs with established automotive certification and regional diversification into India's subsidized packaging corridors. Long-term viability rests on capturing share in monolithic 3D IC sequential processing as sub-3nm node extension displaces traditional TSV architectures. The signal to watch is METI subsidy renewal rates for Japan's advanced packaging buildout.| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Expansion | TSMC's proprietary line extensions lock in hyperscale AI accelerator contracts against Samsung's vertical DRAM-to-packaging control. |
| Hybrid Bonding Equipment Localization | METI-subsidized Kyushu facilities reduce single-source vulnerability to Dutch and Japanese tool vendors. |
| Automotive Certification Investment | MFDS-compliant micro-bump alloys open sensor fusion procurement from Korean and German OEMs. |
| Panel-Level Fan-Out Scale-Up | OSATs in Taiwan and China target cost-sensitive consumer electronics with substrate-free packaging formats. |
| Monolithic 3D IC R&D Partnership | Sequential processing consortia in Yokohama and Osaka pursue sub-3nm extension without EUV lithography scaling. |
Study Parameters
Operator-level perspectives from packaging process engineers, foundry capacity planners, OSAT procurement directors, and hyperscale data center hardware architects anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, BIS export control documentation, and METI subsidy announcements. Bottom-up wafer-volume modeling and top-down semiconductor equipment spending analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against CoWoS capacity expansion delays, hybrid bonding equipment delivery constraints, and BIS regulatory tightening scenarios. Segmentation dimensions modeled include technology node, product type, application vertical, end-user archetype, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycles, and technology transition curves. Industry-specific inputs encompassed TSV thermal dissipation limits, cleanroom depreciation schedules, and material qualification timelines under REACH frameworks.
Decision-makers should treat outputs as directional under assumptions of sustained AI training cluster investment and stable Taiwan Strait logistics; material deviation would warrant model refresh. Revision becomes warranted when hybrid bonding equipment lead times or BIS entity list expansions cross thresholds that restructure foundry access patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Digital IC Market