
 Automotive Heat Exchanger Market | 2026-2036
Automotive Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heat Exchanger Market Analysis
Software-defined thermal management is repositioning what automakers procure, shifting hardware sales toward subscription-capable climate systems. MAHLE GmbH leverages its R&D intensity in electrification-focused heat exchanger architectures. Denso Corporation anchors its position through manufacturing scale across Asian supply corridors. BorgWarner competes by extending its powertrain thermal expertise into battery and inverter cooling domains.
An automotive heat exchanger is a thermal transfer device, typically constructed from aluminum alloy tubes and fins brazed in controlled-atmosphere furnaces, engineered to regulate fluid temperatures across powertrain, battery, and cabin climate loops. Its primary commercial purpose is to protect propulsion components from thermal degradation while enabling cabin comfort with minimal energy penalty. Radiators remain the mature revenue base across internal combustion portfolios, though battery coolers for electric vehicles command premium margin pools as thermal density requirements intensify. Aluminum dominates material selection for weight-driven applications, while copper sustains niche positioning where corrosion resistance and thermal conductivity justify higher unit costs in heavy-duty commercial segments.
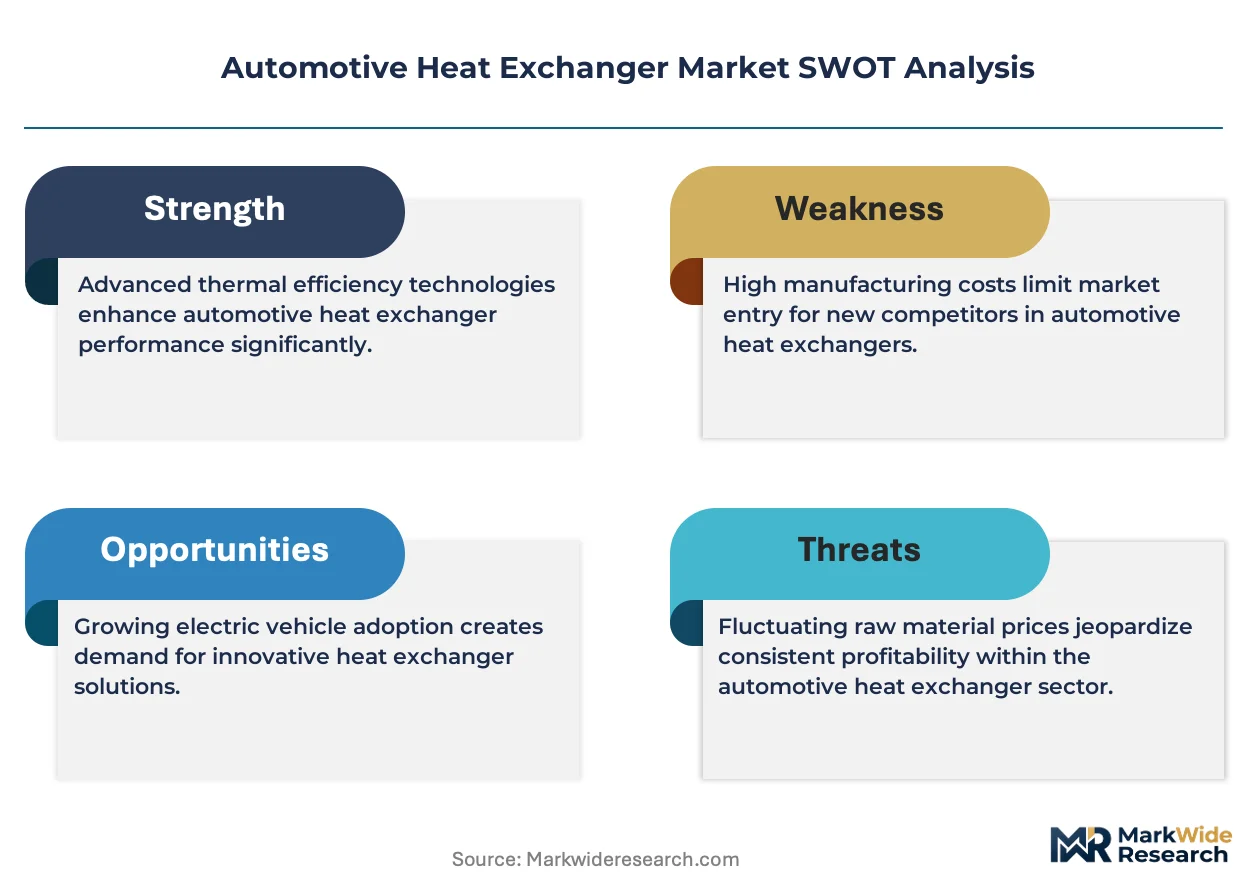
EPA fuel economy mandates, Euro 7 emission frameworks, and China's MIIT dual carbon goals are collectively tightening thermal efficiency thresholds and accelerating aluminum-intensive, lightweight heat exchanger specifications across export-bound production. NHTSA safety standards and ECE regulations further dictate crash-compatible packaging constraints that shape core and radiator dimensional standards. Stakeholders must monitor how battery-electric platform thermal architectures reshape supplier qualification criteria and capital allocation priorities.
Market Dynamics
Platform electrification is fragmenting thermal architectures into battery, inverter, and cabin subsystems that demand discrete cooling loops rather than unified powertrain radiators. This structural shift forces suppliers to requalify for electric-vehicle programs while defending internal-combustion revenue pools.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Mandates for fleet-wide thermal efficiency are accelerating aluminum-intensive, lightweight heat exchanger specifications across US-bound production lines.
- Battery thermal management systems:Electric vehicle OEMs are multiplying cooling loop counts per platform to protect lithium-ion cells from thermal runaway and extend cycle life.
- China's MIIT dual carbon goals:Domestic production quotas for new energy vehicles are concentrating demand for high-performance battery coolers in Shanghai and Shenzhen manufacturing corridors.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations compress margin stability for brazed heat exchanger manufacturers locked into annual automotive supply contracts.
- Supply concentration in Asian brazing sheet:Three Japanese and Chinese metallurgical suppliers control premium clad aluminum coil capacity, creating single-source vulnerability for European and North American fabricators.
- Copper substitution ceiling:Thermal conductivity advantages of copper fail to overcome density penalties above 150 kW cooling loads, limiting its addressable market to heavy-duty commercial segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Component-level incentives for advanced thermal systems are attracting heat exchanger assembly investments in Tamil Nadu and Gujarat export zones.
- Software-defined thermal management:Predictive cabin preconditioning and battery state-of-charge thermal optimization enable subscription revenue streams that hardware suppliers can capture through system integration partnerships.
- Heat pump integration with refrigerant loops:Convergence of R-1234yf cabin climate circuits with battery cooling is creating unified thermal module procurement specifications that favor full-system suppliers.
Industry Challenges
- Multi-physics simulation talent scarcity:Battery pack thermal runaway modeling and two-phase refrigerant dynamics expertise remains concentrated among Tier-1 engineering teams, constraining mid-tier supplier qualification.
- Euro 7 certification timelines:Pre-production validation cycles for emission-compliant thermal management systems now extend 18-24 months, compressing program launch windows.
- Legacy internal-combustion tooling strandedness:Radiator fin-and-tube production lines lack adaptability to micro-channel battery cooler geometries, forcing capital-intensive retooling decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heat Exchanger Market |
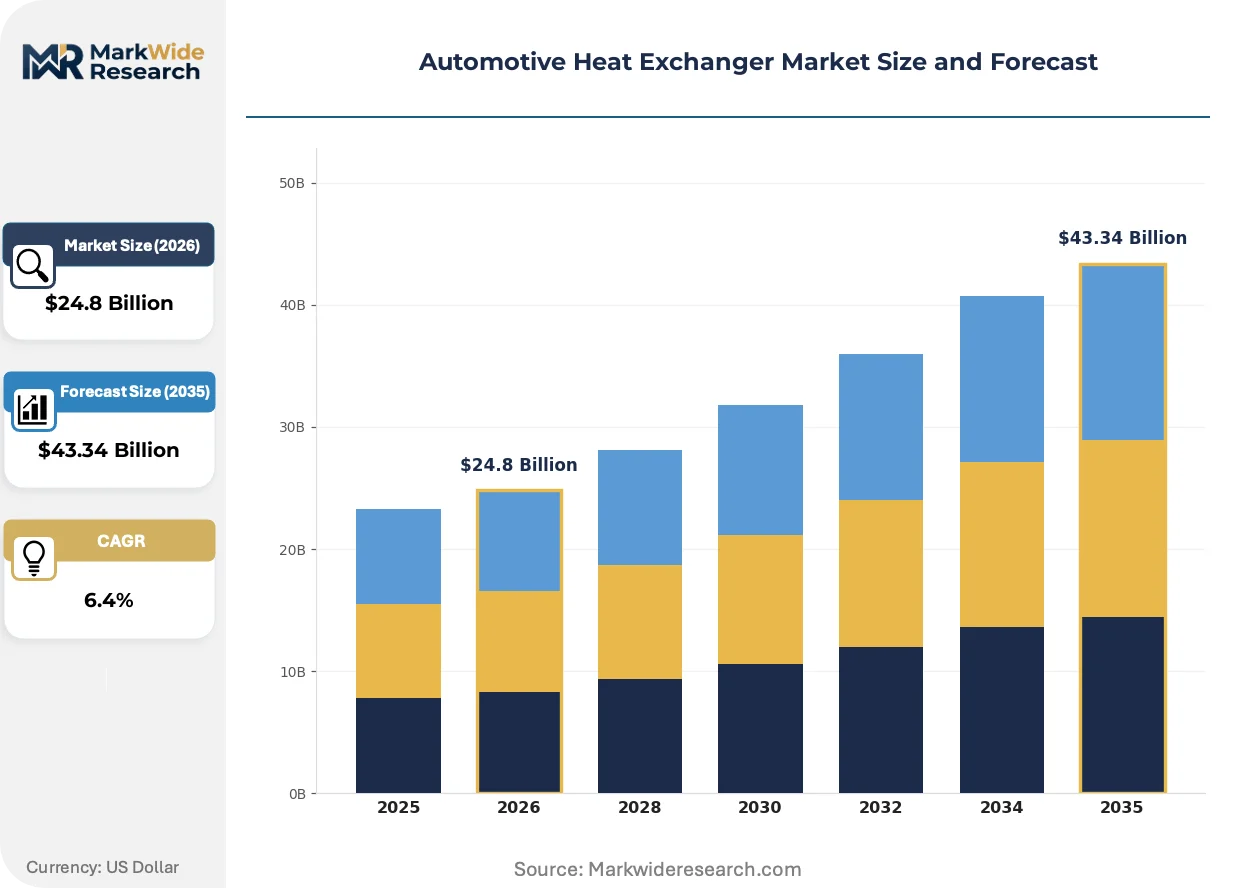
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Coolers, Radiators, Oil Coolers, Heater Cores Material: Aluminum, Copper, Steel, Composites Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Hanon Systems, Modine Manufacturing Company, MAHLE GmbH, BorgWarner, Dana Limited, Denso Corporation, T.RAD Co., Ltd., Keihin Corporation, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heat Exchanger Market Emerging Trajectories
Additive manufacturing of topology-optimized aluminum heat exchanger cores is collapsing tooling lead times from months to days. This capability is reshaping prototyping economics and enabling mass-customization of thermal architectures.
Micro-channel aluminum extrusions are decentralizing thermal management from centralized radiator-and-heater-core architectures toward distributed battery cell contact cooling plates. EV platform engineers are adopting these geometries to reduce refrigerant charge volumes while maintaining heat flux density. The technology is decentralizing supplier relationships from traditional radiator specialists toward aluminum extrusion houses with precision machining capabilities.
Euro 7 emission frameworks are mandating faster catalyst light-off through integrated exhaust gas heat recovery exchangers. Powertrain thermal engineers must now optimize across conflicting objectives of emissions reduction, fuel economy, and packaging density. Passenger car segments in Germany and France are responding with combined intercooler-EGR cooler modules that consolidate heat rejection surfaces.
Fleet operators and leasing companies are unbundling thermal system maintenance from vehicle acquisition, creating standalone service contracts for coolant loop refurbishment and heat exchanger replacement. This disintermediates OEM dealer networks in favor of independent thermal specialists with mobile brazing and refrigerant handling capabilities. The pattern is most visible in German commercial vehicle fleets where total-cost-of-ownership contracts now specify thermal system availability guarantees separate from powertrain warranties.
Automotive Heat Exchanger Market Segmentation
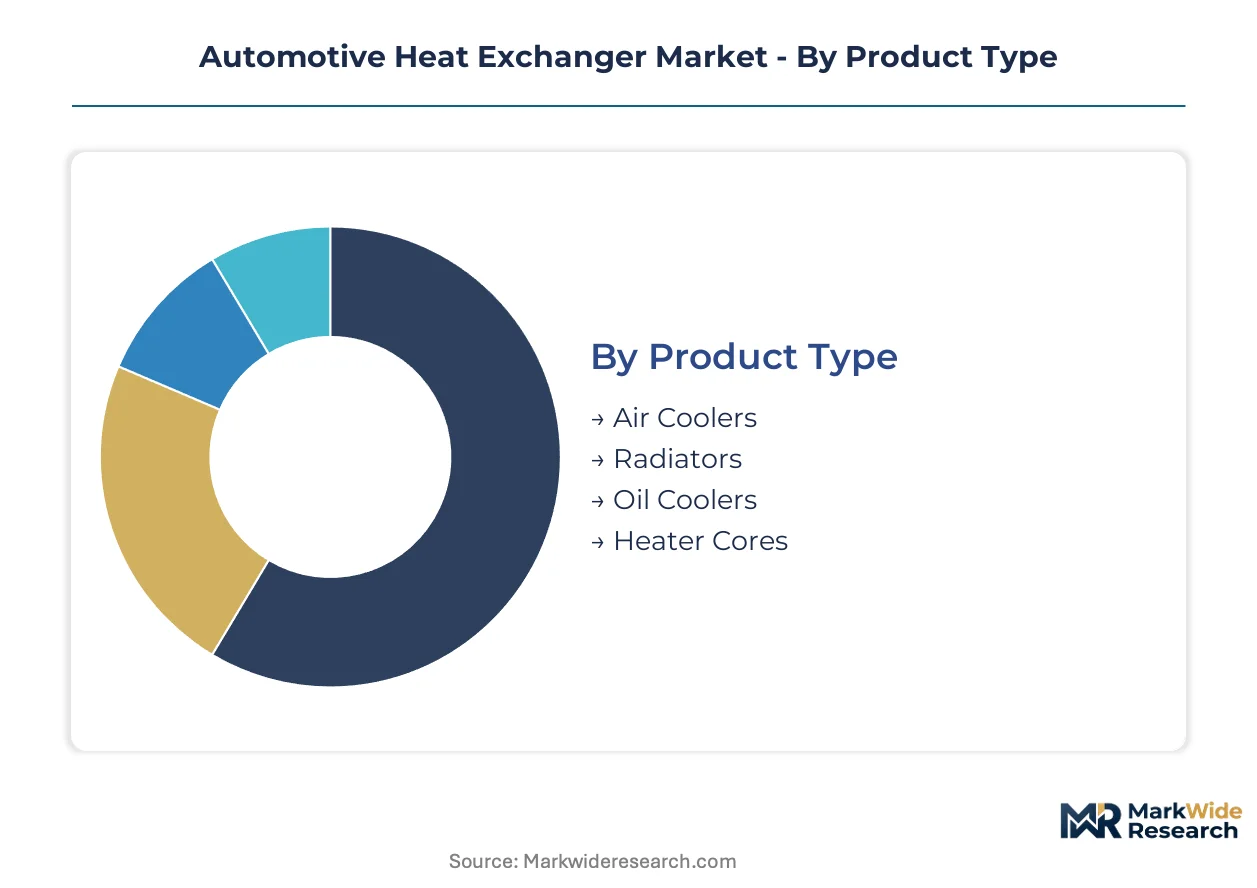
Automotive heat exchanger procurement patterns diverge sharply between legacy internal-combustion platforms and electrified architectures. Understanding where each segment sits within integrated thermal systems versus standalone modules determines supplier qualification pathways and margin capture potential.
Product Type:
Integration depth varies from embedded powertrain components to modular cabin climate units that automakers source separately.
- Radiators:Brazed aluminum tube-and-fin assemblies dominate thermal rejection for internal-combustion engines. Demand concentrates in US and German production corridors where EPA and Euro 7 standards mandate lightweight, high-efficiency specifications.
- Heater Cores:Compact aluminum heat exchangers transfer engine coolant thermal energy to cabin air streams. Chinese and Indian OEMs are multiplying specifications for these units as entry-level vehicle climate content expands.
- Oil Coolers:Plate-and-fin or shell-and-tube configurations protect transmission and engine lubricants from thermal breakdown. Commercial vehicle fleets in Germany specify these for extended drain intervals.
- Air Coolers:Charge air cooling modules reduce compressed intake temperatures in turbocharged powertrains. Integration with intercooler-EGR combined modules is displacing standalone procurement in Euro 7-compliant European platforms.
Volume placements concentrate in Radiators; the faster expansion belongs to Heater Cores.
Material:
Cost-to-performance tradeoffs and weight-driven fuel economy mandates determine material selection across vehicle classes.
- Aluminum:Clad brazing sheet and extruded micro-channel profiles deliver the strength-to-weight ratio that EPA Corporate Average Fuel Economy standards require. US and Chinese automakers have standardized on aluminum for passenger car thermal modules.
- Copper:Superior thermal conductivity sustains positioning in heavy-duty commercial segments where corrosion resistance outweighs density penalties. Mining and construction vehicle specifications in Australia and Canada retain copper-nickel alloy constructions.
- Steel:Lower material costs support economy vehicle applications in India and Southeast Asian markets where BIS standards permit higher mass thermal components.
- Composites:Polymer-aluminum hybrid constructions are penetrating prototype electric vehicle battery enclosures where electrical isolation and thermal conductivity must coexist.
Aluminum commands the dominant placement share; composites are climbing the fastest as battery thermal architectures mature.
Application:
Propulsion technology fragmentation is splitting thermal management into distinct cooling loop architectures with separate procurement specifications.
- Passenger Vehicles:High-volume production programs in China, Germany, and the United States drive radiator and cabin climate module standardization. MIIT dual carbon goals are accelerating aluminum-intensive specifications across domestic Chinese brands.
- Electric Vehicles:Battery coolers, inverter chill plates, and cabin heat pumps demand discrete thermal circuits with higher heat flux density requirements. Tesla, BYD, and Volkswagen Group platforms are multiplying heat exchanger counts per vehicle versus internal-combustion equivalents.
- Commercial Vehicles:Long-haul duty cycles and severe-service environments sustain demand for copper-brass constructions in North American and European heavy truck segments.
- Hybrid Vehicles:Dual thermal architectures combining engine cooling with battery thermal management create complex procurement specifications. Japanese OEMs pioneered these integrated systems; European and Chinese manufacturers are now adopting similar approaches.
Passenger vehicles anchor current volume; electric vehicle applications are expanding most quickly as OEM electrification timelines accelerate.
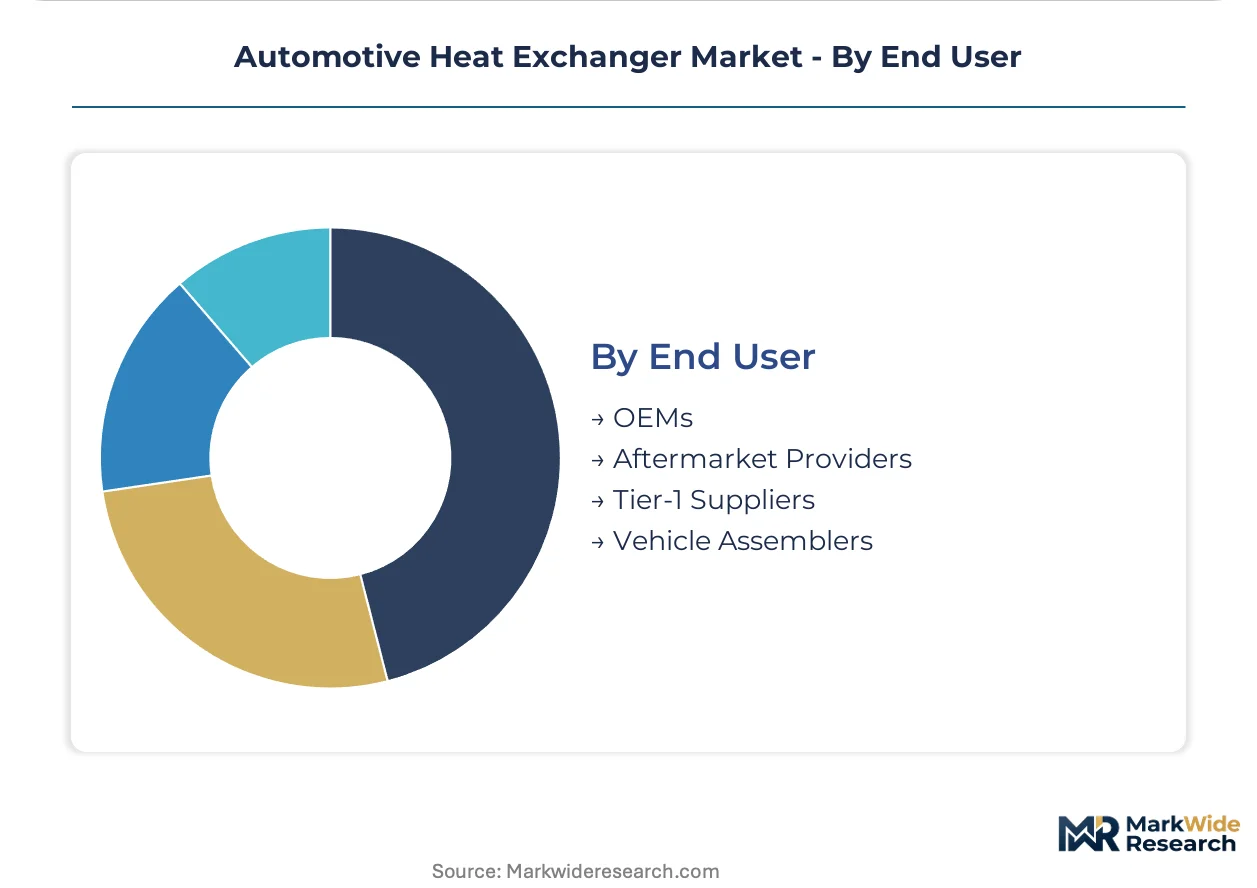
End User:
Supply chain position determines technical specification authority and contract structure across the value chain.
- OEMs:Volkswagen Group, Toyota, and General Motors retain direct thermal system architecture definition for flagship platforms. Their engineering centers in Wolfsburg, Toyota City, and Detroit issue performance specifications that Tier-1 suppliers must meet.
- Tier-1 Suppliers:Denso, MAHLE, and BorgWarner aggregate heat exchanger procurement into integrated thermal module assemblies. These suppliers qualify sub-tier aluminum brazing houses and manage refrigerant loop integration.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities in China and India receive thermal modules as pre-assembled kits. Their procurement authority is limited to fit-and-function verification.
- Aftermarket Providers:Independent distributors and service chains supply replacement radiators and heater cores. German commercial vehicle fleets are unbundling thermal maintenance into standalone service contracts, expanding this channel's relevance.
Tier-1 suppliers concentrate the largest placement volumes; aftermarket providers are gaining share fastest as fleet operators separate thermal system maintenance from powertrain warranties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors heat exchanger procurement intensity as Chinese OEMs electrify platforms at scale. The city's Pudong and Jiading manufacturing corridors concentrate battery cooler assembly for domestic EV brands. This geographic pattern shapes supplier qualification timelines across the forecast window.
China
Domestic EV production quotas from MIIT accelerate aluminum-intensive thermal module specifications. Shanghai and Shenzhen assembly plants multiply cooling loop counts per battery platform. Yangtze River Delta fabricators retool radiator lines for micro-channel battery plate geometries.
Germany
Wolfsburg and Stuttgart engineering centers define integrated thermal architectures for Euro 7 compliance. KBA certification timelines extend pre-production validation cycles for exhaust gas heat recovery exchangers. Bavarian suppliers consolidate intercooler-EGR modules to meet emission thresholds.
United States
Detroit thermal engineering teams specify lightweight aluminum radiators for EPA Corporate Average Fuel Economy compliance. Michigan and Ohio assembly corridors source brazed cores for full-size truck platforms. NHTSA crash-compatible packaging constraints shape radiator dimensional standards.
Japan
Toyota City and Nagoya engineering centers pioneered hybrid thermal architectures combining engine and battery cooling. METI efficiency standards sustain demand for compact heater core specifications. Kansai-region fabricators supply integrated modules to domestic OEM electrification programs.
India
Tamil Nadu and Gujarat export zones attract heat exchanger assembly investments under the PLI scheme for automotive components. BIS standards permit steel constructions in economy vehicle segments. Chennai suppliers qualify for European and North American thermal module procurement.
Automotive Heat Exchanger Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent thermal system procurement models. The vendor base clusters around three strategic archetypes: integrated module suppliers, aluminum brazing specialists, and refrigerant loop integrators. Tier-1 aggregators capture volume through manufacturing scale while mid-tier fabricators defend position in niche geometries. Dominant competitive moves include capacity expansion in Asian supply corridors and technology licensing for micro-channel extrusion capabilities.
Among German-based engineering-intensive suppliers, MAHLE GmbH exemplifies the integrated module archetype through its R&D positioning in electrification-focused architectures. Denso Corporation anchors the scale-driven tier with manufacturing presence across Asian supply corridors. BorgWarner occupies a position bridging powertrain thermal expertise into battery and inverter cooling domains. These three entities represent distinct competitive vectors: engineering intensity, manufacturing scale, and powertrain-to-electrification transition capability.
| Leading Market Players |
|---|
| Hanon Systems |
| Modine Manufacturing Company |
| MAHLE GmbH |
| BorgWarner |
| Dana Limited |
| Denso Corporation |
| T.RAD Co., Ltd. |
| Keihin Corporation |
| Valeo |
| Others |
Supply Flow & Price Mechanics
LME aluminum spot prices cascade through brazed heat exchanger manufacturing into three-tier pricing structure across premium, standard, and economy levels. Annual automotive supply contracts lock fabricators into fixed conversion fees while raw material volatility concentrates margin pressure on mid-tier suppliers without backward integration into clad coil production.
Pricing Analysis
Margin tightening in standard-grade radiator assemblies reflects LME aluminum volatility and locked annual contracts. Contract-based long-term offtake dominates OEM procurement, with price differentiation driven by volume scale and EPA/Euro 7 certification tier. Cost-down pressure on economy-tier aftermarket units accelerates as Indian and Chinese fabricators expand export capacity. Fleet operators show least price sensitivity for thermal system availability guarantees, while independent distributors face greatest margin compression.
Supply Chain Analysis
Refurbishment flows for commercial vehicle heat exchangers are creating secondary material loops that compete with virgin aluminum supply. Premium clad aluminum brazing sheet concentrates in Japan and China, with German and North American fabricators drawing from these metallurgical suppliers. The supply chain rests on micro-channel extrusion capabilities and controlled-atmosphere brazing furnaces. Single-source vulnerability in Asian brazing sheet creates structural risk. Distribution runs through Tier-1 integrated module suppliers who aggregate sub-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive heat exchanger manufacturing is becoming a vertical-integration race as suppliers pursue captive control over aluminum brazing sheet to escape margin compression from raw material volatility.
For Market Incumbents: Deploy in-house production of clad aluminum coil to reduce exposure to Japanese and Chinese metallurgical supplier concentration. Denso, MAHLE, and BorgWarner should accelerate micro-channel extrusion capability acquisition before mid-tier competitors qualify for EV platform programs. Battery cooler procurement specifications from Tesla and BYD threaten to displace traditional radiator specialists without refrigerant loop integration expertise. For New Entrants and Emerging Players: India's PLI scheme for automotive components opens a window for Tamil Nadu and Gujarat-based fabricators to capture export-bound thermal module assembly. Target battery plate geometries for EV platforms where incumbent radiator tooling lacks adaptability. Partner with European Tier-1 suppliers seeking alternative brazing sheet sources to bypass Asian supply concentration. For Investors and Strategic Acquirers: The window for entry favors aluminum extrusion houses with precision machining capabilities that can pivot into battery cell contact cooling plates. Mid-tier suppliers with stranded internal-combustion tooling face viability compression. Monitor Euro 7 certification timeline extensions as inflection indicator for supplier qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Brazing Sheet | Captive clad coil production insulates margin from LME volatility and Asian supplier concentration. |
| Micro-Channel Extrusion Capability Acquisition | Precision machining expertise qualifies suppliers for EV battery plate geometries displacing legacy radiator architectures. |
| Refrigerant Loop System Integration | Unified thermal module procurement specifications from Volkswagen and BYD favor full-system over component suppliers. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Gujarat assembly investments under India's PLI scheme capture export-bound OEM qualification. |
| Software-Defined Thermal Management Partnership | Predictive cabin preconditioning subscriptions enable recurring revenue capture beyond hardware margins. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and aluminum brazing house operations managers combined with secondary validation from EPA fuel economy filings, Euro 7 pre-certification documentation, and MIIT new energy vehicle production databases. Bottom-up vehicle production forecasts and top-down thermal content per vehicle estimates were triangulated to establish market sizing.
Segment-level volume and value outputs were reconciled across propulsion architecture, vehicle class, and regional production cluster dimensions. CAGRs were derived from installed base growth and content-per-vehicle expansion across battery, inverter, and cabin cooling loops. Forecast inputs incorporated OEM electrification timelines, Euro 7 implementation schedules, and aluminum intensity specifications from EPA Corporate Average Fuel Economy compliance pathways.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook. Forecasts reflect documented assumptions about EV platform thermal architecture standardization and brazing sheet supply concentration. Practitioners should monitor LME aluminum price volatility and Euro 7 certification timeline extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Armrest Market