
 Automotive Rocker Arm Market | 2026-2036
Automotive Rocker Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rocker Arm Market Analysis
Original equipment supply chains is reconfiguring as Tier 1 valvetrain suppliers consolidate logistics around powertrain electrification. Schaeffler Technologies AG leverages its European manufacturing footprint to sustain roller rocker arm output for hybrid architectures. Eaton Corporation anchors North American distribution through its long-standing OEM relationships. Delphi Technologies competes on electromechanical integration expertise as combustion engines demand smarter valve control systems.
An automotive rocker arm is a reciprocating lever that transfers camshaft motion to open engine valves, typically forged from steel or aluminum alloys with surface hardness between 58 and 64 HRC to withstand cyclic loading exceeding 10^8 cycles. Its primary purpose is to convert rotational cam lobe displacement into linear valve actuation with minimal frictional loss and precise timing accuracy. Roller rocker arms command the dominant share of OEM value pools due to reduced friction coefficients and extended service intervals, while steel materials retain cost advantages in high-volume passenger car programs. Aftermarket channels for adjustable rocker arms exhibit faster growth velocity as performance enthusiasts and fleet operators pursue custom valvetrain tuning outside factory specifications.
NHTSA fuel economy standards and EPA emission regulations in the United States enforce stricter engine efficiency benchmarks that elevate precision requirements for valvetrain components. The EU Green Deal and Euro 7 standards from EMA compel European manufacturers to reduce combustion losses through optimized valve timing hardware. Stakeholders must monitor how hybrid engine architectures split procurement volumes between traditional rocker arms and camless electromechanical alternatives.
Market Dynamics
Powertrain electrification is fragmenting valvetrain procurement volumes between traditional combustion hardware and camless electromechanical alternatives, forcing suppliers to hedge manufacturing capacity across dual technology tracks.
Growth Catalysts
- EPA Tier 3 Standards:Tightening NOx and particulate limits compel OEMs to optimize valve timing precision, expanding specification-grade roller rocker arm procurement for light-duty commercial fleets.
- Hybrid Architecture Proliferation:Atkinson-cycle engines in Toyota and Honda hybrid systems sustain demand for low-friction roller designs with hardened steel contact surfaces.
- Querétaro Manufacturing Cluster:Mexico's automotive corridor near Silao concentrates engine component stamping and heat-treatment capacity, reducing logistics costs for North American OEM valvetrain programs.
Market Restraints
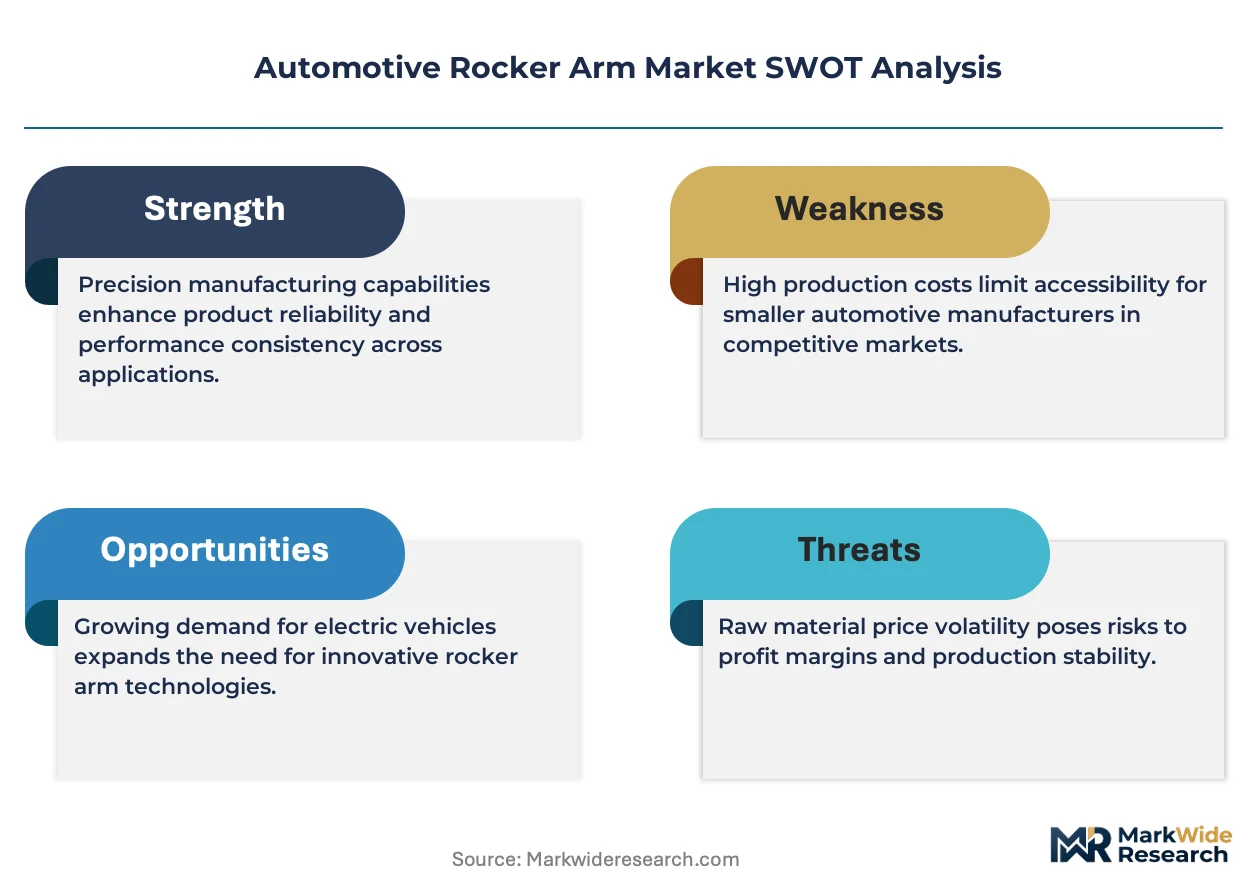
- Aluminum Alloy Price Volatility:Primary aluminum ingot fluctuations compress margin stability for forged rocker arm producers serving high-volume passenger car segments.
- Camless Valve Actuation Substitution:Electromechanical and hydraulic valve control systems eliminate mechanical rocker arms entirely in next-generation combustion architectures.
- REACH Chemical Compliance:European surface treatment chemistries face substitution pressure from ECHA authorization lists, disrupting established heat-treatment and coating process lines.
Strategic Opportunities
- Aftermarket Adjustable Rocker Arms:Performance enthusiasts and fleet operators in the United States pursue custom valvetrain tuning outside factory specifications, creating premium pricing power outside OEM channels.
- Electromechanical Integration:Convergence of precision machining with sensor-enabled smart rocker arms opens software-defined valve control revenue streams.
- EU Green Deal Manufacturing Incentives:Carbon-border adjustment mechanisms reward low-emission forging operations with preferential procurement status from European OEM sustainability scorecards.
Industry Challenges
- CNC Grinding Talent Scarcity:Precision cam profile grinding requires specialized machinist skills that retire faster than vocational programs replenish across Midwestern US manufacturing zones.
- Dual-Platform Capex Burden:Suppliers must simultaneously fund roller rocker arm capacity and electromechanical valve actuation R&D without volume certainty on either technology trajectory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rocker Arm Market |
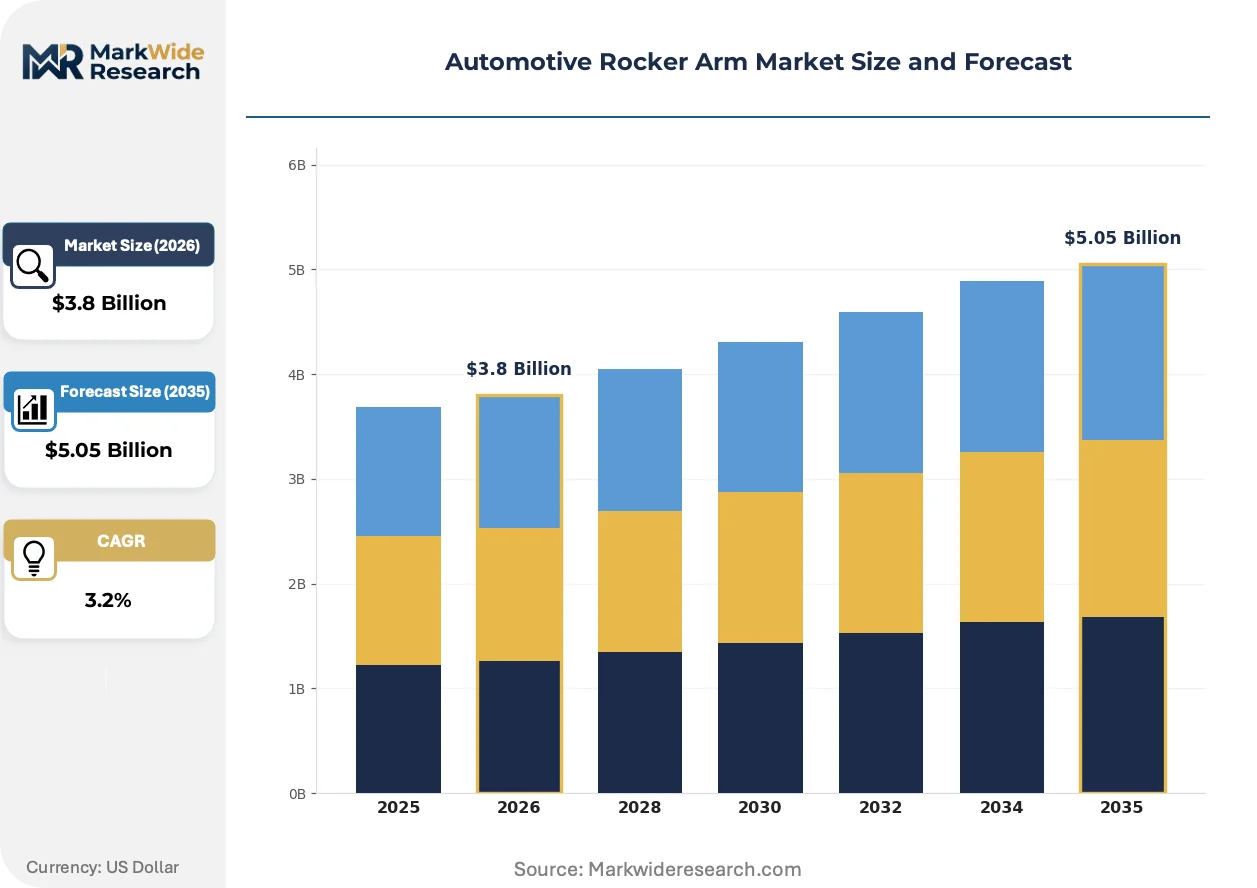
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Rocker Arms, Flat Rocker Arms, Adjustable Rocker Arms, Non-Adjustable Rocker Arms Material: Aluminum, Steel, Titanium, Composite End User: OEMs, Aftermarket, Racing Teams, Fleet Operators Engine Type: Gasoline, Diesel, Hybrid, Electric |
| Companies Covered | Edelbrock LLC, Delphi Technologies, COMP Cams, Eaton Corporation, BorgWarner Inc., Crower Cams & Equipment Company, Mahle GmbH, Federal-Mogul LLC, Schaeffler Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rocker Arm Market Emerging Trajectories
Additive manufacturing is penetrating rocker arm prototyping workflows, compressing tool-up timelines for custom valvetrain geometries while traditional forging retains cost dominance at production scale.
Diamond-like carbon coatings are collapsing friction coefficients between roller rocker arm contact surfaces and camshaft lobes. High-performance engine builders in Germany and Japan specify DLC-treated steel rollers for endurance racing applications. The technology is collapsing service interval differentiation between OEM and aftermarket valvetrain components.
EMA Euro 7 standards from the European Commission mandate real-world emission performance validation that extends beyond laboratory test cycles. Engine hardware suppliers face expanded durability testing requirements for valve train components under transient load conditions. European OEMs are responding with hardened steel rocker arm specifications that exceed prior surface hardness baselines.
Fleet procurement departments are consolidating valvetrain component sourcing through long-term service agreements rather than transactional part purchases. Independent distributors in North America lose volume to captive OEM parts networks. This consolidation pattern concentrates most visibly in Class 3-6 commercial vehicle segments where total cost of ownership calculations dominate specification decisions.
Automotive Rocker Arm Market Segmentation
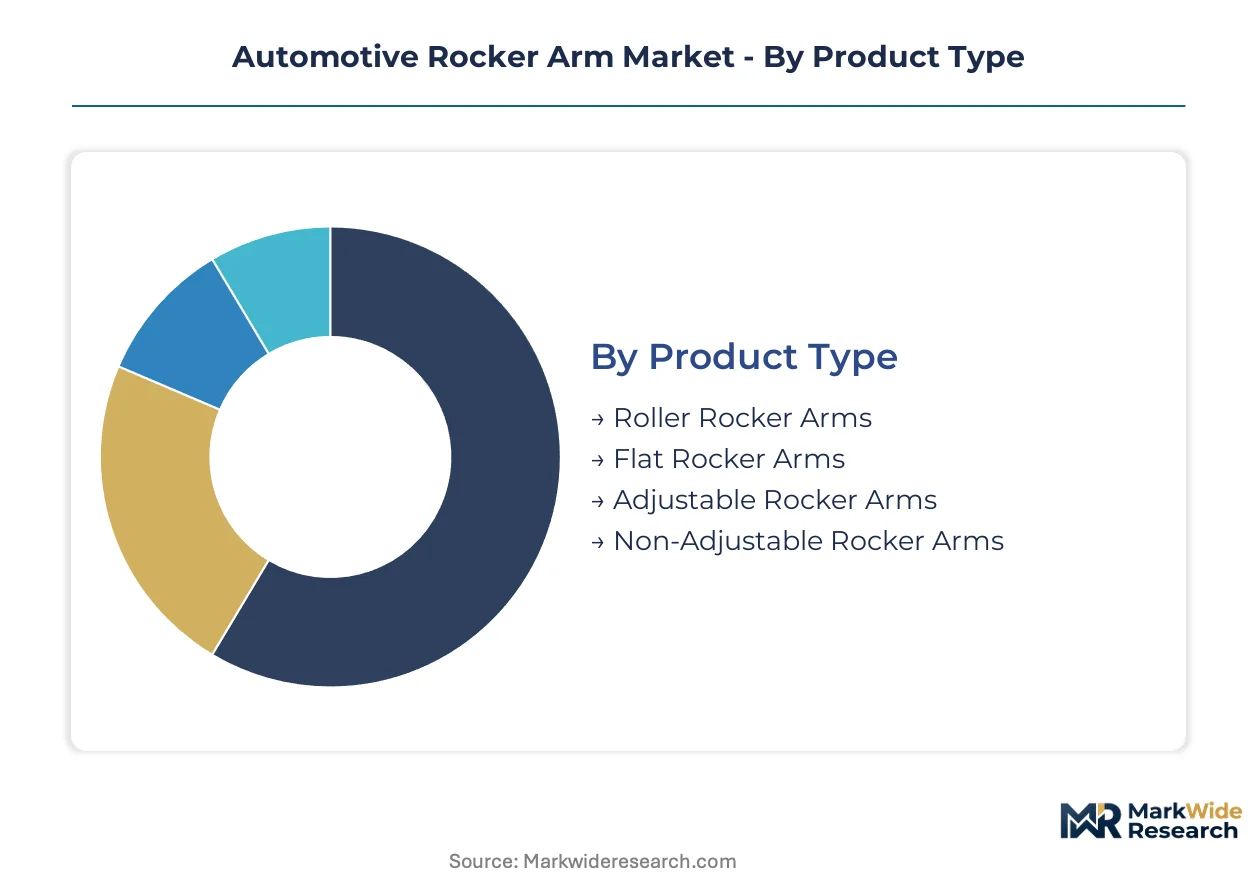
Segmentation in the automotive rocker arm market reveals how procurement patterns split across friction-reduction technologies, material cost tiers, and powertrain electrification trajectories. Understanding these divisions exposes where specification-grade premiums concentrate and where commodity substitution threatens margin stability.
Product Type:
Cost tier differentiation separates precision roller designs from stamped flat configurations, with adjustability commanding aftermarket premiums.
- Roller Rocker Arms:Hardened steel rollers with needle bearing assemblies reduce friction coefficients versus sliding contact designs. Toyota and Honda specify these for Atkinson-cycle hybrid engines produced in Japan and the United States, where EPA Tier 3 efficiency mandates elevate low-friction requirements.
- Adjustable Rocker Arms:Threaded pivot mechanisms enable valve lash tuning outside factory specifications. Performance enthusiasts and fleet operators in the United States drive procurement through specialty distributors, creating pricing power detached from OEM volume contracts.
- Flat Rocker Arms:Stamped steel or forged aluminum sliding-contact designs serve cost-sensitive high-volume passenger car programs.
- Non-Adjustable Rocker Arms:Fixed-geometry stamped components dominate emerging market production where service interval extension receives lower priority.
Roller configurations command the established OEM base. The steepest expansion runs through adjustable designs in aftermarket channels.
Material:
Application severity dictates material selection, with thermal loading and cyclic stress amplitude determining whether aluminum, steel, or exotic alloys justify their cost positions.
- Steel:Forged chrome-moly or carbon steel with induction-hardened contact surfaces withstands contact stresses exceeding 1500 MPa in commercial diesel valvetrains. Ford and Stellantis specify steel roller rockers for Super Duty and Ram heavy-duty programs manufactured in Mexico's Querétaro corridor.
- Aluminum:Gravity-cast or forged 7075-T6 alloys reduce reciprocating mass in high-RPM gasoline engines. German and Japanese sports car manufacturers specify aluminum for turbocharged four-cylinder architectures where valvetrain inertia limits maximum engine speed.
- Titanium:Ti-6Al-4V forgings serve Formula 1 and top-tier endurance racing where mass reduction justifies material costs exceeding steel by 15x.
- Composite:Carbon fiber-reinforced polymer prototypes target camless electromechanical actuation mounts in next-generation hybrid prototypes.
Steel retains the volume base across commercial and passenger applications. Aluminum gains share fastest in downsized turbocharged gasoline architectures.
End User:
Customer type determines whether procurement flows through captive OEM supply chains, fragmented aftermarket distribution, or concentrated fleet purchasing.
- OEMs:Tier 1 suppliers like Schaeffler and Eaton manage just-in-sequence delivery to engine plants, with contracts spanning 5-7 year model cycles and penalty clauses for PPM defects.
- Aftermarket:Independent distributors and e-commerce platforms serve repair shops and performance builders, with adjustable rocker arms carrying 40-60% gross margins versus OEM contract pricing.
- Racing Teams:NASCAR, Formula 1, and World Endurance Championship operations demand lot-traceable components with batch-specific metallurgical certification.
- Fleet Operators:Class 3-6 commercial vehicle fleets in the United States consolidate valvetrain sourcing through long-term service agreements with OEM parts networks, squeezing independent distributor volume.
OEM channels anchor procurement volume. Aftermarket adjustable products expand most quickly as tuning culture penetrates mainstream enthusiast segments.
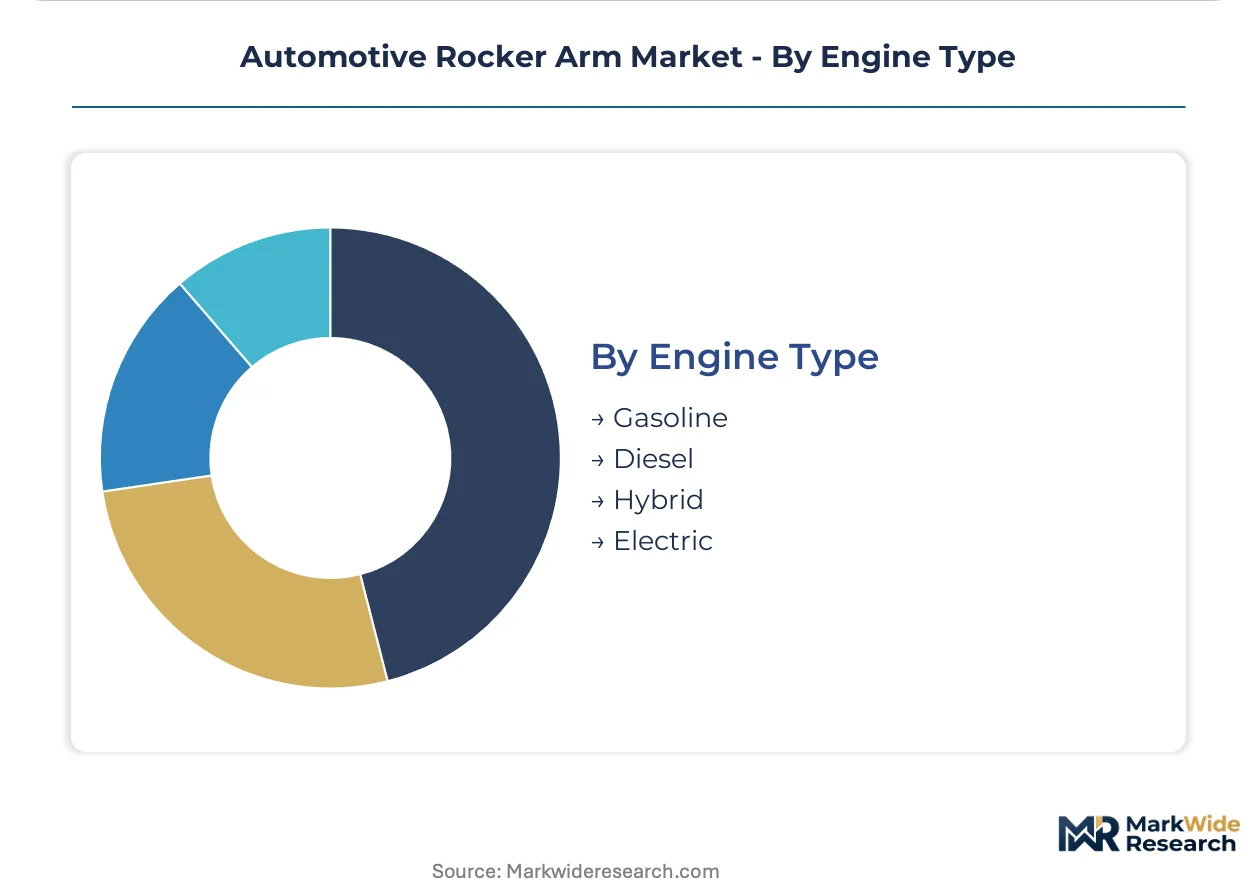
Engine Type:
Powertrain electrification fragments demand across combustion architectures with diverging valvetrain complexity requirements.
- Hybrid:Atkinson-cycle gasoline engines in Toyota Hybrid Synergy Drive and Honda i-MMD systems sustain roller rocker arm demand with unique duration and lift profiles optimized for thermal efficiency over peak power.
- Gasoline:Direct-injection turbocharged engines with variable valve timing require precision-ground rocker arms with sub-10 micron tolerances to maintain cam phaser synchronization.
- Diesel:Compression-ignition engines with exhaust gas recirculation and selective catalytic reduction impose soot-contaminated oil conditions that accelerate steel contact surface wear.
- Electric:Battery-electric powertrains eliminate mechanical valvetrains entirely, representing demand destruction for traditional rocker arm categories.
Gasoline applications hold the incumbent position. Hybrid architectures climb the fastest as electrification penetration sustains combustion component demand through transitional decades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 standards anchor North American demand for precision valvetrain components, while European regulators accelerate Euro 7 compliance timelines. Manufacturing clusters concentrate near engine assembly plants to minimize logistics friction.
United States
Light-duty commercial vehicle production drives specification-grade roller rocker arm procurement from Ford and Stellantis. NHTSA fuel economy standards enforce stricter engine efficiency benchmarks. Midwestern manufacturing zones around Detroit and Toledo concentrate CNC grinding capacity for hardened steel components.
Germany
Premium sports car manufacturers specify aluminum rocker arms for turbocharged four-cylinder architectures. EU Green Deal carbon-border adjustment mechanisms reward low-emission forging operations. Baden-Württemberg suppliers cluster around Stuttgart engine plants serving Porsche and Mercedes-Benz hybrid programs.
China
Domestic OEMs expand hybrid engine production for BYD and Geely electrification platforms. MIIT emission standards tighten tolerances for gasoline direct-injection valvetrains. Yangtze River Delta forging operations near Shanghai supply precision-machined components for regional engine assembly.
Japan
Atkinson-cycle hybrid systems from Toyota and Honda sustain demand for low-friction roller designs. METI energy efficiency regulations prioritize thermal optimization over peak power output. Aichi Prefecture suppliers cluster around Toyota City engine plants with just-in-sequence delivery contracts.
Mexico
Nearshoring trends concentrate North American valvetrain procurement in the Bajío manufacturing corridor. EPA Tier 3 compliance requirements apply to vehicles assembled for US export markets. Querétaro and Silao host heat-treatment and stamping capacity serving Ford Super Duty and Ram heavy-duty programs.
Automotive Rocker Arm Market Vendor Landscape
Integrated powertrain specialists and precision forging houses split the market based on electrification hedging strategies. The supplier base exhibits moderate consolidation around Tier 1 valvetrain incumbents with captive OEM relationships. Two archetypes dominate: European engineering conglomerates with hybrid-architecture portfolios, and North American metal-forming specialists with high-volume passenger car contracts. Competitive moves center on dual-platform capacity funding and electromechanical valve actuation R&D partnerships.
Within the integrated powertrain tier, Schaeffler Technologies AG and Eaton Corporation exemplify divergent geographic anchoring strategies. Delphi Technologies occupies a position bridging mechanical precision with sensor-enabled smart component development. Mahle GmbH represents the forging-centric archetype with European manufacturing footprint concentration. These three entities illustrate how supplier positioning fragments across hybrid combustion sustainment versus camless electromechanical transition bets.
| Leading Market Players |
|---|
| Edelbrock LLC |
| Delphi Technologies |
| COMP Cams |
| Eaton Corporation |
| BorgWarner Inc. |
| Crower Cams & Equipment Company |
| Mahle GmbH |
| Federal-Mogul LLC |
| Schaeffler Technologies AG |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European forging operations for hardened steel valvetrain components is compressing supplier margins while elevating contract pricing power for Tier 1 suppliers with captive heat-treatment capacity. This utilization squeeze forces procurement departments to accept longer lead times or premium pricing for EPA Tier 3-compliant roller rocker arm specifications.
Pricing Analysis
North American OEM contract pricing for steel roller rocker arms runs 15-25% above comparable Mexican-produced components due to labor and energy cost differentials. Three-tier pricing structure across premium DLC-coated, standard induction-hardened, and economy stamped steel levels separates fleet procurement from performance aftermarket channels. Cost compression in aluminum forged rockers is intensifying because primary ingot volatility transfers directly to Tier 2 suppliers. Fleet operators in Class 3-6 commercial segments exhibit highest price sensitivity, while racing teams demonstrate lowest sensitivity due to lot-traceability requirements.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts established sourcing patterns for precision-ground cam contact surfaces and needle bearing assemblies. Manufacturing gravity centers on Germany, Mexico, and Japan, with forging operations drawing from chrome-moly steel billets, aluminum 7075-T6 ingots, and DLC coating chemistries. Single-source vulnerability concentrates in European surface treatment lines facing REACH substitution mandates. Distribution runs through just-in-sequence Tier 1 supplier networks to engine assembly plants, with aftermarket channels fragmenting across independent distributors and OEM captive parts networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camless electromechanical valve actuation threatens demand destruction for mechanical rocker arm incumbents, forcing suppliers to defend combustion-architecture revenue while hedging electrification transition exposure.
For Market Incumbents: Entrench roller rocker arm capacity in Mexico's Querétaro corridor to exploit nearshoring logistics advantages and EPA Tier 3 compliance proximity. Deepen backward integration into induction hardening and DLC coating processes to capture margin currently leaked to European surface treatment specialists. Lock long-term offtake agreements with Ford and Stellantis heavy-duty programs before hybrid architecture fragmentation accelerates. For New Entrants and Emerging Players: Establish a beachhead in aftermarket adjustable rocker arms for performance enthusiasts, where 40-60% gross margins detach from OEM volume contract discipline. Target United States specialty distributors serving fleet operators pursuing custom valvetrain tuning outside factory specifications. Lead with electromechanical integration expertise for sensor-enabled smart rocker arms in hybrid Atkinson-cycle applications. For Investors and Strategic Acquirers: Long-term, this sits as a transition-arbitrage play because combustion valvetrain demand persists through hybrid proliferation even as pure electric architectures eliminate mechanical components entirely. Acquisition targets should display dual-platform R&D capability spanning roller rocker arm precision forging and camless actuation electromechanical development. Monitor Toyota and Honda hybrid production ramp rates as the critical inflection signal for sustained roller rocker arm demand versus accelerated electromechanical substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Platform Capacity Funding | Simultaneous roller rocker arm and electromechanical R&D hedges against technology trajectory uncertainty. |
| Backward Integration into Heat Treatment | In-house induction hardening captures margin from European coating specialists facing REACH compliance pressure. |
| Aftermarket Distribution Partnership | Specialty distributor alliances unlock premium pricing for adjustable rocker arms outside OEM channel discipline. |
| Smart Component Development | Sensor-enabled rocker arms open software-defined valve control revenue streams in hybrid architectures. |
| Mexican Manufacturing Footprint Expansion | Querétaro corridor proximity reduces logistics friction for EPA Tier 3-compliant North American supply. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and OEM technical specification sheets preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and heat-treatment operations specialists. Primary fieldwork captured contract structure, pricing dynamics, and capacity utilization signals across the United States, Germany, Mexico, and Japan. Secondary validation drew from SEC filings of listed automotive suppliers, EPA and NHTSA regulatory dockets, and EMA Euro 7 implementation guidance. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Assumptions around hybrid engine architecture penetration, EPA Tier 3 implementation timelines, and aluminum alloy price trajectories were held fixed across baseline scenarios while electromechanical valve actuation adoption rates and REACH chemical substitution timelines were stress-tested. Segmentation modeling incorporated vehicle class, propulsion architecture, material grade tier, and end-user channel. CAGRs were derived from production volume forecasts mapped to content-per-vehicle assumptions for roller versus flat rocker arm specifications. Forecast inputs included OEM platform life cycles, fleet replacement rates, and aftermarket tuning culture penetration indices.
Stress conditions across aluminum price volatility, camless actuation technology readiness, and Euro 7 durability testing requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hybrid combustion sustainment through the projection horizon. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Global Automotive Cross Car Beam Market