
 Global Automotive Center Stacks Market | 2026-2036
Global Automotive Center Stacks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Center Stacks Market Analysis
The divergence between premium and commodity center stack tiers is hardening around display resolution, haptic feedback density, and integrated domain controller architecture. Preh GmbH leverages its vertical integration into haptic actuators to sustain margin pools in the premium cabin segment. Marelli Corporation anchors its competitive position through manufacturing scale across European and North American assembly plants.
Automotive center stacks constitute the centralized control interface housing infotainment displays, climate controls, and vehicle settings, typically integrating touchscreens from 7 to 15 inches with capacitive or force-sensitive input layers and either standalone or domain-consolidated electronic architectures. Their primary purpose is consolidating human-machine interaction into a single ergonomic surface while reducing physical button count and wiring complexity. Electric stacks within the product type dimension are capturing disproportionate engineering investment as EV platforms prioritize software-defined cabin experiences over mechanical control redundancy. The OEM end user channel maintains pricing power through multi-year platform contracts, whereas aftermarket providers compete on reverse-engineered compatibility modules for aging vehicle fleets.
The EU's Cyber Resilience Act and CE marking requirements for automotive electronics are compelling stack suppliers to embed over-the-air update architectures and document software bill-of-materials across product lifecycles. NHTSA distraction guidelines in the United States are constraining touchscreen interaction complexity and mandating physical backup controls for critical functions. Stakeholders must monitor regulatory divergence between software-update mandates in Europe and driver-distraction limits in North America when allocating R&D across platform generations.
Market Dynamics
The automotive center stack sector is undergoing a fundamental architectural transition as domain consolidation replaces distributed ECU designs, compressing supplier tiers and redistributing value toward software-integrated display systems.
Growth Catalysts
- EU Cyber Resilience Act:Mandated over-the-air update capabilities in vehicle electronics are forcing stack redesigns that embed cellular modems and secure boot architectures, expanding addressable content per vehicle.
- Touchscreen-intensive EV platforms:Electric vehicle manufacturers are eliminating mechanical redundancy in favor of software-defined cabin experiences, concentrating control functions into larger, higher-resolution display surfaces.
- Stuttgart-Ingolstadt cluster:Premium OEM engineering concentration in southern Germany is pulling advanced haptic and force-feedback technologies into series production faster than other geographies.
Market Restraints
- Semiconductor supply concentration:Tight supply of automotive-grade display driver ICs from Taiwan-based foundries creates allocation risk for high-resolution stack programs.
- NHTSA distraction guidelines:Physical backup control mandates for critical functions limit full touch-screen conversion, preserving mechanical component costs in US-bound vehicles.
- Indium tin oxide price volatility:Capacitive touch layer input costs fluctuate with rare earth processing constraints, compressing margins on mid-tier stack variants.
Strategic Opportunities
- India PLI scheme for automotive electronics:Localized stack manufacturing incentives are opening cost-competitive export capacity for right-hand-drive markets.
- Software-defined vehicle convergence:Integration of center stack functions with ADAS visualization and digital instrument clusters is unifying previously separate display procurements.
- Aftermarket retrofit channels:Aging vehicle fleets in eastern Europe and Latin America are creating demand for reverse-engineered compatibility modules with modern connectivity features.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-B compliance for safety-critical stack software is extending development cycles and delaying platform launches.
- Legacy vehicle electrical architecture integration:Domain controller-based stacks must interface with older CAN/LIN networks, requiring costly protocol translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Center Stacks Market |
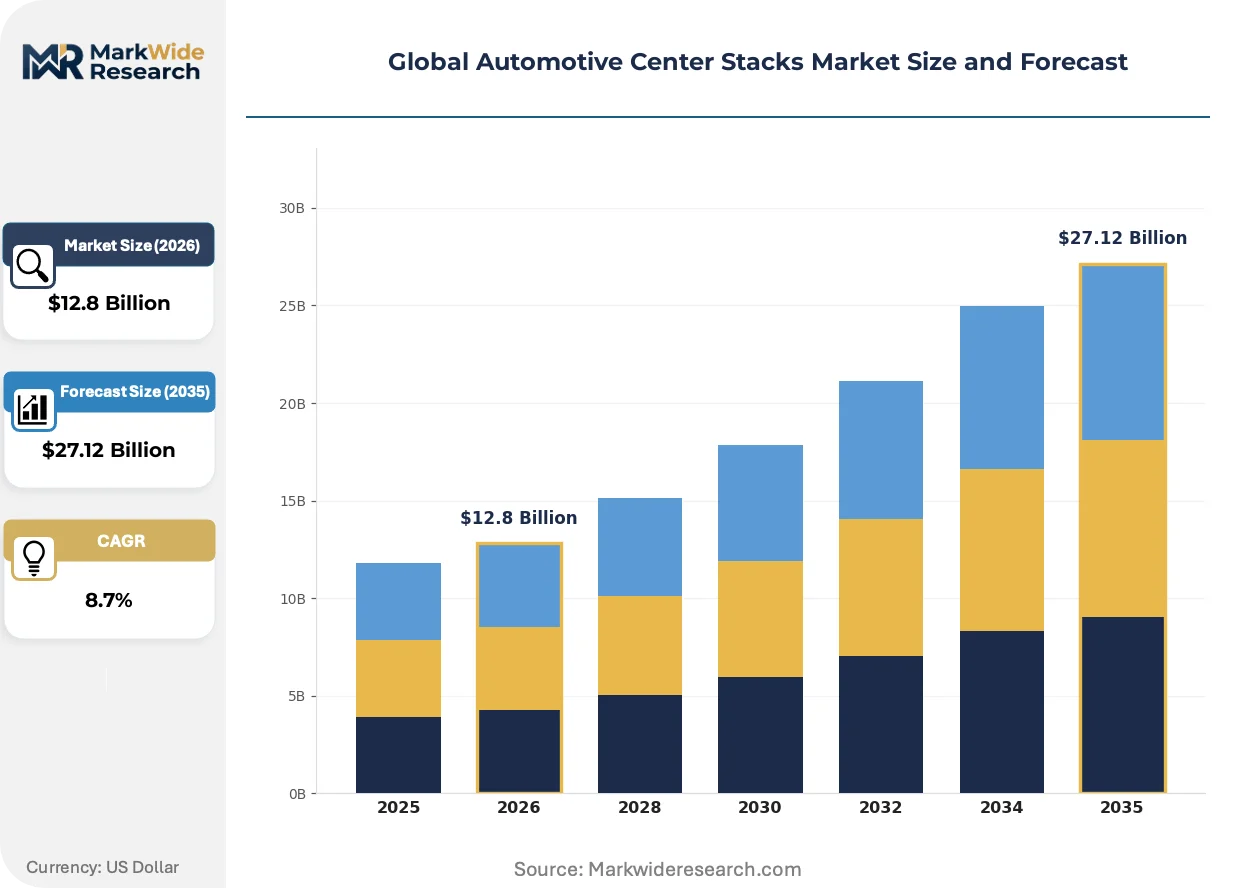
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Stacks, Turbocharged Stacks, Hybrid Stacks, Electric Stacks Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles End User: OEMs, Aftermarket Providers, Retailers, Fleet Operators Technology: Fuel Cell Technology, Internal Combustion, Electric Drive, Bi-Fuel Technology |
| Companies Covered | Preh GmbH, Hyundai Mobis Co Ltd., Marelli Corporation, Methode Electronics Inc., Visteon Corporation, Continental AG, Valeo Group, Magna International Inc., Faurecia S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Center Stacks Market Emerging Trajectories
Software-defined cabin architectures are collapsing previously separate control domains into unified compute platforms, altering how suppliers position their hardware and software capabilities.
Force-sensitive haptic feedback layers are unifying physical button replacement with programmable surface textures. Premium OEMs in Germany and California are adopting these actuators for climate and volume controls. This unification is compressing the traditional supplier base by eliminating discrete switch vendors from stack bills-of-materials.
REACH substance restrictions on halogenated flame retardants in automotive electronics are accelerating migration to phosphorus-based alternatives in stack PCB assemblies. Suppliers serving EU-bound platforms must requalify materials and resubmit technical documentation. The premium segment is absorbing these compliance costs faster than economy tiers, widening specification divergence.
Fleet operators and mobility service providers are consolidating stack procurement decisions at the holding-company level rather than delegating to individual OEM brand teams. This concentration is displacing region-specific feature customization in favor of standardized, globally deployable cabin interfaces. The shift is most visible in ride-hail vehicle specifications across Southeast Asian markets.
Global Automotive Center Stacks Market Segmentation
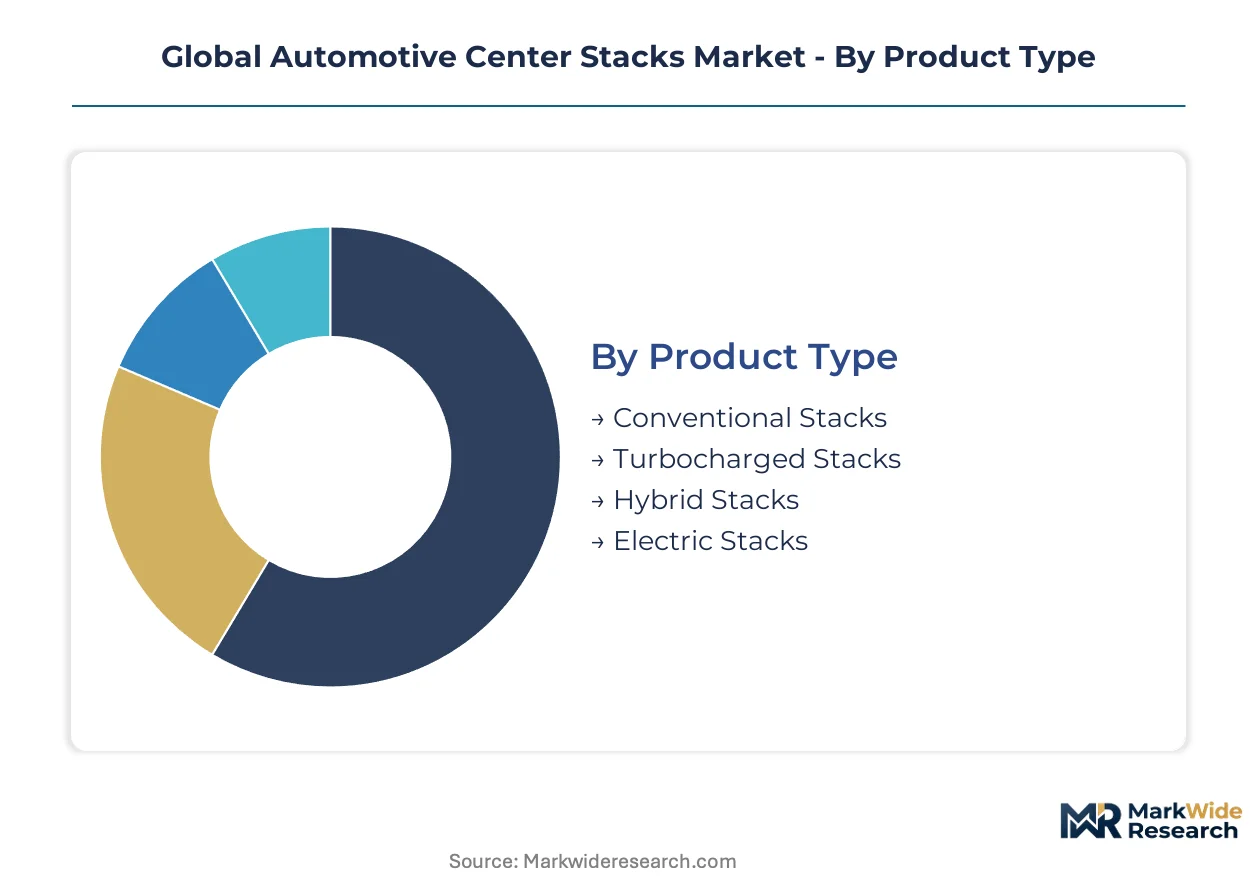
Center stack procurement patterns diverge sharply across vehicle electrification levels and buyer sophistication tiers. Suppliers must configure product portfolios around four distinct segmentation axes that reshape technical specifications, certification requirements, and margin structures.
Product Type:
Cost tier differentiation separates mechanical-intensive designs from software-defined architectures requiring domain controller integration.
- Electric Stacks:These units consolidate climate, media, and vehicle settings into single high-resolution touch surfaces with over-the-air update capability. EV manufacturers in Germany and California are specifying these for new platform launches, with EU Cyber Resilience Act compliance adding cellular modem and secure boot requirements.
- Conventional Stacks:Mechanical button-dominant designs with basic 7-inch resistive touch layers persist in economy vehicle segments. These units face margin pressure from indium tin oxide price volatility while serving aging vehicle fleets in eastern Europe and Latin America.
- Turbocharged Stacks:Mid-tier hybrid mechanical-digital interfaces balance tactile feedback with partial touchscreen integration.
- Hybrid Stacks:Transitional architectures blending analog climate controls with expanding digital display real estate.
Conventional stacks lead volumes today; electric stacks are gaining share fastest.
Application:
Vehicle electrification intensity determines display size minimums and software architecture complexity.
- Electric Vehicles:Cabin experiences are fully software-defined, eliminating mechanical redundancy in favor of 12-15 inch capacitive surfaces with haptic feedback. Stuttgart-based OEMs are pulling advanced force-feedback actuators into series production faster than other geographies.
- Passenger Vehicles:Internal combustion variants split between premium touchscreen-dominant designs and economy hybrid interfaces. NHTSA guidelines in the United States mandate physical backup controls for critical functions, preserving mechanical costs in US-bound production.
- Commercial Vehicles:Fleet operators are consolidating procurement decisions at holding-company level, displacing region-specific customization in favor of standardized cabin interfaces.
- Two-Wheelers:Compact 5-7 inch displays with basic connectivity serve emerging market mobility platforms.
Passenger vehicles dominate current procurement volumes; electric vehicles show the steepest expansion trajectory.
End User:
Purchasing power concentration and technical specification authority vary dramatically across buyer types.
- OEMs:Multi-year platform contracts lock in pricing through vehicle generation cycles, with premium German manufacturers clustering engineering decisions around Stuttgart and Ingolstadt. These buyers specify ASIL-B functional safety compliance and integrated domain controller architectures.
- Aftermarket Providers:Reverse-engineered compatibility modules serve aging fleets in eastern Europe and Latin America, competing on connectivity feature additions rather than original equipment integration depth.
- Fleet Operators:Mobility service providers in Southeast Asia are standardizing specifications across vehicle brands to simplify driver training and maintenance protocols.
- Retailers:Fragmented demand from individual vehicle owners seeking upgrade solutions for out-of-warranty vehicles.
OEMs command the largest contract values; aftermarket providers are expanding most quickly in emerging economies.
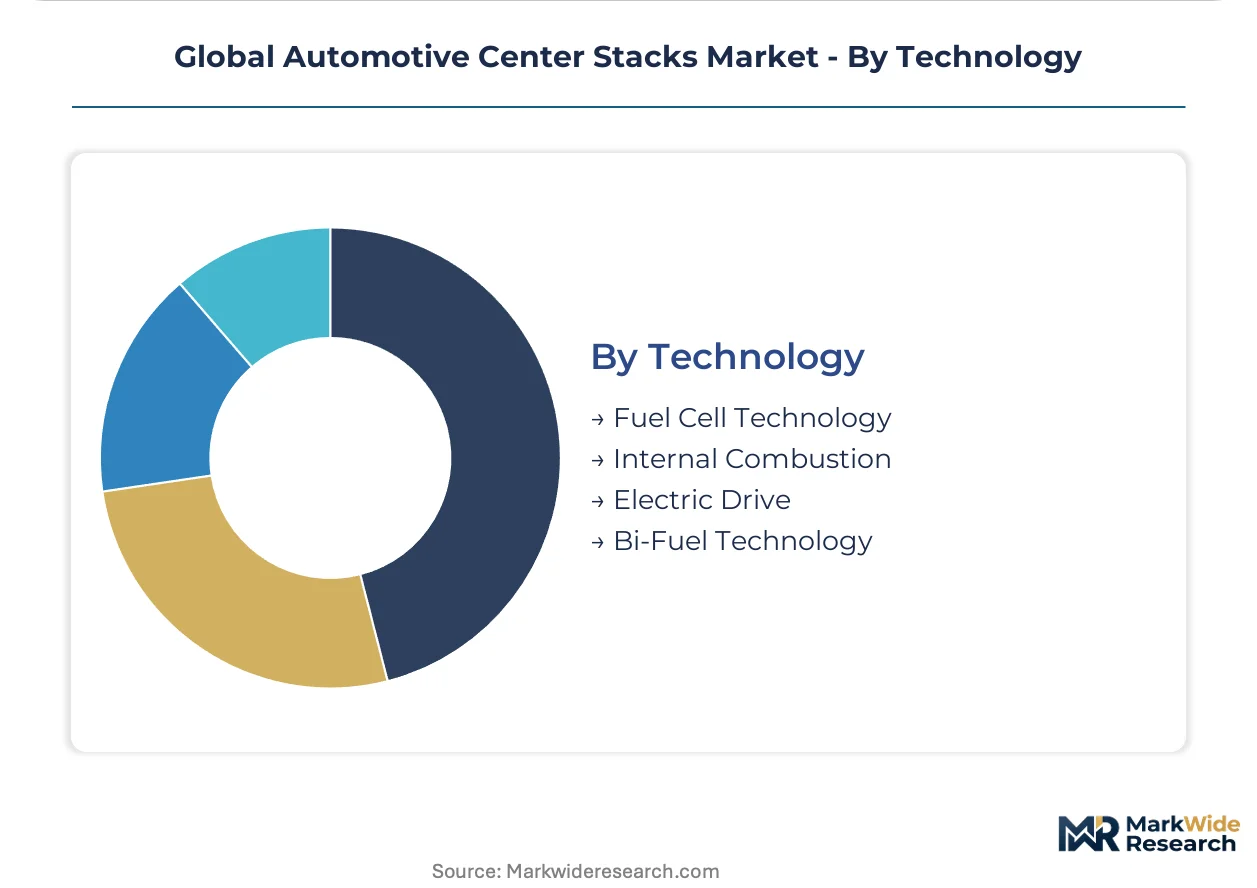
Technology:
Powertrain electrification level dictates stack electronic architecture and thermal management requirements.
- Electric Drive:Full software-defined cabin experiences with unified compute platforms replacing distributed ECU designs. These systems integrate ADAS visualization and digital instrument clusters into single procurement decisions.
- Internal Combustion:Legacy CAN/LIN network interfaces require costly protocol translation layers when upgrading to domain controller-based stacks. REACH substance restrictions on halogenated flame retardants are forcing material requalification in EU-bound production.
- Fuel Cell Technology:Hydrogen powertrain stacks require specialized thermal monitoring integration and extended operating temperature ranges.
- Bi-Fuel Technology:Dual-fuel compatibility demands flexible software calibration for varying energy source operating modes.
Internal combustion anchors current installed base; electric drive systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium engineering concentration while China scales manufacturing throughput for touchscreen-intensive platforms. The United States preserves mechanical backup mandates under NHTSA guidelines. India builds export capacity through electronics manufacturing incentives.
Germany
Stuttgart and Ingolstadt host premium OEM engineering clusters demanding advanced haptic actuators and force-feedback technologies. The KBA enforces type approval for software-update architectures under EU Cyber Resilience Act alignment. Baden-Württemberg suppliers integrate domain controllers into series production faster than competing geographies.
China
MIIT standards for intelligent connected vehicles accelerate large-format display adoption across domestic EV platforms. GB standards mandate cybersecurity management systems for automotive electronics. The Yangtze River Delta concentrates display driver IC packaging capacity serving both domestic and export stack programs.
United States
NHTSA distraction guidelines preserve physical backup controls for critical functions in US-bound vehicles. Michigan and Ohio assembly plants balance touchscreen integration with mechanical redundancy requirements. Detroit-based Tier-1s maintain dual-architecture tooling for domestic and export specifications.
India
PLI scheme incentives for automotive electronics attract stack module assembly for right-hand-drive export markets. Tamil Nadu and Karnataka host emerging electronics manufacturing clusters serving Southeast Asian vehicle platforms. Domestic OEMs specify cost-optimized hybrid interfaces blending mechanical and capacitive elements.
Japan
METI carbon neutrality roadmaps push software-defined cabin architectures into kei-car and compact vehicle segments. Nagoya-area suppliers develop compact haptic modules for space-constrained vehicle platforms. JIS standards govern electromagnetic compatibility for integrated display systems in domestic production.
Global Automotive Center Stacks Market Vendor Landscape
Top-tier vendors anchor multi-year platform contracts with premium German OEMs, while mid-tier specialists compete on manufacturing scale across regional assembly plants. The supplier base compresses around domain consolidation, eliminating discrete ECU vendors from stack procurement decisions. Three archetypes dominate: haptic technology specialists, scale manufacturing integrators, and software-defined cabin platform providers. Competitive moves center on backward integration into actuator production and strategic partnerships for OTA update infrastructure.
Within the haptic technology tier, Preh GmbH exemplifies captive supply of force-feedback actuators for premium cabin specifications. Marelli Corporation and Continental AG occupy positions spanning manufacturing scale and systems integration across European and North American production footprints. Hyundai Mobis Co Ltd. represents the Korea-based archetype linking display module production with parent-affiliated vehicle platform access.
| Leading Market Players |
|---|
| Preh GmbH |
| Hyundai Mobis Co Ltd. |
| Marelli Corporation |
| Methode Electronics Inc. |
| Visteon Corporation |
| Continental AG |
| Valeo Group |
| Magna International Inc. |
| Faurecia S.A. |
| Others |
Supply Flow & Price Mechanics
Premium-commodity bifurcation between haptic-intensive electric stacks and mechanical-dominant conventional units manifests in divergent pricing power and sourcing strategies. ASIL-B certification requirements and domain controller integration anchor premium tier pricing, while indium tin oxide volatility and Taiwan foundry concentration compress margins at the commodity end.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for right-hand-drive export markets. Three-tier pricing structure across premium, standard, and economy levels separates force-feedback actuator integration from basic resistive touch layers. Price differentiation rests on ASIL-B certification grade and volume scale commitments in multi-year OEM contracts. Pricing pressure stems from semiconductor allocation constraints at Taiwan-based foundries serving high-resolution display programs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Ingolstadt engineering clusters. Manufacturing concentrates in Germany, China, and Mexico, with display driver IC packaging anchored in the Yangtze River Delta. Raw material dependencies include indium tin oxide for capacitive layers, automotive-grade driver ICs, and phosphorus-based flame retardants for REACH compliance. Single-source vulnerability at Taiwan foundries creates allocation risk for premium stack programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fleet operators and mobility providers consolidate procurement around standardized, software-defined cabin specifications. Premium haptic integration and OTA update architectures command durable pricing power against commodity alternatives.
For Market Incumbents: Acquire force-feedback actuator production capabilities to defend margin pools against haptic technology specialists. Secure multi-year platform contracts with Stuttgart-based OEMs before domain consolidation eliminates discrete ECU vendors. Prioritize backward integration into secure boot architecture components to meet EU Cyber Resilience Act mandates. For New Entrants and Emerging Players: White-space haptic module development for compact vehicle platforms presents the most penetrable entry vector. Target aftermarket retrofit channels in eastern Europe and Latin America with reverse-engineered connectivity modules. Pursue direct partnerships with India-based electronics manufacturing clusters to access PLI scheme incentives for right-hand-drive export capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where domain controller integration collapses previously separate display procurement decisions. Mid-tier suppliers lacking software-defined vehicle platform capabilities face acquisition or exit over the medium-term horizon. Monitor NHTSA distraction guideline enforcement as a signal for mechanical backup control preservation versus full touchscreen conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Haptic Actuator Backward Integration | Captive supply of force-feedback components secures margin pools in premium cabin specifications. |
| OTA Update Infrastructure Partnership | Cellular modem and secure boot integration meets KBA type approval requirements under EU Cyber Resilience Act. |
| India PLI Manufacturing Footprint | Tamil Nadu and Karnataka assembly capacity targets cost-competitive right-hand-drive export markets. |
| Software-Defined Vehicle Platform Investment | Unification of center stack, ADAS visualization, and digital instrument cluster procurement decisions. |
| Aftermarket Connectivity Module Development | Reverse-engineered compatibility solutions serve aging vehicle fleets in emerging economy markets. |
Methodological Framework
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each regional production cluster. The approach combines structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation. Sources include vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and customs records for display component trade flows. Bottom-up segment sizing triangulates against top-down production volume estimates.
Granularity-level modeling disaggregates volume and value outputs by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from fitted growth curves applied to baseline penetration rates and technology substitution dynamics. Industry-specific forecast inputs incorporate EU Cyber Resilience Act implementation timelines and NHTSA distraction guideline enforcement patterns across the analysis window.
The model holds under stable regulatory implementation schedules; deviation in semiconductor supply allocation or REACH substance restriction enforcement would shift trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market