
 Automotive Intercooler Market | 2026-2036
Automotive Intercooler Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intercooler Market Intelligence
IATF 16949 certification for quality management systems is rotating the competitive landscape toward suppliers with documented process control and traceability. MAHLE GmbH leverages its extensive R&D in thermal management to serve global original equipment manufacturers. BorgWarner Inc. differentiates through its integrated turbocharging and cooling system offerings, while Modine Manufacturing Company specializes in robust solutions for heavy-duty commercial vehicles.
An automotive intercooler is a critical heat exchanger used to cool compressed intake air from a turbocharger or supercharger before it enters the engine. These devices, often featuring aluminum tube and fin construction, increase air density to improve combustion efficiency and overall power output. Air-to-air intercoolers remain the dominant type due to their simplicity in passenger vehicles. Air-to-water designs are gaining significant traction in high-performance applications for their compact packaging and superior thermal performance.
Global emissions regulations, including standards set by the US Environmental Protection Agency (EPA) and the European Union's Euro 7 framework, directly mandate powertrain efficiency improvements. In China, national GB standards for vehicle performance and emissions further compel automakers to adopt advanced thermal management technologies. Supplier success depends on the ability to engineer solutions that balance thermal performance with weight, size, and cost constraints for diverse powertrain architectures.
Market Dynamics
The imperative to improve internal combustion engine efficiency, driven by global emissions regulations, is the central force shaping the automotive intercooler market. This pressure compels engine downsizing and turbocharging, making advanced charge air cooling a non-negotiable system component for automakers.
Growth Catalysts
- Stringent Emissions Standards:Europe's forthcoming Euro 7 framework and existing EPA rules in the United States mandate lower NOx and CO2 emissions, directly promoting powertrain technologies like turbocharging that require intercoolers for optimal performance.
- Commercial Vehicle Efficiency:The global trucking industry is adopting turbocharged engines to meet fuel efficiency targets and payload requirements, creating sustained demand for durable, high-performance intercoolers specifically designed for heavy-duty cycles.
- Engine Downsizing Trend:Automakers in major production centers like China and Germany are replacing larger, naturally aspirated engines with smaller, turbocharged equivalents to improve fuel economy, which necessitates the use of an intercooler.
Market Restraints
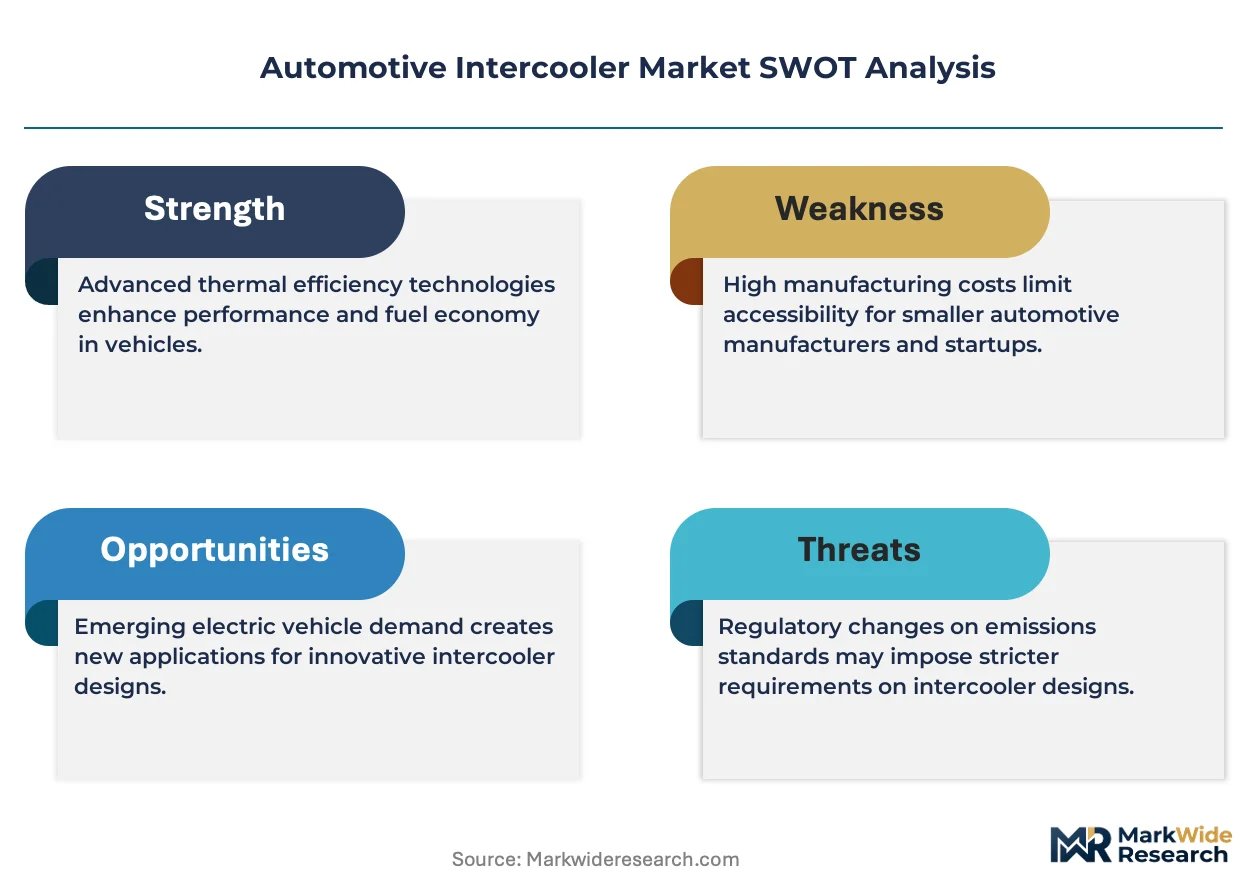
- Raw Material Price Volatility:The market is sensitive to fluctuations in the price of aluminum, the primary material used in tube and fin construction, which can compress supplier margins and impact final component costs for automakers.
- BEV Substitution Threat:The long-term transition toward battery electric vehicles, which do not use internal combustion engines or intercoolers, represents a fundamental structural threat to the market's future demand base.
- Packaging and Thermal Constraints:In compact vehicle platforms, fitting an adequately sized air-to-air intercooler without suffering from heat soak in dense engine bays presents a significant engineering and design challenge.
Strategic Opportunities
- High-Performance Hybrids:The development of advanced hybrid and plug-in hybrid electric vehicles (PHEVs) with downsized, high-output engines creates an opportunity for compact, high-efficiency air-to-water intercooler systems.
- Aftermarket and Tuning Segments:A significant opportunity exists in the performance aftermarket, where enthusiasts and tuners seek larger, more efficient intercoolers to support higher levels of engine boost and power output.
- Integrated Thermal Modules:Engineering intercoolers as part of a consolidated front-end module, combining the radiator, condenser, and charge air cooler, offers automakers a path to reduce weight, complexity, and assembly time.
Industry Challenges
- Certification and Compliance Burden:Achieving and maintaining IATF 16949 certification requires significant investment in process control, documentation, and traceability, creating a barrier for smaller suppliers trying to enter the OEM supply chain.
- Capital-Intensive Tooling:Developing intercoolers for new powertrain architectures requires substantial upfront capital expenditure for design validation, testing rigs, and production tooling, with long payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intercooler Market |
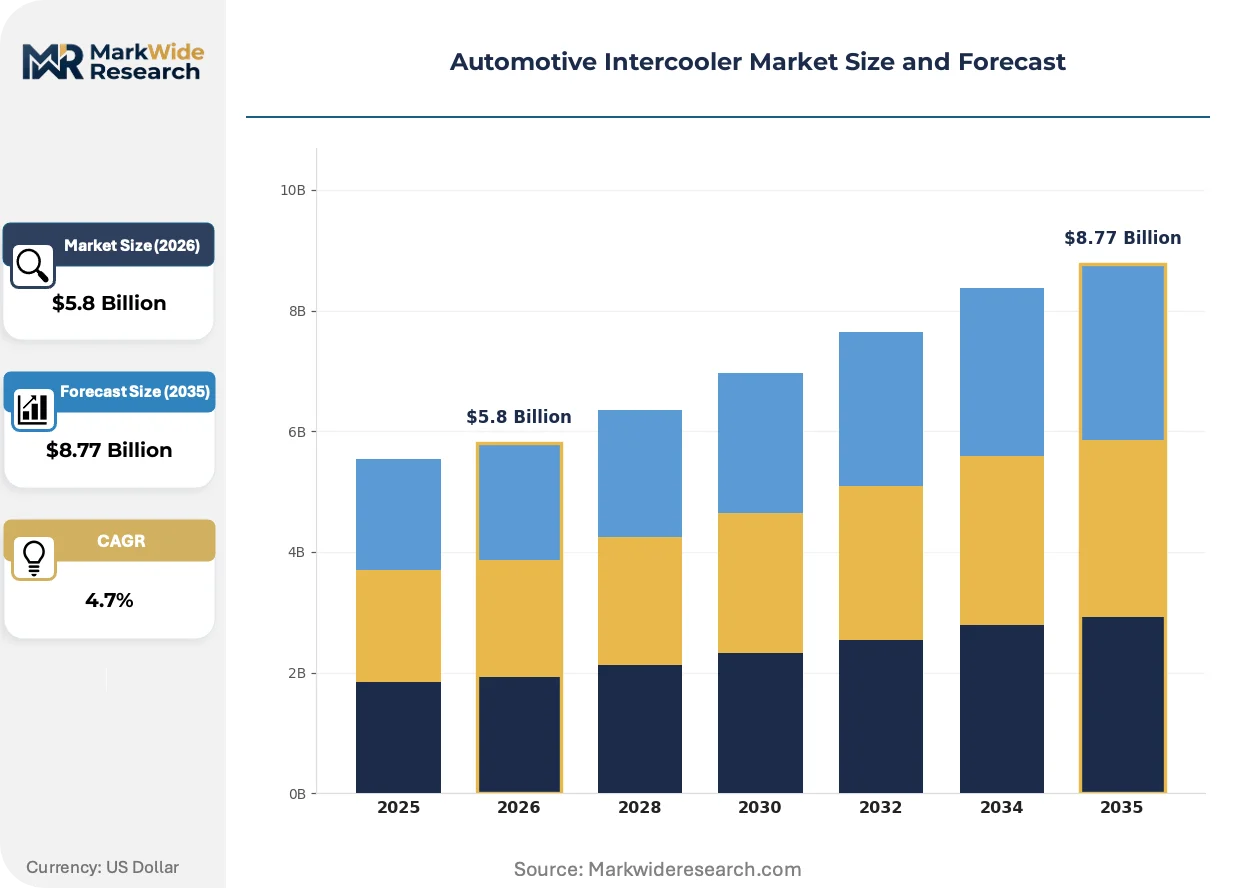
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Air-to-Air, Air-to-Water, Charge Air Cooler, Evaporative Cooler Technology: Bar & Plate, Tube & Fin, Plate & Fin, Spiral Wound Application: Passenger Vehicles, Commercial Trucks, Construction Equipment, Agricultural Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | MANN+HUMMEL Group, Modine Manufacturing Company, Bell Intercoolers, BorgWarner Inc., MAHLE GmbH, Valeo, Mishimoto Automotive, DENSO Corporation, Garrett Motion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intercooler Market Strategic Shifts & Innovations
Material science and thermal management innovations are advancing intercooler design beyond traditional constraints. The market is evolving to meet the demands of more complex powertrain systems, where thermal efficiency is directly linked to regulatory compliance and vehicle performance.
Air-to-water intercooler designs feature a separate coolant circuit to manage intake air temperature with high precision. Automakers are adopting this technology in high-performance and premium vehicle segments where consistent power delivery is a key brand differentiator. This advanced cooling solution is displacing less efficient air-to-air systems in applications where compact packaging and minimal turbo lag are critical design requirements.
China's national GB standards for vehicle emissions and fuel consumption continue to tighten, impacting all vehicles sold in the country. This regulatory pressure forces both domestic manufacturers and foreign joint ventures to upgrade powertrain components to meet local compliance. The heavy-duty commercial truck segment is most affected, accelerating demand for robust intercoolers engineered to withstand harsh operating conditions.
A distinct purchasing preference is solidifying among OEMs for suppliers who can demonstrate full compliance with the IATF 16949 quality management standard. This shift de-risks the automotive supply chain by ensuring process control and component traceability, pushing aside suppliers unable to meet these stringent documentation requirements. This procurement behavior is most pronounced in the German and Chinese automotive sectors, where manufacturing quality is a core competitive focus.
Automotive Intercooler Market Segmentation
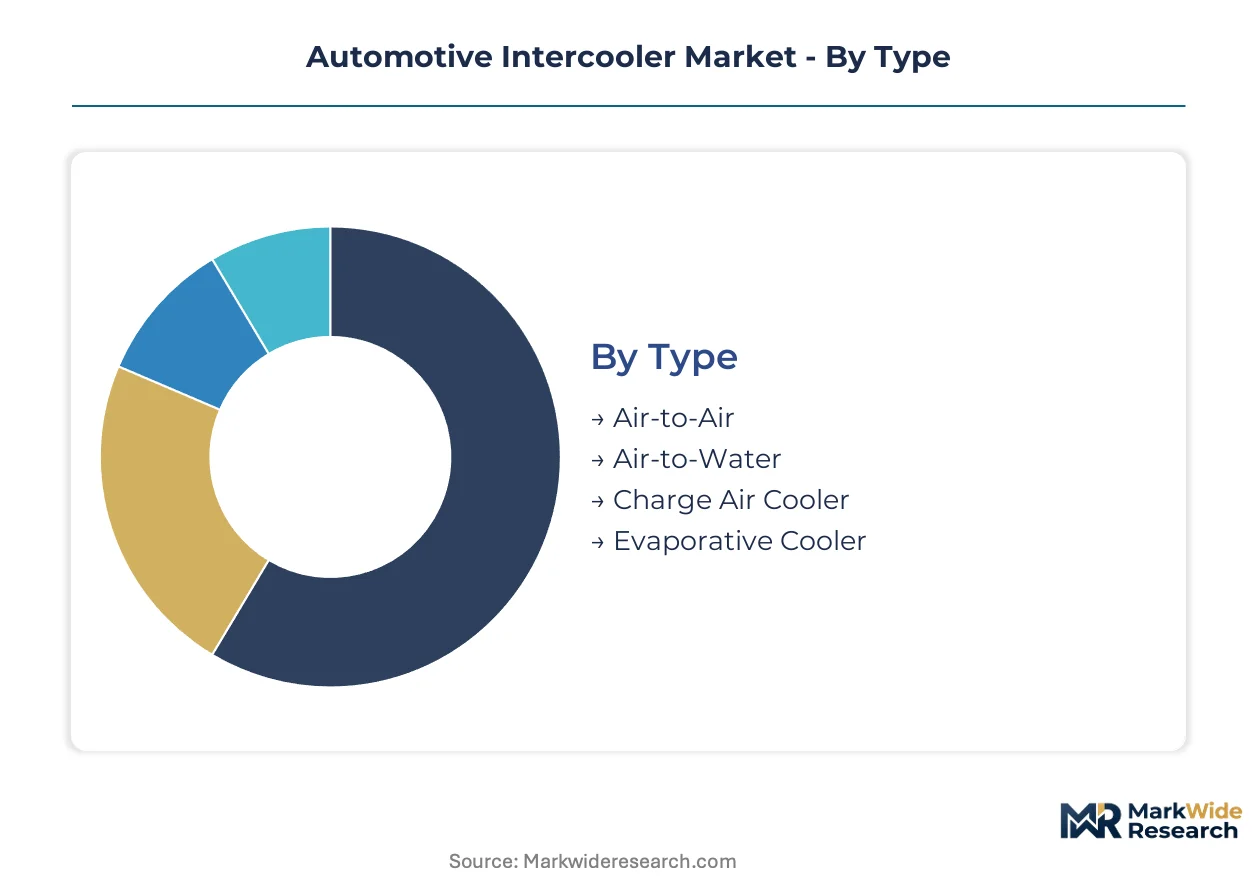
The automotive intercooler market's segmentation provides a granular understanding of product variations, technological underpinnings, and diverse end-user demands. Analyzing these distinct segments reveals specific growth pockets and competitive battlegrounds for suppliers. Each category highlights unique design considerations and performance requirements across the automotive ecosystem.
Type:
For intercoolers, the type often dictates its integration into specific powertrain architectures and supply channels, from standard production lines to specialized performance markets.
- Air-to-Air:These heat exchangers utilize ambient air to cool compressed intake air, typically featuring aluminum tube and fin construction. Demand concentrates in mass-market passenger vehicles, driven by their cost-effectiveness and packaging simplicity.
- Air-to-Water:This design employs a separate coolant circuit to precisely manage intake air temperature, offering superior thermal performance and compact packaging. High-performance applications and premium vehicle segments are driving demand, especially with minimal turbo lag requirements.
- Charge Air Cooler:This is a broader term encompassing intercoolers and aftercoolers, functioning to reduce the temperature of compressed air from forced induction systems.
- Evaporative Cooler:These systems use the evaporation of a liquid, such as water, to cool the intake air, often found in specialized high-performance or racing applications.
Air-to-air intercoolers dominate the installed base in the automotive sector. Air-to-water designs are where expansion concentrates for advanced powertrain systems.
Technology:
The manufacturing technology employed for intercoolers directly influences their thermal efficiency, durability, and cost profile across different vehicle segments.
- Bar & Plate:This robust construction method involves stacking alternating layers of bars and fins, brazed together to form a highly durable core. Commercial trucks and heavy-duty applications demand this technology for its resistance to vibration and pressure.
- Tube & Fin:Featuring a series of tubes connected by fins, this lightweight design offers efficient heat transfer and is cost-effective for mass production. Passenger vehicles extensively utilize tube and fin intercoolers due to their balance of performance and manufacturing ease.
- Plate & Fin:This technology uses flat plates separated by corrugated fins, providing a compact and efficient core often seen in performance-oriented applications.
- Spiral Wound:Utilizing a spirally wound tube design, this niche technology offers specific thermal advantages for certain high-pressure or compact system requirements.
The market widely adopts tube and fin structures for their efficiency and cost. Bar and plate designs offer enhanced durability for demanding applications.
Application:
Intercooler applications vary significantly by vehicle type, with each segment presenting unique requirements for thermal performance and operational resilience.
- Passenger Vehicles:These applications require compact, lightweight intercoolers to support engine downsizing and turbocharging for improved fuel economy and emissions. Demand concentrates in major automotive production centers like Germany and China, driven by stringent Euro 7 and GB standards.
- Commercial Trucks:Intercoolers for heavy-duty commercial vehicles demand extreme durability and consistent performance over long operational cycles. The global trucking industry's pursuit of fuel efficiency targets creates sustained demand for these robust components.
- Construction Equipment:Intercoolers in construction machinery must withstand harsh operating environments and provide reliable cooling for high-torque engines.
- Agricultural Vehicles:These applications require durable intercoolers designed to operate effectively in dusty, demanding conditions, supporting engine performance for farm machinery.
Passenger vehicles account for the largest volume of intercooler installations. Commercial trucks exhibit strong growth due to increasing efficiency mandates.
End User:
The end-user segment dictates procurement channels and specific product requirements, influencing design customization and quality assurance standards.
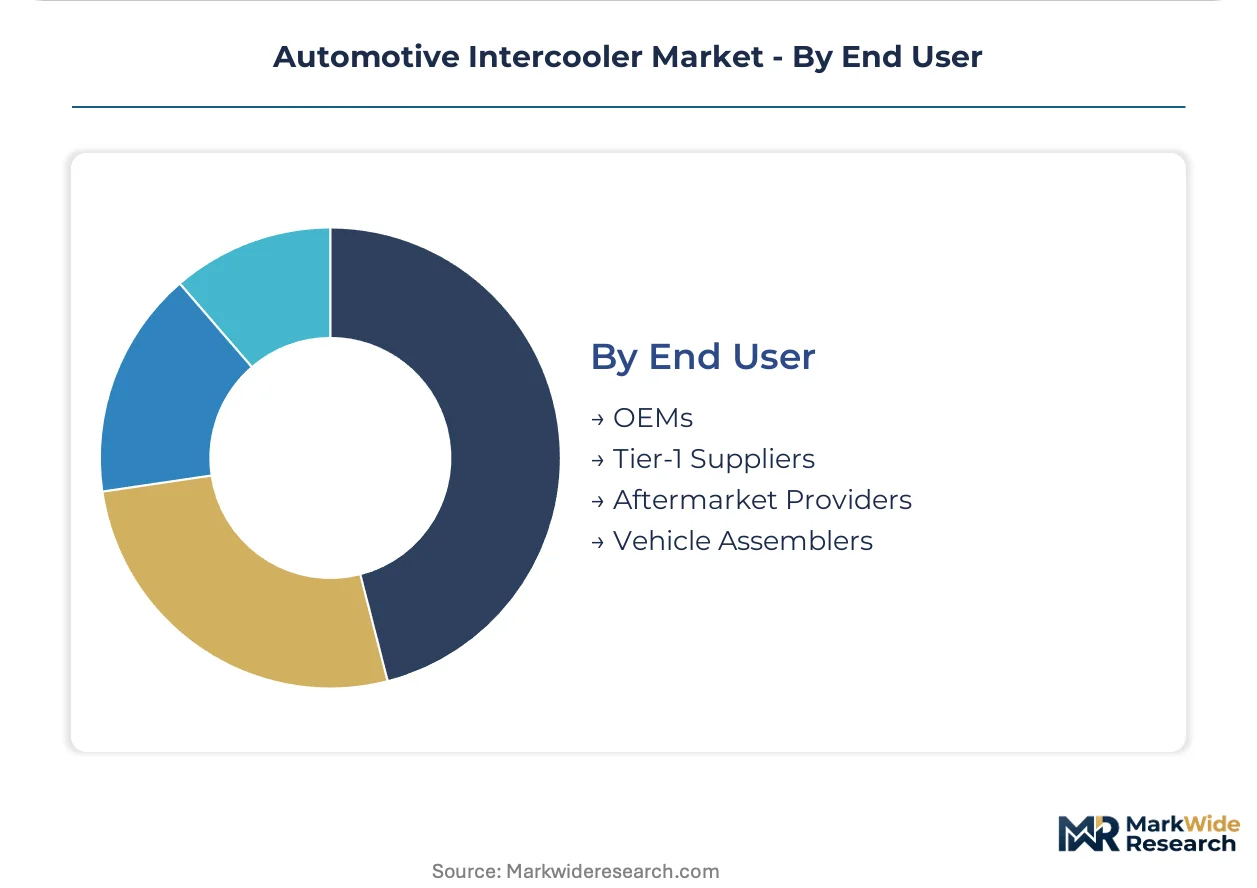
- OEMs:Original Equipment Manufacturers integrate intercoolers directly into new vehicle designs, demanding IATF 16949 certification and solutions balancing thermal performance with weight and cost constraints. Global emissions regulations from the EPA and EU's Euro 7 framework compel OEM adoption.
- Tier-1 Suppliers:These suppliers procure intercoolers as components for larger sub-assemblies, often requiring collaborative engineering and stringent quality control. Their success depends on delivering integrated solutions to OEMs for diverse powertrain architectures.
- Aftermarket Providers:These entities supply replacement parts and performance upgrades for existing vehicles, catering to repair needs and enthusiast tuning segments.
- Vehicle Assemblers:Primarily focused on integrating pre-sourced components into final vehicles, these users require reliable and precisely engineered intercooler units.
OEMs represent the largest demand source for new intercooler designs. Aftermarket providers serve specialized needs for vehicle upgrades and replacements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global emissions regulations, including Europe's Euro 7 framework and US Environmental Protection Agency (EPA) rules, are driving the automotive intercooler market's regional evolution. These mandates compel engine downsizing and turbocharging, necessitating advanced charge air cooling solutions. Major automotive production hubs are responding to these pressures for efficiency.
Germany
Germany's automotive sector demands high-efficiency intercoolers for premium and performance vehicles. The forthcoming Euro 7 framework mandates significant powertrain efficiency improvements, compelling local automakers. Manufacturing centers in Bavaria and Baden-Württemberg are concentrating on developing advanced thermal management solutions for both passenger cars and commercial vehicles.
China
China's vast automotive market requires intercoolers for both passenger vehicles and heavy-duty commercial trucks. National GB standards for emissions and fuel consumption continue to tighten, directly impacting domestic and foreign manufacturers. Production clusters in the Yangtze River Delta are scaling up intercooler manufacturing to meet local compliance and export demand.
United States
United States demand stems from the commercial trucking industry's pursuit of fuel efficiency targets and passenger vehicle downsizing. US EPA regulations drive the need for turbocharged engines, making intercoolers essential for performance and emissions control. Automotive manufacturing hubs in Michigan are integrating sophisticated intercooler technologies into new vehicle platforms.
Japan
Japanese automakers prioritize compact, high-efficiency intercoolers for hybrid and downsized engines. The Ministry of Economy, Trade and Industry (METI) promotes fuel efficiency standards, influencing powertrain design. Advanced thermal management R&D in the Kanto and Chubu regions focuses on innovative air-to-water intercooler systems for next-generation vehicles.
India
India's expanding passenger vehicle and commercial truck segments are driving intercooler demand for turbocharged engines. Bharat Stage (BS) emission norms compel automakers to adopt advanced thermal management solutions for compliance. Manufacturing hubs in Chennai and Pune are increasing production capacity for cost-effective intercooler components to serve the domestic market.
Automotive Intercooler Market Key Industry Players
Player mix skews toward established automotive component suppliers and specialized thermal management firms. The market exhibits a tiered structure, with a few large integrated players and numerous smaller, niche manufacturers operating across different segments. Strategic archetypes include global OEM suppliers focused on advanced thermal solutions and aftermarket performance specialists catering to enthusiast tuning. Dominant competitive moves involve strategic partnerships for integrated powertrain solutions and capacity expansion in major automotive production regions like Germany and China.
Among established global suppliers, MAHLE GmbH exemplifies a leader in comprehensive thermal management, leveraging extensive R&D to serve global original equipment manufacturers. BorgWarner Inc. occupies a significant position through its integrated turbocharging and cooling system offerings, which are crucial for powertrain efficiency. Modine Manufacturing Company represents a specialist in robust intercooler solutions specifically designed for heavy-duty commercial vehicles, emphasizing durability and consistent performance. These entities anchor the market by providing IATF 16949 certified components, essential for modern powertrain architectures and regulatory compliance.
| Leading Market Players |
|---|
| MANN+HUMMEL Group |
| Modine Manufacturing Company |
| Bell Intercoolers |
| BorgWarner Inc. |
| MAHLE GmbH |
| Valeo |
| Mishimoto Automotive |
| DENSO Corporation |
| Garrett Motion Inc. |
| Others |
Cost & Logistics Intelligence
Mass production efficiencies in automotive intercoolers drive down unit costs, fostering concentrated supply bases in major manufacturing regions. This scale advantage significantly influences price floors for mass-market components.
Pricing Analysis
IATF 16949 certification creates the primary pricing spread in the automotive intercooler market. Per-unit transactional pricing dominates, with quality grade and customization level serving as key differentiation drivers. Pricing softness stems from intense competition among Tier-1 suppliers for OEM contracts. Passenger vehicle OEMs are highly price-sensitive, while high-performance aftermarket segments tolerate higher costs for specialized designs.
Supply Chain Analysis
Rising inbound logistics costs, particularly for aluminum coil shipments from Asia, impact intercooler manufacturing margins. Global supply concentrates in Germany, China, and Japan, which rely on aluminum and specialized brazing materials. Commodity price volatility for aluminum represents a significant structural risk. Distribution runs primarily through direct OEM supply channels, with a smaller aftermarket segment served via distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive intercooler market is in a cyclical recovery, driven by renewed vehicle production volumes following recent supply chain disruptions. Automakers are prioritizing efficiency upgrades, further stimulating demand for advanced charge air cooling solutions.
For Market Incumbents: Fortify existing OEM relationships through IATF 16949 compliance and collaborative R&D on next-generation thermal solutions. Invest in capacity expansion within key production regions like Germany to mitigate regional supply disruptions. The BEV substitution threat necessitates R&D into hybrid-optimized intercoolers. Deepen vertical integration into aluminum processing to control raw material costs.
For New Entrants and Emerging Players: Niche high-performance air-to-water intercooler applications represent a significant service-layer gap where incumbents are slower to innovate. Target the performance aftermarket and specialized hybrid vehicle segments with compact, high-efficiency designs. Focus on direct-to-consumer digital channels and tuning communities for rapid market penetration. India's expanding commercial truck segment also offers growth potential.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized thermal management firms with strong intellectual property in air-to-water designs. Long-term viability over the next 5-10 years hinges on advanced hybrid powertrain adoption. Target mid-cap suppliers with IATF 16949 certification and established OEM relationships in Germany or China. The signal to watch is the percentage of new vehicle platforms integrating dedicated air-to-water cooling circuits.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Air-to-Water R&D | Positions for high-performance hybrid and premium vehicle segments. |
| IATF 16949 Certification Expansion | Secures OEM supply contracts and strengthens quality assurance. |
| Capacity Buildout in China | Meets tightening GB standards and local vehicle production demand. |
| Aftermarket Product Line Extension | Captures enthusiast tuning segment and replacement part revenue. |
| Integrated Thermal Module Development | Reduces automaker assembly time and optimizes vehicle packaging. |
Research Approach
Initial hypotheses were tested against primary input from OEM procurement managers, Tier-1 engineering leads, and aftermarket distributors, then refined through iterative processes. This involved extensive interviews with automotive component suppliers and validation against secondary sources. Secondary data included vehicle production databases, regulatory filings from EPA and EU, and industry association reports. A robust bottom-up and top-down triangulation approach ensured data consistency.
Variance decomposition isolated the impact of key market drivers, segmenting the market by intercooler type, technology, application, and end-user. The analytical framework projects market trajectories across the analysis window. Compound annual growth rates were derived from historical trends and projected demand forecasts. Engine downsizing trends and evolving emissions regulations provided critical forecast inputs.
Forecasts assume regulatory continuity in US EPA and EU Euro 7 frameworks; material policy shifts would require re-modeling. Geopolitical events and raw material supply disruptions represent risk factors that could alter projected market paths. Practitioners should keep alternative scenarios live as global trade policies and technological transitions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Powerglide Shifter Market
Automotive Parts
North America Gear Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Morocco Automotive Engine Oils Market