
 Electric Off Highway Equipment Machinery Market | 2026-2036
Electric Off Highway Equipment Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Off Highway Equipment Machinery Market Foresight
Project finance and green leasing structures are reshaping competitive entry in electric off-highway equipment, allowing rental services and mid-tier contractors to access zero-emission machinery without capital-heavy balance sheets. Caterpillar Inc. leverages its captive finance arm to bundle battery-electric excavators with service contracts across North American mining sites. Komatsu Ltd. anchors its position through in-house solid-state battery development and integrated telematics platforms for construction fleet optimization. Volvo Construction Equipment differentiates via its commercialized electric compact excavator lineup and direct-to-rental channel control in European urban construction zones.
Electric off-highway equipment machinery comprises heavy-duty vehicles engineered for earthmoving, material handling, and terrain modification without reliance on public road infrastructure, typically powered by battery-electric architectures exceeding 300 kWh capacity or hydrogen fuel cell systems delivering continuous duty cycles above eight hours. These machines serve mining extraction, commercial construction, and agricultural operations where diesel displacement reduces particulate emissions and operational noise in regulated work environments. Excavators dominate current revenue pools due to universal applicability across construction and mining workflows, while fuel cell loaders represent the fastest-expanding power source segment for high-shift underground operations where battery swapping proves impractical. Forklifts sustain mature demand through warehouse and port logistics electrification, though margin concentration sits with battery-electric variants above five-tonne lift capacity serving steel and container handling terminals.
The US EPA tailpipe emission standards for non-road engines and the EU Green Deal's Fit for 55 framework are accelerating diesel phase-out timelines, compelling manufacturers to redesign powertrain architectures for compliance-driven procurement cycles. China's MIIT dual carbon goals and NEV substitution mandates for state-owned construction fleets create guaranteed demand floors for domestic producers while restricting import access. India's CEA grid integration standards and BIS battery safety certifications for off-highway applications add compliance layers for entrants targeting infrastructure build-out programs. Stakeholders must monitor regulatory divergence between emission-performance standards and local content requirements when configuring regional manufacturing footprints and supplier partnerships.
Market Dynamics
Battery chemistry breakthroughs from Korean and Japanese suppliers are compressing recharge windows for heavy-duty machinery while tightening climate disclosure rules in Australia and Chile force mining operators toward electric fleet procurement.
Growth Catalysts
- EU Green Deal Fit for 55:The framework's diesel phase-out timelines compel construction and mining operators to accelerate electrification roadmaps, creating compliance-driven replacement cycles for excavators and loaders.
- Solid-state battery chemistry:Advances from East Asian suppliers extend duty cycles beyond eight hours for underground mining equipment, eliminating range anxiety in high-shift operations.
- Changzhou-Xuzhou manufacturing clusters:China's state-backed electrification subsidies and local content requirements concentrate production capacity, driving cost curves down for battery-electric compact excavators.
Market Restraints
- Lithium and rare earth input volatility:Cathode material price swings compress margins for battery pack producers serving the 300 kWh-plus capacity segment.
- East Asian cell supply concentration:Over-reliance on Korean and Japanese solid-state battery suppliers creates procurement vulnerability for European and North American OEMs.
- Battery swapping infrastructure gaps:Technical limitations in automated swap systems for heavy loaders above 50 tonnes restrict adoption in remote mining sites without grid access.
Strategic Opportunities
- India infrastructure build-out:The CEA's grid integration standards for off-highway applications create first-mover positioning for compliant battery-electric excavator suppliers.
- Hydrogen fuel cell convergence with telematics:Integration of fuel cell powertrains with fleet optimization platforms enables continuous-duty underground loaders where battery swapping fails.
- Green leasing channel innovation:Project finance structures allow mid-tier contractors to access zero-emission machinery without capital-heavy balance sheets.
Industry Challenges
- High-voltage technician scarcity:The shift to 800V architectures and thermal management systems outpaces vocational training programs for field service operations.
- BIS battery safety certification timelines:India's extended approval processes for off-highway applications delay market entry for new electric loader platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Off Highway Equipment Machinery Market |
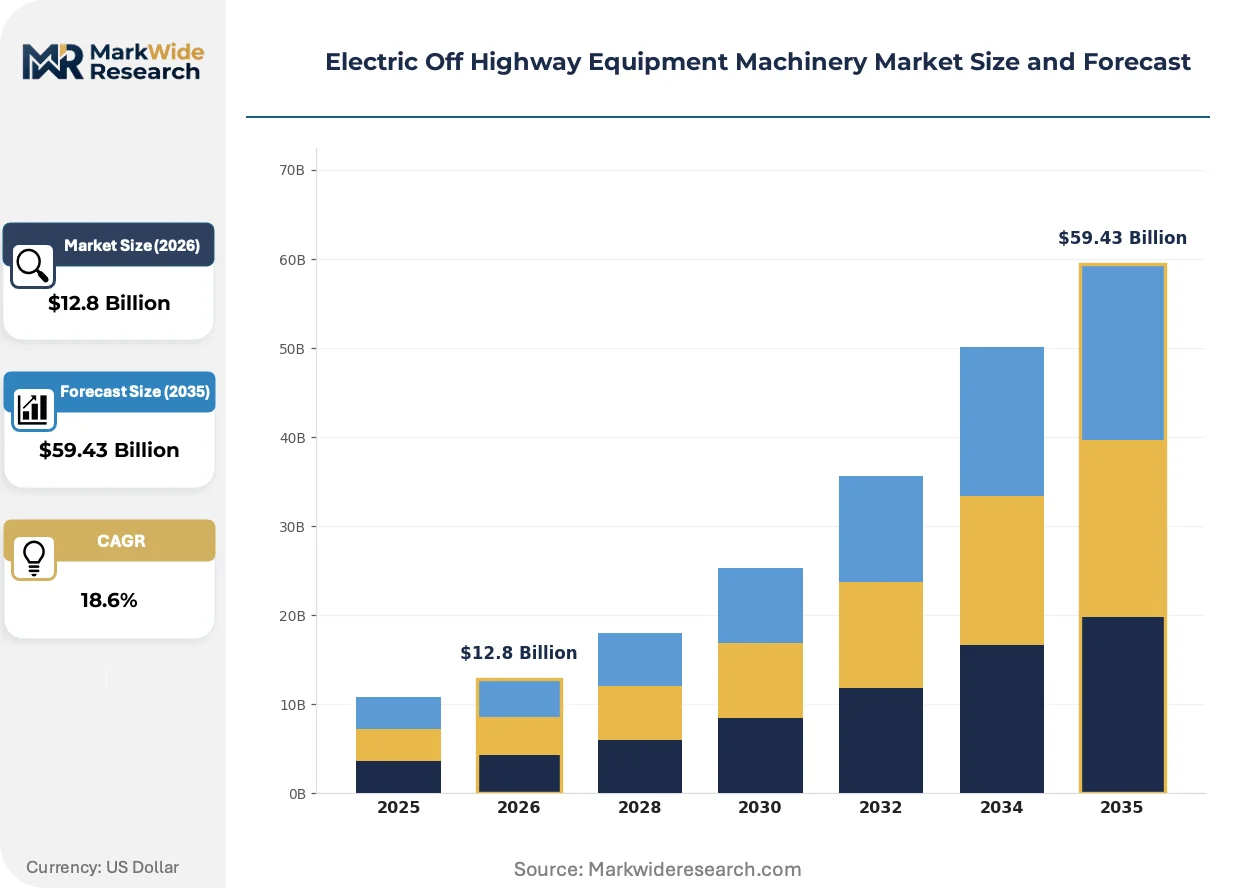
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.43 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Forklifts, Loaders Application: Agriculture, Construction, Mining, Landscaping Power Source: Battery Electric, Hybrid, Fuel Cell, Solar End User: Construction Companies, Mining Operators, Agricultural Firms, Rental Services |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery Co. Ltd., Liebherr Group, Deere & Company, SANY Group, J C Bamford Excavators Ltd., CNH Industrial N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Off Highway Equipment Machinery Market Shifts & Advancements
Telematics integration is compressing the boundary between powertrain hardware and fleet management software, enabling predictive maintenance models that reshape how operators calculate total cost of ownership for electric machinery.
Digital twin simulation is virtualizing equipment testing protocols for battery-electric excavators, allowing OEMs to validate thermal management and duty cycle performance without physical prototyping. Mining operators in Chile and Australia are adopting these virtual validation standards to pre-qualify machinery for Scope 3 compliance reporting. The technology is virtualizing traditional equipment procurement timelines, compressing vendor selection cycles from quarters to weeks.
The US EPA tailpipe emission standards for non-road engines are tightening particulate matter thresholds, forcing diesel-dependent contractors to accelerate electrification timelines or exit regulated mining zones. Equipment lessors report that compliance-driven procurement now dominates replacement decisions in North American surface mining. The construction segment responds with extended rental contracts that bundle electric compact excavators with guaranteed uptime service levels.
Consolidated fleet purchasing is displacing decentralized equipment buying across European urban construction zones, as municipal contractors centralize zero-emission machinery procurement through rental channel partnerships. Komatsu and Volvo Construction Equipment have restructured distribution to serve these consolidated buyers with direct telematics integration and predictive parts availability. Germany and the Netherlands exhibit the strongest concentration of this channel shift, where city-level diesel bans create synchronized replacement windows.
Electric Off Highway Equipment Machinery Market Segmentation
Segmentation in electric off-highway equipment reveals divergent replacement cycles across powertrain architectures and end-use intensities. Procurement patterns vary sharply between high-utilization mining fleets and seasonal agricultural deployments, reshaping how OEMs configure service networks and battery warranty terms.
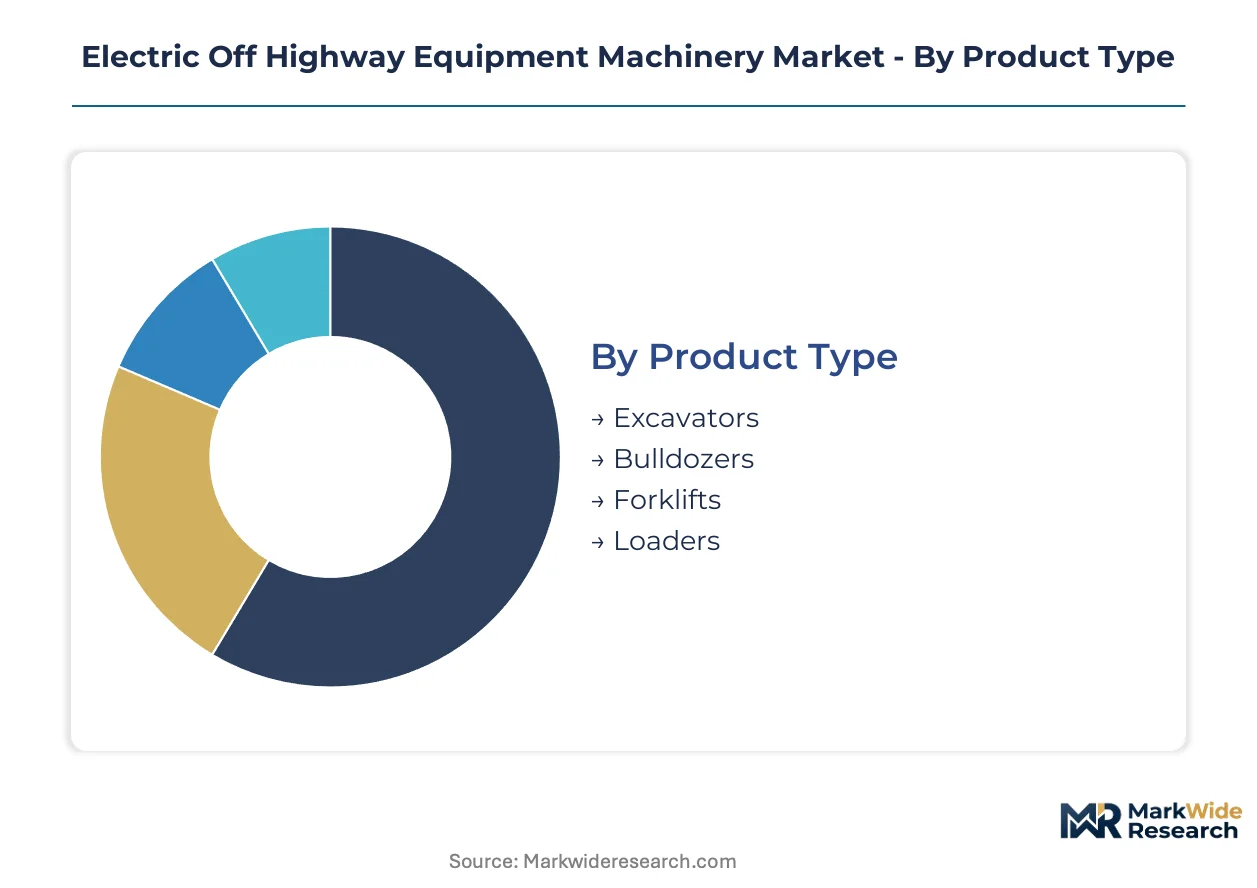
Product Type:
Excavators and loaders turn over fastest in electrifying fleets due to universal application across construction and mining workflows, while bulldozers and specialized forklifts retain longer depreciation schedules in legacy diesel operations.
- Excavators:Battery-electric variants above 20 tonnes dominate current procurement volumes, with hydraulic system electrification requiring complete powertrain redesigns rather than retrofits. Demand concentrates in Australia's iron ore basins and Chile's copper corridors where Scope 3 disclosure rules force accelerated diesel displacement.
- Loaders:Underground mining variants above 50 tonnes face the steepest technical barriers, with solid-state battery packs from Korean suppliers extending duty cycles beyond eight hours in high-shift operations. Procurement is climbing fastest where automated battery swapping infrastructure reaches commercial viability.
- Bulldozers:Track-type earthmovers above 300 kW resist rapid electrification due to continuous high-load duty cycles; hybrid architectures retain interim dominance in North American surface mining.
- Forklifts:Warehouse and port logistics variants above five-tonne lift capacity serve steel handling and container terminals, with mature battery-electric technology compressing replacement windows in European distribution hubs.
Excavators dominate installed base. Loaders are where expansion concentrates.
Application:
Cost tier differentiation separates premium electrification in regulated mining zones from economy-tier hybrid adoption in price-sensitive agricultural segments.
- Mining:Underground extraction operations impose the strictest emission and ventilation constraints, with diesel particulate exposure limits driving battery-electric procurement in Chilean and Australian jurisdictions. Fuel cell loaders gain traction where shift lengths exceed battery practical limits.
- Construction:Urban commercial building sites face municipal diesel bans and noise ordinances, concentrating electric compact excavator demand in German and Dutch metropolitan zones. Rental channel partnerships dominate procurement, bundling telematics-enabled uptime guarantees.
- Agriculture:Seasonal utilization patterns and dispersed grid access slow electrification, with smaller tractors and material handlers retaining diesel-hybrid architectures in emerging market grain belts.
- Landscaping:Low-hour annual usage and fragmented contractor bases limit battery-economic viability, though municipal fleet mandates in select European cities create niche demand pockets for electric compact equipment.
Mining commands premium pricing and shortest replacement cycles. Construction delivers volume scale through rental channel consolidation.
Power Source:
Supply concentration in East Asian solid-state cell production creates procurement bottlenecks for European and North American OEMs assembling heavy-duty battery packs.
- Battery Electric:Lithium-ion architectures exceeding 300 kWh capacity serve surface mining excavators and construction loaders, with thermal management systems determining warranty terms and residual value calculations.
- Fuel Cell:Hydrogen powertrains deliver continuous duty above eight hours for underground loaders where battery swapping infrastructure proves impractical; Japanese and Korean stack suppliers anchor technology leadership.
- Hybrid:Diesel-electric architectures retain transitional relevance in bulldozers and agricultural equipment where grid access remains intermittent and full electrification economics fail.
- Solar:Auxiliary panel integration supplements battery packs in remote landscaping and light agricultural applications, though primary powertrain reliance on solar remains negligible for heavy-duty cycles.
Battery electric dominates current order books. Fuel cell is gaining share fastest in underground mining procurement.
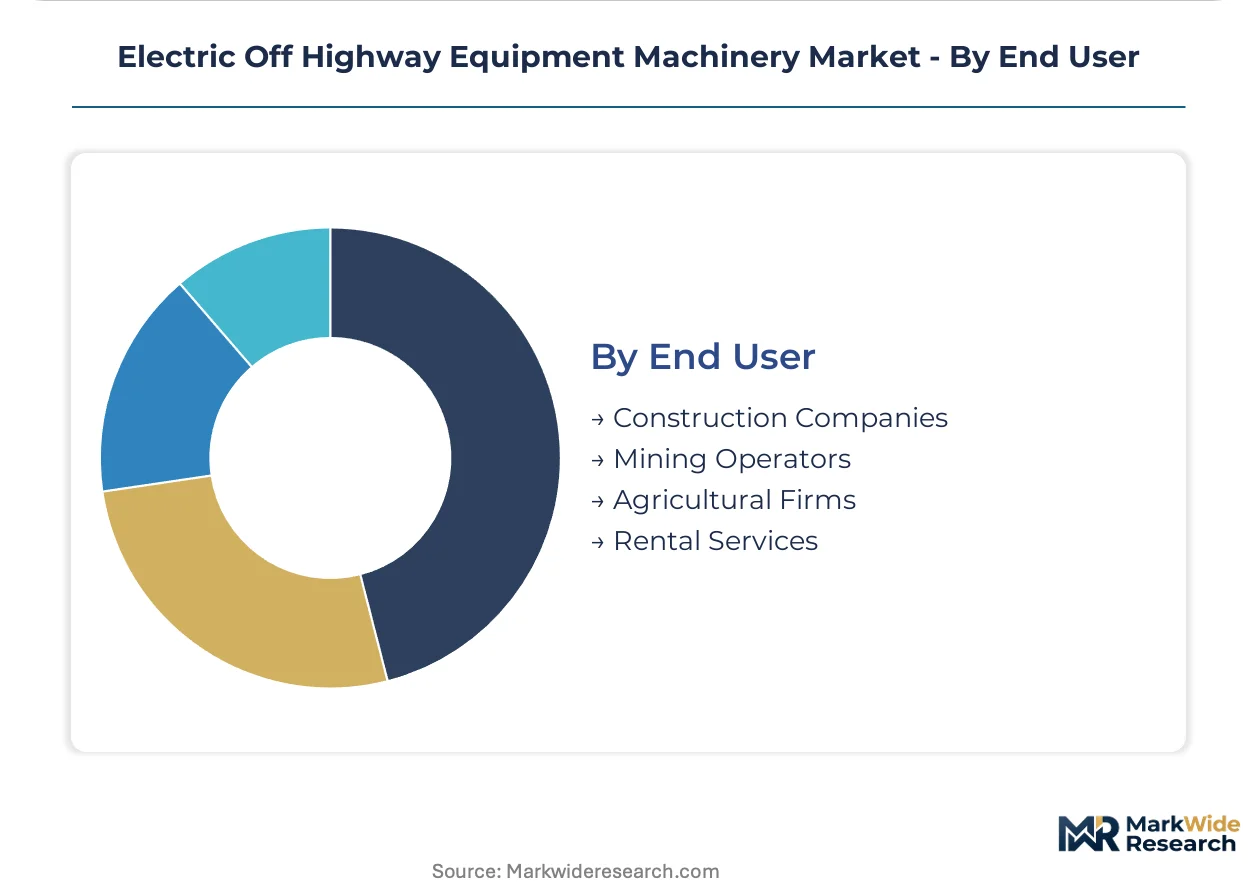
End User:
Customer type stratification separates capital-constrained rental services seeking green leasing structures from mining operators with balance sheet capacity for direct procurement of solid-state battery fleets.
- Mining Operators:Integrated extraction companies in Australia and Chile deploy captive procurement teams to pre-qualify electric machinery against Scope 3 reporting standards, compressing vendor selection cycles through digital twin validation protocols.
- Construction Companies:Municipal contractors in European urban zones centralize zero-emission equipment buying through consolidated rental partnerships, demanding guaranteed uptime service levels and predictive parts availability.
- Rental Services:Mid-tier equipment lessors leverage project finance and green leasing structures to access battery-electric excavators without capital-heavy balance sheets, reshaping competitive entry in North American surface mining zones.
- Agricultural Firms:Grain cooperatives and plantation operators exhibit fragmented procurement with seasonal utilization patterns, slowing electrification adoption relative to continuous-duty mining and construction segments.
Mining operators anchor technology adoption and pricing power. Rental services are where customer base expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed electrification subsidies and tightening diesel phase-out timelines are redistributing production capacity and procurement demand across national markets. Local content requirements and mining disclosure rules are accelerating fleet turnover in jurisdictions with the strongest regulatory enforcement.
China
MIIT dual carbon goals and NEV substitution mandates for state-owned construction fleets create guaranteed demand floors for domestic producers. The country's MIIT electrification directives restrict import access while concentrating production in Changzhou and Xuzhou manufacturing clusters. State-backed subsidies accelerate cost curve compression for battery-electric compact excavators serving municipal construction programs.
Australia
Iron ore basins in Western Australia and Queensland drive accelerated diesel displacement as mining operators face tightening Scope 3 emissions disclosure requirements. The country's climate reporting standards force integrated extraction companies to pre-qualify electric machinery through digital twin validation protocols. Procurement concentrates in Pilbara and Bowen Basin mining corridors where ventilation constraints favor battery-electric loaders.
United States
EPA tailpipe emission standards for non-road engines tighten particulate matter thresholds, compelling surface mining contractors to accelerate electrification timelines. The agency's compliance-driven procurement now dominates replacement decisions across Appalachian and Powder River Basin operations. Equipment lessors report extended rental contracts bundling electric excavators with guaranteed uptime service levels in regulated mining zones.
Germany
EU Green Deal Fit for 55 diesel phase-out timelines synchronize replacement windows for municipal construction fleets facing city-level diesel bans. The framework's emission-performance standards concentrate electric compact excavator demand in metropolitan zones around Berlin, Hamburg, and the Ruhr. Rental channel partnerships with consolidated fleet purchasing reshape distribution structures for zero-emission machinery.
India
CEA grid integration standards and BIS battery safety certifications for off-highway applications create compliance layers for entrants targeting infrastructure build-out programs. The country's extended approval processes delay market entry for new electric loader platforms while state-level electrification pilots concentrate demand in Maharashtra and Gujarat construction corridors. Procurement fragmentation across seasonal agricultural and continuous-duty mining segments slows uniform adoption.
Electric Off Highway Equipment Machinery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated access routes to end-use segments. The structure tiers between consolidated mining procurement teams with captive pre-qualification protocols and fragmented rental services seeking green leasing structures. Three archetypes dominate: integrated OEMs with captive finance arms, battery-technology specialists with in-house cell development, and regional fabricators leveraging state-backed subsidy access. Competitive moves center on telematics platform integration and service contract bundling.
Among integrated OEMs with captive finance capabilities, Caterpillar Inc., Komatsu Ltd., and Volvo Construction Equipment occupy anchor positions representing distinct strategic postures. Caterpillar exemplifies the North American mining-focused archetype through project finance bundling. Komatsu sits within the East Asian technology-integrated tier emphasizing solid-state battery development. Volvo Construction Equipment represents the European urban construction specialist with direct rental channel control. Each anchors a competitive vector without overlapping positioning.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co. Ltd. |
| Liebherr Group |
| Deere & Company |
| SANY Group |
| J C Bamford Excavators Ltd. |
| CNH Industrial N.V. |
| Others |
Supply & Pricing Matrix
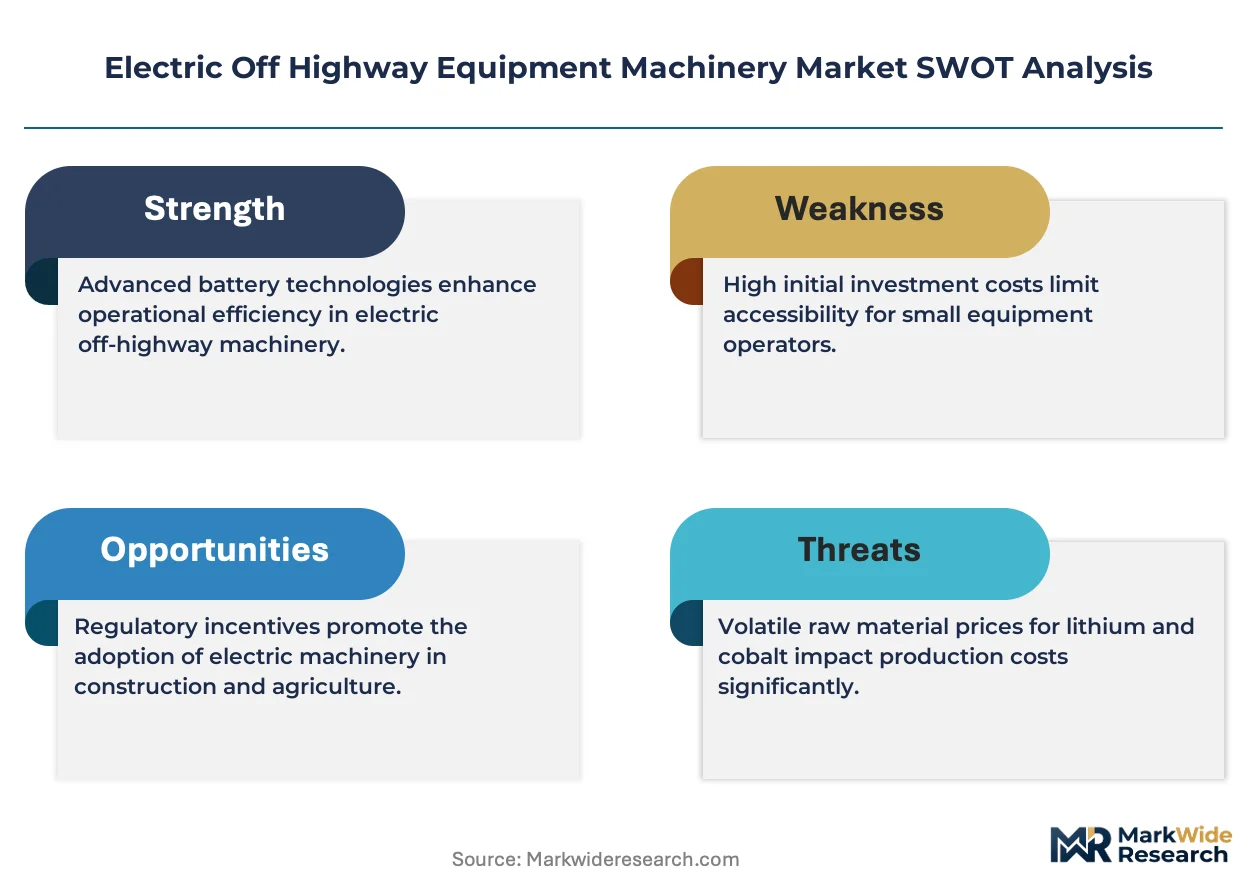
Korean and Japanese solid-state battery cell concentration anchors margin distribution across the electric off-highway equipment value chain, with cathode material volatility compressing pack producer returns while OEMs capture service-integrated premiums through captive finance structures.
Pricing Analysis
Certification level (CE marking for EU market access, EPA compliance for North American mining zones, BIS battery safety clearance for India) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium certified, standard compliant, and economy hybrid levels dominates procurement, with thermal management warranty terms and predictive service bundling as secondary differentiation factors. Cost compression in the 300 kWh-plus battery pack segment is intensifying because lithium and rare earth input volatility outpaces OEM hedging capacity. Rental services exhibit highest price sensitivity due to green leasing margin constraints, while integrated mining operators in Australia and Chile demonstrate lowest sensitivity given Scope 3 compliance-driven procurement mandates.
Supply Chain Analysis
Export control regimes limiting solid-state electrolyte technology transfer from Japan and Korea constrain European and North American OEM access to next-generation cell architectures. Manufacturing concentration centers on China, South Korea, and Japan for lithium-ion cell production, with Changzhou and Xuzhou clusters dominating battery-electric compact excavator assembly. Raw material dependencies rest on Chilean lithium carbonate, Indonesian nickel, and Chinese rare earth processing capacity. Single-source vulnerability in East Asian solid-state cell supply creates procurement bottlenecks for underground mining loader programs. Distribution runs through consolidated rental channel partnerships in European urban construction zones and direct OEM sales teams for Australian mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric off-highway equipment machinery sits in early-cycle expansion, with diesel phase-out regulatory deadlines across multiple jurisdictions guaranteeing replacement demand regardless of near-term commodity price turbulence.
For Market Incumbents: Entrench position through backward integration into solid-state battery cell supply and captive telematics platform development. Korean and Japanese battery specialists threaten margin capture upstream; defend by securing long-term offtake agreements with cathode material processors. Capacity addition in Changzhou-Xuzhou manufacturing corridors preserves cost competitiveness against state-subsidized Chinese producers. For New Entrants and Emerging Players: Establish a beachhead in India's infrastructure build-out segment where CEA grid integration standards create compliance barriers for established OEMs lacking localized certification experience. Target Maharashtra and Gujarat construction corridors with battery-electric excavator platforms pre-certified to BIS safety protocols. Go-to-market angle: project finance partnerships with domestic equipment lessors bypassing capital constraints that slow multinational direct sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European rental services consolidating municipal fleet procurement in German and Dutch urban zones. Long-term viability hinges on telematics-enabled service revenue streams displacing transactional equipment sales. Acquisition target archetype: regional fabricators with state-backed subsidy access in China and proven battery-thermal management IP. Signal to watch: automated battery swapping infrastructure deployment rates in remote Australian mining sites as fuel cell loader substitution threshold indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Supply Agreement | Long-term Korean cell offtake secures duty cycle extension for underground mining loaders. |
| Telematics Platform Integration | Predictive maintenance bundling with Volvo and Komatsu systems reshapes rental channel economics. |
| Green Leasing Structure Innovation | Project finance vehicles allow mid-tier contractors EPA compliance without balance sheet strain. |
| CEA Grid Integration Certification | First-mover compliance in Maharashtra construction corridors captures India infrastructure spend. |
| Digital Twin Validation Protocol | Virtual equipment testing compresses Australian mining procurement cycles from quarters to weeks. |
Research Methodology
A spread of perspectives from mining procurement directors, construction fleet managers, battery pack engineering leads, and rental channel operators converged on the working assumptions. Primary interviews with OEM product strategy heads and aftermarket service directors combined with secondary validation from SEC filings, MIIT electrification directives, EPA non-road engine standards, and Chilean mining disclosure regulations. Bottom-up equipment shipment data triangulated against top-down construction and mining capital expenditure forecasts.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include powertrain architecture, application intensity, end-user procurement structure, and regional regulatory cluster. CAGRs derived from replacement cycle compression rates and electrification mandate phase-in schedules. Industry-specific forecast inputs incorporated solid-state battery chemistry maturation curves and automated battery swapping infrastructure deployment timelines.
Sensitivities concentrate around lithium carbonate price volatility, East Asian cell supply disruption, and regulatory timeline acceleration or delay. Forecasts reflect documented assumptions on technology cost curves and substitution elasticity. Material shifts in Scope 3 disclosure enforcement stringency or solid-state battery commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Automotive Cross Member Market