
 China Automotive Heat Exchanger Market | 2026-2036
China Automotive Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Heat Exchanger Market Outlook
China is rewriting competitive dynamics in automotive thermal management through massive capacity additions across eastern manufacturing corridors. Hanon Systems Co Ltd leverages its Korean parent technology base to sustain premium OEM contracts in Shanghai and Beijing. Zhejiang Lurun Group Co Ltd anchors domestic supply chains with cost-optimized radiator production for local vehicle assemblers. Denso Corporation competes through integrated climate-system platforms that extend beyond discrete heat exchanger sales.
Automotive heat exchangers are thermal transfer devices typically constructed from aluminum alloy cores with brazed fin-and-tube architecture, engineered to regulate powertrain, cabin, and battery temperatures across operating conditions. Aluminum dominates material selection due to density advantages and compatibility with vacuum brazing processes that achieve leak rates below specified thresholds. Radiators occupy the largest product category by unit volume, reflecting continued internal combustion engine fleet density, while intercoolers represent the fastest-growing segment as turbocharged powertrains and battery thermal loops expand. Electric vehicle application demand reshapes margin pools, with OEMs and tier-1 suppliers capturing value through system-level thermal module integration rather than component supply alone.
MIIT enforces GB standards for vehicle energy consumption that directly constrain heat exchanger weight and thermal efficiency parameters. SAMR administers market access rules under which aluminum suppliers and brazing equipment providers must demonstrate compliance with national metallurgical specifications. The country's dual carbon goals from MEE impose lifecycle emissions accountability that propagates through automotive supply chains. Stakeholders must monitor how battery-electric platform thermal architectures diverge from legacy engine cooling topologies and whether domestic OEMs insource thermal module production or deepen tier-1 supplier partnerships.
Market Dynamics
MIIT fuel-efficiency mandates and dual carbon goals from MEE are compressing thermal management system weights while expanding aluminum heat exchanger specifications across domestic OEM platforms.
Growth Catalysts
- GB standards enforcement:MIIT energy consumption rules mandate lighter thermal components, accelerating aluminum radiator adoption in passenger vehicle platforms.
- Battery thermal loops:Electric vehicle powertrains require dedicated cooling circuits, expanding addressable component volume beyond legacy engine architectures.
- Jiangsu-Zhejiang supplier density:Tier-1 manufacturing clusters enable rapid prototype-to-production cycles for domestic vehicle assemblers.
Market Restraints
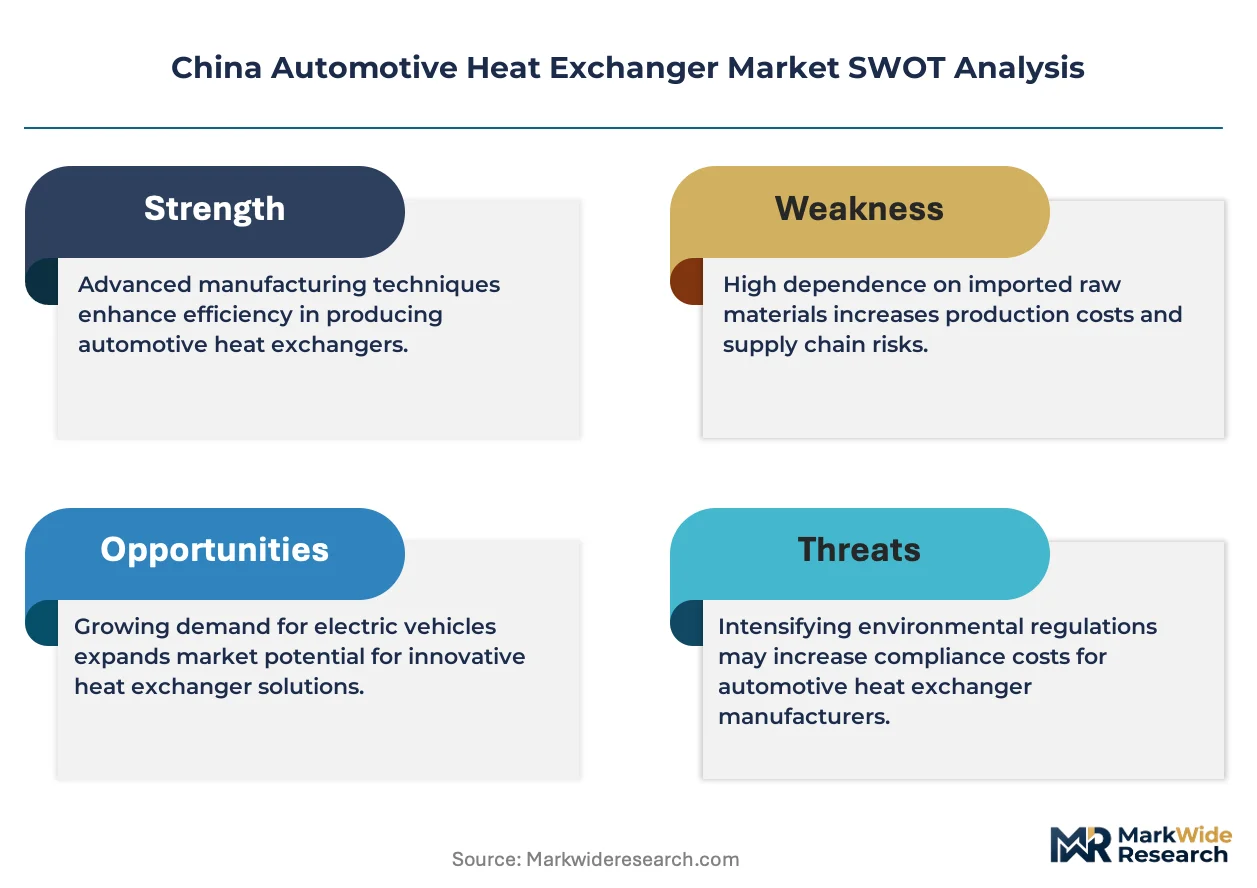
- Aluminum price volatility:Raw material cost swings compress margin pools for vacuum-brazed heat exchanger producers serving cost-sensitive domestic OEMs.
- Brazing equipment concentration:Vacuum furnace supply concentrates among German and Japanese equipment makers, creating capex bottlenecks for capacity expansion.
- Copper substitution threat:Some thermal module integrators specify copper-brass architectures for extreme-duty commercial vehicle applications.
Strategic Opportunities
- Thermal module integration:System-level climate platform contracts capture value beyond discrete heat exchanger supply to electric vehicle OEMs.
- SAMR metallurgical compliance:Certified aluminum suppliers gain preferential access to domestic OEM qualification programs under national material specifications.
- Western China logistics corridors:Inland manufacturing relocation creates localized thermal component demand from expanding vehicle assembly plants in Sichuan and Chongqing.
Industry Challenges
- Vacuum brazing technician scarcity:Specialized furnace operation and quality control skills command premium wages in eastern manufacturing corridors.
- GB standard recertification timelines:Updated MIIT energy consumption test cycles force thermal system redesign cycles that compress product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Heat Exchanger Market |
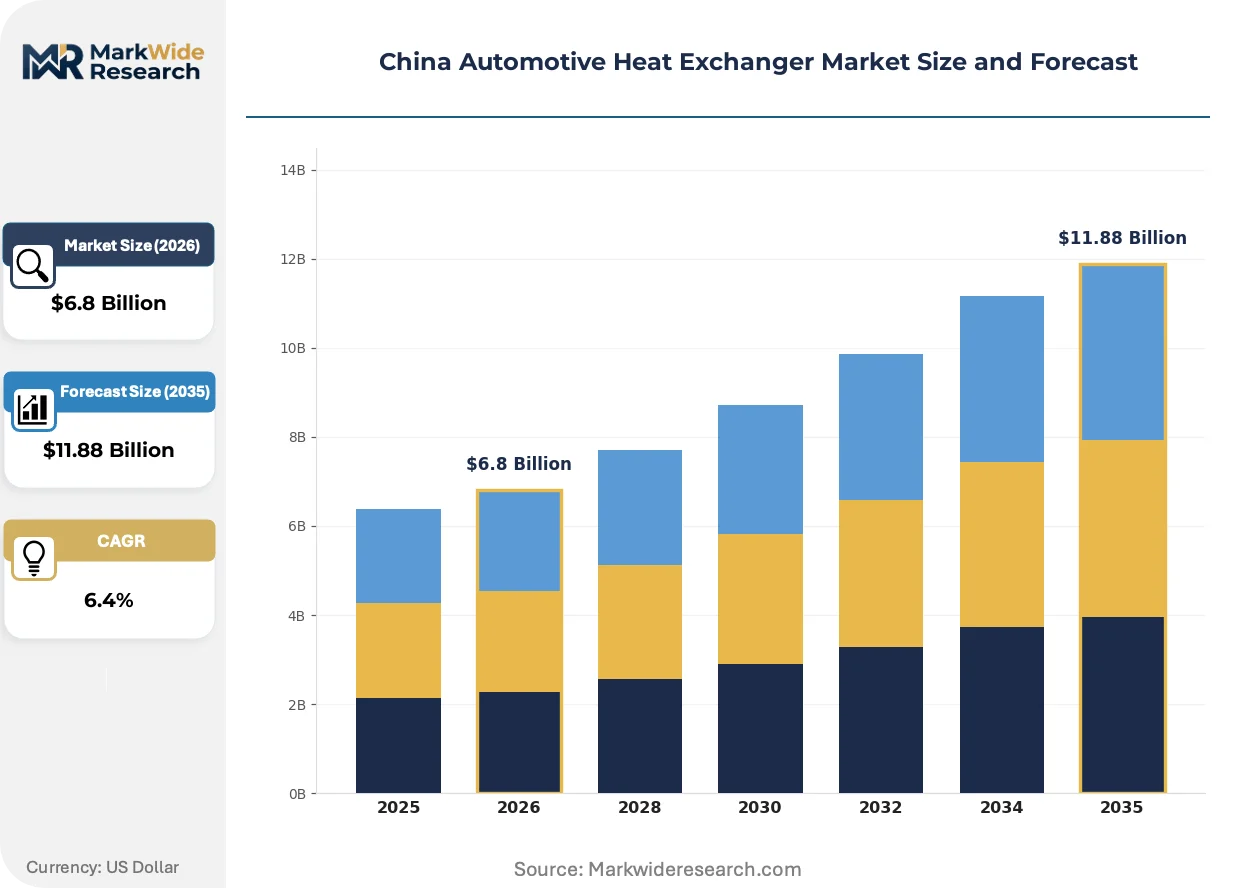
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiators, Condensers, Oil Coolers, Intercoolers Material: Aluminum, Copper, Plastic, Steel Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Electric Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Hanon Systems Co Ltd, Zhejiang Lurun Group Co Ltd, SANHUA Holding Group, Pierburg China Ltd, AKG Thermal Systems Co Ltd, JIANGSU JIAHE THERMAL SYSTEM RADIATOR CO LTD, Denso Corporation, Magneti Marelli Powertrain Co Ltd, MAHLE Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Heat Exchanger Market Strategic Shifts
Digital process control and predictive thermal modeling are compressing development cycles while enabling mass-customized heat exchanger architectures for heterogeneous electric vehicle platforms.
Microchannel aluminum tube technology is digitizing thermal design workflows. Domestic OEMs specify these architectures for battery cooling loops and cabin climate systems. The technology is digitizing how tier-1 suppliers simulate thermal performance, compressing prototype iterations from months to weeks.
Dual carbon goals from MEE propagate lifecycle emissions accountability through automotive supply chains. Aluminum suppliers must now document carbon intensity across mining, smelting, and brazing operations. Battery-electric platform thermal architectures face the strictest material provenance requirements.
Fleet operators and OEM procurement departments now unbundle after-sales thermal system service from initial component supply. Independent service networks in Guangdong and Shandong provinces capture replacement radiator and intercooler volume previously held by captive dealer channels.
China Automotive Heat Exchanger Market Segmentation
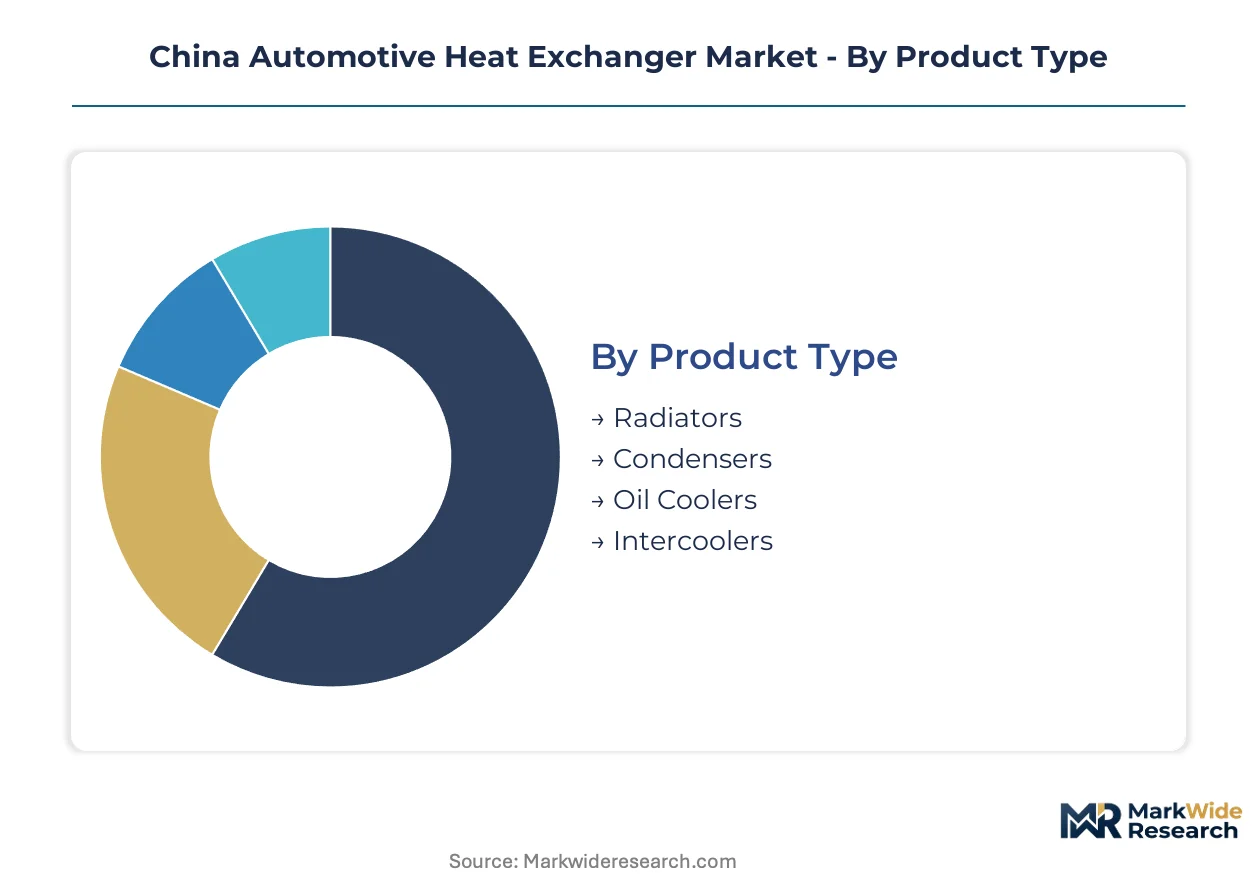
Segmentation in China's automotive heat exchanger market exposes divergent margin structures across thermal architectures. Product type and material selection determine brazing process requirements, while application mix tracks the country's vehicle fleet electrification trajectory.
Product Type:
Product type captures the functional specialization of thermal transfer devices across powertrain and cabin climate systems.
- Radiators:Aluminum-core brazed assemblies regulate internal combustion engine coolant temperatures through fin-and-tube architectures. Jiangsu and Zhejiang tier-1 clusters supply these units to domestic ICE-dominant OEM platforms under MIIT fuel-efficiency constraints.
- Intercoolers:Charge-air cooling modules reduce compressed air temperatures in turbocharged engines and battery thermal loops. Zhejiang Lurun Group and Hanon Systems manufacture these for expanding turbo-penetration rates and electric vehicle battery conditioning circuits.
- Condensers:Refrigerant-to-air heat exchangers enable cabin air conditioning across vehicle platforms.
- Oil Coolers:Lubricant temperature regulation modules serve high-performance engines and transmission systems.
Radiators hold installed capacity. Intercoolers are rotating up the share rankings.
Material:
Material selection stratifies by weight targets, thermal conductivity requirements, and brazing process compatibility.
- Aluminum:Vacuum-brazed aluminum alloys achieve density advantages under GB standards enforcement while meeting MIIT-mandated weight reduction targets for passenger vehicle platforms.
- Copper:Higher thermal conductivity suits extreme-duty commercial vehicle specifications where weight penalties are secondary to heat rejection capacity.
- Plastic:Polymer-based tank components and end tanks reduce assembly mass in cost-optimized radiator designs.
- Steel:Structural brackets and frame elements provide mechanical integrity in heavy-duty truck applications.
Aluminum dominates new platform specifications. Copper maintains defensive positions in commercial segments.
Application:
Application segmentation tracks vehicle platform thermal architecture divergence under China's dual carbon policy framework.
- Electric Vehicles:Battery thermal loops and power electronics cooling demand dedicated low-temperature circuits with microchannel aluminum architectures. Denso Corporation and domestic tier-1 suppliers capture system-level module contracts beyond discrete component supply.
- Passenger Vehicles:ICE-dominant platforms specify integrated radiator-condenser assemblies with weight-optimized aluminum cores from eastern manufacturing corridors.
- Commercial Vehicles:Fleet operators in Guangdong and Shandong provinces drive aftermarket replacement volume for radiators and intercoolers.
- Heavy-Duty Trucks:Severe-duty thermal loads sustain copper-brass specifications in select extreme-service applications.
Electric vehicle thermal modules command premium integration value. Passenger vehicle applications retain volume concentration.
End User:
End user segmentation reveals value capture points across captive production and outsourced supply relationships.
- OEMs:Domestic vehicle manufacturers including SAIC, BYD, and George directly procure thermal modules for flagship electric platforms, insourcing design integration while outsourcing component fabrication.
- Tier-1 Suppliers:Hanon Systems, Zhejiang Lurun Group, and Denso Corporation aggregate component supply into system-level climate platforms for multiple OEM customers.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations receive pre-integrated thermal modules from qualified supplier networks.
- Aftermarket Providers:Independent service networks in Guangdong and Shandong provinces capture replacement radiator and intercooler volume outside captive dealer channels.
Tier-1 suppliers hold manufacturing scale. OEM direct procurement is expanding for electric platform thermal modules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive heat exchanger consumption concentrates in eastern coastal provinces where electric vehicle assembly density diverges sharply from western regions still anchored to commercial vehicle replacement cycles.
Yangtze River Delta
Jiangsu and Zhejiang provinces host dense tier-1 supplier clusters serving SAIC and Geely electric platforms. MIIT fuel-efficiency mandates accelerate aluminum radiator specifications for passenger vehicle OEMs. Vacuum-brazing facilities in Suzhou and Ningbo achieve prototype-to-production cycles under eight weeks.
Pearl River Delta
Guangdong province drives aftermarket replacement volume through independent service networks in Guangzhou and Shenzhen. SAMR metallurgical compliance programs qualify aluminum suppliers for domestic OEM procurement. BYD's Shenzhen headquarters anchors battery thermal module demand for dedicated cooling circuits.
Beijing-Tianjin-Hebei
Capital region OEMs including BAIC procure system-level climate platforms rather than discrete components. MEE dual carbon goals impose lifecycle emissions documentation on aluminum supply chains. Tianjin port facilities handle imported vacuum furnace equipment from German and Japanese makers.
Sichuan-Chongqing
Western China logistics corridors create localized demand from expanding vehicle assembly plants in Chengdu and Chongqing. Domestic OEMs relocate thermal component sourcing inland to reduce logistics costs. Chongqing's automotive industrial park attracts radiator fabricators serving Chang'an and Ford joint ventures.
Shandong Peninsula
Heavy-duty truck manufacturing in Jinan and Qingdao sustains copper-brass specifications for extreme-service thermal loads. Fleet operators drive aftermarket radiator volume outside captive dealer channels. Shandong's metallurgical base supplies raw aluminum to eastern brazing facilities.
China Automotive Heat Exchanger Market Competitive Environment
Capability concentration sits with foreign-owned tier-1 suppliers possessing integrated climate-system platforms; scale advantage sits with domestic fabricators optimized for cost-sensitive radiator production. The vendor base stratifies across three tiers: premium system integrators, mid-market component specialists, and regional aftermarket suppliers. Two strategic archetypes dominate competitive positioning: technology licensors leveraging parent-company R&D and volume manufacturers capturing domestic OEM contracts. M&A activity concentrates among Korean and Japanese parents consolidating Chinese subsidiaries; capacity expansion focuses on microchannel tube lines for battery cooling applications.
Within the foreign-tier camp, Hanon Systems Co Ltd and Denso Corporation exemplify system-level platform providers. Among domestic fabricators, Zhejiang Lurun Group Co Ltd occupies a position as a cost-optimized radiator specialist serving local vehicle assemblers. These three companies represent the capability-scale spectrum: Korean-owned integrated climate systems, Japanese-owned technology platforms, and Chinese-owned volume manufacturing.
| Leading Market Players |
|---|
| Hanon Systems Co Ltd |
| Zhejiang Lurun Group Co Ltd |
| SANHUA Holding Group |
| Pierburg China Ltd |
| AKG Thermal Systems Co Ltd |
| JIANGSU JIAHE THERMAL SYSTEM RADIATOR CO LTD |
| Denso Corporation |
| Magneti Marelli Powertrain Co Ltd |
| MAHLE Group |
| Others |
Value Chain & Pricing Dynamics
German and Japanese vacuum furnace equipment concentration anchors margin capture at the brazing tier, while downstream OEM procurement shifts volume premiums toward system-integrated thermal module suppliers over discrete component vendors.
Pricing Analysis
Long-term offtake contracts dominate premium OEM relationships, with spot purchasing limited to aftermarket channels and project-based pricing emerging for battery platform thermal module development. Price differentiation hinges on SAMR metallurgical certification tier and geographic delivery cost to eastern manufacturing corridors. Cost compression in domestic OEM supply tiers is intensifying because aluminum price volatility feeds through vacuum-brazed component quotes. Fleet operators in Guangdong and Shandong provinces exhibit highest price sensitivity, while Beijing-Tianjin-Hebei OEMs prioritize system integration over unit cost.
Supply Chain Analysis
Tier-1 contract manufacturers in Jiangsu and Zhejiang provinces hold brazed aluminum core capacity, with secondary fabrication clustering in Sichuan-Chongqing logistics corridors. Raw material flows draw from Shandong Peninsula aluminum smelters, Japanese brazing alloy suppliers, and German vacuum furnace makers. Single-source vulnerability concentrates in imported brazing equipment, where German and Japanese OEMs control furnace supply. Distribution runs through qualified supplier networks directly to OEM platform engineering teams and tier-1 climate system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's automotive heat exchanger market is cycling through a recovery phase as electric vehicle platform volumes reset thermal component demand trajectories.
For Market Incumbents: Pre-empt copper substitution threats in commercial vehicle segments by securing SAMR-certified aluminum specifications for extreme-duty applications. Accelerate backward integration into microchannel tube extrusion capacity within Jiangsu-Zhejiang corridors to defend margin position against raw material volatility.
For New Entrants and Emerging Players: Establish a beachhead in western China logistics corridors where Sichuan-Chongqing vehicle assembly expansion outpaces localized thermal component supply. Target aftermarket service networks in Guangdong province through direct distributor relationships rather than captive OEM channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with Korean and Japanese parent companies consolidating Chinese thermal system subsidiaries. Long-term viability centers on battery-electric platform thermal architecture divergence from legacy cooling topologies. Monitor MIIT GB standard recertification timelines as inflection signals for product development cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Module Integration | Denso and Hanon capture system-level value beyond discrete heat exchanger supply to BYD and SAIC platforms. |
| Microchannel Tube Capacity Expansion | Zhejiang Lurun and domestic tier-1 suppliers add battery cooling-dedicated extrusion lines for electric vehicle thermal loops. |
| SAMR Metallurgical Certification Investment | Certified aluminum suppliers gain preferential access to SAIC and Geely qualification programs under national material specifications. |
| Western China Manufacturing Relocation | Radiator fabricators establish Chengdu and Chongqing facilities to serve Chang'an and Ford joint venture assembly plants. |
| Aftermarket Channel Diversification | Independent service networks in Guangdong and Shandong capture replacement radiator volume outside captive dealer channels. |
Study Parameters
Operator-level perspectives from tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and vacuum brazing equipment technicians anchored the qualitative base. Primary interviews combined with secondary validation from MIIT regulatory filings, SAMR market access databases, vehicle production registries, and aluminum trade flow records. Bottom-up component demand modeling and top-down thermal system value triangulation cross-verified segment outputs.
Scenario-bracketing framed volume projections across the analysis window, with segmentation modeled by propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to electric vehicle penetration trajectories and ICE fleet replacement cycles. Forecast inputs incorporated MIIT fuel-efficiency mandate compliance timelines and dual carbon goal material provenance requirements.
Stress conditions across aluminum price volatility, vacuum furnace import lead times, and GB standard recertification cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electric vehicle thermal architecture standardization and tier-1 supplier consolidation trajectories. Quarterly review of MIIT regulatory updates and OEM platform launch schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Torsion Bar Market