
 Railway Radiator Market | 2026-2036
Railway Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Radiator Market Analytics
India is narrowing its domestic manufacturing gap for railway thermal management components through targeted capacity additions in Gujarat and Tamil Nadu. Wabtec Corporation leverages its integrated brake and cooling platform to anchor North American freight contracts. Knorr-Bremse sustains European market presence through deep specialization in HVAC-integrated radiator modules. Bergstrom Inc. competes aggressively on compact form factors designed for constrained locomotive engine bays.
A railway radiator is a heat exchanger assembly engineered to maintain optimal operating temperatures for traction motors, diesel engines, or power electronics, typically constructed from aluminum fin-and-tube cores with copper or brass headers rated for pressures exceeding 3 bar and thermal loads above 200 kW. Its primary function is to dissipate waste heat generated during propulsion and auxiliary operations, preventing thermal derating and extending component service life. Aluminum material configurations now lead volume shipments due to their density advantage over steel alternatives, while high-speed train end-user applications represent the fastest-expanding demand pool as operators prioritize weight reduction for energy efficiency gains. Fixed installation systems retain the largest installed base, though modular designs are gaining traction in retrofit programs where downtime minimization commands premium pricing.
The EPA regulates locomotive emissions thresholds that indirectly tighten thermal management requirements, while the EU Green Deal's F-Gas Regulation pushes manufacturers toward lower-global-warming-potential coolants compatible with next-generation radiator designs. India's BIS certification mandates thermal performance testing for imported railway cooling equipment, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor how evolving carbon-border adjustment mechanisms reshape sourcing economics for aluminum and copper feedstocks before committing to long-term capacity investments.
Market Dynamics
The EU Green Deal's F-Gas Regulation is forcing railway thermal management suppliers to redesign coolant compatibility specifications across their aluminum radiator portfolios, compressing development cycles while elevating material testing costs.
Growth Catalysts
- High-speed rail electrification in China:The country's expanding network of 350 km/h corridors demands lightweight aluminum cooling systems that reduce energy consumption per passenger-kilometer. Domestic procurement quotas favor local radiator manufacturers with certified thermal performance ratings.
- REACH compliance retrofit mandates:European freight operators must replace legacy copper-brass radiators containing restricted substances, creating replacement demand for compliant aluminum fin-and-tube assemblies. The regulation's substance restrictions apply to coolant seals and header gaskets.
- Power electronics thermal loads:Traction inverters in next-generation locomotives generate waste heat exceeding 300 kW, requiring advanced radiator cores with enhanced fin density. Silicon carbide switching devices intensify cooling requirements beyond conventional diesel engine specifications.
Market Restraints
- Aluminum ingot price volatility:LME aluminum fluctuations above fifteen percent annually compress radiator fabricator margins, particularly for fixed-price maintenance contracts. Smaller suppliers in India and Southeast Asia lack hedging instruments to buffer input cost spikes.
- Copper supply concentration:Header and tube manufacturing depends on Chilean and Peruvian copper concentrate, exposing radiator producers to export quota disruptions. Alternative brass formulations from scrap recycling remain inconsistent for pressure-rated railway applications.
- Welding automation limits:Aluminum fin-to-tube brazing requires vacuum furnace investments exceeding ten million dollars, constraining entry by regional fabricators. Manual welding techniques fail to meet pressure cycle fatigue standards for high-speed train specifications.
Strategic Opportunities
- Indian PLI scheme localization:Production-linked incentives for railway component manufacturing attract radiator assembly investments in Gujarat and Tamil Nadu. The scheme covers capital expenditure for testing facilities and thermal validation equipment.
- HVAC-integrated thermal modules:Convergence of traction motor cooling with passenger climate control systems enables single-supplier contracts for integrated thermal management. European operators prioritize packaged solutions reducing interface complexity.
- Remanufacturing service channels:Direct-to-operator radiator refurbishment programs bypass traditional distributor networks, capturing aftermarket value. German freight operators pilot core exchange models minimizing locomotive downtime.
Industry Challenges
- Pressure vessel certification timelines:TÜV and DEKRA testing protocols for 5-bar rated aluminum headers extend eighteen to twenty-four months, delaying product launches. Parallel certification requirements across multiple European notified bodies fragment validation resources.
- Legacy locomotive interface standards:Retrofit radiator designs must accommodate fifty-year-old mounting geometries and coolant port configurations without structural modifications. Engineering teams reconcile modern thermal performance with obsolete mechanical interfaces.
- Skilled brazing technician scarcity:Vacuum furnace operation and fluxless brazing quality control require specialized training unavailable in emerging manufacturing clusters. Workforce development lags behind capacity expansion schedules in India and Southeast Asia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Radiator Market |
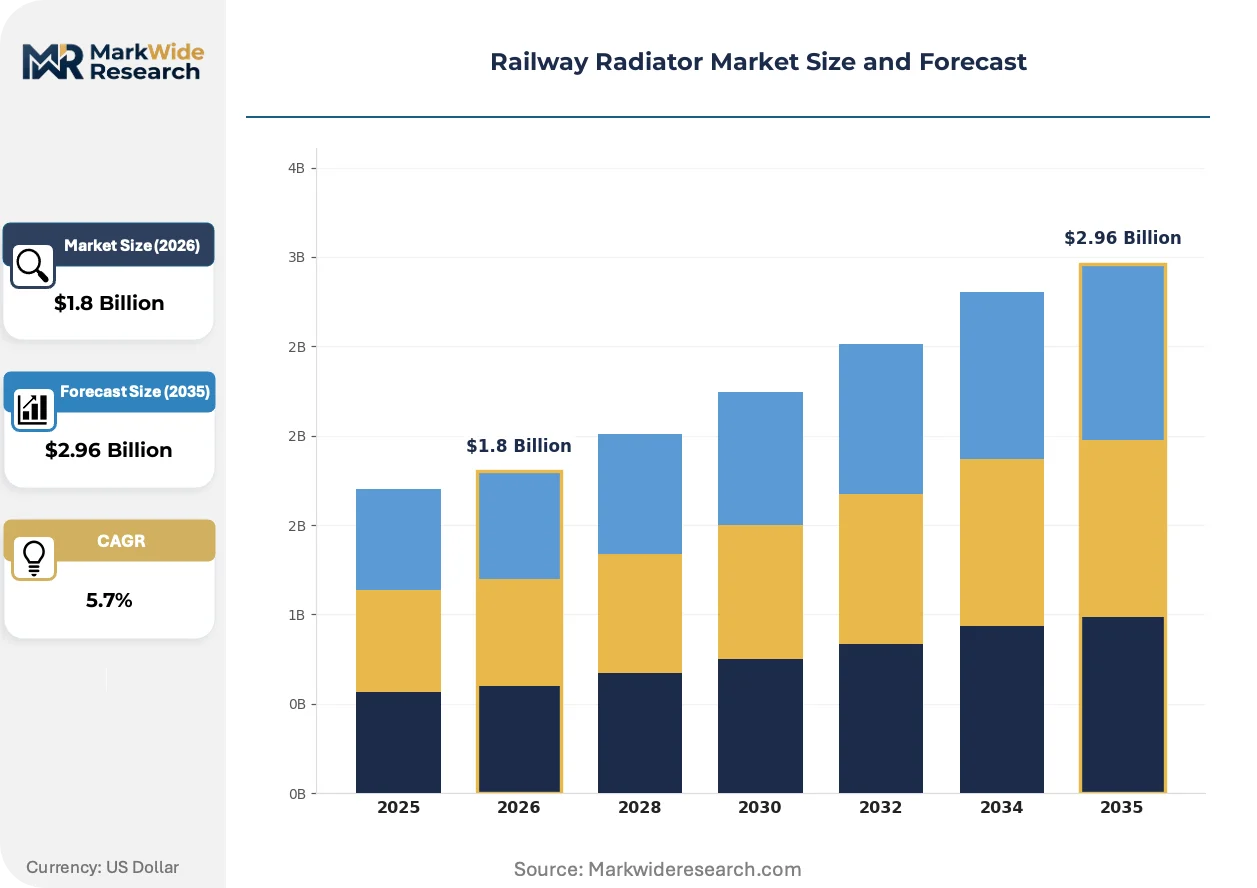
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
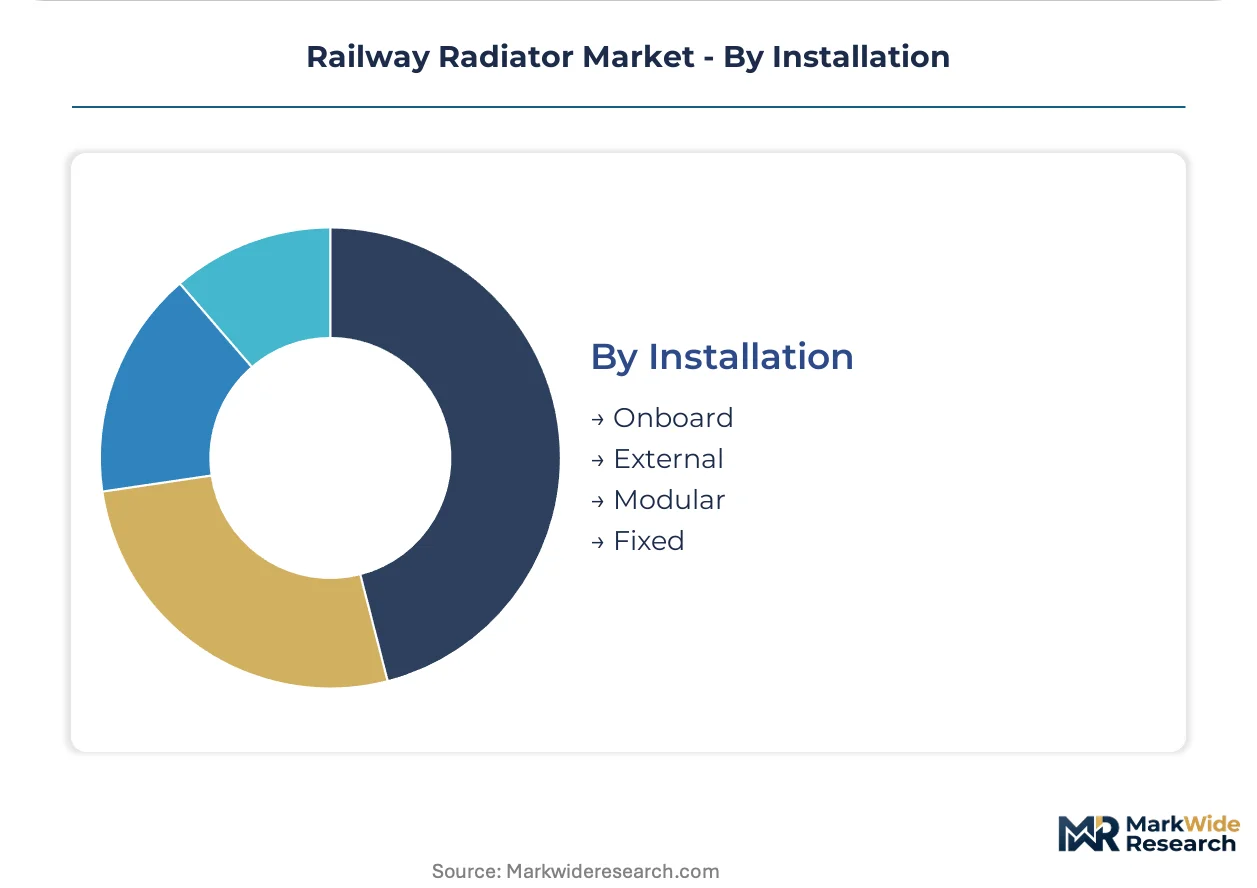
| Segmentation | Type: Conventional, Electric, Hybrid, Diesel Material: Aluminum, Steel, Copper, Plastic End User: Passenger Trains, Freight Trains, High-Speed Trains, Locomotives Installation: Onboard, External, Modular, Fixed |
| Companies Covered | Wabtec Corporation, Knorr-Bremse, Bergstrom Inc., Valeo SA, Alfa Laval, Trane Technologies, Danfoss, ZIEHL-ABEGG Inc., Horton Holding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Radiator Market Evolving Landscape
Additive manufacturing of aluminum heat exchanger manifolds is collapsing traditional sand-casting lead times while enabling topology-optimized coolant flow geometries previously impossible with conventional fabrication methods.
Microchannel aluminum tubing is collapsing the thermal performance gap between copper and aluminum radiator cores, enabling weight reductions exceeding twenty percent without sacrificing heat rejection capacity. Japanese high-speed rail operators have adopted microchannel designs for their N700S series traction cooling systems. The technology is collapsing premium pricing for copper-based alternatives in premium locomotive segments.
The EPA's locomotive emissions standards are tightening indirect thermal management requirements by elevating engine operating temperatures to optimize combustion efficiency. Rail operators must upgrade radiator capacity to handle elevated coolant temperatures without derating. US Class I freight railroads are responding with specification changes for next-generation diesel-electric locomotive cooling packages.
Chinese state rail procurement is consolidating supplier qualification around integrated thermal-electric platform vendors rather than standalone radiator manufacturers. The procurement model compresses vendor lists from dozens to single-digit approved suppliers per region. This concentration is most visible in CRRC's centralized tendering for 350 km/h trainset thermal systems.
Railway Radiator Market Segmentation
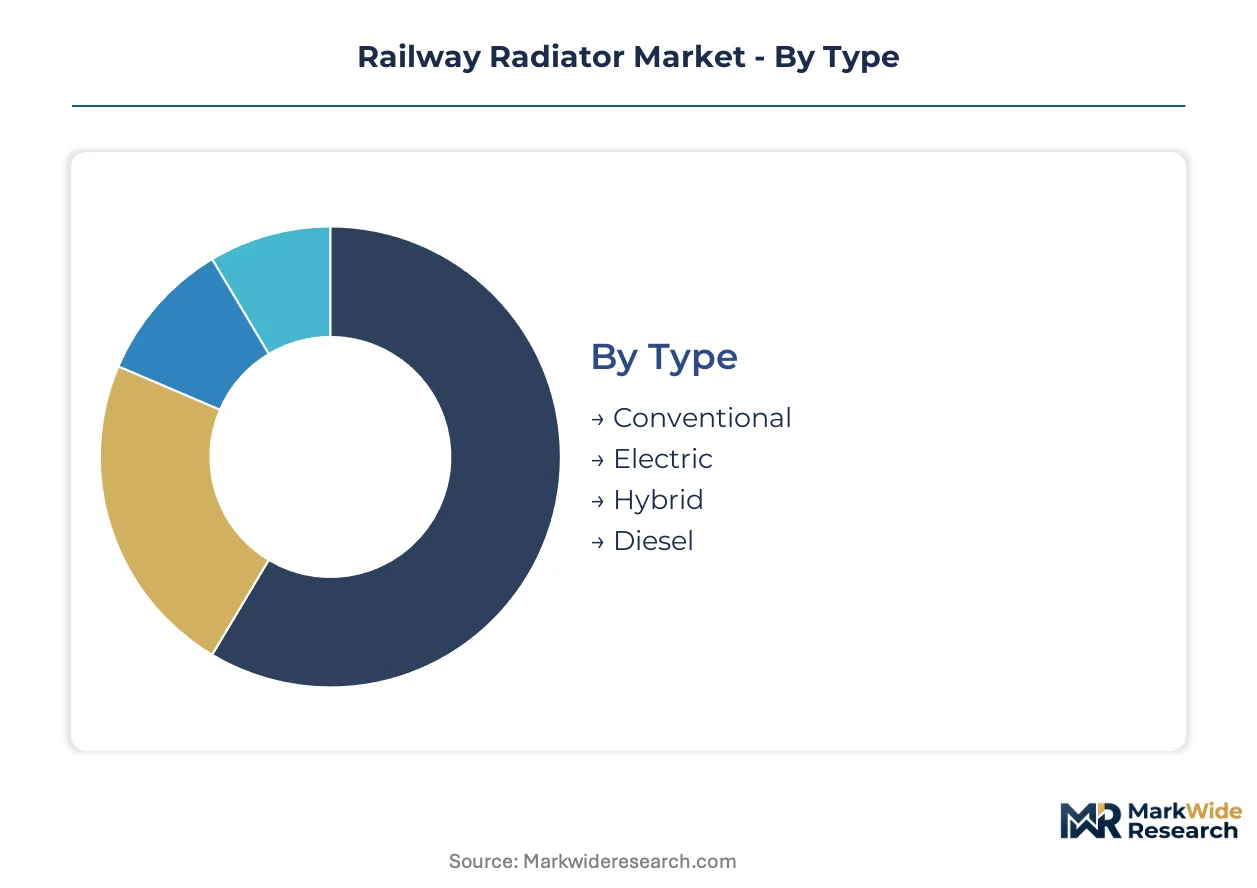
Railway radiator segmentation reveals distinct aftermarket service profiles across propulsion architectures and material systems. Procurement patterns diverge sharply between high-speed train operators prioritizing lightweight thermal solutions and freight railroads optimizing for repair-cycle durability.
Type:
After-sales service intensity varies dramatically by propulsion type, with electric and hybrid systems demanding specialized diagnostic capabilities that conventional diesel cooling architectures rarely require.
- Conventional:Copper-brass fin-and-tube cores dominate legacy diesel-electric locomotive cooling packages. North American Class I freight railroads concentrate procurement here, driven by EPA Tier 4 emissions compliance retrofit cycles and extended locomotive lifecycles exceeding thirty years.
- Electric:Power electronics cooling modules with microchannel aluminum cores manage traction inverter thermal loads above 300 kW. China's expanding 350 km/h network concentrates demand, propelled by state procurement quotas favoring domestic thermal management suppliers with certified pressure-cycle performance.
- Hybrid:Dual-circuit designs accommodate both diesel engine and battery thermal management in a single envelope. European regional operators pilot these configurations under EU Green Deal electrification timelines.
- Diesel:Standalone engine radiators with enhanced fin density address elevated combustion temperatures from emissions-optimized engine calibrations. Indian freight corridors represent concentrated demand, shaped by Dedicated Freight Corridor Corporation fleet expansion.
By volume, Conventional leads. By growth pace, Electric is ahead.
Material:
Material selection directly governs warranty exposure and field service frequency, with aluminum systems commanding premium service contracts due to brazing complexity.
- Aluminum:Vacuum-brazed fin-and-tube cores with density advantages exceeding twenty percent over steel alternatives. Japanese Shinkansen N700S series and Chinese CRRC 350 km/h trainsets anchor demand, pressured by energy efficiency mandates requiring weight reduction per passenger-kilometer.
- Steel:Welded tubular construction persists in heavy-haul freight applications where impact resistance outweighs mass considerations. Russian and South African mining railroads concentrate procurement, constrained by limited aluminum brazing infrastructure in their supplier bases.
- Copper:Brass headers with copper tubes deliver superior thermal conductivity for high-pressure locomotive engine cooling. REACH substance restrictions are accelerating replacement demand in European retrofit programs.
- Plastic:Polyamide header tanks and end caps reduce galvanic corrosion in mixed-metal assemblies. Emerging adoption in regional passenger multiple units focuses on cost-sensitive procurement.
Aluminum captures the dominant revenue share. Copper retreats fastest from new-build specifications.
End User:
End-user thermal load profiles determine radiator core sizing and coolant flow architecture, with high-speed applications imposing the most severe pressure-cycle fatigue requirements.
- Passenger Trains:HVAC-integrated thermal modules combine traction motor cooling with cabin climate control. European operators Deutsche Bahn and SNCF prioritize packaged solutions reducing supplier interface complexity.
- Freight Trains:Heavy-duty engine radiators rated for 5-bar header pressure and extended maintenance intervals. Union Pacific and BNSF specification changes under EPA locomotive emissions standards are reshaping cooling capacity requirements.
- High-Speed Trains:Compact aluminum microchannel cores with enhanced fin density for 300+ kW heat rejection. China's state rail procurement consolidation around integrated thermal-electric platform vendors is compressing approved supplier lists.
- Locomotives:Modular retrofit designs accommodating fifty-year-old mounting geometries without structural modification. German freight operators pilot core exchange remanufacturing programs minimizing downtime.
Freight Trains dominate installed base. High-Speed Trains expand most quickly.
Installation:
Installation architecture governs field service economics, with modular systems enabling revenue capture through direct-to-operator refurbishment channels.
- Onboard:Integrated cooling packages within locomotive engine compartments requiring compact form factors. Bergstrom Inc. competes aggressively here with space-constrained designs for constrained bays.
- External:Roof-mounted or underframe radiators on passenger coaches with separate HVAC integration points. Indian Railways ICF coaches represent volume concentration.
- Modular:Quick-exchange core assemblies minimizing locomotive downtime through standardized interface geometries. German freight operator pilot programs validate core exchange business models.
- Fixed:Permanent welded installations with longest service intervals but highest replacement labor costs. Legacy North American freight locomotives retain this architecture.
Fixed installation retains the largest installed base. Modular designs gain share fastest in retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum radiator fabrication concentrates in manufacturing clusters with established vacuum-brazing infrastructure and proximity to rail OEM assembly plants. China's CRRC supply chain dominates high-speed train thermal system procurement. European REACH compliance mandates and India's PLI localization incentives are reshaping regional competitive positioning.
China
State rail procurement for 350 km/h trainsets drives demand for microchannel aluminum cooling systems with certified pressure-cycle performance. MIIT domestic content requirements favor local thermal management suppliers with integrated platform capabilities. CRRC's Qingdao and Changchun manufacturing clusters anchor radiator assembly for export and domestic high-speed corridors.
United States
EPA locomotive emissions standards tighten thermal management specifications for Class I freight railroads upgrading diesel-electric cooling packages. Tier 4 compliance retrofits concentrate procurement among integrated brake-and-cooling platform vendors. Wabtec's Pennsylvania operations and supplier networks across the Midwest serve Union Pacific and BNSF specification changes.
Germany
EU Green Deal F-Gas Regulation forces coolant compatibility redesigns across aluminum radiator portfolios. DEKRA and TÜV pressure vessel certification timelines extend eighteen to twenty-four months for 5-bar rated headers. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host HVAC-integrated thermal module specialists serving Deutsche Bahn.
India
Dedicated Freight Corridor Corporation fleet expansion generates demand for heavy-duty engine radiators rated for tropical operating conditions. BIS certification mandates thermal performance testing for imported cooling equipment. PLI scheme incentives attract radiator assembly investments to Gujarat and Tamil Nadu manufacturing corridors with testing facility coverage.
Japan
Shinkansen N700S series adoption of microchannel aluminum cores validates weight reduction architectures for 300+ kW heat rejection. METI energy efficiency mandates pressure thermal system designs per passenger-kilometer. Kawasaki and Nagoya industrial clusters concentrate precision brazing capacity for domestic and export high-speed train programs.
Railway Radiator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base stratifies between integrated thermal-electric platform vendors approved for Chinese state procurement and standalone radiator fabricators serving aftermarket retrofit cycles. Three archetypes dominate: diversified industrial conglomerates with rail divisions, pure-play thermal management specialists, and automotive crossover suppliers leveraging scale. Competitive moves concentrate on strategic partnerships for HVAC-integrated modules and capacity expansion in India under PLI coverage.
Among diversified industrial players, Wabtec Corporation and Knorr-Bremse occupy positions anchoring North American and European procurement respectively. Bergstrom Inc. exemplifies the compact-form-factor specialist archetype competing for constrained locomotive engine bay applications. These three represent distinct strategic postures: integrated platform breadth, deep HVAC-radiator convergence, and space-optimized mechanical design.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Knorr-Bremse |
| Bergstrom Inc. |
| Valeo SA |
| Alfa Laval |
| Trane Technologies |
| Danfoss |
| ZIEHL-ABEGG Inc. |
| Horton Holding Inc. |
| Others |
Value Network & Pricing Analysis
Changchun's vacuum-brazing corridor concentrates aluminum radiator fabrication capacity for CRRC's 350 km/h procurement, translating upstream metallurgical expertise into pricing power over domestic and export contracts. LME aluminum volatility and Chilean copper concentrate exposure feed directly into fabricator margin structures, compressing returns on fixed-price maintenance agreements.
Pricing Analysis
EU Green Deal F-Gas Regulation dictates the pricing tier structure across aluminum radiator portfolios, forcing coolant compatibility redesigns that elevate material testing costs and extend development cycles. Three-tier pricing structure across premium, standard, and economy levels separates HVAC-integrated platform vendors from standalone fabricators and regional aftermarket suppliers. Cost compression in standard-tier brazed assemblies is intensifying because smaller Indian and Southeast Asian fabricators lack hedging instruments against aluminum ingot spikes. Freight railroads in North America exhibit highest price sensitivity due to extended locomotive lifecycles and retrofit budget constraints, while high-speed train operators in China prioritize certified thermal performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and Western procurement jurisdictions dominates supply chain risk planning for aluminum radiator manufacturers serving export markets. Vacuum-brazing capacity concentrates in China, Japan, and Germany, with emerging clusters in Gujarat and Tamil Nadu drawing from PLI scheme incentives. Raw material dependencies rest on Chilean and Peruvian copper concentrate for brass headers, LME-traded aluminum ingot for fin-and-tube cores, and specialized flux materials for fluxless brazing processes. Single-source vulnerability around vacuum furnace equipment manufacturers constrains regional fabricator entry. Distribution runs through CRRC's centralized tendering system for Chinese state rail, integrated brake-and-cooling platform vendors for North American freight, and direct-to-operator remanufacturing channels for European retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railway radiator market functions as a defensive-moat industry where regulatory certification timelines and vacuum-brazing capital requirements create entrenched switching costs that protect incumbent positions.
For Market Incumbents: Insulate core positions by deepening backward integration into aluminum ingot sourcing and captive brazing flux production, neutralizing margin pressure from LME volatility. Prioritize certification investment for 5-bar pressure vessel ratings across TÜV and DEKRA protocols to extend lead times that deter emerging competitors. Counter the threat of Chinese state procurement consolidation by anchoring integrated thermal-electric platform capabilities rather than standalone radiator supply. For New Entrants and Emerging Players: Indian PLI scheme corridors in Gujarat and Tamil Nadu represent the most penetrable entry point for radiator assembly investments, given capital expenditure coverage for thermal validation equipment. European REACH compliance retrofit cycles for copper-brass replacement create aftermarket white space where specialized brazing quality control can differentiate against incumbents burdened by legacy cost structures. Pursue direct-to-operator remanufacturing service channels as the primary go-to-market angle, bypassing distributor networks that incumbents dominate. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because eighteen-to-twenty-four-month certification timelines and ten-million-dollar vacuum furnace thresholds structurally limit competitive entry. Target acquisition candidates among HVAC-integrated thermal module specialists with existing Deutsche Bahn or SNCF supplier status, as European rail operators prioritize packaged solutions reducing interface complexity. Monitor aluminum-copper price ratio movements as the critical inflection signal for margin compression severity across the fabricator tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Ingot Sourcing | Captive supply of LME-linked feedstock buffers margin volatility for high-volume fabricators serving fixed-price contracts. |
| HVAC-Integrated Thermal Module Development | Single-supplier positioning with Deutsche Bahn and SNCF captures convergence of traction motor and passenger climate cooling. |
| Remanufacturing Service Channel Establishment | Direct-to-operator core exchange models minimize German freight locomotive downtime while bypassing traditional distributor networks. |
| PLI-Aligned Capacity Expansion in India | Gujarat and Tamil Nadu assembly investments leverage production-linked incentives covering thermal validation equipment capex. |
| Microchannel Aluminum Core Certification | Pressure-cycle validation for 300+ kW heat rejection opens Chinese CRRC 350 km/h procurement and Japanese Shinkansen programs. |
Research Methodology
Desk research of customs trade databases, SEC filings from listed rail equipment suppliers, and CRRC tender documentation preceded structured interviews with thermal management engineering directors, procurement leads at Class I freight railroads, vacuum furnace equipment specialists, and aftermarket service managers. Primary fieldwork covered aluminum radiator fabricators in China, India, Germany, and Japan, validated against secondary sources including EPA locomotive emissions guidance, EU F-Gas Regulation implementation notices, and BIS certification protocols. Bottom-up segment sizing across propulsion type, material system, and end-user application was triangulated with top-down market value reconstruction.
Forecast assumptions held fixed the current regulatory trajectory for EPA Tier 4 compliance, EU Green Deal thermal efficiency mandates, and MIIT domestic content requirements, while varying aluminum-copper price ratio scenarios and high-speed rail electrification pace across the projection horizon. Segmentation modeling incorporated propulsion architecture, material configuration, end-user thermal load profile, and installation architecture as core dimensions. CAGRs were derived from installed base replacement cycles, new-build procurement schedules, and retrofit penetration curves. Industry-specific inputs included traction inverter thermal load specifications for silicon carbide switching devices and pressure-cycle fatigue testing protocols for 5-bar rated headers.
Macroeconomic conditions sit as an overlay; deviation in LME aluminum pricing, Chilean copper concentrate export quotas, or freight railroad capital expenditure budgets would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and certification body capacity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Control Stands Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Point Machine Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Digital Railway Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Railway Couplers Market