
 Automotive Tie Rod Assembly Market | 2026-2036
Automotive Tie Rod Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tie Rod Assembly Market Analysis
Commercial vehicle electrification is hardening demand for precision-engineered steering linkages capable of handling higher axle loads without proportional weight gain. ZF Friedrichshafen AG leverages its integrated chassis systems portfolio to supply modular tie rod solutions across European and North American OEM programs. Nexteer Automotive Corporation anchors its position through advanced manufacturing scale in electrically powered steering architectures. GKN Automotive Limited differentiates via constant-velocity joint integration that reduces assembly points and warranty exposure.
An automotive tie rod assembly comprises an inner and outer rod connected by an adjustable sleeve, transmitting steering force from the rack or gearbox to the steering knuckle while permitting toe angle calibration; typical specifications include hardened alloy steel construction with yield strengths exceeding 600 MPa, threaded M14-M16 connections, and elastomer boot sealing rated for salt spray cycles exceeding 500 hours per ISO 9227. Steel material segments dominate current volume owing to established forging infrastructure and OEM cost discipline, though aluminum and composite alternatives are gaining structural share where unsprung mass reduction directly extends electric vehicle range. The OEM end-user channel commands the largest value pool due to specification lock-in during platform development, while aftermarket providers compete on logistics density and same-day availability.
NHTSA FMVSS 126 stability control mandates and EPA Corporate Average Fuel Economy standards collectively shape tie rod durability requirements and lightweighting incentives in the United States, while ECE R79 steering equipment regulations govern European type approval and testing protocols. ISO 26262 functional safety classifications increasingly influence design verification for steer-by-wire precursor architectures. Stakeholders must monitor regulatory convergence between UN ECE and NHTSA test methodologies, as divergence in corrosion and fatigue validation cycles threatens to fragment supplier qualification costs across Atlantic and Pacific supply corridors.
Market Dynamics
Commercial vehicle electrification is hardening demand for precision-engineered steering linkages capable of handling higher axle loads without proportional weight gain, forcing material science and forging investments toward aluminum and composite architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Lightweighting mandates accelerate aluminum tie rod adoption in electric vehicle platforms where unsprung mass reduction directly extends range.
- Germany:OEM production volumes anchor European demand for modular chassis systems with integrated steering linkages specified during platform development.
- Steer-by-wire architectures:ISO 26262 functional safety classifications drive design verification investments for next-generation steering systems.
Market Restraints
- Aluminum price volatility:Raw material cost swings compress margin structures for suppliers transitioning from established steel forging infrastructure.
- Supplier concentration in China:Forging capacity geographic clustering creates exposure to trade corridor disruptions and qualification timeline extensions.
- ECE R79 testing divergence:European steering equipment regulations impose validation cycles that fragment supplier qualification costs across Atlantic supply corridors.
Strategic Opportunities
- India aftermarket density:Logistics network expansion targets same-day availability for replacement tie rod assemblies in high-vehicle-parc urban corridors.
- Recyclable aluminum alloys:EU Green Deal circular economy frameworks incentivize closed-loop material recovery in chassis component manufacturing.
- Additive manufacturing convergence:Topology optimization software combined with powder bed fusion enables complex sleeve geometries unachievable through conventional forging.
Industry Challenges
- Fatigue testing talent scarcity:Specialized engineers capable of correlating ISO 9227 salt spray cycles with road-load durability data command premium compensation.
- Dual certification timelines:NHTSA FMVSS 126 and UN ECE test methodology divergence forces parallel validation tracks for transatlantic OEM programs.
- Legacy rack-and-pinion integration:Electrified steering architectures must maintain mechanical backup compatibility during multi-year platform transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tie Rod Assembly Market |
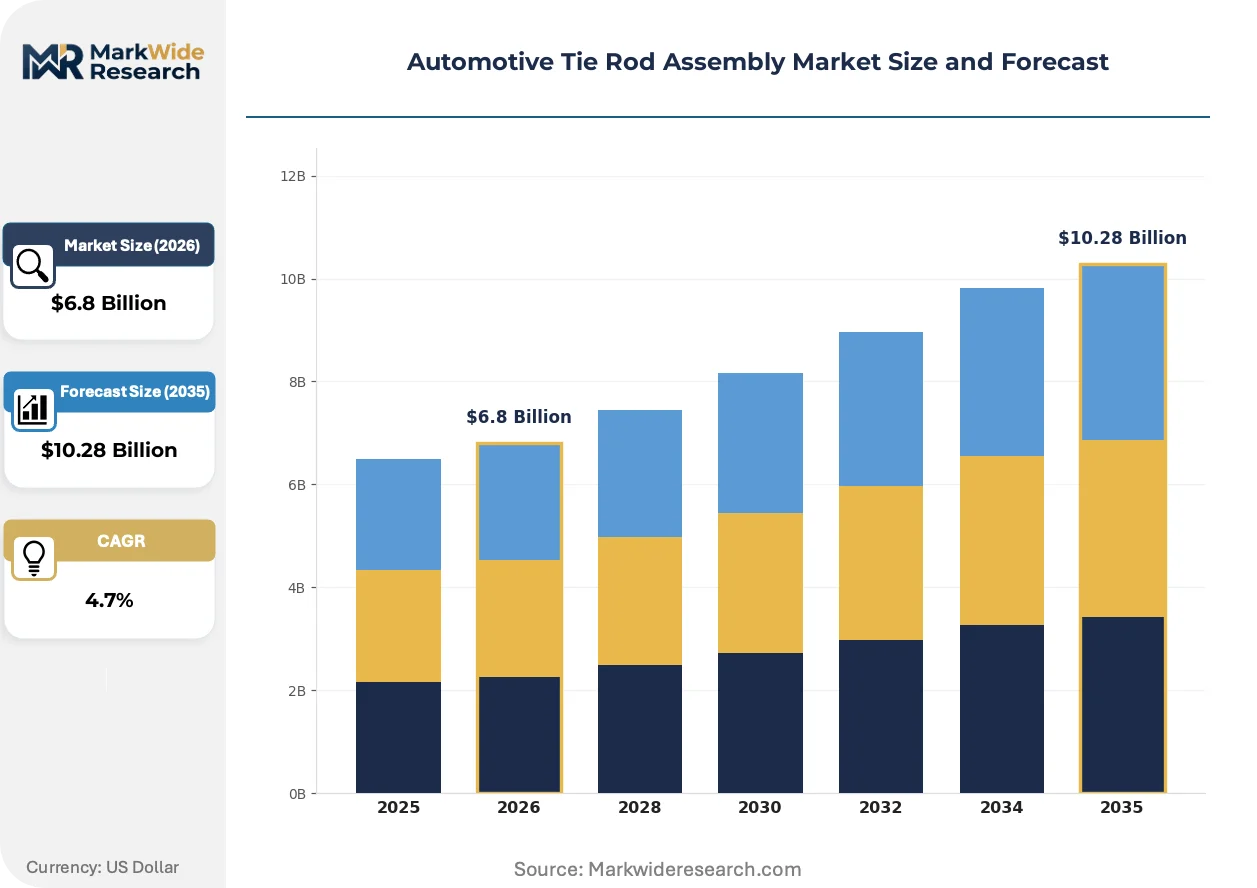
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Male Tie Rod, Female Tie Rod, Adjustable Tie Rod, Non-Adjustable Tie Rod Material: Steel, Aluminum, Composite, Rubber End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Installation Type: Direct Replacement, Upgraded Assembly, Custom Fit, Aftermarket |
| Companies Covered | ZF Friedrichshafen AG, Nexteer Automotive Corporation, GKN Automotive Limited, Ample Auto Tech Pvt. Ltd., G.S. Autocomp Pvt. Ltd., FAI Automotive, Moog Inc., Teknorot, Powers & Sons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tie Rod Assembly Market Emerging Trajectories
Material substitution and regulatory convergence are compressing traditional design cycles while procurement patterns favor integrated chassis module suppliers over discrete component vendors.
Carbon fiber-reinforced polymer tie rods are integrating into premium electric vehicle platforms where unsprung mass reduction targets exceed 40 percent versus steel baselines. Luxury OEMs specify these assemblies for front-axle applications where steering precision and range extension justify unit cost premiums. The technology is integrating constant-velocity joint geometries previously requiring separate forging operations, collapsing assembly point counts and warranty exposure.
NHTSA FMVSS 126 stability control mandates tighten lateral force transmission tolerances for steering linkages in commercial vehicles above 10,000 pounds gross vehicle weight rating. Test protocols now require validated performance across degraded friction surfaces, forcing recalibration of elastomer boot sealing specifications. Heavy-duty truck manufacturers in the United States are responding with hardened alloy steel grades exceeding 800 MPa yield strength for inner rod applications.
Fleet operators now specify outcome-based lifecycle cost contracts for steering components, displacing traditional unit-price procurement in long-haul trucking segments. Third-party logistics providers aggregate demand across regional carrier networks, consolidating specification authority previously dispersed among individual maintenance facilities. This pattern concentrates most visibly in Germany's autobahn freight corridors where uptime guarantees dominate total cost of ownership calculations.
Automotive Tie Rod Assembly Market Segmentation
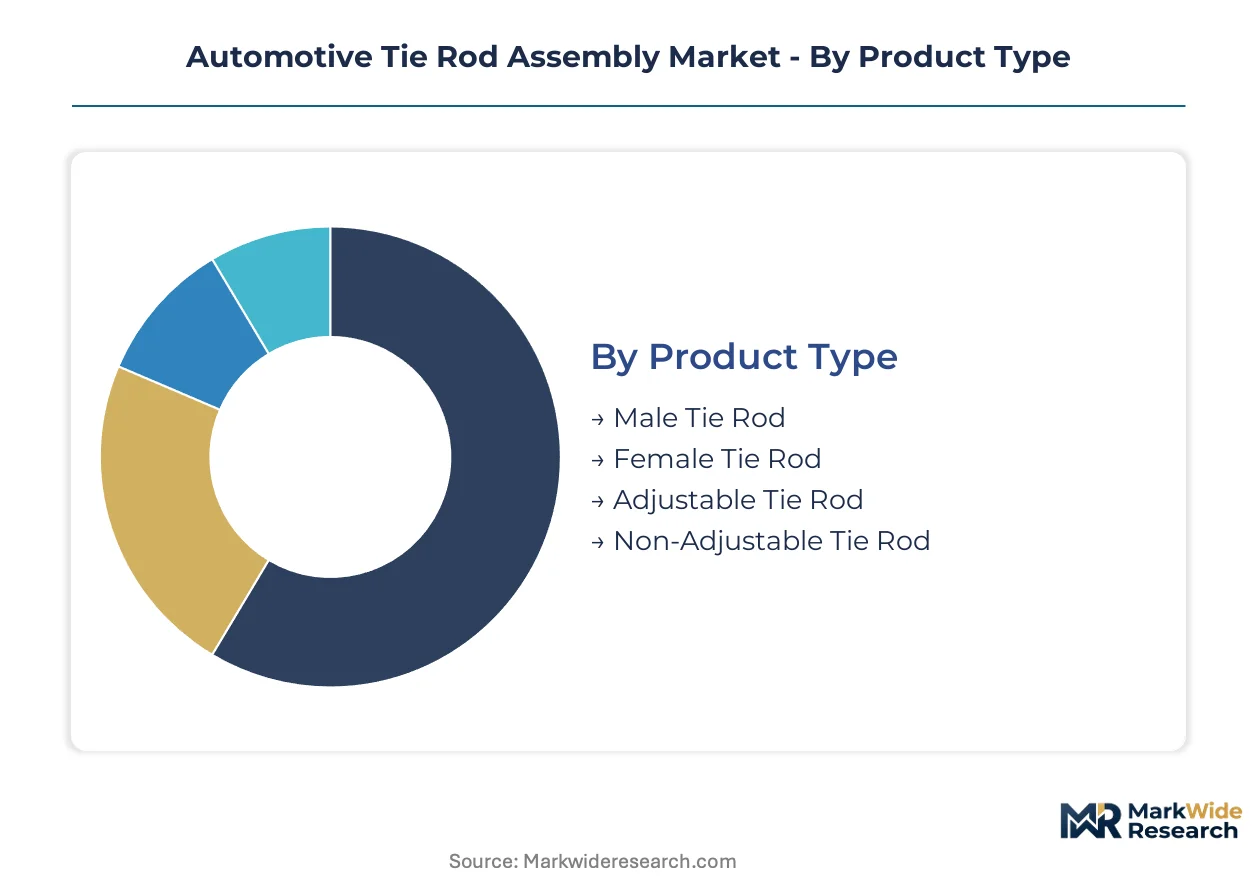
Segmentation in tie rod assembly markets reveals how specification authority, material substitution economics, and channel control reshape procurement patterns across vehicle platforms. Buyers differentiate sharply between locked-in OEM platform specifications and aftermarket logistics-driven replacement cycles.
Product Type:
Cost tier separates platform-integrated buyers from maintenance-driven purchasers.
- Male Tie Rod:Features external threading for direct knuckle attachment with hardened alloy steel construction rated above 600 MPa yield strength. Demand concentrates in German and Japanese OEM programs where precision steering geometry specifications lock suppliers into multi-year platform contracts.
- Adjustable Tie Rod:Incorporates threaded sleeve mechanisms permitting toe angle calibration across suspension travel ranges. Fleet operators in United States long-haul corridors specify these for commercial vehicles where alignment maintenance intervals directly impact tire wear costs and uptime guarantees.
- Female Tie Rod:Receives male rod insertion with internal threading for rack-end connection.
- Non-Adjustable Tie Rod:Fixed-length construction specified for sealed steering systems with factory-set geometry.
Volume sits with Male Tie Rods; growth tilts toward Adjustable Tie Rods.
Material:
Application severity and unsprung mass targets drive material selection divergence between durability-critical and range-optimized platforms.
- Steel:Dominant forged construction utilizing hardened alloy grades with established fatigue testing protocols per ISO 9227 salt spray cycles exceeding 500 hours. Production gravity centers on Chinese forging clusters supplying cost-disciplined OEM volume programs.
- Aluminum:Extruded and forged variants reducing unsprung mass by 30-40 percent versus steel baselines. Electric vehicle platforms in Germany and China specify these where range extension justifies raw material cost premiums and recycling infrastructure investments.
- Composite:Carbon fiber-reinforced polymer configurations for premium front-axle applications.
- Rubber:Elastomer boot sealing and vibration damping components integrated across all material tiers.
Steel commands current volume; aluminum claims the steepest expansion trajectory.
End User:
Customer type determines specification authority, pricing leverage, and inventory holding patterns.
- OEMs:Platform development-phase specification lock-in during chassis architecture definition. NHTSA FMVSS 126 and ECE R79 type approval requirements force parallel validation tracks for transatlantic programs, consolidating procurement authority with integrated chassis module suppliers.
- Aftermarket Providers:Logistics density and same-day availability competition across high-vehicle-parc urban corridors. Third-party distributors in India aggregate demand across regional carrier networks, displacing individual maintenance facility procurement autonomy.
- Vehicle Assemblers:Contract manufacturing arrangements for niche and specialty vehicle production.
- Repair Shops:Jobber-channel purchasing with price-sensitive brand substitution behavior.
Volume concentrates with OEMs; aftermarket channels expand most quickly in emerging parc markets.
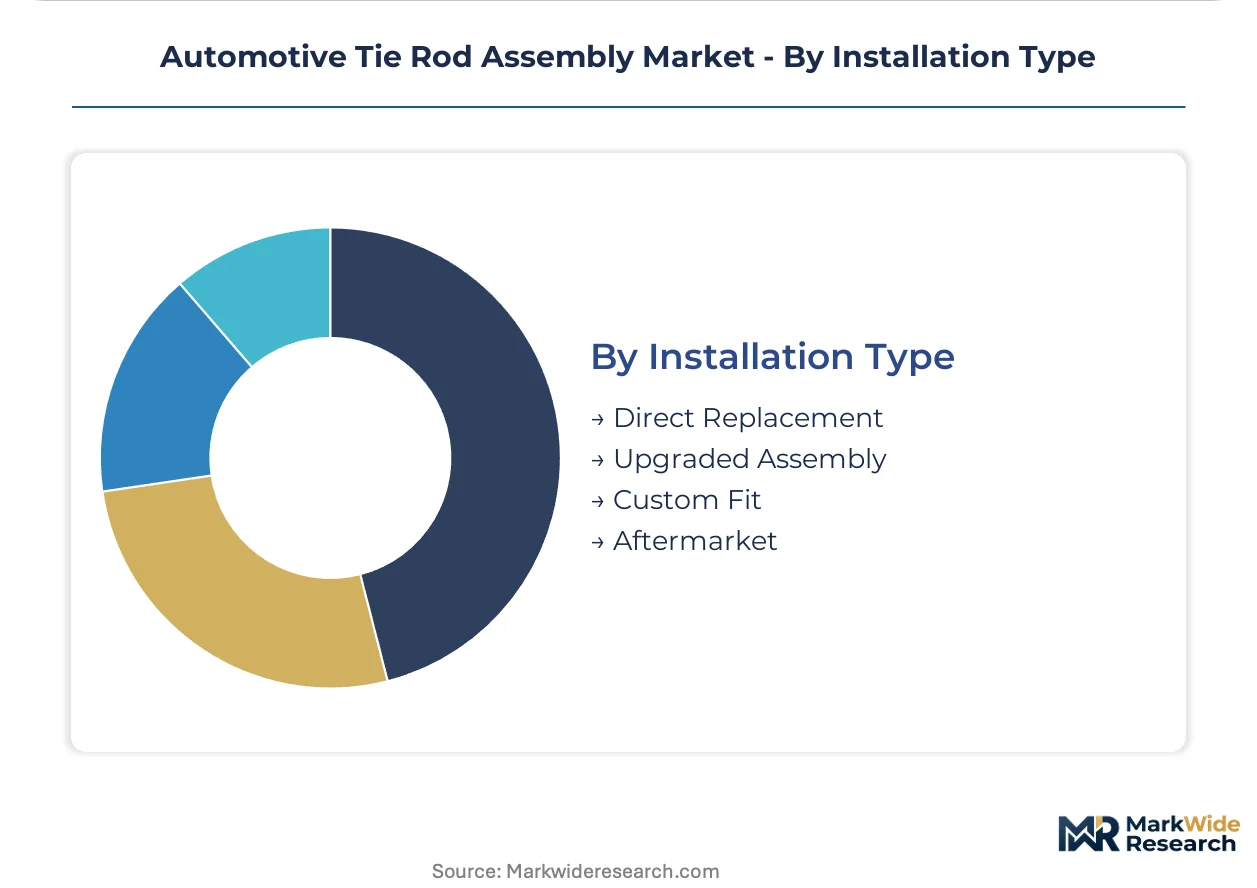
Installation Type:
Volume scale and margin structure separate original equipment fitment from service bay replacement economics.
- Direct Replacement:Identical-specification assemblies matching factory geometry without calibration requirements. United States commercial fleet operators specify these under outcome-based lifecycle cost contracts where downtime minimization overrides unit price considerations.
- Upgraded Assembly:Enhanced material grades or geometric configurations for modified suspension architectures. Performance vehicle specialists in Japan specify hardened alloy variants exceeding 800 MPa yield for track applications.
- Custom Fit:Tailored geometries for aftermarket suspension modifications and lifted vehicle configurations.
- Aftermarket:Generic replacement assemblies competing on logistics availability and price positioning.
Direct Replacement dominates volume; Upgraded Assembly gains share fastest in performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in China and Germany supply forging capacity that outpaces domestic consumption, while the United States and Japan concentrate demand through OEM platform specifications and stringent regulatory validation requirements.
United States
Commercial fleet electrification and heavy-duty truck stability mandates drive specification intensity for hardened alloy steering linkages. NHTSA FMVSS 126 mandates tighten lateral force transmission tolerances across degraded friction surfaces. Detroit-Windsor automotive corridor suppliers operate parallel validation tracks for EPA emissions compliance and NHTSA safety protocols.
Germany
OEM platform development cycles anchor European demand for modular chassis systems with integrated steering architectures. ECE R79 steering equipment regulations govern type approval and fatigue testing protocols diverging from Atlantic standards. Stuttgart and Munich engineering clusters concentrate R&D investment in aluminum forging for electric vehicle unsprung mass reduction.
China
Domestic OEM production volumes and export-oriented forging infrastructure create supply-side concentration exceeding regional consumption. MIIT new energy vehicle mandates accelerate lightweight tie rod adoption in domestic electric platforms. Yangtze River Delta forging clusters supply cost-disciplined volume programs for transnational OEM sourcing.
Japan
Precision steering geometry specifications in passenger vehicle platforms lock suppliers into multi-year development contracts with limited substitution. METI carbon neutrality roadmaps incentivize material substitution studies for chassis component lightweighting. Nagoya and Tokyo automotive supplier networks maintain vertical integration into heat treatment and surface finishing operations.
India
Aftermarket logistics density in high-vehicle-parc urban corridors drives replacement cycle demand independent of OEM platform specifications. BIS automotive component standards govern domestic manufacturing certification and import substitution programs. Pune and Chennai supplier clusters target same-day availability contracts for commercial vehicle maintenance networks.
Automotive Tie Rod Assembly Market Vendor Landscape
Top-tier vendors anchor integrated chassis module supply, while mid-scale forging specialists compete on cost discipline and regional logistics density. The supplier base stratifies across three tiers: multinational system integrators with platform-level specification authority, national forging houses serving domestic OEM programs, and aftermarket distributors competing on inventory proximity. Strategic moves concentrate on aluminum alloy forging capacity expansion and dual-certification testing infrastructure for transatlantic regulatory convergence.
Within the integrated systems tier, ZF Friedrichshafen AG and Nexteer Automotive Corporation exemplify multinational chassis module suppliers with platform-development-phase lock-in. GKN Automotive Limited occupies a position among forged driveline and steering component specialists leveraging constant-velocity joint integration. Among regional forging houses, Ample Auto Tech Pvt. Ltd. and G.S. Autocomp Pvt. Ltd. represent Indian suppliers targeting aftermarket density and domestic OEM qualification. Moog Inc. and Teknorot sit within the precision-engineered replacement segment serving fleet operators with outcome-based lifecycle contracts.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Nexteer Automotive Corporation |
| GKN Automotive Limited |
| Ample Auto Tech Pvt. Ltd. |
| G.S. Autocomp Pvt. Ltd. |
| FAI Automotive |
| Moog Inc. |
| Teknorot |
| Powers & Sons |
| Others |
Supply Flow & Price Mechanics
Aluminum ingot cost volatility propagates through forging operations in China and Germany, compressing margin structures for suppliers transitioning from steel-dominant production while fleet operators in the United States negotiate outcome-based lifecycle contracts that displace unit-price procurement.
Pricing Analysis
Margin tightening in aluminum tie rod tiers reflects LME price swings and recycling infrastructure investments, while steel-forged variants maintain cost discipline through Yangtze River Delta capacity concentration. Three-tier pricing structure across premium carbon-fiber, standard aluminum, and economy steel levels separates OEM platform-locked specifications from aftermarket logistics-driven replacement cycles. Cost compression in commercial vehicle segments accelerates as fleet operators aggregate demand across regional carrier networks. Aftermarket providers in India exhibit highest price sensitivity; German OEM platform engineers demonstrate lowest sensitivity due to specification lock-in during chassis architecture definition.
Supply Chain Analysis
Remanufacturing flows for heavy-duty tie rod cores create secondary material loops between United States fleet depots and Mexican reforging facilities, reducing virgin alloy demand in circular economy frameworks. Supply concentrates in China, Germany, and Japan, with Yangtze River Delta forging clusters feeding cost-disciplined volume programs. Raw material dependencies center on hardened alloy steel billets, aluminum extrusion stock, and carbon fiber prepreg. Single-source vulnerability in Chinese forging capacity creates exposure to trade corridor disruptions. Distribution runs through integrated chassis module suppliers for OEM channels and third-party logistics aggregators for aftermarket density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steer-by-wire architectures are displacing mechanical rack-and-pinion linkages, forcing suppliers to recalibrate R&D portfolios toward ISO 26262 functional safety verification and redundant force transmission systems.
For Market Incumbents: Lock in platform-development-phase specification authority with German and Japanese OEMs through integrated chassis module offerings that bundle tie rod assemblies with electrically powered steering architectures. Deepen backward integration into aluminum forging capacity in Stuttgart engineering clusters to capture unsprung mass reduction mandates. Defend against carbon fiber-reinforced polymer substitution by accelerating fatigue testing talent acquisition.
For New Entrants and Emerging Players: Enter via India's aftermarket logistics density, targeting same-day availability contracts in Pune and Chennai commercial vehicle maintenance corridors. Focus on adjustable tie rod variants for United States long-haul fleet operators under outcome-based lifecycle cost arrangements. Pursue recyclable aluminum alloy closed-loop recovery partnerships aligned with EU Green Deal circular economy frameworks.
For Investors and Strategic Acquirers: Dual certification timeline convergence between NHTSA FMVSS 126 and UN ECE test methodologies is the leading indicator that transatlantic regulatory alignment will consolidate supplier qualification costs and favor integrated chassis module vendors with parallel validation infrastructure. Position for aluminum forging specialists with captive recycling streams. Monitor MIIT new energy vehicle mandate acceleration in China as inflection signal for lightweight tie rod demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Forging Capacity Expansion | Captures EPA lightweighting mandates for electric vehicle range extension. |
| Dual Certification Testing Infrastructure | Reduces parallel validation costs across NHTSA and ECE R79 regulatory tracks. |
| Recyclable Alloy Closed-Loop Recovery | Aligns chassis component manufacturing with EU Green Deal circular economy targets. |
| Additive Manufacturing Convergence | Enables topology-optimized sleeve geometries unachievable through conventional forging. |
| Aftermarket Logistics Network Densification | Targets same-day availability contracts in India's high-vehicle-parc urban corridors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution operators, and fleet maintenance directors. Secondary validation drew from NHTSA FMVSS documentation, ECE R79 type approval records, MIIT new energy vehicle production databases, and ISO 26262 functional safety filings. Bottom-up vehicle production forecasts and top-down chassis component content-per-vehicle estimates were triangulated against forging capacity utilization data.
Granularity-level modeling tracked product type, material substitution trajectory, end-user channel, and installation category across the analysis window, with vehicle class and propulsion architecture as cross-cutting dimensions. CAGRs were derived from regression analysis against historical production volumes and regulatory mandate implementation schedules. Electric vehicle platform penetration rates and commercial vehicle electrification timelines served as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility spikes or transatlantic regulatory divergence extensions. Practitioners should monitor NHTSA-ECE test methodology harmonization progress and MIIT mandate acceleration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market