
 Global 3D Printing Automotive Market | 2026-2036
Global 3D Printing Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printing Automotive Market Foresight
North American polymer powder production capacity is realigning around automotive-qualified feedstock grades. HP Inc. leverages its Multi Jet Fusion platform to sustain high-volume part consistency for OEM qualification programs. Stratasys anchors its position through FDM and PolyJet systems tailored to jigs, fixtures, and interior component validation. EOS GmbH dominates metal powder bed fusion installations serving powertrain and chassis applications for European and Asian vehicle programs.
Global 3D printing in automotive encompasses additive manufacturing systems, consumable materials, process software, and engineering services used to produce geometrically complex vehicle components directly from digital models, typically achieving layer resolutions between 20 and 100 microns depending on the technology platform. Its primary commercial purpose is to compress product development cycles and enable topology-optimized designs unmanufacturable through conventional casting, stamping, or machining methods. Materials and services together capture the deepest margin pools as proprietary powder formulations and print-parameter development command pricing premiums over commoditized hardware. Selective Laser Sintering and Digital Light Processing are expanding fastest in tooling and end-use parts as these technologies deliver surface finish and mechanical properties matching injection-molded or die-cast benchmarks.
FDA, EPA, and REACH frameworks govern material safety, emissions during thermal processing, and chemical substance registration for automotive 3D printing feedstocks, effectively raising the compliance threshold for new market entrants without certified supply chains. NHTSA crashworthiness standards and EU Green Deal material circularity requirements are pushing manufacturers toward validated, recyclable powder systems and documented part traceability. Stakeholders must monitor evolving OEM qualification protocols and regulator harmonization efforts between the United States, Germany, and China to anticipate where production-scale additive manufacturing contracts will concentrate.
Market Dynamics
Topology-optimized lattice structures are compressing powertrain component mass while maintaining crashworthiness, forcing OEMs to rebuild supplier qualification protocols around additive-specific material datasets rather than legacy wrought-alloy specifications.
Growth Catalysts
- EU Green Deal circularity mandates:REACH-registered recyclable powder systems are gaining preferential access to German and French OEM supply chains, accelerating validated closed-loop material flows.
- Topology optimization software:Generative design tools integrated with powder bed fusion are enabling chassis components unmanufacturable through conventional stamping, pulling demand from weight-reduction engineering teams.
- China's NEV production concentration:MIIT-supported additive manufacturing centers in Shanghai and Shenzhen are absorbing metal powder bed fusion capacity for electric drivetrain thermal management parts.
Market Restraints
- Argon and nitrogen feedstock volatility:Inert gas costs for powder bed fusion atmosphere control fluctuate with industrial gas supply concentration in Germany and the United States, compressing margin predictability for high-volume contract manufacturers.
- Qualified powder supply concentration:Automotive-grade titanium and aluminum powder production clusters in Germany and Pennsylvania create geographic single-point vulnerabilities for Tier-1 suppliers scaling beyond pilot volumes.
- Surface finish limitations:As-built roughness on metal laser powder bed fusion parts requires secondary machining for sealing surfaces, adding process steps that erode the cycle-time advantage over die casting.
Strategic Opportunities
- India's PLI scheme for auto components:BIS certification pathways for additive materials remain underdeveloped, creating first-mover positioning for powder suppliers establishing local blending and testing infrastructure.
- Battery thermal management integration:Conformal cooling channels printed directly into electric vehicle battery housings are displacing brazed or machined assemblies, opening design-to-print service contracts with cell manufacturers.
- ISO/ASTM 52900 standard harmonization:Unified terminology and test methods across the United States, Germany, and China are reducing duplicate qualification costs for multi-regional OEM programs.
Industry Challenges
- Process-parameter IP fragmentation:Proprietary laser scan strategies and build recipes are locked behind equipment OEM paywalls, complicating technology transfer when Tier-1 suppliers switch machine platforms.
- Non-destructive testing bottlenecks:CT scanning capacity for internal defect detection in complex geometries remains concentrated in specialized service bureaus, extending lead times for production part approval.
- Post-processing skill scarcity:Hot isostatic pressing and precision machining of near-net additive forms require hybrid competencies rare in traditional automotive workforces, inflating labor costs for qualified technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printing Automotive Market |
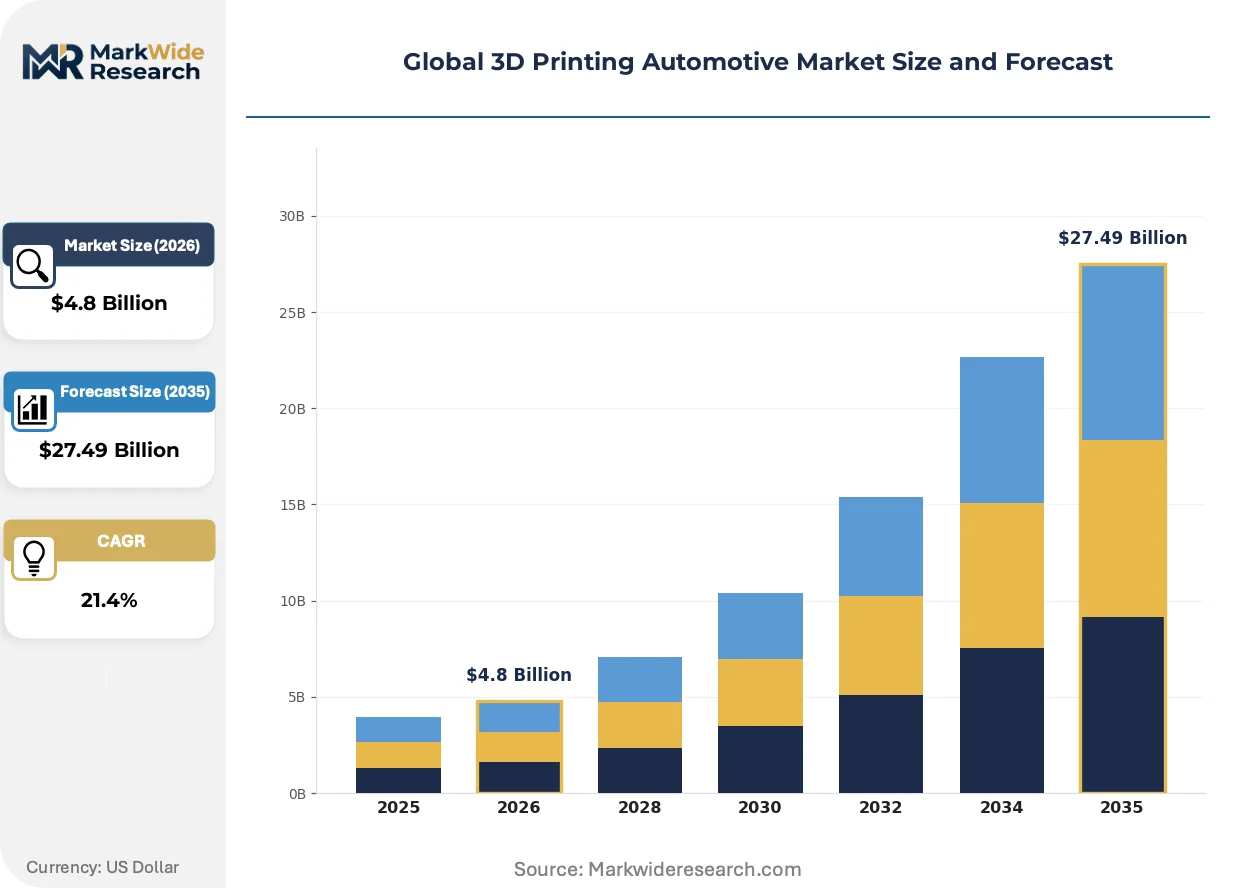
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $27.49 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
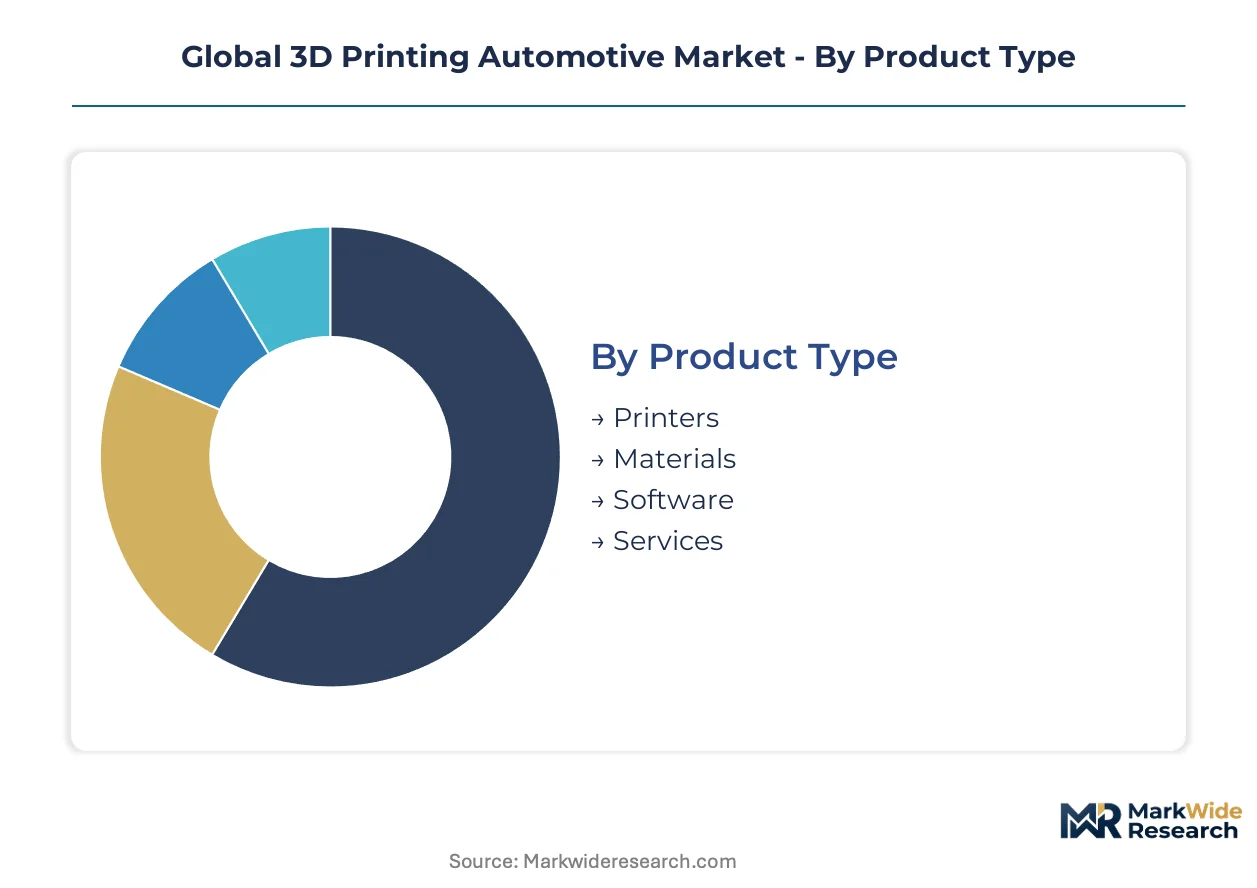
| Segmentation | Product Type: Printers, Materials, Software, Services Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Application: Prototyping, Tooling, End-Use Parts, Customization End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | HP Inc., Desktop Metal, Stratasys, Carbon, Markforged, 3D Systems, Materialise NV, Protolabs, EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printing Automotive Market Shifts & Advancements
Multi-material deposition and real-time melt pool monitoring are collapsing the boundary between prototyping and certified production, forcing equipment suppliers to reposition hardware platforms as process control systems rather than standalone machine tools.
Continuous fiber-reinforced polymer printing is absorbing structural load paths previously reserved for stamped metal assemblies. BMW and Porsche engineering teams are qualifying carbon-fiber nylon parts for seat frames and pedal boxes. The technology is absorbing crash energy management functions that die casting cannot lightweight without sacrificing ductility.
REACH authorization requirements for nickel and cobalt compounds are tightening powder feedstock documentation burdens. ECHA's 2024 updates to substance restriction lists are forcing European powder producers to segregate automotive-qualified batches from industrial grades. German OEMs are responding by consolidating supplier audits around single-source certified material streams rather than multi-vendor spot purchasing.
Direct digital manufacturing contracts are displacing traditional tooling procurement for low-volume specialty vehicles. Aston Martin and Lamborghini are contracting build-to-print services for suspension uprights and intake manifolds without amortizing mold costs across production runs. This pattern concentrates most visibly in Italian and British low-volume sports car manufacturing, where batch sizes below five thousand units invalidate conventional casting economics.
Global 3D Printing Automotive Market Segmentation
Automotive additive manufacturing segments along technology maturity curves and supply chain integration depth. Each axis reveals distinct margin structures and qualification barriers that determine competitive positioning.
Product Type:
Hardware specifications and consumable chemistry differentiate margin capture across the value chain.
- Printers:Powder bed fusion and material extrusion systems dominate factory floor deployments. OEMs in Germany and the United States prioritize multi-laser metal platforms for powertrain qualification programs.
- Materials:Proprietary aluminum and titanium powder formulations command pricing premiums over commoditized polymer feedstocks. REACH-registered recyclable grades are gaining preferential access to French and German OEM supply chains.
- Software:Build preparation and topology optimization tools compress design-to-print workflows. Generative design integration with powder bed fusion is pulling demand from chassis engineering teams.
- Services:Engineering consultancies and contract manufacturers bridge equipment ownership gaps for mid-tier suppliers.
Mature deployment sits with Materials. Newer deployment is concentrated in Software.
Technology:
Process physics and surface finish capabilities segment applications across prototyping-to-production spectrum.
- Fused Deposition Modeling:Thermoplastic filament extrusion delivers cost-efficient jigs and interior validation parts. Tier-1 suppliers in Michigan and Bavaria deploy FDM for non-structural tooling at scale.
- Stereolithography:Photopolymer resin curing achieves finest feature resolution for optical and aerodynamic prototypes. Wind tunnel model production concentrates in Stuttgart and Turin engineering centers.
- Selective Laser Sintering:Polymer powder bed fusion produces functional ducting and bracketry without support structures. Nylon 12 and PA11 grades are expanding fastest in under-hood thermal management.
- Digital Light Processing:Projected light polymerization matches injection-molded surface quality for interior trim validation. Tooling and end-use parts applications are climbing the fastest as build speeds approach production thresholds.
Established volume sits with Fused Deposition Modeling. Accelerating qualification is occurring in Digital Light Processing.
Application:
Development stage and production volume requirements determine technology-platform selection.
- Prototyping:Design iteration cycles for body panels and powertrain housings consume polymer and resin platforms. German and Japanese OEMs maintain captive rapid prototyping centers.
- Tooling:Conformal cooling channels printed directly into injection molds and die casting inserts displace machined steel. Lead time compression drives adoption among high-mix, low-volume suppliers.
- End-Use Parts:Topology-optimized seat brackets and suspension components achieve weight targets impossible with stamping. BMW and Porsche engineering teams are qualifying carbon-fiber nylon for crash-critical assemblies.
- Customization:Low-volume interior trim and badging serve specialty vehicle programs and aftermarket personalization.
Volume concentration rests with Prototyping. Steepest expansion trajectory is visible in End-Use Parts.
End User:
Supply chain tier and procurement authority shape equipment investment scale and material qualification depth.
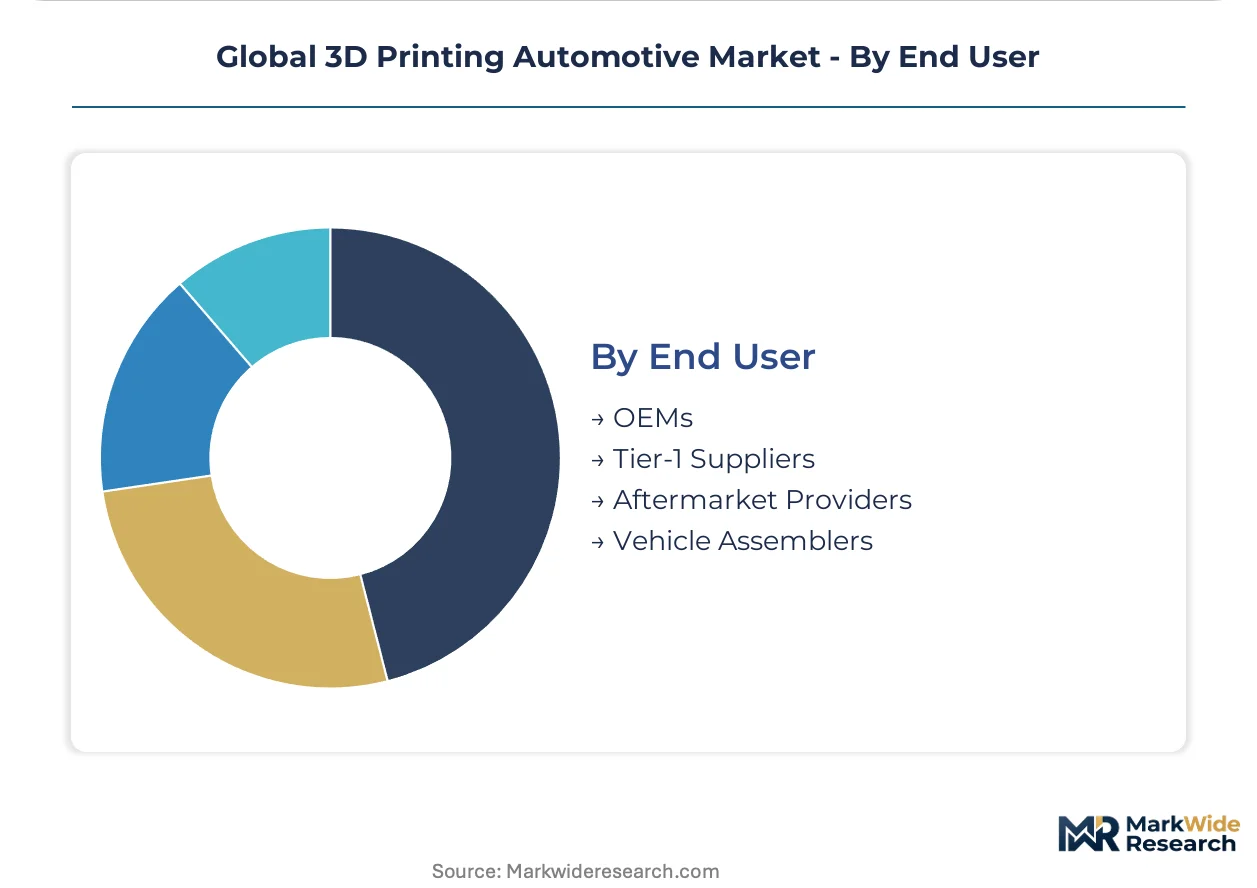
- OEMs:Volkswagen, Ford, and Toyota operate captive additive centers for powertrain and chassis development. Direct digital manufacturing contracts are displacing traditional tooling procurement for specialty vehicle programs.
- Tier-1 Suppliers:Bosch, Continental, and Magna deploy hybrid manufacturing for thermal management and electronic housing integration. Process-parameter IP fragmentation complicates technology transfer when switching machine platforms.
- Aftermarket Providers:Obsolete part reproduction and performance customization drive service bureau demand. CT scanning capacity for internal defect detection remains concentrated in specialized bureaus.
- Vehicle Assemblers:Contract manufacturers and low-volume sports car builders absorb build-to-print services without amortizing mold costs.
Capital deployment concentrates with OEMs. Emerging demand is surfacing among Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive-grade titanium and aluminum powder production anchors European supply security, while Pennsylvania and Shanghai clusters concentrate qualified feedstock capacity for transatlantic and Asia-Pacific manufacturing programs.
United States
Michigan and California OEM captive centers absorb metal powder bed fusion systems for powertrain qualification. NHTSA crashworthiness standards push manufacturers toward documented part traceability. Pittsburgh and Austin R&D clusters develop closed-loop recyclable powder systems for Ford and General Motors programs.
Germany
Bavarian and Baden-Württemberg engineering centers drive topology-optimized chassis component adoption. REACH authorization requirements for nickel and cobalt compounds tighten powder feedstock documentation burdens. Stuttgart and Munich host the densest concentration of EOS GmbH metal powder bed fusion installations serving Volkswagen and BMW vehicle programs.
China
Shanghai and Shenzhen MIIT-supported additive manufacturing centers absorb capacity for electric drivetrain thermal management parts. Dual carbon goals under MEE frameworks accelerate validated recyclable powder system development. Yangtze River Delta clusters concentrate NEV production integration with conformal cooling channel applications.
Japan
Kanto and Nagoya engineering centers maintain captive rapid prototyping capabilities for Toyota and Honda design iteration cycles. METI industrial technology roadmaps prioritize generative design integration with powder bed fusion. Osaka-area suppliers qualify carbon-fiber nylon for interior structural validation programs.
India
Maharashtra and Tamil Nadu component manufacturers explore additive tooling for high-mix, low-volume production scenarios. PLI scheme incentives for auto components create first-mover positioning for powder suppliers establishing local blending infrastructure. Bangalore R&D clusters develop BIS certification pathways for automotive-qualified feedstock grades.
Global 3D Printing Automotive Market Competitive Landscape
Global majors compete with regional champions across equipment platforms and qualified material supply chains. Market structure tilts toward technology-specific consolidation, with powder bed fusion and material extrusion each commanded by distinct equipment archetypes. Three player categories dominate: integrated hardware-materials-service conglomerates, pure-play equipment specialists, and contract manufacturing service bureaus. Competitive moves concentrate on strategic partnerships for OEM qualification programs and captive powder production capacity expansion.
Within the integrated systems tier, HP Inc. and Stratasys occupy positions spanning hardware platforms and consumable ecosystems. EOS GmbH anchors the European metal powder bed fusion specialist segment. Among North American pure-plays, Desktop Metal and Markforged exemplify scale-driven equipment vendors targeting production-floor deployment. 3D Systems and Carbon represent diversified technology portfolio holders across polymer and resin platforms. Materialise NV and Protolabs sit within the service bureau archetype, bridging equipment ownership gaps for mid-tier suppliers without captive additive capacity.
| Leading Market Players |
|---|
| HP Inc. |
| Desktop Metal |
| Stratasys |
| Carbon |
| Markforged |
| 3D Systems |
| Materialise NV |
| Protolabs |
| EOS GmbH |
| Others |
Supply & Pricing Matrix
Argon and nitrogen feedstock costs for powder bed fusion atmosphere control cascade from industrial gas production clusters in Germany and Pennsylvania through to contract manufacturer margins, with automotive-qualified titanium and aluminum powder commanding premiums over commoditized grades based on REACH registration status and closed-loop recyclability certification.
Pricing Analysis
Warranty and service bundling separates equipment OEM pricing tiers, with HP Inc. and EOS GmbH including multi-year maintenance and parameter optimization support in premium platform contracts while entry-level material extrusion systems ship unbundled. Price differentiation hinges on automotive qualification depth and ISO/ASTM 52900 certification tier, with OEM-direct procurement showing lowest sensitivity and mid-tier suppliers facing acute pressure from inert gas cost volatility eroding per-part economics.
Supply Chain Analysis
Dual-sourcing mandates from Volkswagen and Ford procurement protocols require qualified powder suppliers to maintain parallel production lines across Germany, Pennsylvania, and Shanghai clusters, insulating programs from geographic single-point failures. Automotive-grade titanium sponge draws from Ukrainian and Russian feedstock origins now subject to substitution pressures, with distribution running through Tier-1 supplier captive blending facilities rather than spot market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive additive manufacturing operates as a supply-constrained market where qualified powder production capacity, not equipment installation base, props pricing power and determines which contract manufacturers capture OEM direct digital manufacturing contracts.
For Market Incumbents: Acquire captive powder production assets in Pennsylvania and Bavaria to secure automotive-qualified titanium and aluminum supply chains against emerging Chinese equipment vendors. Consolidate process-parameter IP libraries through exclusive licensing agreements with university R&D clusters, insulating against technology transfer risks when Tier-1 suppliers switch machine platforms. For New Entrants and Emerging Players: India's PLI scheme for auto components opens a window for powder suppliers establishing local BIS certification pathways and blending infrastructure ahead of developed-market saturation. Target aftermarket obsolete part reproduction services where CT scanning capacity constraints and low volume requirements favor build-to-print service bureau models over captive OEM investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturing service bureaus with established OEM qualification programs and documented part traceability systems in Michigan and Baden-Württemberg. Monitor NHTSA crashworthiness standard updates as the inflection signal for which topology-optimized designs achieve production-scale approval.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Production Expansion | Backward integration into titanium and aluminum feedstock secures REACH-registered supply for German OEM qualification programs. |
| Multi-Material Platform Integration | Real-time melt pool monitoring systems collapse prototyping-to-production boundaries for BMW and Porsche engineering teams. |
| Conformal Cooling Channel Partnerships | Design-to-print service contracts with cell manufacturers displace brazed battery thermal management assemblies. |
| ISO/ASTM 52900 Harmonization Investment | Unified test methods reduce duplicate qualification costs for multi-regional Volkswagen and Toyota vehicle programs. |
| India PLI Scheme Localization | BIS certification pathway development captures first-mover positioning in Maharashtra and Tamil Nadu component manufacturing. |
Research Methodology
SEC filings, ECHA substance registration databases, and OEM supplier qualification protocols formed the secondary backbone, supplemented by primary interviews with Tier-1 supplier procurement directors, powder bed fusion equipment R&D leads, automotive platform engineers, and aftermarket service bureau operators. Bottom-up and top-down triangulation validated installed base estimates against consumables demand and qualified material production capacity disclosures.
Bottom-up modeling segmented volume and value across technology platform, application maturity curve, and end-user tier, with CAGR derivation anchored in OEM powertrain and chassis qualification pipeline visibility across the projection horizon. Forecast inputs incorporated powder bed fusion build speed evolution, inert gas cost trajectories, and REACH authorization timeline assumptions for nickel and cobalt compound feedstocks.
The model assumes a particular technology adoption path; alternative pathways for continuous fiber-reinforced polymer printing would alter the outlook if BMW and Porsche crash-critical qualification programs accelerate beyond current powertrain-focused deployment. A model refresh is warranted upon material change in NHTSA or EU Green Deal material circularity enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market