
 Automotive Tensioner Market | 2026-2036
Automotive Tensioner Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tensioner Market Outlook
Steel-to-composite material substitution is expanding the addressable margin pool for suppliers capable of hybrid-metal designs. Continental AG leverages captive polymer research to anchor European OEM relationships. Gates Corporation sustains aftermarket channel control through direct distributor networks in North America. SKF dominates precision bearing integration within hydraulic tensioner assemblies.
An automotive tensioner is a mechanical or electromechanical device that maintains optimal belt or chain tension in engine timing and accessory drive systems, typically incorporating spring-loaded arms, hydraulic dampers, or electronically controlled actuators with operating pressures between 2 and 15 bar. Its primary purpose is preventing slippage, reducing vibration, and extending drivetrain component life across internal combustion and electrified powertrains. Belt tensioners retain the largest installed base due to widespread serpentine drive architectures, while electronic tensioners represent the fastest-growing category as EV powertrain architectures demand active, software-controlled tension management. Hydraulic tensioners command premium positioning in heavy-duty vehicle applications where thermal cycling severity exceeds passive spring capacity.
EPA fuel-economy standards and NHTSA safety regulations in the United States compel tensioner suppliers to validate components for 240,000-mile durability cycles, directly elevating R&D overhead for market access. China's MEE enforces dual carbon-aligned emissions benchmarks that favor low-friction tensioner designs in domestic vehicle production. The EU's F-Gas Regulation and REACH chemical restrictions constrain seal and damping fluid formulations, reshaping material qualification pathways. Stakeholders must monitor how EV powertrain adoption alters tensioner content-per-vehicle calculations across hybrid and fully electric architectures.
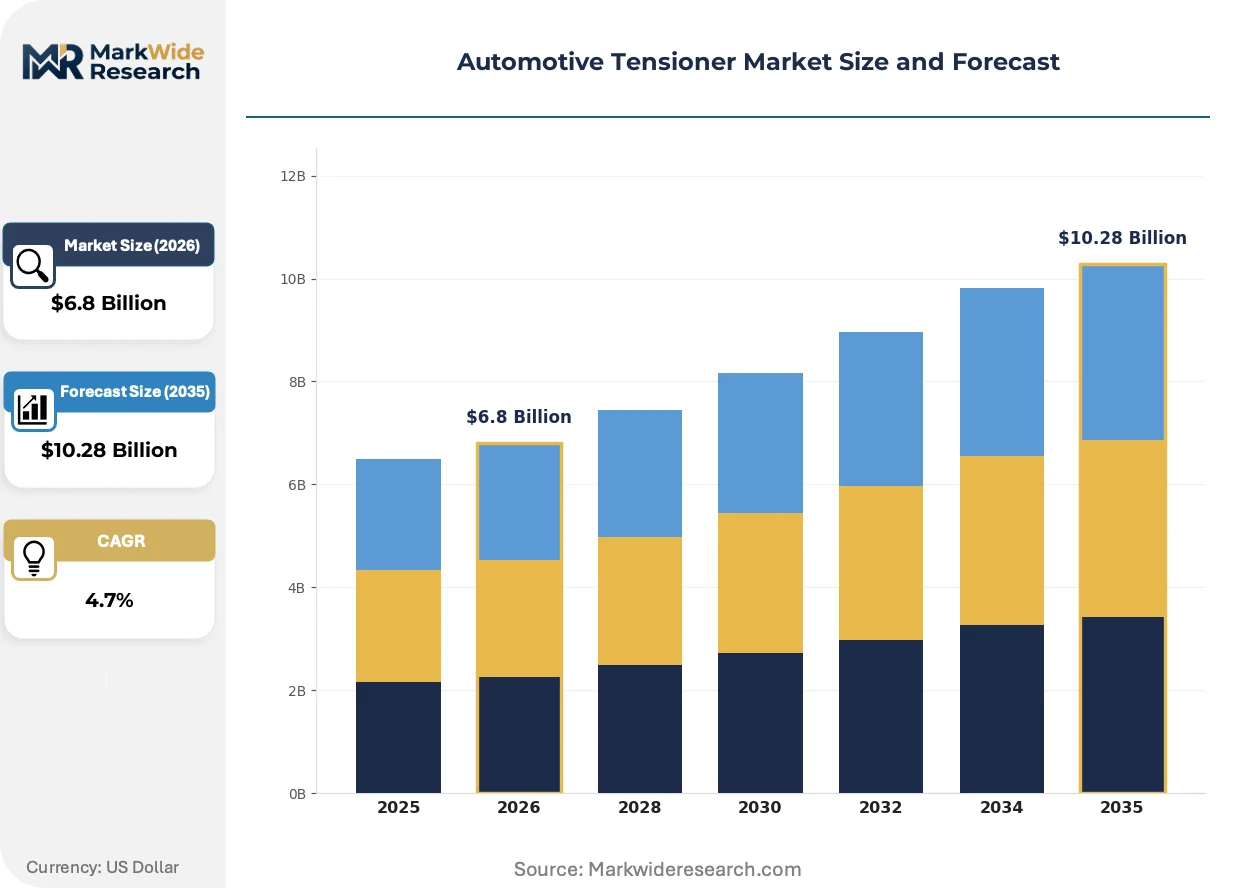
Market Dynamics
China's dual carbon policy alignment is compressing tensioner design cycles, forcing suppliers to requalify materials for lightweighting while maintaining 240,000-mile durability validation under NHTSA protocols.
Growth Catalysts
- EPA fuel-economy mandates:United States OEMs now require tensioner systems validated for extended durability cycles, expanding the addressable market for premium hydraulic assemblies in heavy-duty platforms.
- EV powertrain architectures:Electronic tensioners with software-controlled actuation are capturing incremental content-per-vehicle as hybrid and battery-electric platforms proliferate across passenger and commercial segments.
- Shanghai-Ningbo manufacturing corridor:Concentrated domestic EV output in China's eastern seaboard is generating localized demand for tensioner specifications optimized for electrified drivetrains.
Market Restraints
- Steel price volatility:Raw material input swings compress margin predictability for suppliers reliant on conventional stamped-metal arm constructions.
- REACH chemical restrictions:EU seal and damping fluid formulations face constrained qualification pathways, extending R&D timelines for European market access.
- Passive spring tensioners:Mature belt-drive architectures face displacement risk as active electronic systems penetrate mid-range vehicle segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Incentive structures for advanced manufacturing create entry pathways for tensioner suppliers with hybrid-metal capabilities.
- Aftermarket channel digitization:Direct-to-distributor platforms are disintermediating traditional wholesale networks in North American replacement demand.
- Polymer-composite convergence:Integration of captive polymer research with precision bearing engineering enables margin expansion through material substitution.
Industry Challenges
- Mechatronics engineering scarcity:Electronic tensioner development requires software-hardware integration expertise that outpaces current workforce supply.
- ISO 26262 functional safety certification:Electrified powertrain applications demand ASIL-rated validation processes that extend qualification timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tensioner Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Tensioners, Chain Tensioners, Hydraulic Tensioners, Electronic Tensioners End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: On-Road Vehicles, Off-Road Vehicles, Heavy-Duty Vehicles, Motorcycles Transmission Type: Manual Transmission, Automatic Transmission, CVT, EV Powertrain |
| Companies Covered | Continental AG, Gates Corporation, Litens Automotive Group, Dayco, NTN Corporation, Muhr und Bender KG, ABA Automotive, GMB Corporation, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tensioner Market Strategic Shifts
Active tension management is displacing passive mechanical systems across powertrain architectures, with software-defined control becoming the primary axis of supplier differentiation.
Electromechanical tensioner actuators are decentralizing control authority from centralized engine management units to edge-mounted smart devices. Tier 1 suppliers in Germany and Japan are deploying these systems in premium hybrid platforms. This architecture is decentralizing the traditional supplier-OEM interface, enabling over-the-air calibration updates and reducing wiring harness complexity.
China's MEE enforcement of dual carbon-aligned emissions benchmarks is accelerating low-friction tensioner specifications in domestic production. The regulation compresses allowable parasitic losses from accessory drive systems. Domestic EV manufacturers in the Yangtze River Delta are responding with ceramic-coated pulley surfaces and optimized damping profiles.
Fleet procurement departments are consolidating supplier relationships around full-system drivetrain partners rather than discrete component vendors. This concentration is displacing standalone tensioner specialists from commercial vehicle platforms. The pattern is most pronounced in North American heavy-duty segments where total cost of ownership modeling dominates sourcing decisions.
Automotive Tensioner Market Segmentation
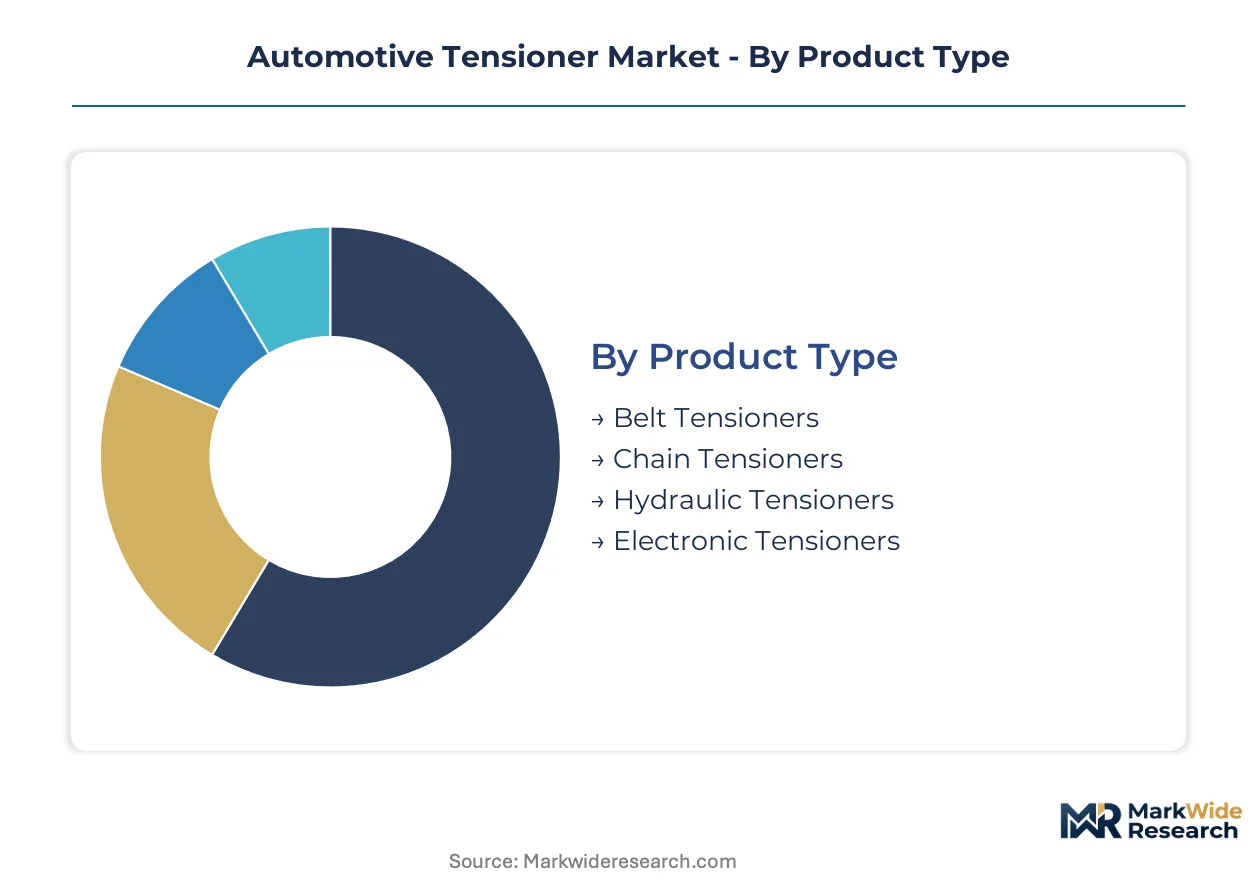
Automotive tensioner configurations diverge sharply by powertrain architecture, with electrification forcing material and actuation technology choices that reshape supplier economics. Segmentation clarity determines which specifications capture volume versus margin across hybrid and battery-electric platforms.
Product Type:
Capital intensity peaks with electronic tensioners requiring mechatronics integration and software validation, while hydraulic assemblies demand precision machining infrastructure that favors established Tier-1 suppliers.
- Belt Tensioners:Spring-loaded mechanical assemblies with stamped-metal arms and polymer pulleys dominate serpentine accessory drive installations. Demand concentrates in India's passenger vehicle OEM corridor, where cost-sensitive platforms favor passive designs over active actuation.
- Chain Tensioners:Engine timing applications require hardened steel guide rails with hydraulic damping elements to manage camshaft load variation. China's domestic EV manufacturers in the Yangtze River Delta specify ceramic-coated contact surfaces to reduce parasitic friction under MEE emissions benchmarks.
- Hydraulic Tensioners:Pressurized damping chambers with precision seals address thermal cycling in heavy-duty diesel architectures.
- Electronic Tensioners:Sensor-integrated actuators with ECU-controlled pressure modulation enable real-time tension adjustment.
Most installed capacity flows through belt tensioners. Expansion is steepest in electronic tensioners.
End User:
Customer type dictates contract structure, with vehicle assemblers demanding system-level integration while aftermarket channels prioritize inventory velocity and cross-reference compatibility.
- OEMs:Original equipment manufacturers specify tensioners as part of complete accessory drive modules, requiring 240,000-mile durability validation under NHTSA protocols. EPA fuel-economy mandates in the United States compress development cycles for lightweight composite alternatives.
- Aftermarket Providers:Independent distributors and service chains stock replacement units for aging vehicle parc maintenance. North American demand runs through direct-to-distributor digitization platforms that disintermediate traditional wholesale networks.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities source tensioners through consolidated drivetrain supplier relationships.
- Tier-1 Suppliers:System integrators bundle tensioners with pulley assemblies and mounting hardware for engine plant delivery.
Vehicle assemblers command the largest procurement volumes. Aftermarket providers are gaining share fastest through channel digitization.
Installation Type:
Operating environment severity separates specifications, with thermal load and contamination exposure driving material selection divergence across mobility categories.
- On-Road Vehicles:Passenger cars and light trucks utilize compact tensioner designs optimized for underhood packaging constraints. China's eastern manufacturing corridor generates concentrated demand for electrified powertrain-compatible specifications.
- Off-Road Vehicles:Agricultural and construction equipment encounters dust ingress and irregular load profiles that accelerate seal degradation.
- Heavy-Duty Vehicles:Class 8 trucks and commercial buses require hydraulic damping assemblies rated for 15 bar operating pressure and extended thermal cycling.
- Motorcycles:Compact single-cylinder and V-twin engines specify miniaturized tensioner units with reduced spring rates.
On-road vehicles absorb the majority of production output. Heavy-duty vehicles deliver the highest unit margins.
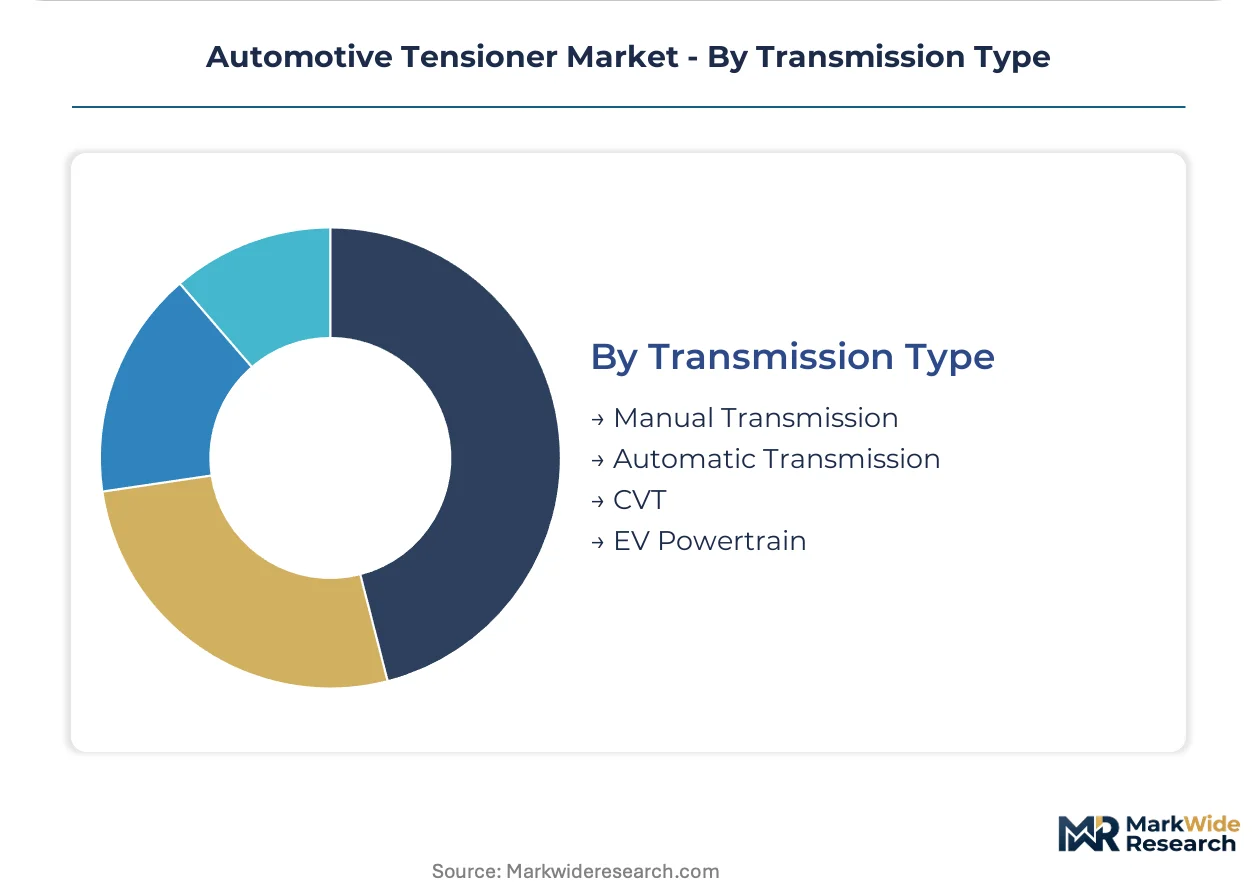
Transmission Type:
Powertrain architecture determines tensioner functional requirements, with electrification eliminating traditional accessory drive configurations in full battery-electric platforms.
- Manual Transmission:Clutch-dependent powertrains retain conventional belt-drive architectures with mechanical tensioners. India's domestic passenger vehicle segment sustains demand for cost-optimized spring-loaded designs.
- Automatic Transmission:Torque converter architectures require robust tensioner damping to manage engine speed variation during gear shifts.
- CVT:Continuously variable transmissions impose sustained high-RPM operation that elevates belt tensioner thermal stress.
- EV Powertrain:Battery-electric architectures eliminate engine-driven accessory belts, redirecting tensioner demand toward thermal management pump drives and range-extender applications.
Automatic transmission platforms anchor current volume. EV powertrain applications are climbing the fastest as electrification penetrates passenger and commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global automotive tensioner demand, with Shanghai-Ningbo manufacturing corridor generating concentrated procurement for electrified powertrain specifications. China's domestic EV output reshapes tensioner design requirements across belt, chain, and electronic actuator categories. Regulatory pressure from Beijing's dual carbon policy compresses material qualification cycles while elevating lightweight composite adoption.
China
Domestic EV manufacturers in Jiangsu and Zhejiang provinces drive specifications for ceramic-coated pulley surfaces and optimized damping profiles. MEE enforcement of dual carbon-aligned emissions benchmarks mandates reduced parasitic losses from accessory drive systems. The Shanghai-Ningbo corridor concentrates precision machining capacity for hydraulic tensioner assemblies serving both domestic OEMs and export markets.
United States
EPA fuel-economy standards compel tensioner validation for 240,000-mile durability cycles, elevating R&D overhead for market access. NHTSA safety protocols extend qualification timelines for electromechanical actuators in hybrid platforms. Michigan and Ohio-based drivetrain suppliers anchor heavy-duty hydraulic tensioner production for Class 8 commercial vehicle segments.
Germany
Premium hybrid platform development in Baden-Württemberg and Bavaria demands electronic tensioners with software-defined control architectures. EU F-Gas Regulation and REACH chemical restrictions constrain seal and damping fluid formulations, reshaping material qualification pathways. Stuttgart-Munich industrial corridor hosts Tier 1 system integrators bundling tensioners with complete accessory drive modules.
India
Cost-sensitive passenger vehicle OEMs in Maharashtra and Gujarat sustain demand for passive spring-loaded belt tensioners over active actuation. PLI scheme incentive structures for advanced manufacturing create entry pathways for suppliers with hybrid-metal capabilities. The Pune-Chennai manufacturing belt concentrates stamping capacity for conventional stamped-metal arm constructions.
Japan
Precision bearing integration expertise in Aichi and Kanagawa prefectures supports hydraulic tensioner assembly for thermal cycling severity applications. METI industrial policy channels R&D investment toward mechatronics engineering for sensor-integrated electronic actuators. The Nagoya-Yokohama corridor anchors development of edge-mounted smart tensioner devices with decentralized control authority.
Automotive Tensioner Market Competitive Environment
Global majors compete with regional champions across precision bearing integration and polymer-composite material substitution. The supplier base organizes around three tiers: integrated drivetrain system vendors, standalone tensioner specialists, and captive in-house production units at major OEMs. Strategic differentiation flows through M&A consolidation of distributor networks and capacity expansion in China's eastern seaboard manufacturing corridor.
Within the integrated system tier, Continental AG exemplifies European-based polymer research capabilities, while Gates Corporation occupies a position in North American aftermarket channel structures. SKF anchors precision bearing engineering for hydraulic damping assemblies. These three entities represent contrasting archetypes: materials-led vertical integration, distribution-controlled aftermarket positioning, and precision component specialization.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Litens Automotive Group |
| Dayco |
| NTN Corporation |
| Muhr und Bender KG |
| ABA Automotive |
| GMB Corporation |
| SKF |
| Others |
Value Chain & Pricing Dynamics
Vehicle assemblers in the Yangtze River Delta anchor pricing power through consolidated drivetrain procurement contracts that compress margins for standalone tensioner specialists. Contract structures favor full-system suppliers capable of 240,000-mile durability validation under NHTSA protocols, forcing price discipline across component tiers.
Pricing Analysis
Steel and polymer composite input costs pass through to OEM contract pricing with 6-12 month lags, creating margin volatility for suppliers reliant on conventional stamped-metal arm constructions. Three-tier pricing structure across premium hydraulic, standard mechanical, and economy passive spring assemblies dominates contract negotiations. Pricing pressure stems from China's MEE emissions benchmarks accelerating low-friction design requirements. Aftermarket distributors exhibit highest price sensitivity due to inventory velocity constraints, while heavy-duty OEMs prioritize performance validation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from European and North American OEMs require suppliers to qualify secondary manufacturing sites across Germany, China, and Mexico for supply security. Precision bearing components draw from Aichi prefecture machining clusters, while polymer composite formulations rest on captive research at Continental AG's European facilities. Tariff exposure on Chinese-sourced ceramic-coated pulleys creates qualification risk for EV-optimized specifications. Distribution runs through Tier 1 system integrators bundling tensioners with complete accessory drive modules for just-in-time engine plant delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive tensioner market functions as a stable compounder anchored by EPA fuel-economy mandates that extend component durability requirements across vehicle replacement cycles. Electrification tailwinds from EV powertrain proliferation sustain content-per-vehicle expansion in electronic actuator categories.
For Market Incumbents: Extend precision bearing integration capabilities into electronic tensioner architectures to capture hybrid platform specifications. SKF and NTN Corporation anchor hydraulic assembly dominance through thermal cycling expertise; backward integration into polymer-composite formulations defends margin position against material substitution threats from Continental AG's captive research. Capacity expansion in China's Shanghai-Ningbo corridor secures proximity to concentrated EV output. For New Entrants and Emerging Players: India's PLI scheme for automotive components opens a window for hybrid-metal tensioner specialists to establish manufacturing presence in Maharashtra and Gujarat. Target cost-sensitive passenger vehicle OEMs with passive spring-loaded designs before advancing to active actuation. Aftermarket channel digitization in North America offers direct-to-distributor entry bypassing wholesale network incumbency. For Investors and Strategic Acquirers: Drivetrain system integrators are the most active acquirer in this space, consolidating standalone tensioner specialists into full-module suppliers. The 5-10 year investment horizon favors precision machining assets with ISO 26262 ASIL-rated certification capabilities. Watch EV powertrain adoption rates as the inflection signal for electronic versus mechanical tensioner demand mix.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Composite Material Integration | Captive research at Continental AG enables margin expansion through steel substitution in lightweight designs. |
| Electronic Actuator Platform Standardization | Software-defined control architectures differentiate Tier 1 suppliers in German premium hybrid development. |
| ASIL-Rated Functional Safety Certification | ISO 26262 validation extends qualification timelines but secures electrified powertrain supplier status. |
| Direct-to-Distributor Aftermarket Digitization | Gates Corporation's North American channel control disintermediates traditional wholesale networks. |
| Shanghai-Ningbo Manufacturing Footprint | Proximity to China's Yangtze River Delta EV output reshapes tensioner specification requirements. |
Study Parameters
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads grounded qualitative insights in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA fuel-economy filings, and NHTSA safety protocol documentation. Bottom-up and top-down triangulation reconciled component-level specifications with aggregate powertrain demand forecasts.
Bottom-up modeling segmented volume and value across belt, chain, hydraulic, and electronic tensioner categories by propulsion architecture, vehicle class, and regional production cluster. Top-down constraints from OEM platform rollout schedules and electrification penetration curves bounded growth assumptions. CAGRs derived from regression analysis of historical content-per-vehicle trends against regulatory durability mandates and material substitution trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility and REACH chemical restriction enforcement timelines. Deviation in EV powertrain adoption rates or dual carbon policy implementation intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Air Vent Assembly Market