
 Engine Fixture Market | 2026-2036
Engine Fixture Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Fixture Market Insights
Precision-grade tolerances is bifurcating the competitive landscape between premium-positioned suppliers and cost-optimized manufacturers. Haas Automation leverages its integrated CNC machine tool ecosystem to bundle fixture solutions with machining centers. Sandvik Coromant sustains technology leadership through advanced cutting tool and workholding material science. SCHUNK dominates modular gripping and clamping architectures that reduce changeover times in automated engine lines.
An engine fixture is a specialized workholding device designed to locate, support, and secure an engine block, cylinder head, or rotating assembly during machining, assembly, or inspection operations, typically constructed from hardened steel or cast iron with locating pins positioned to within 0.01 mm repeatability to maintain geometric dimensioning and tolerancing across production batches. Its primary purpose is to eliminate datum shift during multi-axis operations such as cylinder boring, deck surfacing, and crankshaft line boring, ensuring interchangeability of engine components across high-volume manufacturing. Hydraulic fixtures command the largest installed base among product types due to their clamping force consistency in heavy-duty engine block machining, while sensor-based alignment technology is gaining share fastest as inline metrology integration reduces first-article inspection cycles. CAD/CAM integration remains the dominant technology dimension as digital twin workflows allow fixture designs to validate interference detection before physical prototyping, though robotic automation is displacing manual loading in Tier-1 assembler environments.
ISO standards for geometric tolerancing and workholding safety intersect with EPA emissions compliance requirements that dictate tighter machining specifications for engine sealing surfaces. FDA regulations do not govern this industrial equipment category, though OSHA machine guarding standards directly affect fixture enclosure and interlock designs in US manufacturing plants. Stakeholders must monitor how evolving powertrain electrification strategies reshape fixture demand profiles between internal combustion architectures and e-motor assembly platforms.
Market Dynamics
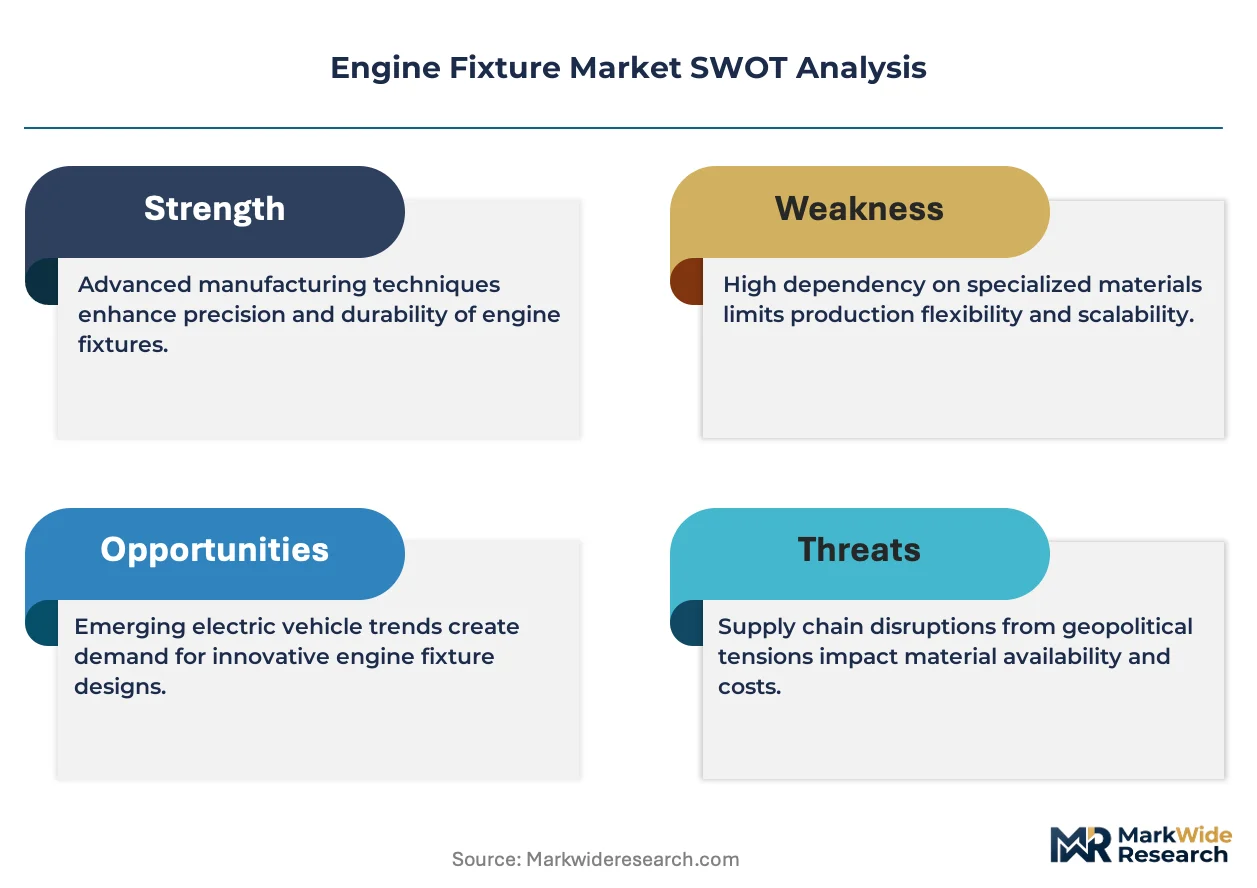
Powertrain electrification strategies are bifurcating fixture demand between legacy internal combustion architectures and emerging e-motor assembly platforms, forcing suppliers to maintain dual competency portfolios.
Growth Catalysts
- ISO 9001 Quality Mandates:Tightening geometric tolerancing requirements across automotive OEM supply chains are elevating fixture precision specifications to 0.01 mm repeatability thresholds.
- German Powertrain Clusters:Stuttgart and Munich engineering corridors are driving specialized fixture development for hybrid engine platforms combining combustion and electric architectures.
- Sensor-Based Alignment:Inline metrology integration is compressing first-article inspection cycles and reducing changeover downtime in automated engine lines.
Market Restraints
- Hardened Steel Input Volatility:Alloy steel price fluctuations directly compress fixture manufacturer margins and destabilize long-term contract pricing.
- German Supplier Concentration:Specialized hydraulic fixture production clusters heavily in Baden-Württemberg, creating geographic supply vulnerability.
- Manual Loading Substitution:Robotic automation is eroding demand for traditional manual fixture designs in Tier-1 assembler environments.
Strategic Opportunities
- E-Motor Assembly Platforms:Electric vehicle powertrain manufacturing requires entirely new fixture architectures for stator winding and rotor balancing operations.
- Digital Twin Workflows:CAD/CAM integration enables virtual interference detection before physical prototyping, reducing development cycles.
- Modular Clamping Architectures:Standardized gripping systems that reduce changeover times are penetrating Japanese and South Korean automotive markets.
Industry Challenges
- Multi-Axis Programming Expertise:Shortage of technicians skilled in simultaneous 5-axis fixture operation and CNC integration is constraining deployment timelines.
- OSHA Machine Guarding Compliance:US manufacturing plants face extended certification cycles for fixture enclosure and interlock redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Fixture Market |
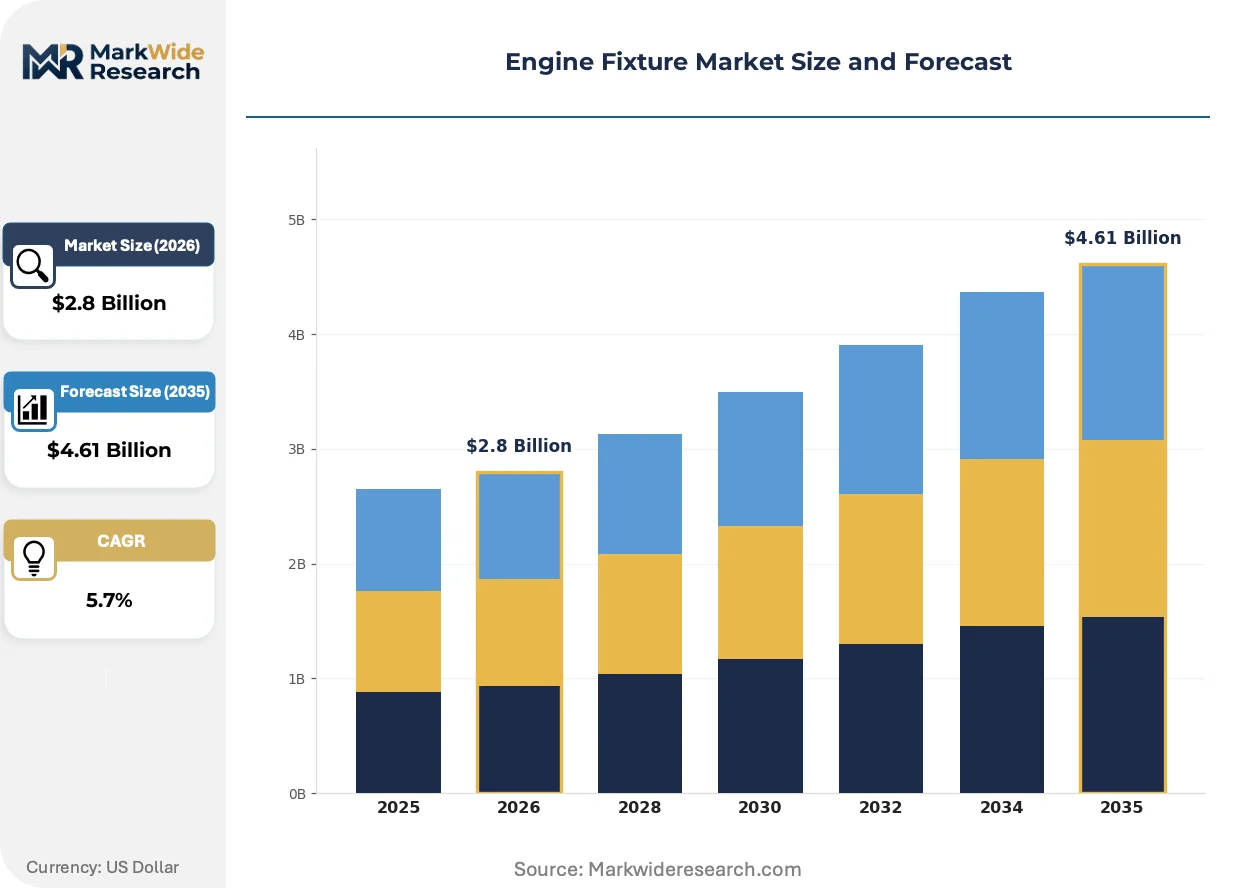
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fixtures, Pneumatic Fixtures, Mechanical Fixtures, Magnetic Fixtures, Manual Fixtures Technology: CAD/CAM Integration, CNC Compatible, Sensor-based Alignment, Robotic Automation, Modular Design Application: Engine Assembly, Valve Seat Machining, Cylinder Honing, Turbocharger Installation, Gear Fitting End User: OEM Manufacturing Plants, Aftermarket Suppliers, Engine Rebuilders, Tier-1 Assemblers |
| Companies Covered | Haas Automation, Sandvik Coromant, SMW-AUTOBLOK Group, SCHUNK, Jergens, Carr Lane Manufacturing, Forkardt International, Kitagawa Iron Works, DESTACO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Fixture Market Trends and Innovations
Fixture technology is converging with digital manufacturing workflows and automated material handling systems, compressing the boundary between workholding and intelligent production infrastructure.
Sensor-based alignment technology is supplanting mechanical dial-indicator setups in high-volume engine block machining. Tier-1 automotive assemblers in Germany and Japan are adopting photogrammetric and laser-tracker integration at accelerating rates. This convergence is enabling real-time datum correction and eliminating manual inspection bottlenecks in multi-axis operations.
REACH substance restrictions and RoHS compliance mandates in Europe are reshaping fixture surface treatment specifications. Chromium plating processes face substitution pressure from trivalent alternatives and ceramic coatings. German fixture manufacturers are reformulating corrosion protection protocols to maintain CE marking eligibility for export markets.
Buyer consolidation among automotive OEMs is compressing supplier qualification timelines and elevating performance guarantees. Volkswagen Group and Toyota Motor are unbundling fixture procurement from machining center bundles, forcing standalone fixture vendors to demonstrate interoperability across heterogeneous equipment fleets. This pattern is most pronounced in North American powertrain plant expansions.
Engine Fixture Market Segmentation
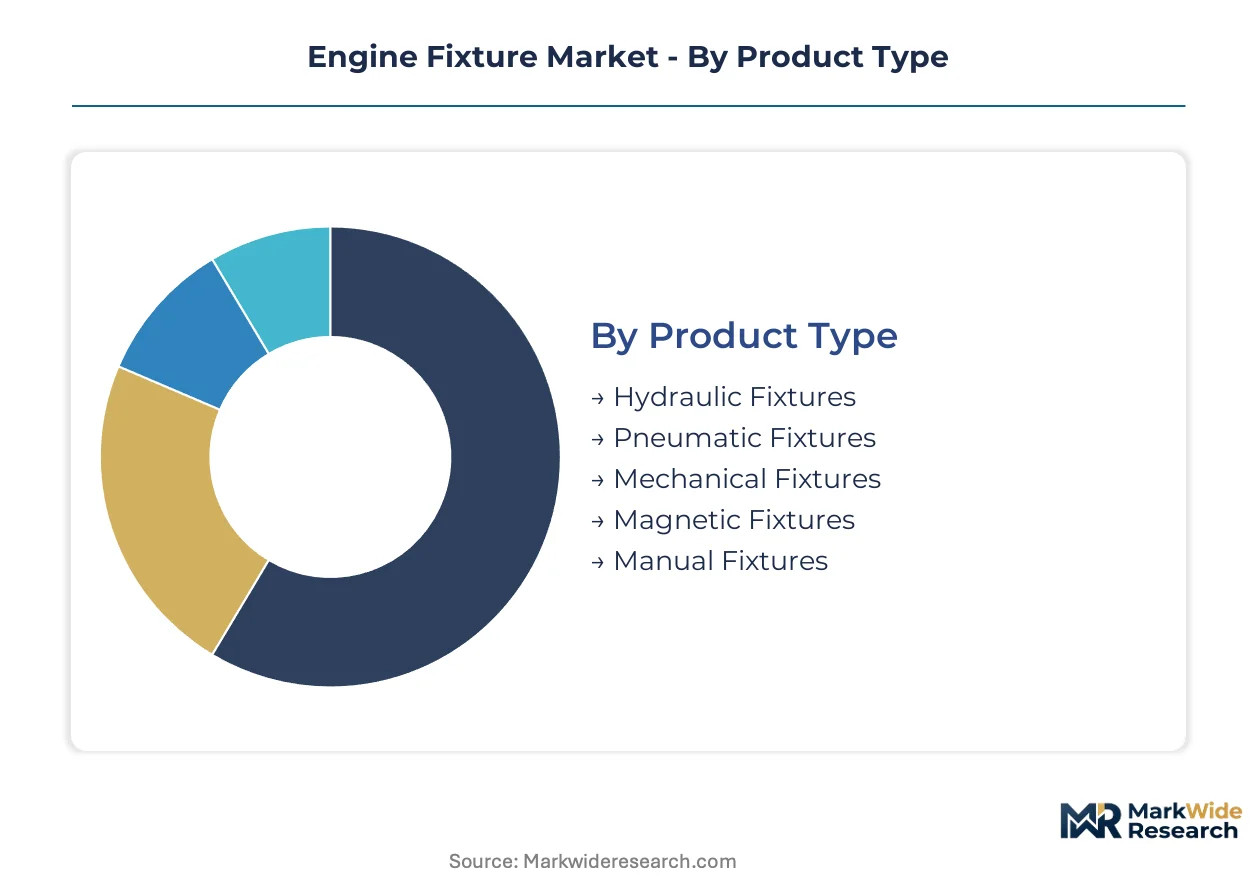
Engine fixture procurement channels diverge sharply by precision grade and automation level. OEM manufacturing plants favor integrated technology bundles, while aftermarket suppliers prioritize cost-optimized mechanical alternatives.
Product Type:
Channel mix varies by clamping force requirements and automation integration, with hydraulic and pneumatic systems dominating Tier-1 assembler contracts while manual fixtures persist in rebuild operations.
- Hydraulic Fixtures:These systems deliver consistent clamping force through pressurized fluid circuits, essential for heavy-duty engine block machining. Demand concentrates in German powertrain clusters where ISO 9001 mandates enforce 0.01 mm repeatability thresholds for high-volume cylinder boring operations.
- Pneumatic Fixtures:Compressed air actuation enables rapid cycling in automated assembly lines. Japanese and South Korean automotive markets are adopting these systems fastest as OEMs compress changeover times in hybrid engine production.
- Mechanical Fixtures:Screw and cam-actuated designs serve cost-sensitive aftermarket rebuilders with simpler maintenance protocols.
- Magnetic Fixtures:Electromagnetic workholding suits ferrous component finishing where minimal contact preserves surface integrity.
- Manual Fixtures:Hand-operated clamping persists in low-volume engine rebuilder shops where capital constraints limit automation investment.
By volume, hydraulic fixtures lead. By growth pace, pneumatic variants are climbing the fastest.
Technology:
Margin tiers separate digital-native platforms from legacy mechanical systems, with sensor-integrated solutions commanding premium positioning against basic CNC-compatible alternatives.
- CAD/CAM Integration:Digital twin workflows enable virtual interference detection before physical prototyping, compressing development cycles. Stuttgart engineering corridors drive adoption as Volkswagen Group and BMW unbundle fixture procurement from machining center bundles.
- Sensor-based Alignment:Photogrammetric and laser-tracker systems enable real-time datum correction. Tier-1 assemblers in Germany and Japan are expanding these installations fastest as inline metrology eliminates manual inspection bottlenecks.
- CNC Compatible:Standardized interfaces ensure interoperability across heterogeneous equipment fleets in North American powertrain expansions.
- Robotic Automation:Automated material handling integration displaces manual loading in high-throughput OEM lines.
- Modular Design:Standardized gripping architectures reduce changeover times and inventory complexity for multi-platform manufacturers.
CAD/CAM integration holds the largest installed base. Sensor-based alignment is gaining share fastest.
Application:
Customer type determines specification intensity, with OEM plants demanding multi-axis precision for core powertrain operations while rebuilders accept broader tolerances on peripheral components.
- Engine Assembly:Final powertrain integration requires fixture systems that locate and secure complete engine blocks during crankshaft installation and head decking. Munich and Stuttgart manufacturing corridors concentrate demand for hybrid platform compatibility.
- Valve Seat Machining:Precision grinding and cutting operations demand hardened steel fixtures with thermal stability. EPA emissions compliance is tightening sealing surface specifications, elevating fixture investment in US powertrain plants.
- Cylinder Honing:Cross-hatch pattern generation requires rotational workholding with vibration damping.
- Turbocharger Installation:Compact component handling needs specialized gripping for rotating assembly balance.
- Gear Fitting:Transmission integration fixtures synchronize with engine assembly lines in integrated powertrain facilities.
Engine assembly commands the greatest fixture volume. Valve seat machining is expanding most quickly.
End User:
Supply concentration maps to automotive OEM consolidation patterns, with surviving suppliers facing compressed qualification timelines and elevated performance guarantees.
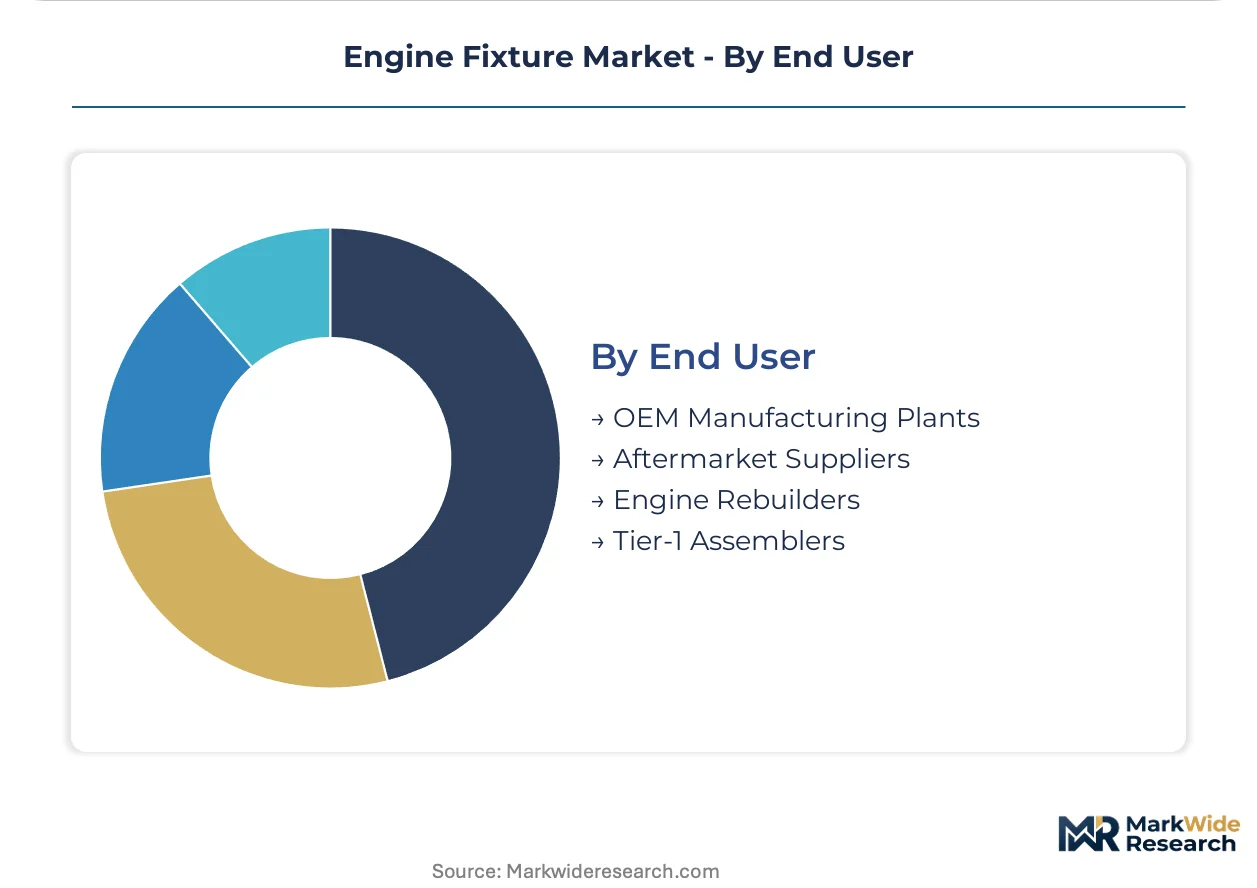
- OEM Manufacturing Plants:Original equipment manufacturers operate the most demanding procurement standards, requiring fixture interoperability across machining center fleets from multiple vendors. Toyota Motor and Volkswagen Group are driving unbundling trends that force standalone fixture suppliers to demonstrate cross-platform compatibility.
- Tier-1 Assemblers:Contract manufacturers serving OEM supply chains prioritize modular systems that adapt to model changeovers. These buyers are accelerating robotic automation adoption fastest as labor costs rise in Japanese and German manufacturing zones.
- Aftermarket Suppliers:Independent component producers favor cost-optimized mechanical fixtures for replacement part production.
- Engine Rebuilders:Remanufacturing operations utilize manual and basic hydraulic systems for lower-volume refurbishment cycles.
OEM manufacturing plants represent the largest addressable base. Tier-1 assemblers are showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German powertrain engineering corridors concentrate specialized fixture production for hybrid platforms, while Japanese and South Korean automotive clusters drive pneumatic system adoption for compressed changeover cycles.
United States
EPA emissions compliance tightens machining specifications for engine sealing surfaces across Michigan and Ohio powertrain plants. OSHA machine guarding standards extend fixture certification cycles for enclosure redesigns. Detroit-area manufacturing zones anchor demand for CNC-compatible workholding systems in high-volume cylinder boring operations.
Germany
Stuttgart and Munich engineering corridors specialize in hydraulic fixture development for internal combustion and hybrid engine platforms. REACH substance restrictions and RoHS compliance reshape surface treatment specifications toward trivalent chromium alternatives. Baden-Württemberg production clusters face geographic supply vulnerability as alloy steel price volatility compresses manufacturer margins.
Japan
Tier-1 assemblers accelerate sensor-based alignment adoption to eliminate manual inspection bottlenecks in multi-axis operations. METI industrial standards govern workholding safety protocols for automated engine lines. Nagoya manufacturing zones prioritize modular clamping architectures that reduce inventory complexity for multi-platform producers.
South Korea
OEM procurement unbundling from machining center bundles forces standalone fixture vendors to demonstrate cross-platform compatibility. MFDS regulatory frameworks do not directly govern industrial equipment, though national quality standards elevate precision specifications. Seoul Capital Area automotive clusters drive fastest pneumatic fixture adoption for hybrid engine production compression.
China
Dual carbon goals and MIIT industrial policies accelerate powertrain electrification strategies that reshape fixture demand profiles toward e-motor assembly platforms. GB standards for geometric tolerancing intersect with automotive OEM supply chain mandates. Yangtze River Delta manufacturing bases expand fixture procurement for stator winding and rotor balancing operations.
Engine Fixture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-grade tolerance capabilities bifurcating the vendor base between premium-positioned suppliers and cost-optimized manufacturers. The market structure consolidates around integrated machine tool ecosystems, modular gripping specialists, and cutting tool material science leaders. Three strategic archetypes dominate: bundled solution providers, standalone workholding architects, and component-scale fabricators. Competitive moves center on CAD/CAM integration partnerships and geographic expansion into electrification-focused automotive corridors.
Within the integrated technology tier, Haas Automation anchors bundled fixture solutions alongside machining center portfolios, while Sandvik Coromant exemplifies material science leadership through advanced workholding applications. SCHUNK occupies a dominant position in modular gripping architectures that serve automated engine lines. These three players represent distinct competitive vectors—machine tool integration, cutting tool convergence, and clamping system standardization—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Haas Automation |
| Sandvik Coromant |
| SMW-AUTOBLOK Group |
| SCHUNK |
| Jergens |
| Carr Lane Manufacturing |
| Forkardt International |
| Kitagawa Iron Works |
| DESTACO |
| Others |
Pricing and Supply Chain Analysis
Twenty-four-week lead times for hardened steel alloy deliveries concentrate pricing power among Baden-Württemberg fixture manufacturers who maintain strategic inventory positions. This inventory discipline allows premium-tier suppliers to enforce ISO 9001-certified pricing premiums while cost-optimized competitors absorb margin compression from spot-market alloy purchases.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European engine fixture procurement. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated hydraulic systems from basic CNC-compatible fixtures and manual rebuild-shop alternatives. Price differentiation hinges on certification grade and volume scale, with OEM manufacturing plants least sensitive to unit cost. Cost compression in economy-tier mechanical fixtures is intensifying because aftermarket rebuilders face capital constraints limiting automation investment.
Supply Chain Analysis
Port congestion on Hamburg-Rotterdam trade lanes elevates inbound logistics costs for alloy steel shipments originating from East Asian mills. Fixture production draws from German, Japanese, and Chinese manufacturing clusters, with hardened steel and precision locating pins as critical inputs. Single-source vulnerability concentrates in Baden-Württemberg hydraulic component specialists. Distribution runs through OEM direct procurement channels and Tier-1 assembler contract manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification strategies fragment fixture demand between legacy internal combustion and emerging e-motor architectures, creating specialized niches for suppliers with dual-competency portfolios.
For Market Incumbents: Consolidate around sensor-based alignment technology investments to defend against modular gripping specialists eroding share in automated engine lines. Deepen backward integration into hardened steel processing to offset alloy price volatility compressing contract margins. Prioritize CE marking eligibility maintenance as REACH substance restrictions reshape surface treatment specifications.
For New Entrants and Emerging Players: Aftermarket service-layer gaps in digital twin workflow support create entry points where incumbent fixture vendors under-serve independent engine rebuilders. Target South Korean automotive clusters for pneumatic fixture penetration where OEM procurement unbundling forces cross-platform compatibility demonstrations. Pursue CAD/CAM integration partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among Volkswagen Group and Toyota Motor compresses supplier qualification timelines and elevates performance guarantee requirements. Acquisition targets should display modular clamping architecture expertise with established presence in German or Japanese powertrain corridors. Monitor EPA emissions compliance tightening as the signal indicating accelerated fixture replacement cycles in US manufacturing plants.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Photogrammetric alignment contracts with Stuttgart engineering corridors accelerate Tier-1 assembler adoption. |
| Backward Integration into Alloy Processing | In-house hardened steel treatment insulates margins from spot-market volatility in Baden-Württemberg. |
| Modular Clamping Platform Launch | Standardized gripping architectures reduce changeover times for Nagoya multi-platform manufacturers. |
| Digital Twin Workflow Integration | CAD/CAM interoperability demonstrations satisfy Volkswagen Group unbundled procurement requirements. |
| E-Motor Fixture Architecture Development | Stator winding and rotor balancing workholding positions suppliers for Yangtze River Delta electrification investments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from machine tool manufacturers, and ISO certification registries. Primary interviews engaged plant engineers at OEM manufacturing facilities, procurement leads at Tier-1 automotive assemblers, aftermarket service heads at engine rebuild operations, and technical directors at hydraulic component suppliers. Secondary validation drew from production databases tracking vehicle powertrain output, IHS Markit registration statistics, and REACH compliance disclosure filings. Bottom-up fixture unit demand estimates triangulate against top-down powertrain production forecasts.
Segmentation dimensions modeled include fixture product type, technology integration level, application operation, and end-user procurement channel across the projection horizon. CAGRs derive from regression analysis against powertrain production indices and electrification adoption curves. Industry-specific forecast inputs incorporate EPA emissions compliance timelines and MIIT dual carbon policy implementation patterns affecting powertrain mix.
Forecasts assume regulatory continuity in REACH substance restrictions and OSHA machine guarding standards; material policy shifts would require re-modeling. Alloy steel price volatility and powertrain electrification acceleration represent primary forecast revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Rocker Arm Market