
 Automotive Armrest Market | 2026-2036
Automotive Armrest Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Armrest Market Analysis
Asset-light manufacturing partnerships and modular seating supply contracts is narrowing the field of full-system integrators capable of bidding on global OEM programs. Faurecia SA leverages its European seating architecture to anchor armrest modules within consolidated cockpit contracts. Lear Corporation competes through backward integration into foam and trim operations across North American truck platforms. TACHI-S Co. Ltd. specializes in Japanese OEM relationships, sustaining long-term supply agreements through co-located engineering teams.
An automotive armrest is a structural interior component mounted to center consoles, door panels, or seat frames, typically incorporating polypropylene substrates with polyurethane foam padding and surface trim to provide occupant forearm support and storage integration. The component serves ergonomic and aesthetic functions while housing electronic interfaces, ventilation ducts, or wireless charging modules in premium configurations. Center console armrests command the strongest margin pools as they integrate climate controls, USB ports, and sliding adjustment mechanisms across SUV and sedan platforms. Leather-trimmed variants lead in revenue contribution within the material dimension, though vinyl formulations gain ground in fleet-operator specifications where durability and cleanability outweigh tactile premium positioning.
NHTSA occupant protection standards and EPA volatile organic compound limits on interior materials shape armrest substrate and adhesive selection for US-bound production. EU REACH substance restrictions and ECHA SVHC disclosure requirements extend compliance obligations to leather tanning chemicals and flame-retardant foam additives. China MIIT passenger vehicle interior air quality standards and GB/T 27630 limits on formaldehyde emissions from plastic components add testing layers for suppliers serving domestic OEMs. Stakeholders must monitor how cascading regulatory timelines for recycled content mandates will force material substitution decisions before next-generation platform commitments lock in.
Market Dynamics
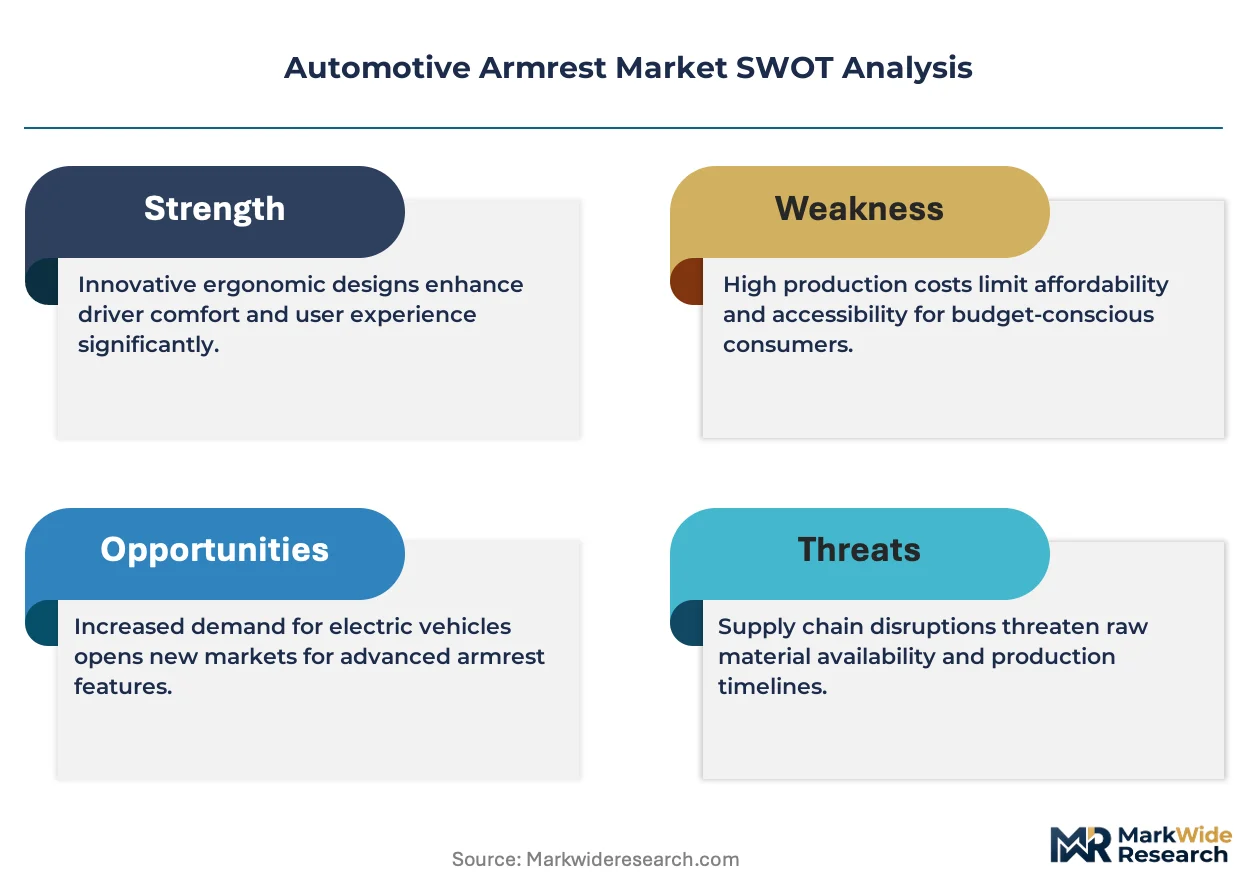
EU REACH substance restrictions on leather tanning chemicals and flame-retardant foam additives are forcing material substitutions across armrest supply chains before next-generation platform commitments lock in specifications. This regulatory pressure compounds with OEM consolidation of cockpit module sourcing, squeezing standalone armrest suppliers into tier-two positions.
Growth Catalysts
- MIIT interior air quality standards:China's GB/T 27630 formaldehyde emission limits for plastic components are accelerating domestic OEM upgrades of interior trim specifications across SUV and sedan lineups.
- Luxury electric vehicle platforms:Premium adjustable armrests with integrated climate controls and wireless charging modules are capturing expanded specification share as EV architectures prioritize cabin differentiation.
- Modular seating architectures:Consolidated cockpit contracts are embedding armrest modules within broader interior system packages, reducing engineering friction for full-system integrators.
Market Restraints
- Polyurethane foam input volatility:Petrochemical feedstock price swings compress margin stability for molded padding operations serving high-volume programs.
- Supplier concentration in East Asia:Polypropylene substrate and synthetic leather capacity clusters create geographic exposure to regional logistics disruptions and tariff escalations.
- ECHA SVHC disclosure requirements:Extended compliance obligations for leather tanning chemicals add testing layers and documentation burdens that extend quoting cycles.
Strategic Opportunities
- Recycled content mandates:Cascading regulatory timelines for post-consumer material quotas create first-mover advantage for suppliers with validated circular feedstock streams.
- Sensor-integrated surfaces:Convergence of capacitive touch interfaces with haptic feedback modules enables premium positioning in autonomous vehicle cabin concepts.
- Fleet-operator specifications:Vinyl formulations with enhanced durability and cleanability protocols are displacing leather in commercial vehicle segments where lifecycle cost dominates procurement criteria.
Industry Challenges
- Cross-functional engineering talent scarcity:Integration of electronic interfaces, ventilation ducts, and wireless charging modules demands combined mechanical, electrical, and software competencies that outpace workforce development pipelines.
- Platform lock-in timing:Material substitution decisions for recycled content and low-emission alternatives must precede tooling commitments by 24-36 months, compressing validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Armrest Market |
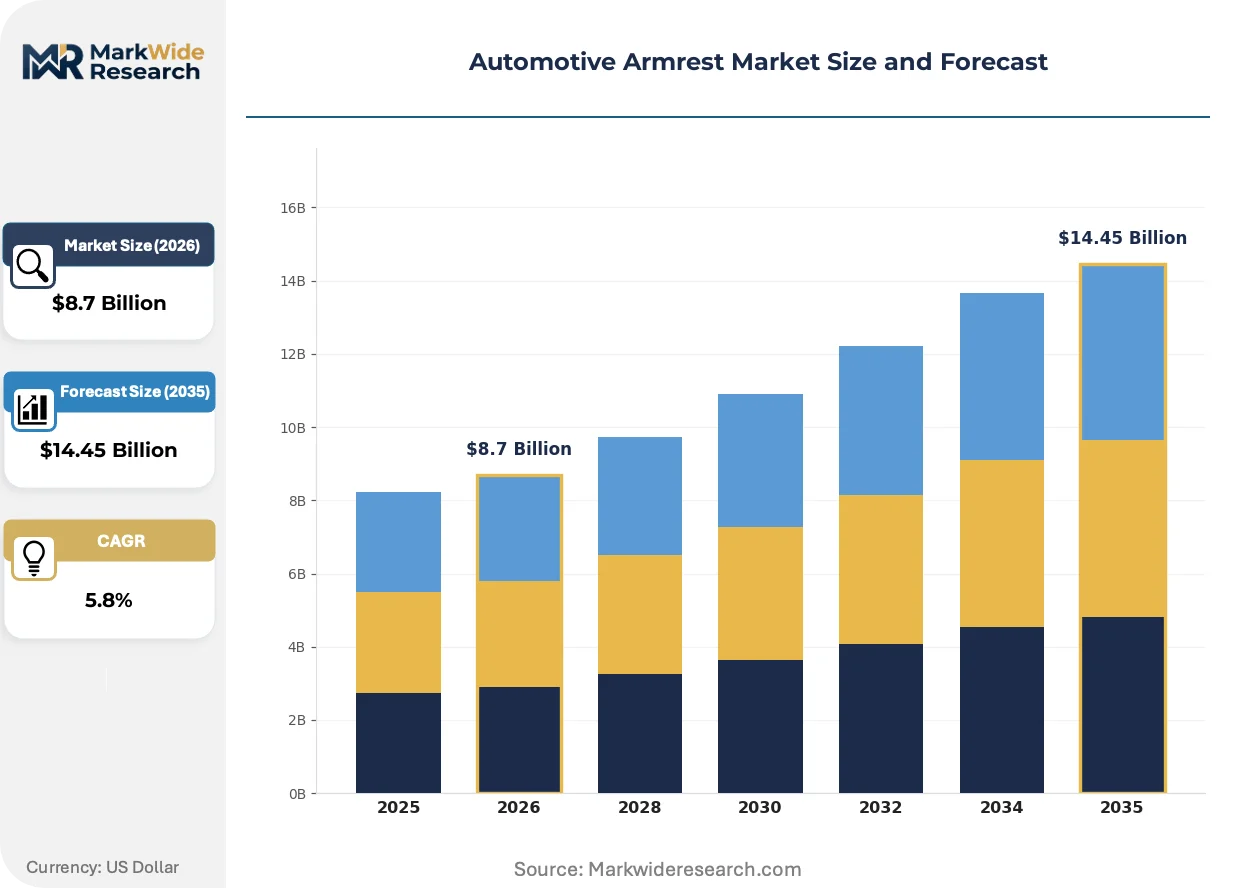
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Armrests, Center Console Armrests, Door Armrests, Adjustable Armrests Material: Leather, Fabric, Plastic, Vinyl Vehicle Type: SUVs, Sedans, Trucks, Vans End User: Original Equipment Manufacturers, Aftermarket Providers, Car Owners, Fleet Operators |
| Companies Covered | Adient plc, Faurecia SA, Grammer AG, Toyota Boshoku, Piston Group, TACHI-S Co. Ltd., Ningbo Jifeng Auto Parts Co., Ltd, Lear Corporation, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Armrest Market Emerging Trajectories
Capacitive touch surfaces and haptic feedback modules are digitizing the occupant-armrest interface, transforming a passive structural component into an active control node. This shift reconfigures supplier value capture toward electronics integration and away from pure trim operations.
Sensor-embedded polyurethane foam substrates are digitizing pressure mapping and gesture recognition capabilities within armrest surfaces. German luxury OEMs are specifying these modules for Level 3 autonomous vehicle programs where cabin reconfiguration demands seamless interface transitions. The technology is digitizing traditional tier boundaries as seating suppliers acquire electronics capabilities and electronics suppliers acquire trim expertise.
EU REACH compliance deadlines for SVHC disclosure in leather tanning chemicals and flame-retardant additives are compressing qualified material lists. Suppliers serving European-bound production must reformulate coverings and foam substrates or exit specification pools. The regulation most affects center console armrests with integrated climate controls, where multi-material bonding complexity amplifies traceability requirements.
Direct sourcing contracts between OEMs and material compounders are fragmenting traditional tier-one relationships. Fleet operators and commercial vehicle buyers now specify vinyl durability grades independently of seating supplier recommendations, unbundling material selection from module integration. This pattern concentrates in North American truck platforms where lifecycle cost analysis dominates procurement committees and aftermarket replacement cycles create secondary revenue stakes.
Automotive Armrest Market Segmentation
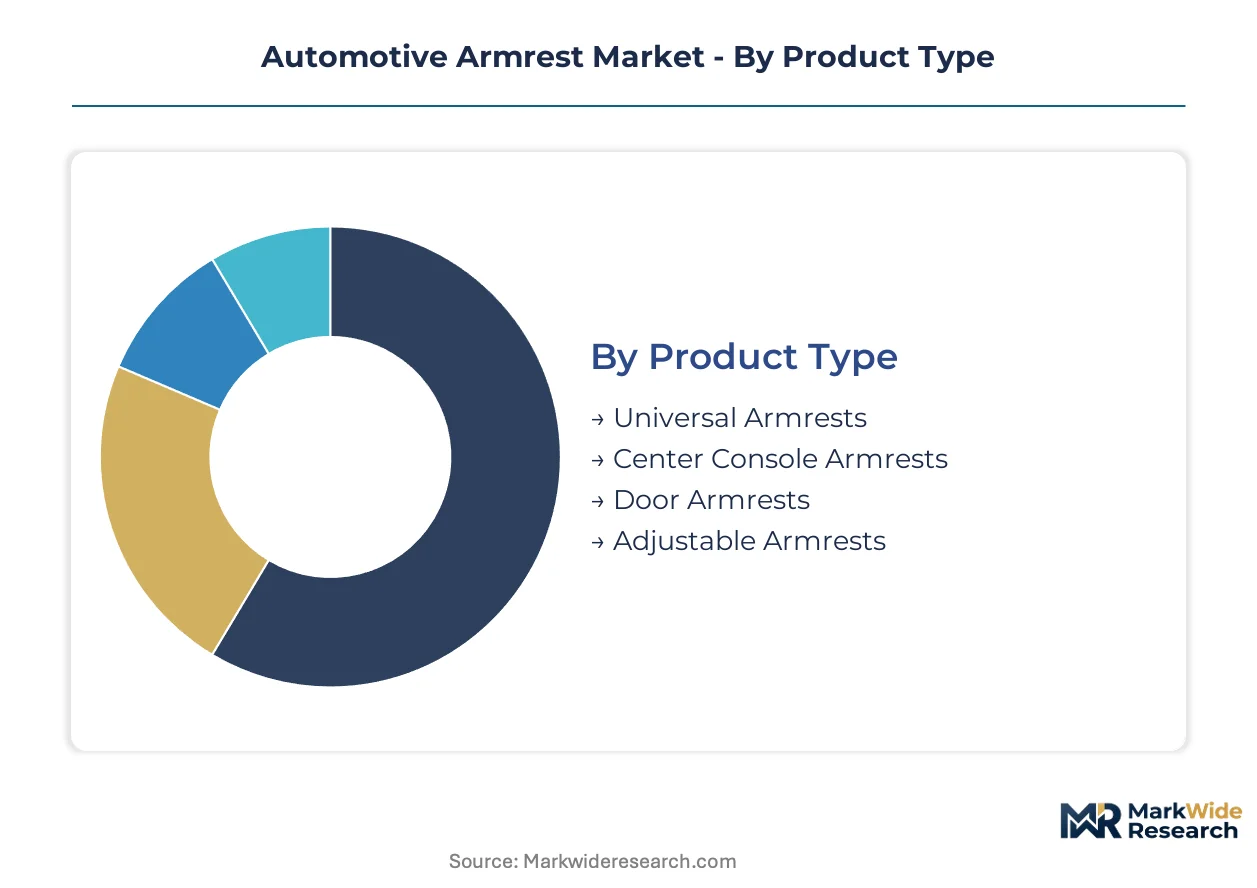
Armrest specification varies sharply across vehicle architectures and procurement channels, with center console integration and material selection driving divergent margin structures. Understanding these segment boundaries clarifies where suppliers can defend pricing power versus where volume aggregation dominates.
Product Type:
Application context determines engineering complexity, with console-mounted variants demanding multi-functional integration against simpler door-mounted alternatives.
- Center Console Armrests:These modules integrate polypropylene substrates with polyurethane foam padding, housing climate controls, USB ports, and sliding adjustment mechanisms. Demand concentrates in China as domestic OEMs upgrade interior trim specifications across SUV and sedan lineups, with GB/T 27630 formaldehyde emission limits accelerating specification upgrades.
- Door Armrests:Mounted to interior door panels, these units prioritize ergonomic forearm positioning alongside window switch integration. Fleet operators in North American truck platforms specify vinyl durability grades independently of seating supplier recommendations, unbundling material selection from module integration.
- Universal Armrests:Aftermarket-fitment designs accommodate multiple vehicle architectures through adjustable mounting hardware.
- Adjustable Armrests:Premium electric vehicle platforms specify these with integrated wireless charging modules and capacitive touch surfaces.
Center Console Armrests hold installed capacity. Adjustable Armrests is rotating up the share rankings.
Material:
Cost tier and tactile positioning split procurement committees, with durability protocols displacing premium positioning in commercial segments.
- Leather:Tanned hide coverings deliver tactile premium positioning through natural grain texture and aging patina. EU REACH substance restrictions on leather tanning chemicals are forcing material substitutions across supply chains before next-generation platform commitments lock in specifications.
- Vinyl:Synthetic formulations with enhanced durability and cleanability protocols are displacing leather in fleet-operator specifications where lifecycle cost dominates procurement criteria and aftermarket replacement cycles create secondary revenue stakes.
- Fabric:Woven textile coverings reduce material cost while permitting color-matching flexibility for mass-market platforms.
- Plastic:Molded polypropylene substrates form the structural foundation across all surface trim categories.
Leather holds installed capacity. Vinyl is rotating up the share rankings.
Vehicle Type:
Platform architecture dictates armrest specification intensity, with passenger-centric designs demanding richer feature integration than utility-focused alternatives.
- SUVs:Elevated seating positions and expanded center console footprints accommodate larger armrest modules with integrated storage and climate ducting. Luxury electric vehicle platforms within this segment are expanding adoption of premium adjustable armrests with integrated controls as cabin differentiation priorities intensify.
- Sedans:Constrained console dimensions prioritize slim-profile designs with sliding mechanisms to accommodate varying occupant statures.
- Trucks:Commercial duty cycles emphasize durability over tactile refinement, with fleet operators specifying vinyl grades based on lifecycle cost analysis.
- Vans:Multi-occupant configurations drive standardized, cost-optimized armrest specifications across seating rows.
SUVs hold installed capacity. Sedans is rotating up the share rankings.
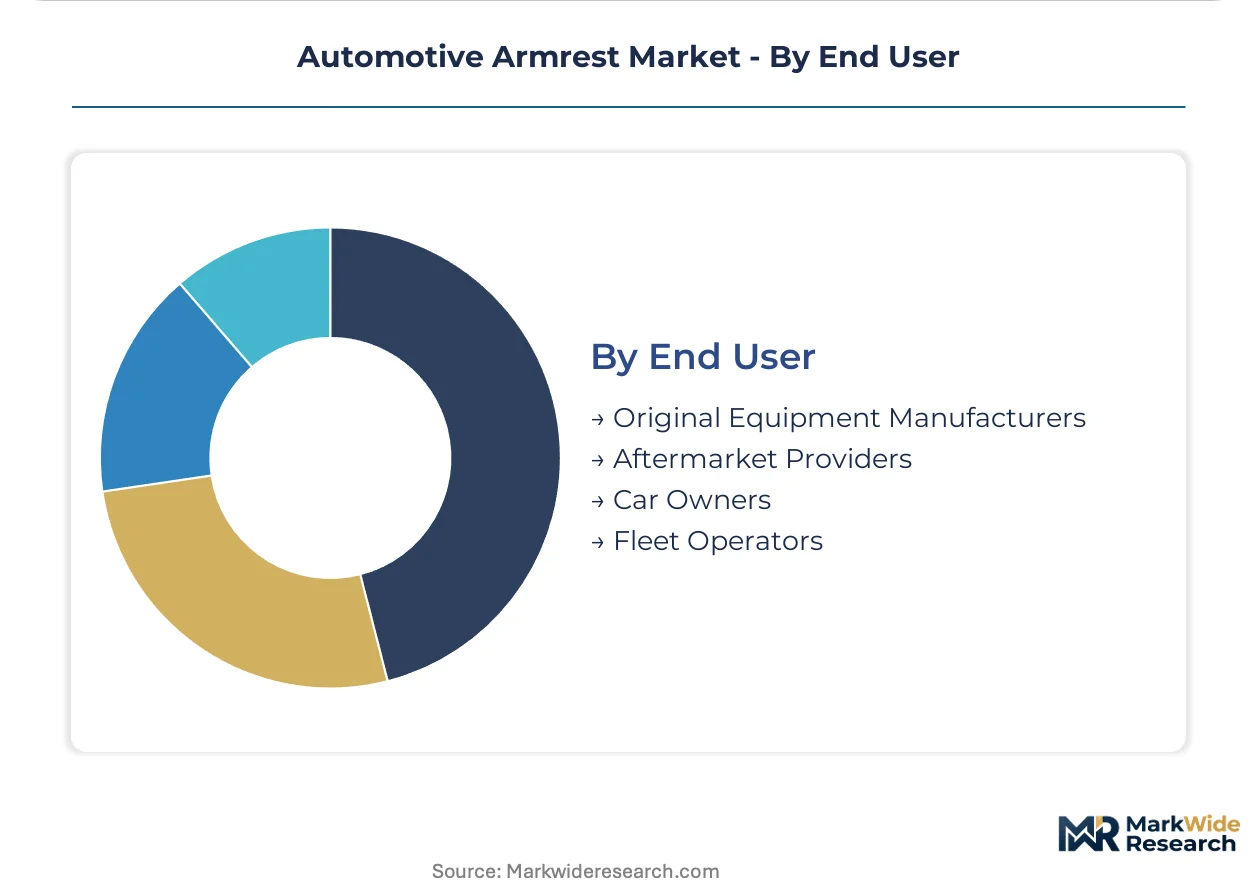
End User:
Customer type determines procurement authority and specification influence, with fragmented aftermarket channels contrasting consolidated OEM sourcing.
- Original Equipment Manufacturers:Consolidated cockpit module sourcing is embedding armrest modules within broader interior system packages, reducing engineering friction for full-system integrators capable of bidding on global programs.
- Fleet Operators:Lifecycle cost analysis dominates procurement committees, with durability and cleanability protocols outweighing tactile premium positioning.
- Aftermarket Providers:Universal-fitment inventory competes on price and installation convenience rather than integrated functionality.
- Car Owners:Individual replacement demand concentrates in wear-prone surface trim rather than structural substrate failures.
Original Equipment Manufacturers hold installed capacity. Fleet Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT interior air quality standards are accelerating specification upgrades across domestic OEM lineups, while EU REACH substance restrictions force material substitutions in European-bound production. These regulatory drivers are reshaping regional competitive positioning as suppliers adapt to divergent compliance timelines.
China
Domestic OEMs are upgrading interior trim specifications across SUV and sedan platforms to meet GB/T 27630 formaldehyde emission limits. MIIT passenger vehicle interior air quality standards add testing layers for plastic component suppliers. The Yangtze River Delta cluster hosts concentrated seating supplier engineering teams co-located with SAIC and Geely manufacturing bases.
Germany
Luxury electric vehicle platforms from BMW and Mercedes-Benz specify premium adjustable armrests with integrated climate controls and wireless charging modules. EU REACH compliance deadlines for SVHC disclosure in leather tanning chemicals compress qualified material lists. The Baden-Württemberg region anchors cockpit module integration facilities serving consolidated OEM sourcing contracts.
United States
Fleet operators in commercial truck segments specify vinyl durability grades based on lifecycle cost analysis, displacing leather in procurement committees. NHTSA occupant protection standards shape substrate and adhesive selection for US-bound production. The Midwest manufacturing corridor concentrates molded foam operations serving Detroit Three platform commitments.
Japan
Long-term supply agreements with Toyota and Honda sustain tier-one positioning through co-located engineering teams and just-in-time delivery protocols. METI industrial standards influence material qualification timelines for export-bound production. The Aichi Prefecture cluster integrates armrest modules within broader seating architecture contracts.
South Korea
Hyundai-Kia platform differentiation strategies prioritize cabin interior upgrades as competitive leverage against Japanese and European rivals. MFDS and KATRI standards govern interior material emissions testing for domestic and export markets. The Seoul Capital Area concentrates electronics-integrated surface development for autonomous vehicle programs.
Automotive Armrest Market Vendor Landscape
On the supply side, the industry is consolidating around full-system integrators capable of bidding on global OEM cockpit module contracts. Asset-light manufacturing partnerships are narrowing the field of standalone armrest suppliers, pushing them into tier-two positions. Three archetypes dominate: European seating architecture specialists, North American foam-and-trim integrators, and Japanese OEM-aligned engineering partners. Competitive moves concentrate on backward integration into foam operations and strategic co-location with OEM engineering centers.
Within the European specialist tier, Faurecia SA anchors consolidated cockpit contracts through its seating architecture capabilities. Lear Corporation exemplifies the North American integrator archetype with captive foam and trim operations. TACHI-S Co. Ltd. occupies the Japanese OEM-aligned position, sustaining long-term agreements through embedded engineering teams. These three represent divergent geographic and structural approaches to module integration.
| Leading Market Players |
|---|
| Adient plc |
| Faurecia SA |
| Grammer AG |
| Toyota Boshoku |
| Piston Group |
| TACHI-S Co. Ltd. |
| Ningbo Jifeng Auto Parts Co., Ltd |
| Lear Corporation |
| Magna International |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cluster anchors global polyurethane foam and polypropylene substrate capacity, concentrating bargaining power among compounders serving tier-one seating integrators. OEM consolidation of cockpit module sourcing transfers price pressure upstream, compressing margin pools for standalone armrest suppliers locked into fixed-price contracts.
Pricing Analysis
Certification level (REACH-compliant, GB/T 27630-grade, NHTSA-certified) creates the primary spread between premium and standard tiers. Pricing stratifies across leather-trimmed, vinyl-durability, and fabric-economy tiers, with fleet-operator procurement committees driving cost compression in commercial vehicle segments. Price differentiation reflects material emission compliance burdens and integrated electronics content. Margins are tightening due to petrochemical feedstock volatility and extended quoting cycles from ECHA SVHC documentation requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese OEMs strain working capital for molders serving consolidated cockpit contracts. Manufacturing gravity centers on China, Germany, and Mexico, with polypropylene substrate and synthetic leather capacity clustering in East Asia. The chain draws from petrochemical feedstocks, tanned hides, and electronic control modules. Single-source vulnerability in polyurethane foam additives amplifies tariff exposure. Distribution runs through tier-one seating integrators bidding on global OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM consolidation of cockpit module sourcing has shifted buyer power toward full-system integrators, fragmenting standalone armrest suppliers into tier-two positions. Three stakeholder archetypes face divergent imperatives.
For Market Incumbents: Harden backward integration into captive foam operations to defend margin pools against petrochemical volatility. Deepen co-location with OEM engineering centers in the Yangtze River Delta and Baden-Württemberg to secure platform lock-in timing. Certification investment in REACH-compliant and GB/T 27630-grade material streams anchors specification share as regulatory timelines compress.
For New Entrants and Emerging Players: Pursue fleet-operator vinyl specifications in North American truck platforms, where lifecycle cost analysis has unbundled material selection from module integration. Target sensor-integrated surface development for autonomous vehicle programs in the Seoul Capital Area as the most penetrable white space. A go-to-market angle through direct material compounding contracts bypasses tier-one seating supplier gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electronics-integrated seating suppliers over pure trim operations as capacitive touch and haptic feedback modules digitize the armrest interface. Long-term viability rests on validated circular feedstock streams ahead of cascading recycled content mandates. The signal to watch is OEM platform commitment timing for next-generation EV architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Operations | Captive polyurethane molding insulates margin pools from petrochemical feedstock volatility. |
| REACH-Compliant Material Reformulation | Validated low-emission substrates preserve specification access for European-bound production. |
| Co-Located Engineering Teams | Embedded presence at SAIC and Geely bases accelerates platform lock-in ahead of tooling commitments. |
| Sensor-Integrated Surface Development | Capacitive touch modules capture value shift toward electronics integration in autonomous cabins. |
| Circular Feedstock Validation | Post-consumer material quotas create first-mover advantage as recycled content mandates cascade. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with tier-one supplier procurement officers, OEM platform engineers, and aftermarket distributors; and secondary validation through vehicle production databases, IHS Markit registration data, customs records, and SEC filings from seating architecture specialists. Bottom-up segment sizing triangulated against top-down market aggregation.
Forecast inputs spanned vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the analysis window. CAGRs derived from segment-level growth rate blending with OEM platform rollout schedules and regulatory compliance timelines. Modeled variables included GB/T 27630 adoption curves, REACH SVHC list expansion, and EV cabin differentiation intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese domestic suppliers or accelerated OEM insourcing would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Structural Sheet Market