
 Automotive Strut Bar Market | 2026-2036
Automotive Strut Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Strut Bar Market Analysis
OEM procurement concentration is shifting toward tier-one chassis integrators as vehicle platforms consolidate. Eibach leverages its spring-and-bar bundled supply relationships to sustain long-term contracts with European performance divisions. Cusco dominates motorsports-derived aftermarket channels across Asia-Pacific. Ultra Racing competes aggressively on price in Southeast Asian tuner markets through direct-to-garage distribution.
An automotive strut bar is a rigid brace spanning the suspension towers of a vehicle's chassis, typically manufactured from hollow or solid aluminum extrusions, seam-welded steel tubing, or pre-preg carbon fiber layups, engineered to reduce torsional flex and sharpen steering response under lateral load. Front strut bars occupy the largest installed base due to universal compatibility with MacPherson strut architectures, while carbon fiber variants command premium positioning among weight-sensitive track applications. Adjustable strut bars capture the fastest growth trajectory as electronic damper interfaces and active suspension calibration demand precise preload tuning.
NHTSA chassis safety guidelines and EPA material sourcing disclosures shape North American product compliance pathways, while Japan's JIS standards govern fatigue-test protocols for bonded aluminum joints. The EU AI Act and CE marking requirements are beginning to intersect with electronically adjustable strut systems. Stakeholders must monitor how software-defined vehicle architectures redefine the boundary between passive bracing and active chassis control.
Market Dynamics
Vehicle electrification is fundamentally altering chassis load distribution, forcing strut bar manufacturers to engineer braces that accommodate battery pack mass while maintaining torsional rigidity across heavier platforms.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance mandates are accelerating substitution of bonded aluminum joints with mechanical fastening systems that eliminate fluorinated gas curing processes.
- MacPherson strut architecture proliferation:Front-wheel-drive platforms continue dominating mass-market production, sustaining universal fitment demand for front strut bars across compact and mid-size segments.
- Track-day participation:Amateur motorsports enrollment in Germany and Japan is expanding the addressable base for adjustable preload systems among weekend performance drivers.
Market Restraints
- Aluminum extrusion cost volatility:Energy-intensive smelting operations expose hollow bar producers to electricity price spikes concentrated in European manufacturing corridors.
- Carbon fiber supply concentration:Pre-preg layup capacity clusters in Japanese and South Korean facilities, creating single-source vulnerability for premium track-grade variants.
- MacPherson architecture substitution:Multi-link rear suspensions in luxury electric vehicles eliminate upper mount points, removing rear strut bar installation feasibility.
Strategic Opportunities
- Software-defined chassis calibration:Electronically adjustable strut bars that interface with active damper control systems represent unoccupied white space in OEM integration contracts.
- Southeast Asian tuner channel expansion:Direct-to-garage distribution models bypass traditional wholesale markups in Indonesia and Thailand aftermarket segments.
- EU AI Act intersection:CE marking pathways for sensor-integrated braces create first-mover advantage for suppliers capable of embedded load-cell telemetry.
Industry Challenges
- Fatigue-test protocol harmonization:JIS bonded joint standards diverge from NHTSA chassis safety guidelines, forcing dual certification investments for cross-border suppliers.
- Active suspension integration complexity:Electronic damper interfaces require firmware compatibility layers that strain traditional mechanical engineering competencies.
- Pre-preg autoclave capacity constraints:Carbon fiber variant lead times extend when motorsports demand surges compete for limited curing oven availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Strut Bar Market |
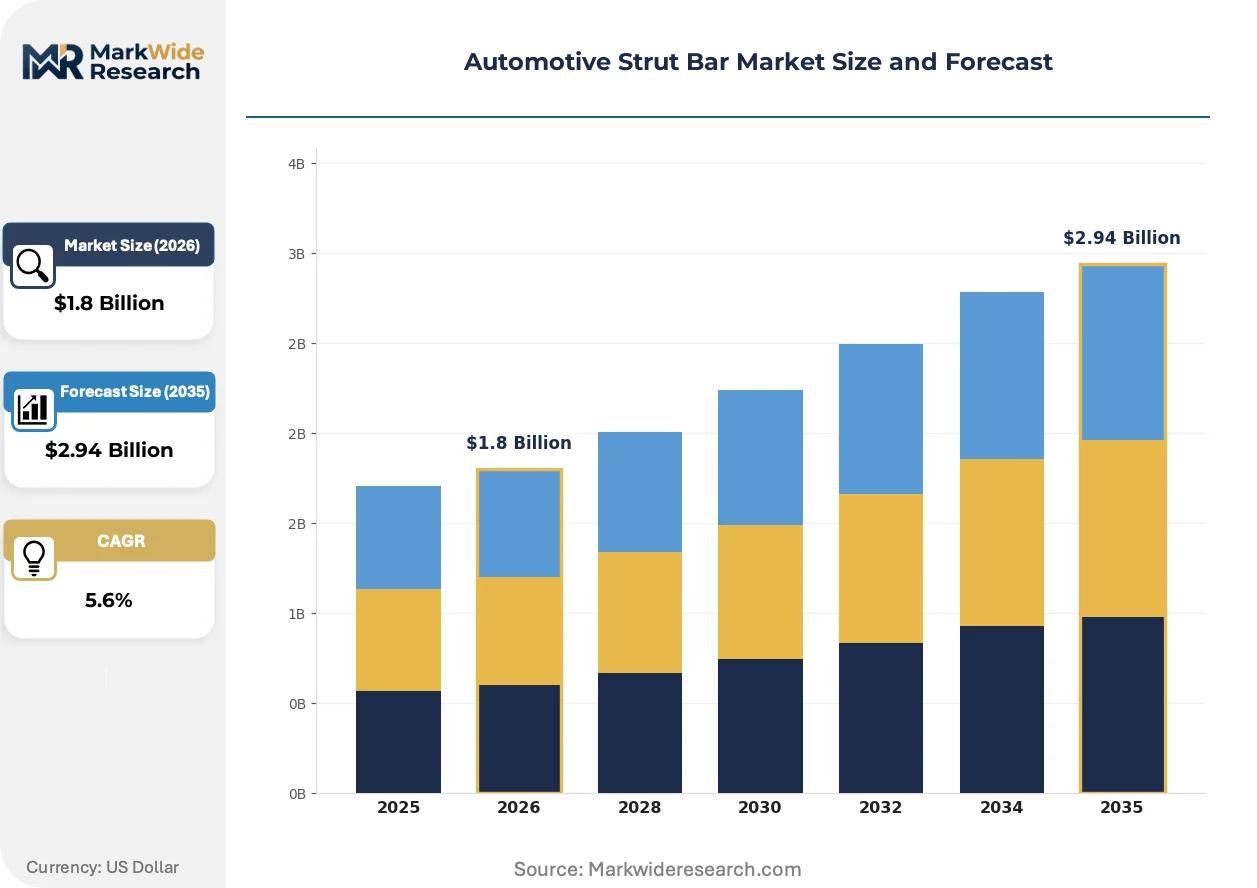
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Strut Bars, Rear Strut Bars, Adjustable Strut Bars, Fixed Strut Bars Material: Aluminum, Steel, Carbon Fiber, Polycarbonate Application: Sport Cars, Luxury Vehicles, Off-Road Vehicles, Compact Cars End User: DIY Enthusiasts, Performance Tuners, Automotive Manufacturers, Commercial Fleets |
| Companies Covered | Heidts, Sparco, Ultra Racing, Eibach, H&R Special Springs, Whiteline, Cusco, KYB, Bilstein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Strut Bar Market Emerging Trajectories
Strut bar engineering is converging with active chassis control architectures, blurring the historical boundary between passive bracing and electronically mediated suspension management.
Preload-adjustable strut bars with integrated load sensors are automating real-time stiffness calibration based on lateral acceleration inputs. Performance divisions at German OEMs are piloting these systems for track-focused trim levels. This convergence is automating the transition from fixed aftermarket upgrades to software-tunable chassis components.
REACH substance restrictions are eliminating hexavalent chromium surface treatments for seam-welded steel tubing. European suppliers are migrating to zinc-nickel plating chemistries that satisfy corrosion resistance without SVHC classification. Bonded aluminum joint producers face accelerated validation timelines to certify alternative adhesive formulations.
Direct-to-consumer fitment configurators are displacing traditional counter-based sales in aftermarket channels. Southeast Asian tuner garages now specify vehicle VINs to receive pre-validated hardware kits with installation torque specifications. This channel compression is most visible in Indonesia's independent workshop ecosystem, where distributor margins previously captured 35-40 percent of end-user pricing.
Automotive Strut Bar Market Segmentation
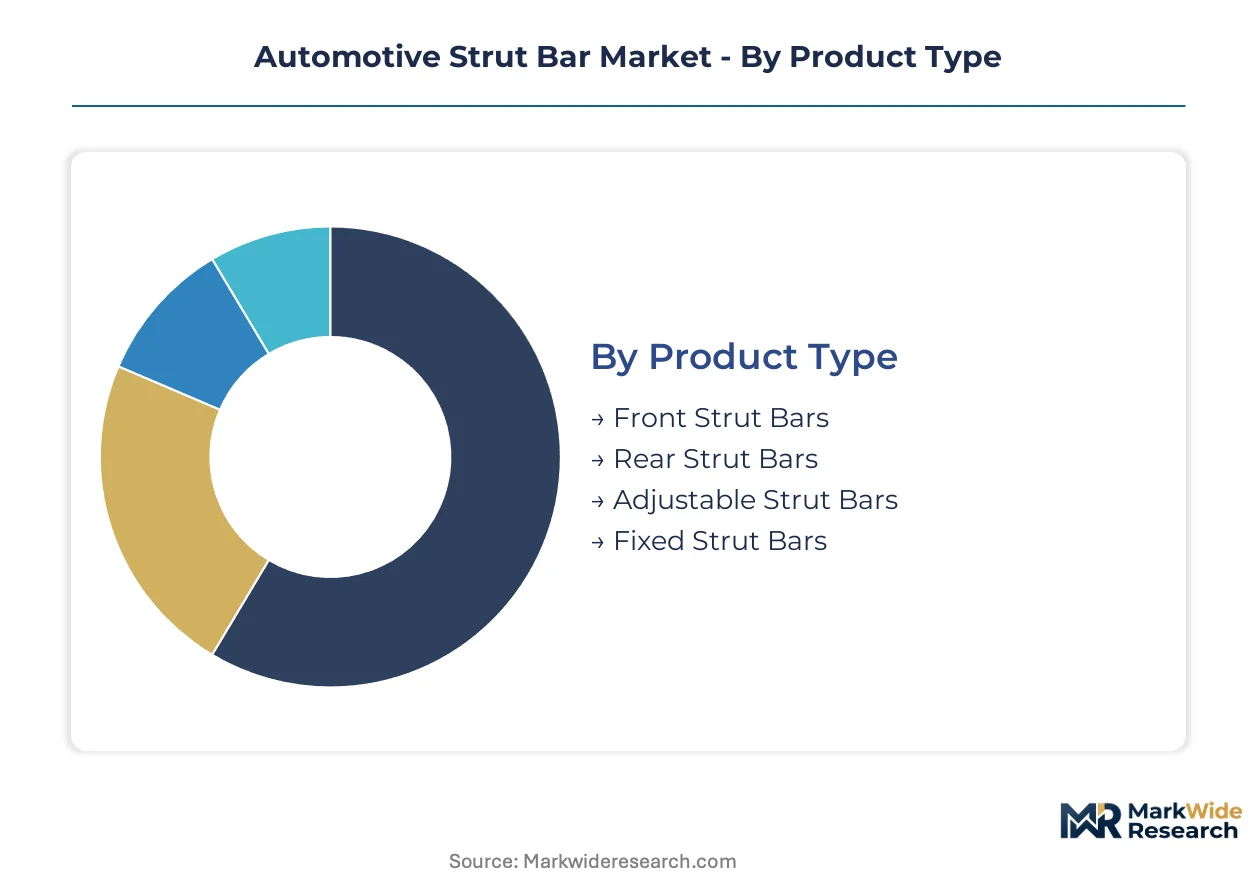
Strut bar segmentation reflects divergent engineering priorities across vehicle architectures and buyer sophistication levels. Material selection and adjustability features separate premium track-grade systems from mass-market fitments, while procurement channels fragment between OEM chassis integrators and direct-to-garage aftermarket distributors.
Product Type:
Adjustability and mounting position distinguish buyer willingness to pay for calibration control versus baseline chassis reinforcement.
- Front Strut Bars:These braces span the MacPherson strut towers at the front bulkhead, manufactured from hollow aluminum extrusions or seam-welded steel tubing. Demand concentrates in Germany's compact and mid-size production corridors where front-wheel-drive platforms dominate mass-market assembly. MacPherson architecture proliferation sustains universal fitment requirements across high-volume segments.
- Adjustable Strut Bars:Preload-tunable systems incorporate threaded collars or eccentric bushings for stiffness calibration. Performance tuners in Japan's motorsports clusters drive adoption as electronic damper interfaces and active suspension systems demand precise chassis tuning. These configurations are expanding most quickly among weekend track-day participants seeking real-time handling adjustability.
- Rear Strut Bars:Brace configurations for rear suspension towers, typically hollow aluminum or steel tube constructions.
- Fixed Strut Bars:Non-adjustable rigid braces offering baseline torsional rigidity without calibration capability.
Front strut bars lead volumes today; adjustable variants are gaining share fastest.
Material:
Weight-to-stiffness ratios and corrosion compliance separate motorsports-grade specifications from fleet-service durability requirements.
- Aluminum:Hollow extrusions dominate mass-market production due to favorable strength-to-weight ratios and compatibility with mechanical fastening systems. European suppliers face REACH-mandated shifts away from bonded joints toward bolted architectures that eliminate fluorinated gas curing processes.
- Carbon Fiber:Pre-preg layup constructions command premium positioning in weight-sensitive track applications. Japanese and South Korean autoclave capacity constraints create supply bottlenecks when motorsports demand surges compete for limited curing oven availability.
- Steel:Seam-welded tubing offers cost-optimized durability for commercial fleet applications.
- Polycarbonate:Emerging composite alternative for low-load aesthetic applications in show-vehicle segments.
Aluminum extrusions anchor current production volumes; carbon fiber shows the steepest expansion trajectory among premium tiers.
Application:
Chassis load characteristics and buyer performance expectations determine material specification and adjustability feature bundling.
- Sport Cars:Track-focused vehicles demand carbon fiber or high-grade aluminum systems with integrated load-sensor telemetry. German OEM performance divisions pilot electronically adjustable configurations that interface with active damper control systems.
- Luxury Vehicles:Multi-link rear suspensions in electric luxury platforms eliminate upper mount points, constraining rear strut bar feasibility while front applications persist for steering precision.
- Off-Road Vehicles:Heavy-duty steel constructions prioritize impact resistance over weight minimization for terrain-loaded chassis.
- Compact Cars:High-volume front-wheel-drive platforms sustain standardized aluminum front strut bar fitments across MacPherson architectures.
Compact cars generate the highest unit volumes; sport cars command the strongest value concentration per vehicle.
End User:
Technical sophistication and procurement channel access separate professional tuners from casual DIY installers and fleet maintenance operations.
- Performance Tuners:Professional installation shops and motorsports specialists specify preload-adjustable systems with VIN-validated fitment kits. Southeast Asian direct-to-garage distribution models bypass traditional wholesale markups in Indonesia and Thailand aftermarket channels.
- DIY Enthusiasts:End consumers purchasing through direct-to-consumer configurators that specify torque specifications and installation guidance. Channel compression is most visible in Indonesia's independent workshop ecosystem.
- Automotive Manufacturers:OEM chassis integrators procuring bundled spring-and-bar assemblies for platform consolidation strategies.
- Commercial Fleets:Maintenance operations prioritizing durability and standardized replacement intervals over performance optimization.
Automotive manufacturers dominate procurement volumes today; performance tuners are expanding fastest as electrification alters aftermarket upgrade patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's performance divisions generate premium-tier demand that contrasts sharply with Indonesia's price-sensitive tuner channels, revealing how procurement sophistication fragments across mature and emerging automotive ecosystems.
Germany
OEM chassis integrators in Stuttgart and Munich bundle spring-and-bar assemblies for platform consolidation strategies. The EU F-Gas Regulation and REACH compliance mandate mechanical fastening substitutions that eliminate fluorinated gas curing in bonded aluminum joints. Baden-Württemberg's manufacturing corridor hosts fatigue-test laboratories certifying preload-adjustable systems for track-focused trim levels.
Japan
Weekend track-day participants in Kansai and Kanto regions drive demand for electronically adjustable strut bars with integrated load-sensor telemetry. METI and JIS standards govern bonded aluminum joint validation protocols that diverge from North American test methodologies. Nagoya's motorsports component clusters specialize in carbon fiber pre-preg layups constrained by autoclave capacity competition.
United States
Performance tuners in Southern California and Texas specify VIN-validated hardware kits through direct-to-consumer configurators. NHTSA chassis safety guidelines and EPA material sourcing disclosures shape compliance pathways for hollow aluminum extrusion producers. Michigan's automotive engineering corridors pilot software-defined chassis calibration interfaces with active damper control systems.
Indonesia
Independent workshop ecosystems in Jakarta and Surabaya bypass traditional wholesale markups through direct-to-garage distribution models. The country's national automotive regulator enforces import certification for suspension modification components. Java's tuner garage networks compress distributor margins that previously captured 35-40 percent of end-user pricing.
South Korea
Carbon fiber variant producers face supply bottlenecks when motorsports demand surges compete for limited autoclave curing capacity. The country's national industrial standards body aligns fatigue-test protocols with broader Asia-Pacific certification frameworks. Gyeonggi-do's composite manufacturing facilities supply pre-preg layup constructions for weight-sensitive track applications.
Automotive Strut Bar Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold differentiated positions in motorsports-derived channels. The vendor base organizes around bundled chassis integrators, standalone performance component fabricators, and direct-to-garage aftermarket distributors. Three strategic archetypes dominate: tier-one platform suppliers, premium track-grade specialists, and price-optimized volume players. Competitive moves concentrate on spring-and-bar bundled procurement contracts and Southeast Asian distribution network expansion.
Within the premium track-grade tier, Eibach and Cusco exemplify contrasting geographic specializations. H&R Special Springs occupies a position among German fabricators emphasizing bundled supply relationships. Ultra Racing anchors the price-competitive vector in Southeast Asian tuner markets. These three entities represent how procurement channel access and regional manufacturing proximity stratify competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Heidts |
| Sparco |
| Ultra Racing |
| Eibach |
| H&R Special Springs |
| Whiteline |
| Cusco |
| KYB |
| Bilstein |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany's Baden-Württemberg manufacturing corridor anchor premium-tier pricing discipline through captive spring-and-bar bundled production, while Southeast Asian direct-to-garage distributors compress markups through channel disintermediation that eliminates traditional wholesale layers.
Pricing Analysis
Capacity additions in South Korean autoclave facilities are reshaping price floors for carbon fiber track-grade variants. Three-tier pricing structure across premium, standard, and economy levels separates motorsports-certified pre-preg layups from hollow aluminum fleet fitments and seam-welded steel commercial applications. Cost compression in Indonesian tuner channels is intensifying because direct-to-garage distribution bypasses 35-40 percent distributor margins previously embedded in end-user pricing. DIY enthusiasts exhibit highest price sensitivity; German OEM performance divisions demonstrate lowest sensitivity due to bundled chassis integration contracts.
Supply Chain Analysis
Freight cost volatility from Japanese and South Korean pre-preg autoclave clusters to European assembly plants strains just-in-time delivery commitments for carbon fiber variants. Raw material flows draw from German aluminum extrusion corridors, Japanese bonded joint adhesive formulators, and Indonesian steel tubing fabricators. Single-source vulnerability concentrates in Japanese autoclave curing capacity where motorsports demand surges compete for limited oven availability. Distribution runs through tier-one chassis integrators for OEM procurement and direct-to-garage networks for Southeast Asian aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive strut bar market represents a late-cycle quality story as electrification shifts chassis load distribution toward premium adjustable systems with electronic damper interfaces.
For Market Incumbents: Hedge aluminum extrusion cost exposure through backward integration into hollow bar production or long-term electricity purchase agreements with European grid operators. Defend bundled spring-and-bar procurement relationships against emerging software-defined chassis calibration specialists by accelerating preload-adjustable system certification under EU AI Act CE marking pathways. For New Entrants and Emerging Players: The price-point gap between premium carbon fiber track systems and economy steel fleet applications offers white-space entry for hybrid aluminum-steel composite constructions. Southeast Asian direct-to-garage channels present the most penetrable geography; Indonesia's independent workshop ecosystem lacks VIN-validated fitment configurators. Pursue garage-level technical training partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among seam-welded steel tubing fabricators without software-defined vehicle integration capabilities. Long-term viability favors suppliers with embedded load-sensor telemetry and active damper firmware compatibility. Watch for inflection when German OEM performance divisions convert pilot electronically adjustable programs to platform-standard fitments.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Chassis Calibration Investment | Electronically adjustable strut bars interfacing with active damper control systems capture unoccupied OEM integration white space. |
| Backward Integration into Aluminum Extrusion | In-house hollow bar production insulates margin from European electricity price volatility and REACH compliance costs. |
| Direct-to-Garage Distribution Expansion | Indonesia and Thailand channel compression eliminates wholesale markups while capturing VIN-validated fitment data. |
| Carbon Fiber Autoclave Capacity Buildout | Additional South Korean curing oven availability reduces lead time bottlenecks during motorsports demand surges. |
| EU AI Act CE Marking Pathway | First-mover certification for sensor-integrated braces creates regulatory moat against mechanical-only competitors. |
Methodological Framework
Coverage spans Germany, Japan, the United States, Indonesia, and South Korea, with primary inputs from each market's manufacturing clusters. The study combines structured interviews with tier-one chassis integrator procurement directors, aftermarket distributor operations managers, and motorsports component fabrication engineers with secondary validation from vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from automotive supplier peers. Bottom-up fitment volume estimates triangulate against top-down OEM platform production forecasts.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. The analytical framework models segmentation across vehicle class, propulsion architecture, material grade tier, adjustability feature set, and regional production cluster. CAGRs derive from fitted trend extrapolation calibrated to platform consolidation timelines and electrification penetration curves. Industry-specific inputs include MacPherson architecture proliferation rates and track-day participation enrollment trends.
Caveats apply where EU F-Gas Regulation enforcement intensity or aluminum smelting electricity cost spikes could materially shift the outlook. Forecasts embed assumptions about bonded joint adhesive substitution timelines and autoclave capacity expansion schedules. A model refresh is warranted upon material change in German OEM software-defined chassis pilot program conversion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Grille Market