
 Global Automotive Air Spring Market | 2026-2036
Global Automotive Air Spring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Air Spring Market Analysis
Asset-light leasing models for commercial vehicle fleets are rewriting capital deployment patterns across the air spring value chain. Tenneco Inc. leverages its captive elastomer compounding capacity to sustain margin resilience against volatile natural rubber costs. Continental AG anchors European OEM programs through integrated electronic control modules that pair pneumatic actuation with real-time damping algorithms. SAF-Holland competes aggressively in the North American trailer segment by controlling distribution through dedicated service networks rather than third-party channels.
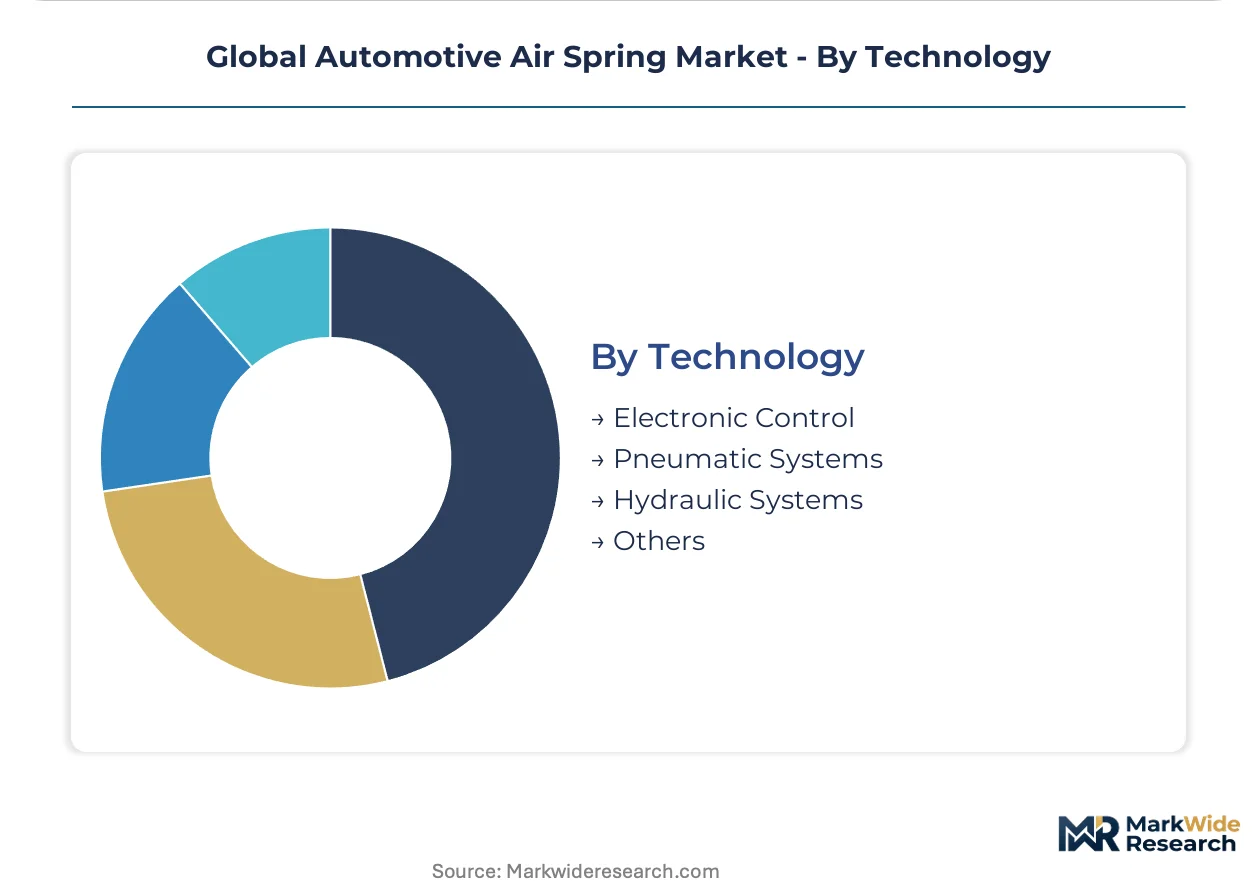
Automotive air springs are elastomeric bellows reinforced with synthetic fiber cords, pressurized with compressed air to provide variable ride height and load-leveling functions in vehicle suspension systems. Manufacturing employs multi-layer calendering and rubber-to-metal bonding processes to achieve burst pressures exceeding 1,000 kPa while maintaining fatigue resistance across millions of duty cycles. Bellows configurations dominate current production volumes due to their proven durability in heavy commercial applications, while adaptive spring variants represent the fastest-growing product category as OEMs integrate electronically controlled damping for predictive load management. Electronic control technology commands the highest value-added margins within the technology dimension, though pneumatic systems continue to occupy the largest installed base across price-sensitive emerging markets.
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles and the EU Green Deal's commercial fleet decarbonization timelines are forcing manufacturers to redesign suspension systems for reduced un-sprung weight and improved aerodynamic ride-height control. China's MIIT enforces GB standards for commercial vehicle safety that explicitly mandate air suspension on specific bus and coach categories above defined gross vehicle weights. Stakeholders must monitor how regulatory divergence between California's Advanced Clean Trucks rule and European CO2 performance standards fragments platform engineering requirements across major export markets.
Market Dynamics
Heavy-duty commercial vehicle fleets are abandoning mechanical leaf springs for electronically controlled air suspension architectures as EPA Phase 3 greenhouse gas standards and EU Green Deal decarbonization timelines mandate reduced un-sprung weight and precision ride-height management.
Growth Catalysts
- EPA Phase 3 Standards:Heavy-duty truck OEMs must cut greenhouse gas emissions through aerodynamic optimization, forcing air spring adoption for active ride-height control that reduces drag at highway speeds.
- China MIIT GB Mandates:Bus and coach categories above specified gross vehicle weights now require air suspension, pulling procurement volumes toward domestic tier-1 suppliers in Shandong and Jiangsu provinces.
- Synthetic Fiber Cord Reinforcement:Advanced aramid and polyester cord architectures enable thinner bellows walls without sacrificing burst pressure ratings, expanding duty cycle longevity in mining and construction applications.
Market Restraints
- Natural Rubber Price Volatility:Elastomer compounding costs fluctuate with Southeast Asian latex harvest cycles and climate disruption, compressing margins for suppliers without captive polymer synthesis capabilities.
- Electronic Control Module Concentration:Integrated damping algorithm hardware depends on semiconductor supply chains concentrated in Taiwan and South Korea, creating vulnerability to foundry capacity constraints.
- Mechanical Spring Substitution:Parabolic leaf springs retain cost advantages in price-sensitive emerging markets where pneumatic infrastructure for roadside service remains underdeveloped.
Strategic Opportunities
- India Commercial Fleet Modernization:The Bureau of Indian Safety's proposed bus and truck suspension standards create regulatory white space for air spring penetration in a market historically dominated by steel springs.
- Predictive Load Management Convergence:Integration of air spring pressure sensors with telematics platforms enables real-time cargo weight monitoring, creating value-added service revenue streams for fleet operators.
- Direct-to-Fleet Distribution Channels:Large commercial operators in Germany and the United States are bypassing traditional parts distributors to contract directly with air spring manufacturers for scheduled replacement programs.
Industry Challenges
- Rubber-to-Metal Bonding Expertise Scarcity:Multi-layer calendering and adhesive chemistry specialization required for 1,000+ kPa burst pressure ratings concentrates among aging technician populations in Germany and Japan.
- Legacy Pneumatic System Integration:Retrofitting electronically controlled air springs onto existing truck chassis requires reconciling incompatible sensor protocols and compressed air plumbing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Air Spring Market |
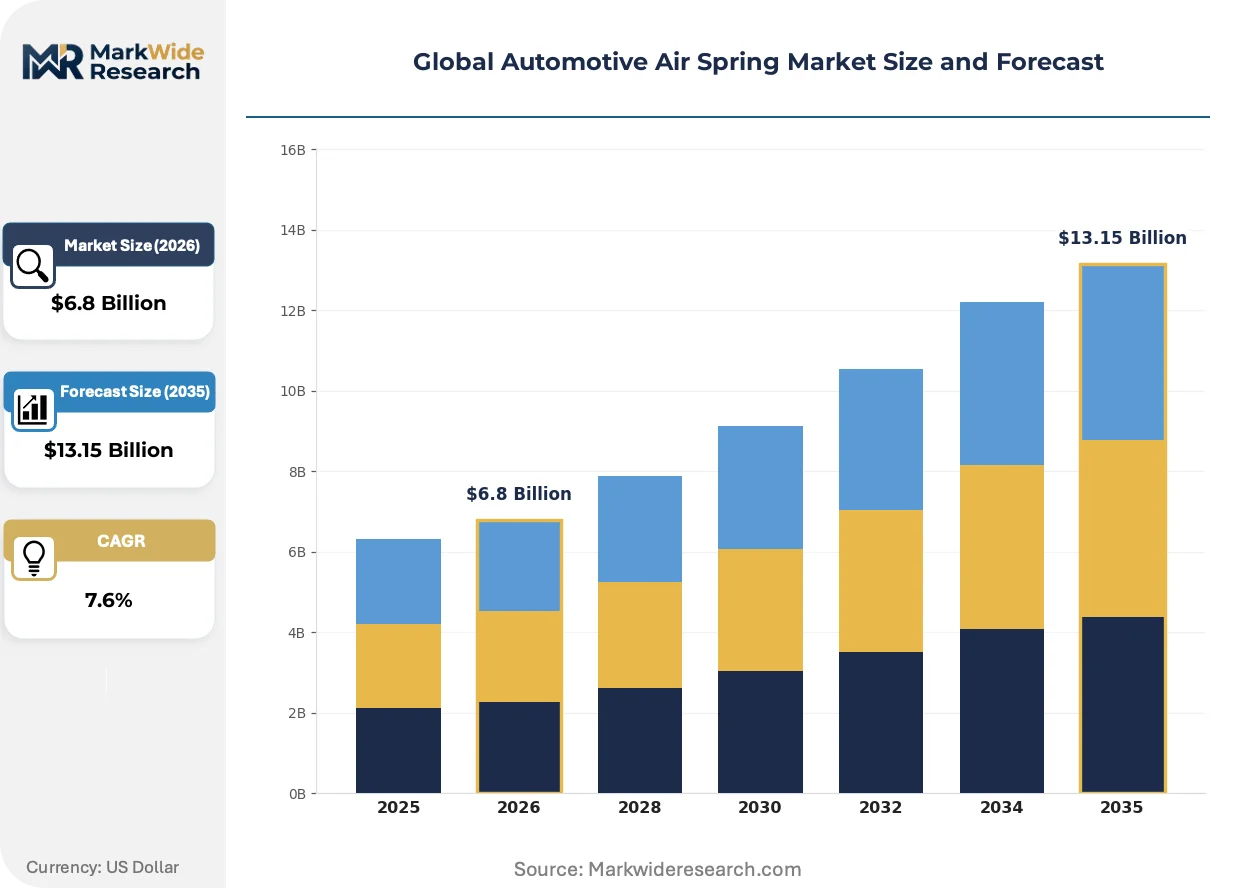
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bellows, Adaptive Springs, Heavy Duty Springs, Standard Springs End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Trains Technology: Electronic Control, Pneumatic Systems, Hydraulic Systems, Others |
| Companies Covered | Tenneco Inc., SAF-Holland, Continental AG, Hitachi Astemo Ltd., Vibracoustic SE, ZF Friedrichshafen AG, Goodyear Tire and Rubber Company, ThyssenKrupp AG, Firestone Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Air Spring Market Emerging Trajectories
Active suspension intelligence is migrating from mechanical pneumatic systems toward predictive, electronically controlled architectures that adjust damping in milliseconds based on road surface data and vehicle load conditions.
Adaptive spring variants with integrated solenoid valves and pressure transducers are migrating from premium coach applications into mid-duty delivery trucks as fleet operators demand cargo protection for fragile e-commerce shipments. European OEM programs now specify these systems as standard equipment on vehicles above 12-tonne gross weight. The technology is migrating from aftermarket retrofit kits to factory-installed platforms, compressing the addressable market for independent installers.
The EU Green Deal's commercial fleet decarbonization timelines are forcing suspension redesigns that prioritize mass reduction and aerodynamic efficiency over durability alone. Manufacturers must now certify air spring systems for CO2 contribution scores alongside traditional performance metrics. Trailer segments in the Netherlands and Denmark face the steepest compliance curves as these member states accelerate national implementation ahead of EU minimums.
Leasing companies and fleet operators in the United States are unbundling air spring replacement from full-service maintenance contracts, creating spot procurement markets where price transparency pressures supplier margins. Large operators now benchmark component life-cycle costs across multiple brands rather than accepting OEM-specified replacement intervals. This behavior is most visible in California's Advanced Clean Trucks corridors, where zero-emission vehicle adoption concentrates capital-intensive fleet renewal programs.
Global Automotive Air Spring Market Segmentation
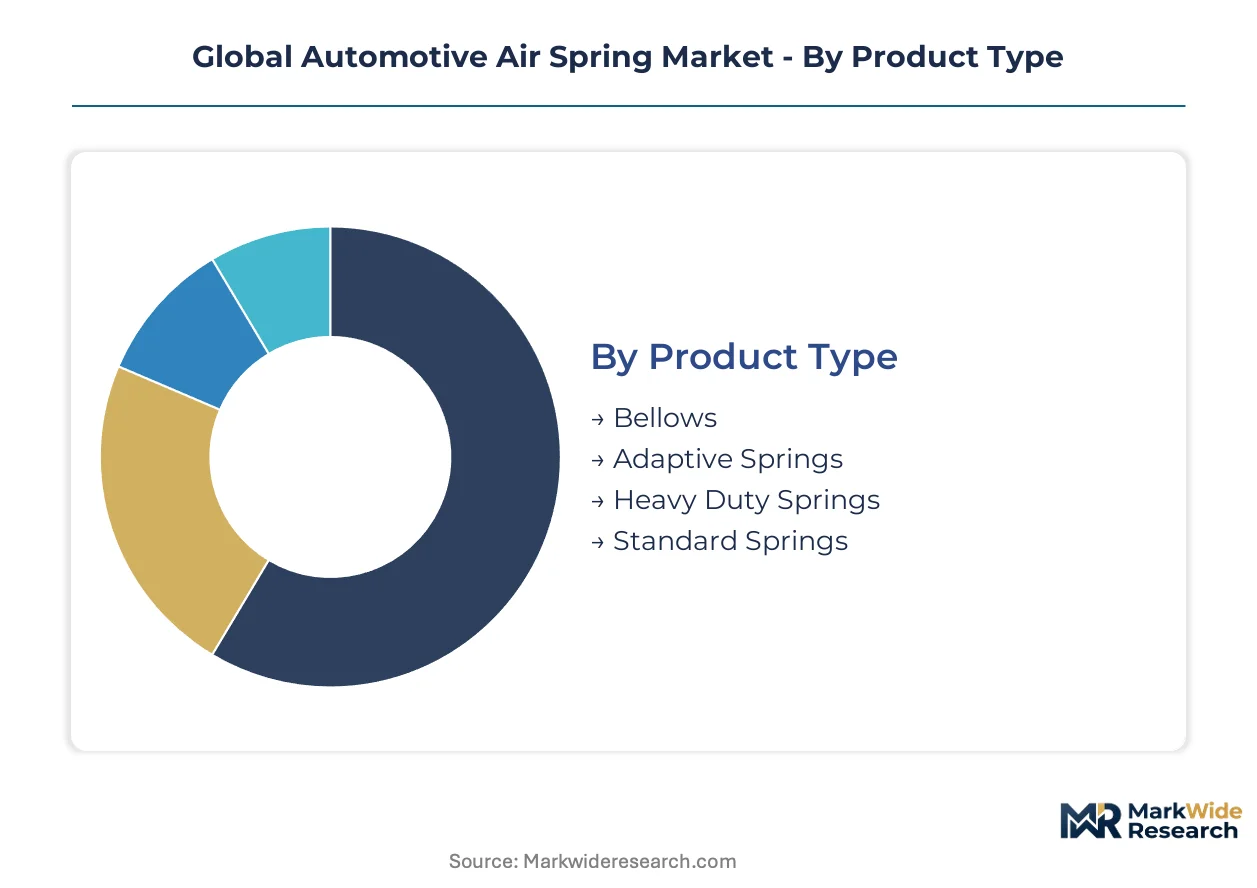
Air spring procurement patterns diverge sharply across customer types, with replacement cycles and technical support requirements creating distinct margin profiles. Fleet operators prioritize total cost of ownership calculations that weight durability against downtime risk, while OEMs engineer for platform standardization.
Product Type:
After-sales service intensity varies dramatically by product architecture, with electronically controlled variants demanding diagnostic software subscriptions and field technician certification programs.
- Adaptive Springs:These integrate solenoid valves and pressure transducers for millisecond-level damping adjustments. Demand concentrates in European coach manufacturing above 12-tonne gross weight, where the EU Green Deal mandates aerodynamic ride-height optimization for CO2 compliance.
- Bellows:Multi-layer elastomeric constructions reinforced with aramid or polyester cords dominate heavy commercial applications. Mining and construction fleets in Australia and South Africa specify these for burst pressure ratings exceeding 1,000 kPa in abrasive operating conditions.
- Heavy Duty Springs:Engineered for extreme load cycles in refuse collection and logging equipment.
- Standard Springs:Basic pneumatic configurations serving price-sensitive replacement markets.
Bellows holds the largest share; momentum sits with Adaptive Springs.
End User:
Cost tier stratification separates captive OEM supply arrangements from fragmented aftermarket channels.
- OEMs:Vehicle manufacturers specify air springs at platform design stage, locking in multi-year supply agreements with technical collaboration clauses. German and Swedish truck OEMs increasingly mandate integrated electronic control modules from approved supplier lists.
- Aftermarket Providers:Independent distributors and service networks handle replacement demand from aging fleet populations. North American leasing companies are unbundling air spring replacement from full-service contracts, creating spot procurement markets.
- Tier-1 Suppliers:Subsystem integrators combining air springs with suspension modules for OEM delivery.
- Vehicle Assemblers:Contract manufacturers building to third-party specifications.
OEMs command volume concentration; aftermarket channels are expanding most quickly.
Application:
Volume distribution tracks commercial fleet renewal cycles and infrastructure investment waves.
- Commercial Vehicles:Heavy-duty trucks and buses generate the dominant procurement pull. China's MIIT GB standards mandate air suspension on specified coach categories, concentrating demand with domestic suppliers in Shandong province.
- Trains:Railway rolling stock requires specialized high-cycle bellows for primary and secondary suspension. European high-speed rail programs in France and Spain specify these for passenger comfort at sustained velocities.
- Passenger Vehicles:Premium SUV and luxury sedan platforms in Germany and Japan.
- Construction Equipment:Articulated dump trucks and motor graders.
Commercial Vehicles holds the largest share; trains show the steepest expansion trajectory.
Technology:
Margin concentration favors electronically controlled architectures despite pneumatic systems maintaining installed base dominance.
- Electronic Control:Real-time damping algorithms paired with pneumatic actuation command premium pricing. Taiwan and South Korean semiconductor supply chains create foundry capacity vulnerabilities for integrated control module production.
- Pneumatic Systems:Conventional compressed air architectures retain cost advantages in emerging markets. Indian and Brazilian commercial fleets continue specifying these where roadside pneumatic service infrastructure remains limited.
- Hydraulic Systems:Niche applications requiring fluid-based damping characteristics.
- Others:Emerging magnetorheological and electromechanical alternatives.
Pneumatic Systems holds the largest share; Electronic Control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in China, Germany, and the United States concentrate procurement volumes for air spring systems, with regulatory mandates in each jurisdiction reshaping supplier access patterns and technical certification requirements.
China
Domestic bus and truck manufacturers in Shandong and Jiangsu provinces drive the steepest volume expansion. MIIT enforces GB standards mandating air suspension on coach categories above specified gross vehicle weights. Qingdao and Yantai host tier-1 supplier clusters where local fabricators scale production for both domestic OEMs and export programs.
Germany
Commercial vehicle OEMs in Munich and Stuttgart specify integrated electronic control modules for platform standardization. The EU Green Deal's commercial fleet decarbonization timelines force suspension redesigns prioritizing mass reduction and aerodynamic efficiency. Suppliers in Baden-Württemberg concentrate rubber-to-metal bonding expertise for 1,000+ kPa burst pressure applications.
United States
Heavy-duty fleet operators in California's Advanced Clean Trucks corridors unbundle air spring replacement from full-service maintenance contracts. EPA Phase 3 greenhouse gas standards mandate aerodynamic ride-height control for drag reduction at highway speeds. Detroit and Chicago anchor distribution networks where leasing companies benchmark component life-cycle costs across multiple brands.
India
Commercial fleet modernization creates regulatory white space for air spring penetration historically dominated by steel springs. The Bureau of Indian Safety proposes bus and truck suspension standards that would mandate pneumatic architectures. Manufacturing clusters in Pune and Chennai attract subsystem integrators seeking to localize supply for domestic vehicle assemblers.
Japan
Premium automotive platforms in Toyota City and Yokohama integrate adaptive spring variants for predictive load management. METI supports technology transitions through industrial standards harmonization with export markets. Aging technician populations in Nagoya concentrate multi-layer calendering expertise that suppliers struggle to replicate elsewhere.
Global Automotive Air Spring Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply arrangements. The vendor base separates into consolidated subsystem integrators, captive elastomer compounders, and regional distribution specialists. Three archetypes dominate: integrated chassis module suppliers, rubber-to-metal bonding specialists, and direct-to-fleet service network operators. Competitive moves concentrate on backward integration into polymer synthesis and geographic expansion through dedicated service infrastructure.
Among German-based subsystem integrators, Continental AG and ZF Friedrichshafen AG exemplify the integrated module archetype, anchoring European OEM programs through combined pneumatic and electronic control capabilities. Tenneco Inc. represents the captive compounding model, while SAF-Holland occupies a position within the channel-control tier.
| Leading Market Players |
|---|
| Tenneco Inc. |
| SAF-Holland |
| Continental AG |
| Hitachi Astemo Ltd. |
| Vibracoustic SE |
| ZF Friedrichshafen AG |
| Goodyear Tire and Rubber Company |
| ThyssenKrupp AG |
| Firestone Industrial Products |
| Others |
Supply Flow & Price Mechanics
Shandong province's tier-1 supplier clusters in Qingdao and Yantai concentrate elastomer compounding capacity that translates directly into pricing leverage for domestic OEM procurement programs. This geographic concentration of rubber-to-metal bonding expertise creates asymmetric bargaining power when international buyers seek burst-pressure-certified components for heavy commercial applications.
Pricing Analysis
Cost-plus contracts with natural rubber indexation dominate long-term supply agreements between fleet operators and tier-1 manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates electronically controlled adaptive springs from conventional bellows and basic pneumatic configurations. Pricing pressure stems from unbundled replacement procurement in North American leasing markets where spot purchasing compresses margins. Aftermarket channels exhibit highest price sensitivity due to fragmented distributor networks benchmarking across multiple brands.
Supply Chain Analysis
Upstream natural rubber feedstock draws from Southeast Asian latex harvest regions in Thailand, Indonesia, and Vietnam where climate disruption creates harvest volatility. Synthetic fiber cord reinforcement sources from specialized aramid and polyester manufacturers concentrated in Germany and Japan. Semiconductor supply chain concentration in Taiwan and South Korea creates single-source vulnerability for electronic control module production. Distribution runs through dedicated service networks in mature markets and third-party aftermarket channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diagnostic software subscriptions and field technician certification programs represent a service-attach layer expanding faster than hardware sales as electronically controlled air spring architectures proliferate across European and North American fleet renewal programs.
For Market Incumbents: Pre-empt margin erosion from unbundled procurement by deepening captive control over elastomer synthesis capacity in Southeast Asia. Consolidate rubber-to-metal bonding expertise through targeted certification programs in Baden-Württemberg and Nagoya before aging technician populations retire. Defend against mechanical spring substitution in price-sensitive markets by embedding predictive load management telemetry as standard equipment.
For New Entrants and Emerging Players: India's commercial fleet modernization represents the most penetrable entry point where regulatory white space around proposed Bureau of Indian Safety standards creates first-mover positioning. Mid-duty delivery truck segments in Germany and the United States offer secondary expansion channels as adaptive spring variants migrate from premium coach applications. Contract directly with large fleet operators for scheduled replacement programs rather than penetrating fragmented aftermarket distribution.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA Phase 3 and EU Green Deal mandates structurally displace mechanical leaf springs regardless of commodity cost cycles. Acquisition targets should concentrate on subsystem integrators with approved supplier status at German and Swedish truck OEMs. Monitor foundry capacity utilization in Taiwan and South Korea as an inflection indicator for electronic control module supply security.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Synthesis | Tenneco's captive compounding insulates margins against Southeast Asian latex price volatility. |
| Electronic Control Module Platform Standardization | Continental AG anchors European OEM programs through integrated pneumatic-electronic architectures. |
| Direct-to-Fleet Distribution Channel Development | SAF-Holland bypasses third-party distributors to capture replacement contract value in North American corridors. |
| Predictive Load Management Telemetry Integration | Real-time cargo weight monitoring creates recurring service revenue streams for fleet operators. |
| Rubber-to-Metal Bonding Expertise Certification | German and Japanese technician training programs concentrate scarce 1,000+ kPa burst pressure capabilities. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, fleet maintenance directors, and elastomer compounding specialists; and secondary validation through vehicle production databases, EPA regulatory filings, EU Green Deal implementation documents, MIIT GB standard publications, and customs trade records. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, end user, application, and technology dimensions.
Forecast inputs considered vehicle class stratification, propulsion architecture evolution, content per vehicle trends, OEM tier positioning, and regional production cluster dynamics across the projection horizon. CAGRs derived from regression analysis of historical procurement volumes against regulatory mandate implementation timelines. Industry-specific inputs incorporated heavy-duty fleet renewal cycles, air suspension mandate compliance curves, and semiconductor foundry capacity constraints.
Practitioners should monitor EPA Phase 3 enforcement intensity, EU Green Deal commercial fleet decarbonization acceleration, and MIIT GB standard expansion scope for early signals requiring forecast revision. Cross-checking against IHS Markit vehicle registration data and tier-1 supplier order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Idler Arm Market