
 Automotive Grill Guard Market | 2026-2036
Automotive Grill Guard Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grill Guard Market Analysis
North American steel fabricators is repositioning capacity toward tubular alloy products for heavy-duty truck applications. CURT Manufacturing LLC leverages its Wisconsin-based stamping and welding infrastructure to anchor supply for bolt-on guard systems. SteelCraft competes through specialized retail distribution across the Rocky Mountain and Pacific Northwest off-road corridors. Westin Automotive dominates the West Coast custom fabrication segment with California-specific styling configurations.
An automotive grill guard is a tubular or plate-type front-end protective device, typically fabricated from carbon steel, aluminum alloy, or engineering-grade polymer, mounted to a vehicle frame via bolt-on brackets or weld plates to absorb collision impact and shield radiator grilles. Its primary commercial purpose is to reduce repair costs for fleet vehicles and provide aesthetic differentiation in the consumer aftermarket. Steel grill guard configurations occupy the largest installed base due to cost efficiency and impact resistance in commercial trucking applications. Aluminum grill guard demand is accelerating among SUV owners seeking weight reduction without sacrificing structural integrity. Custom grill guard fabrication captures premium margin pools through vehicle-specific fitment and powder-coat finishing options.
NHTSA frontal impact guidelines and EPA corrosion-resistance standards shape product testing protocols and material certification requirements for US-market suppliers. FMVSS bumper compatibility rules influence mounting system design and grille clearance specifications across OEM and aftermarket channels. Stakeholders must monitor evolving pedestrian protection standards and aluminum tariff structures to calibrate material sourcing and pricing strategies.
Market Dynamics
Fleet operators across the United States pickup and SUV belt are driving procurement of protective front-end accessories, while NHTSA pedestrian safety standards simultaneously force design modifications to tube geometry and mounting systems.
Growth Catalysts
- FMVSS bumper compatibility rules:Aftermarket suppliers redesign mounting brackets to meet federal clearance specifications, expanding addressable market for bolt-on systems.
- Texas-Michigan-Southeast manufacturing corridor:Concentrated commercial truck production creates localized demand clusters for heavy-duty steel guard fabrication.
- Aluminum alloy substitution:SUV owners prioritize weight reduction without structural compromise, accelerating material diversification beyond carbon steel.
Market Restraints
- Steel tariff volatility:Input cost uncertainty from Section 232 duties compresses margin pools for carbon steel fabricators serving price-sensitive fleet segments.
- NHTSA pedestrian protection compliance:Tube geometry redesign requirements extend engineering cycles and raise certification costs for traditional bull-bar configurations.
- Engineering-grade polymer substitution:Lightweight composite alternatives threaten aluminum growth trajectories in consumer aftermarket channels.
Strategic Opportunities
- Rocky Mountain off-road corridors:Specialized retail distribution remains underpenetrated for custom powder-coat finishing and vehicle-specific fitment services.
- EPA corrosion-resistance standards:Material certification protocols create competitive moats for suppliers with in-house testing infrastructure.
- E-commerce direct-to-installer channels:Digital procurement platforms displace traditional jobber networks for aftermarket accessory distribution.
Industry Challenges
- Welding technician scarcity:Tubular alloy fabrication requires certified TIG/MIG specialists that Wisconsin and California production facilities struggle to retain.
- OEM integration complexity:Aftermarket guard systems must interface with evolving sensor arrays and adaptive cruise control modules without triggering fault codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grill Guard Market |
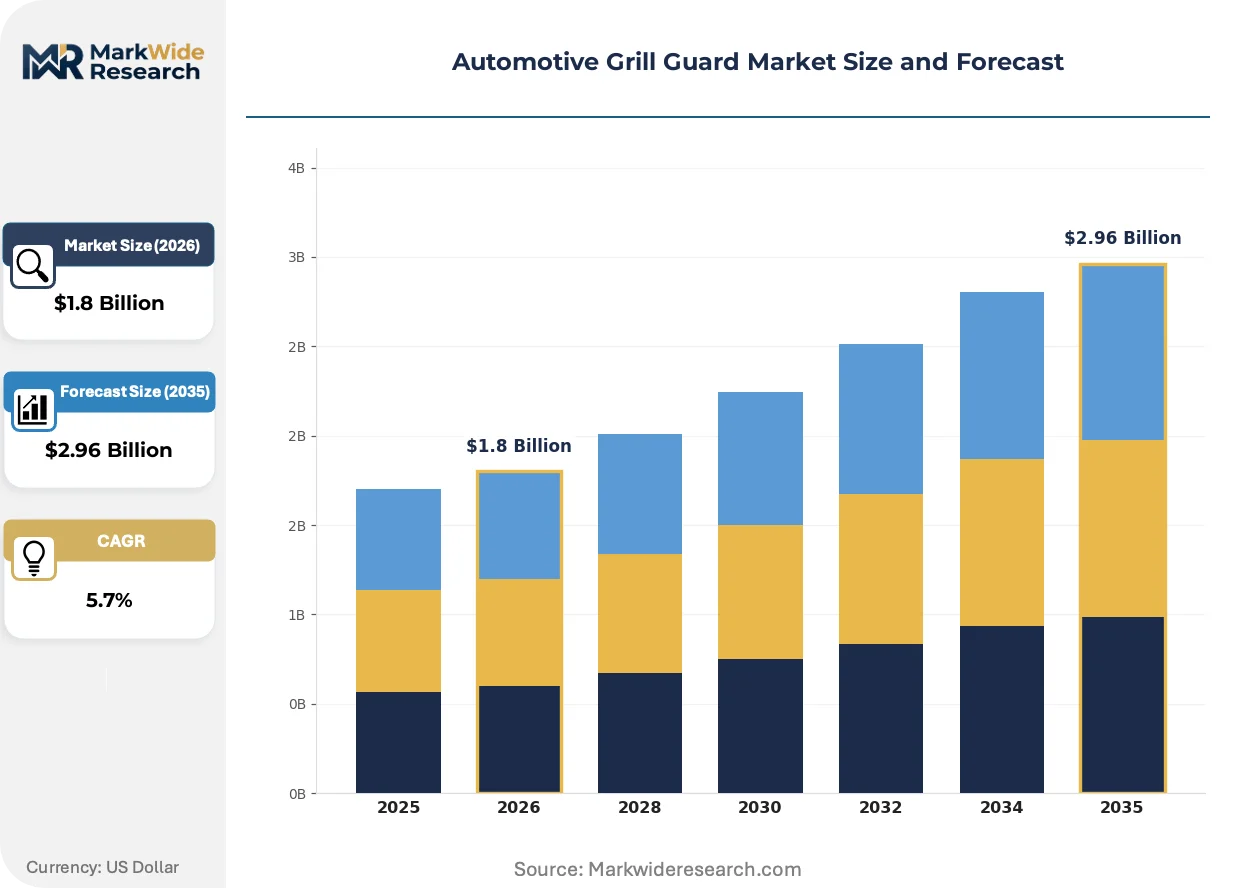
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Grill Guard, Aluminum Grill Guard, Plastic Grill Guard, Custom Grill Guard Installation Type: Bolt-on, Weld-on, No Drilling, Modular End User: OEMs, Retail Users, Fleet Operators, Aftermarket Consumers Vehicle Type: Trucks, SUVs, Vans, Recreational Vehicles |
| Companies Covered | CURT Manufacturing LLC, Onki Corporation, Armordillo USA, Go Rhino, SteelCraft, Tuff-Bar, Frontier Truck Gear, Broadfeet, Westin Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grill Guard Market Emerging Trajectories
Design automation and regulatory compliance software are compressing product development cycles while reshaping competitive advantage toward digital engineering capabilities rather than pure manufacturing scale.
Computer-aided tube bending with integrated stress analysis is automating guard geometry optimization for specific vehicle crush zones. Fleet engineering departments at commercial trucking operators now specify CAD-validated designs before procurement. This technology is automating the traditional trial-and-error prototyping phase that previously consumed eight to twelve weeks in product development.
NHTSA frontal impact guidelines are mandating revised energy-absorption testing for all tubular front-end protection devices. Suppliers must submit finite element analysis documentation alongside physical crash test data. Aftermarket fabricators serving the Texas and Michigan markets are investing in simulation software licenses to maintain FMVSS compliance without repeated destructive testing.
Installer certification programs are displacing open distribution for premium guard systems. Independent shops in the Pacific Northwest now require manufacturer-authorized training before stocking powder-coated custom configurations. This behavioral shift concentrates margin capture with West Coast fabricators who control both production and channel credentialing.
Automotive Grill Guard Market Segmentation
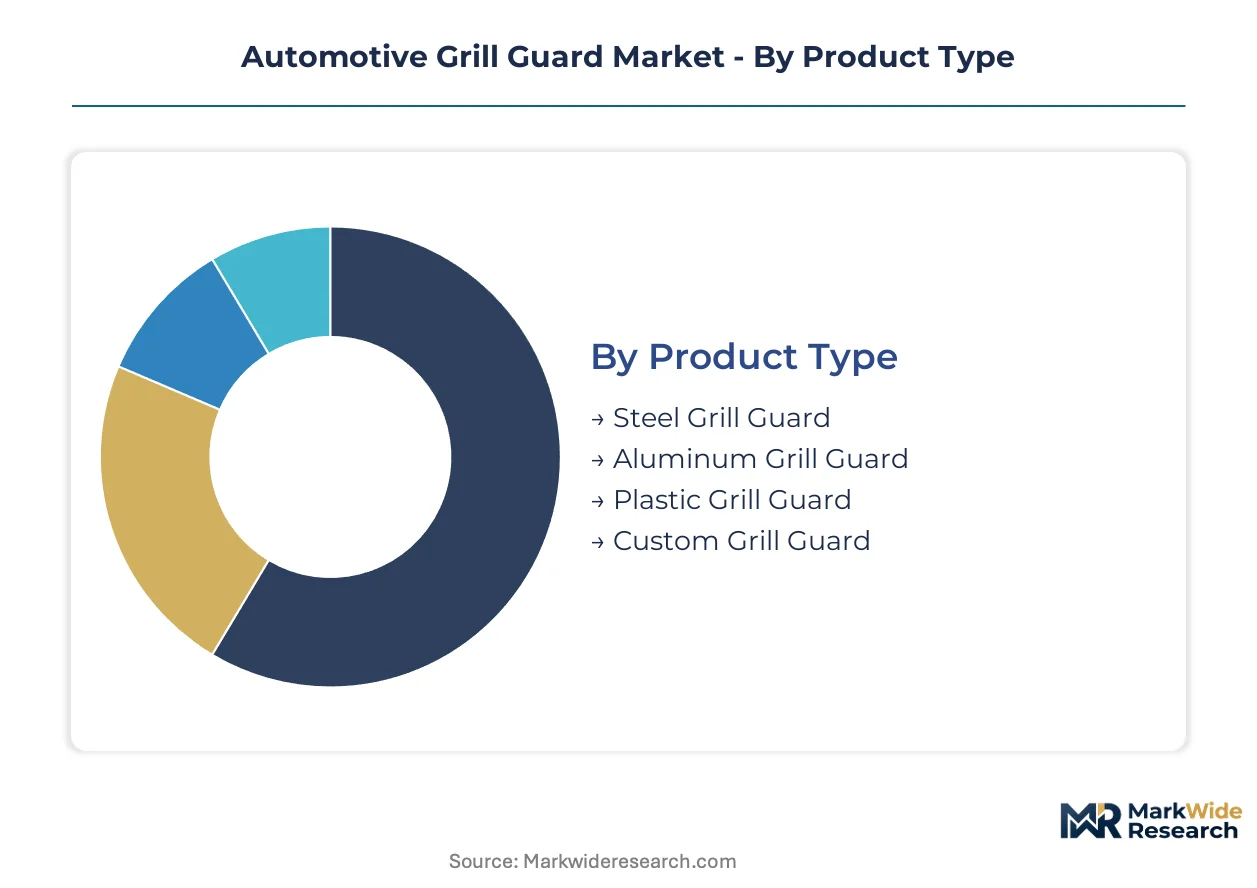
Material selection and mounting complexity drive buyer decisions across the automotive grill guard market. Fleet procurement teams prioritize impact resistance and serviceability, while retail consumers balance weight reduction with aesthetic customization. Understanding these segment boundaries enables suppliers to align fabrication capacity with distinct margin profiles and certification requirements.
Product Type:
Cost tier positioning determines procurement patterns across commercial and consumer channels, with material density and finishing complexity separating economy from premium configurations.
- Steel Grill Guard:Fabricated from carbon steel tubing with powder-coat or chrome plating, these configurations dominate fleet specifications for impact absorption and repair cost reduction. Texas and Michigan commercial truck operators specify heavy-gauge steel guards for highway debris protection and minor collision mitigation.
- Aluminum Grill Guard:Extruded and welded aluminum alloy construction reduces unsprung weight by 30-40% versus steel equivalents while maintaining structural integrity for SUV applications. California and Pacific Northwest retail demand concentrates here, driven by fuel economy consciousness and corrosion resistance in coastal climates.
- Plastic Grill Guard:Engineering-grade polymer injection molding serves price-sensitive aftermarket channels with lightweight, color-matched aesthetics for urban SUV owners.
- Custom Grill Guard:Vehicle-specific tube bending and bespoke powder-coat finishing capture premium margin pools through Rocky Mountain off-road retail networks.
Steel grill guards lead on scale; aluminum grill guards lead on momentum.
Installation Type:
Application environment dictates mounting system selection, with service bay capabilities and frame modification tolerance separating professional fleet installation from consumer DIY preferences.
- Bolt-on:Bracket-based attachment using existing frame holes enables reversible installation without structural modification, dominating fleet maintenance protocols and lease vehicle applications. NHTSA bumper compatibility rules have standardized bracket geometry for this configuration.
- Weld-on:Permanent frame plate attachment delivers maximum structural integrity for severe-duty commercial trucking in mining and logging operations. Wisconsin and Southeast fabrication shops specialize in certified weld-on systems for regional fleet operators.
- No Drilling:Clamp-based mounting preserves factory frame integrity for leased vehicles and warranty-sensitive consumer applications.
- Modular:Component-based assembly allows field reconfiguration between brush guard, bull bar, and full grille guard geometries.
Bolt-on systems dominate addressable market breadth; modular configurations are gaining share fastest in specialty retail channels.
End User:
Volume concentration and margin structure diverge sharply across procurement entities, with specification authority and lifecycle cost accounting driving distinct commercial behaviors.
- Fleet Operators:Commercial trucking and utility vehicle fleets specify CAD-validated designs with standardized mounting protocols to minimize downtime and repair expenditure. Texas-based energy sector fleets drive procurement volume for heavy-duty steel configurations.
- Aftermarket Consumers:Individual vehicle owners prioritize aesthetic differentiation and vehicle-specific fitment through specialty retailers and direct-to-installer digital channels. Pacific Northwest custom fabricators capture premium positioning here.
- OEMs:Original equipment manufacturers integrate guard systems at assembly for select trim packages, requiring crash-test validation and sensor compatibility certification.
- Retail Users:Mass-market automotive retailers stock economy bolt-on configurations for price-sensitive pickup and SUV owners.
Fleet operators anchor procurement volume; aftermarket consumers deliver the steepest expansion trajectory through e-commerce penetration.
Vehicle Type:
Platform architecture and duty cycle severity determine guard geometry requirements, with frame rail spacing and crush zone engineering varying substantially across vehicle classes.
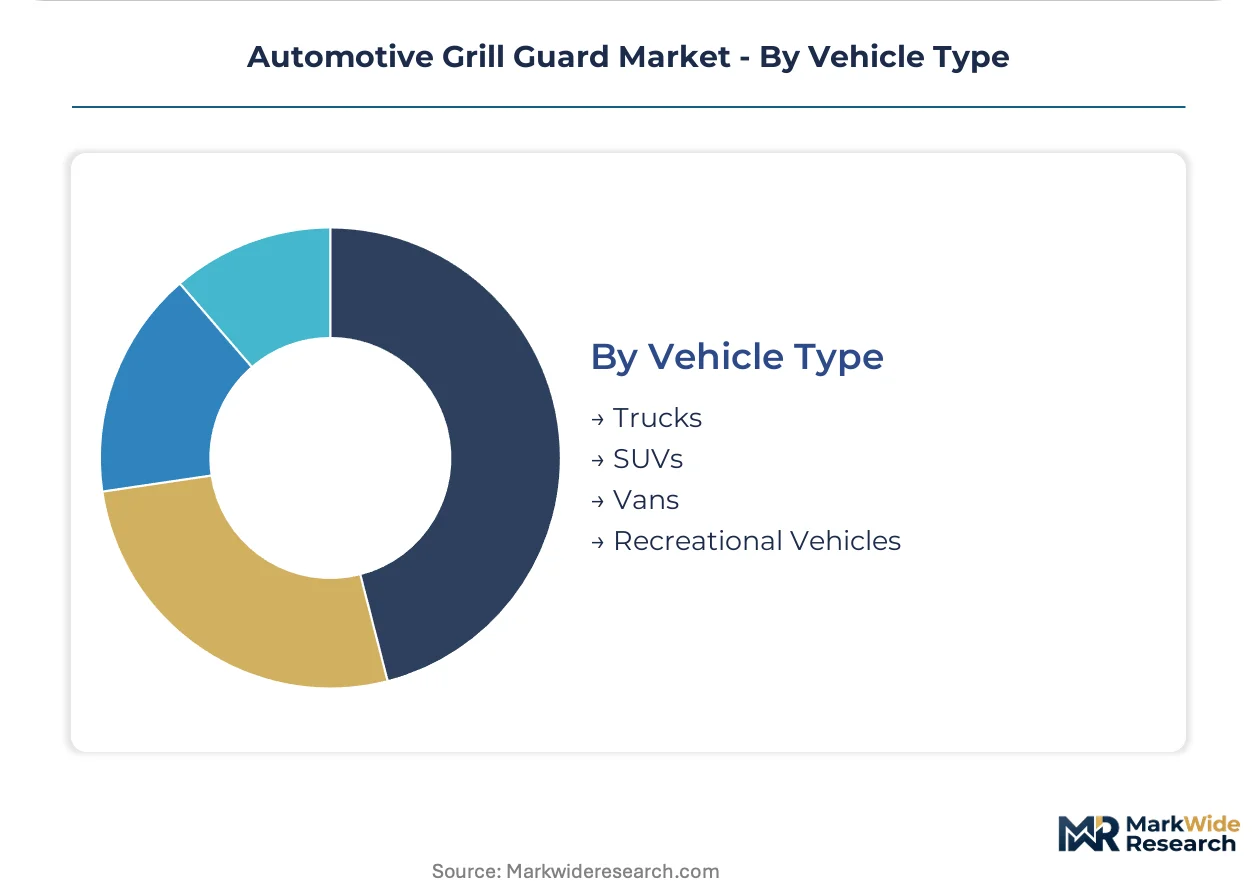
- Trucks:Full-size and heavy-duty pickup platforms with exposed frame rails accommodate the broadest range of guard configurations, from lightweight aluminum brush guards to severe-duty steel bull bars. Michigan manufacturing corridor demand concentrates here.
- SUVs:Unibody and body-on-frame sport utility vehicles require integrated mounting solutions that preserve pedestrian impact performance, driving aluminum and polymer substitution in NHTSA-compliant designs.
- Vans:Commercial delivery and passenger van applications prioritize aerodynamic integration and parking sensor compatibility over aggressive styling.
- Recreational Vehicles:Motorhome and towable RV chassis demand specialized guard geometries for road debris deflection during extended highway operation.
Trucks lead on installation base; SUVs are climbing the fastest as aluminum adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabricators are migrating capacity toward jurisdictions with lower NHTSA compliance costs while maintaining US market access through distributor partnerships. This regulatory-arbitrage dynamic concentrates production in tariff-advantaged locations and established automotive manufacturing corridors.
United States
Fleet procurement from Texas energy sector operators and Michigan commercial trucking drives heavy-gauge steel guard demand. NHTSA pedestrian protection standards force tube geometry redesigns that extend engineering cycles for domestic fabricators. Wisconsin-based stamping operations anchor supply for bolt-on bracket systems serving the Great Lakes manufacturing belt.
Canada
Cross-border supply integration positions Ontario fabricators as secondary sourcing options for US fleet operators seeking tariff mitigation. Health Canada maintains alignment with EPA corrosion-resistance standards for automotive accessories entering the North American market. Quebec-based metalworking clusters specialize in aluminum alloy extrusion for weight-conscious SUV applications.
Mexico
Maquiladora operations in Nuevo León and the Bajío Region capture assembly-stage guard integration for OEM trim packages exported to US markets. Mexico's automotive manufacturing incentives attract tubular fabrication capacity from US suppliers facing Section 232 steel duty pressure. Monterrey-area plants serve as final-assembly nodes for powder-coated configurations bound for Texas and California distribution.
Germany
KBA vehicle type approval requirements for front-end protection devices create a compliance gateway for premium guard systems entering European markets. German automotive engineering standards influence global testing protocols for energy-absorption performance. Bavaria-based metal fabrication clusters supply precision-bent tube assemblies to aftermarket distributors across Central Europe.
China
MIIT automotive component certification and GB standards for vehicle exterior accessories structure export-oriented production from Yangtze River Delta manufacturing zones. Chinese fabricators compete on aluminum alloy cost efficiency for Pacific Northwest aftermarket channels. Zhejiang and Jiangsu province clusters dominate polymer guard injection molding for price-sensitive consumer segments.
Automotive Grill Guard Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue aluminum lightweighting and custom powder-coat specialization. The vendor base stratifies across three capability levels: high-volume stamping operations serving fleet procurement, regional fabricators with vehicle-specific fitment expertise, and vertically integrated players controlling both production and authorized installer networks. Strategic moves concentrate on welding automation investments and e-commerce direct-to-installer channel development.
Among US-based metal fabricators, CURT Manufacturing LLC and Westin Automotive exemplify distinct competitive archetypes. SteelCraft occupies a position within the specialized retail distribution segment. These named entities anchor industry commentary without implying specific strategic actions or market positions beyond their visible operational footprints.
| Leading Market Players |
|---|
| CURT Manufacturing LLC |
| Onki Corporation |
| Armordillo USA |
| Go Rhino |
| SteelCraft |
| Tuff-Bar |
| Frontier Truck Gear |
| Broadfeet |
| Westin Automotive |
| Others |
Supply Flow & Price Mechanics
Carbon steel tubing costs cascade through three pricing tiers as raw material volatility from Section 232 tariffs compresses margin pools for fleet-facing fabricators while aluminum alloy premiums widen for coastal SUV aftermarket channels. NHTSA compliance testing requirements add fixed certification overhead that bolt-on system suppliers pass downstream through bracket assembly markups.
Pricing Analysis
Distributor margin layers separate factory gate pricing from end-user expenditure across fleet procurement and retail aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects mounting complexity, powder-coat finishing grade, and CAD-validation status. Price differentiation hinges on NHTSA crash-test documentation and volume scale, with fleet operators capturing 15-20 point discounts against single-unit retail purchasers. Pricing pressure stems from engineering-grade polymer substitution in consumer channels, squeezing aluminum guard premiums. Fleet operators exhibit highest price sensitivity due to lifecycle cost accounting, while Rocky Mountain custom fabricators command lowest sensitivity through vehicle-specific fitment scarcity.
Supply Chain Analysis
Refurbishment flows remain minimal for tubular steel guards given permanent deformation characteristics, though aluminum alloy scrap recovery from fabrication waste feeds secondary extrusion in Quebec and Zhejiang. Geographic supply concentrates in Wisconsin for stamped bracket subassemblies, Monterrey for powder-coat final assembly, and Jiangsu for polymer injection molding. Raw material dependencies rest on domestic carbon steel coil, imported aluminum billet, and engineering-grade ABS resin. Tariff exposure on Chinese aluminum extrusions creates margin vulnerability for Pacific Northwest retail suppliers. Distribution runs through authorized installer networks displacing traditional jobber channels for premium configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between NHTSA compliance costs in domestic fabrication and tariff-advantaged assembly in Mexican maquiladora zones, with Section 232 steel duties widening the cost differential.
For Market Incumbents: Lock in certified welding technician pipelines through Wisconsin and California technical college partnerships before labor scarcity intensifies. Secure backward integration into aluminum extrusion capacity in Quebec or Nuevo León to hedge tariff exposure on billet imports. Prioritize e-commerce direct-to-installer channel control to defend margin position against digital-native entrants displacing traditional distribution. For New Entrants and Emerging Players: E-commerce direct-to-installer platforms offer the most penetrable route for bypassing incumbent jobber networks and capturing Pacific Northwest custom fabrication demand. Target modular guard configurations for SUV owners seeking field-reconfigurable geometries between brush guard and full grille specifications. Pursue vehicle-specific CAD database licensing as the primary go-to-market angle for fitment accuracy differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where welding technician scarcity intersects with NHTSA certification cost escalation, favoring acquisition of Wisconsin-based fabricators with in-house testing infrastructure. Long-term viability centers on aluminum lightweighting capability and digital engineering automation rather than pure stamping scale. Watch for inflection signals in pedestrian protection standard revisions that would obsolete traditional bull-bar geometries.| Strategic Initiative | Industry Significance |
|---|---|
| Welding Automation Investment | Certified TIG/MIG technician scarcity in Wisconsin and California production facilities compresses throughput capacity for tubular alloy fabrication. |
| Aluminum Extrusion Backward Integration | Quebec and Nuevo León billet sourcing hedges Section 232 tariff exposure for Pacific Northwest retail suppliers. |
| Direct-to-Installer E-Commerce Launch | Digital procurement platforms displace traditional jobber networks and capture margin pools in aftermarket accessory distribution. |
| NHTSA Compliance Software Licensing | Finite element analysis documentation requirements favor suppliers with simulation infrastructure over repeated physical crash testing. |
| Authorized Installer Certification Program | Channel credentialing concentrates margin capture with West Coast fabricators controlling both production and distribution access. |
Methodological Framework
Coverage spans the United States pickup and SUV belt, Ontario and Quebec fabrication clusters, and Nuevo León maquiladora zones, with primary inputs from each. The analysis combines structured interviews with fleet procurement directors, aftermarket distributor operations managers, Tier 1 supplier platform engineers, and Wisconsin-based welding technicians with secondary validation. Secondary sources include NHTSA FMVSS documentation, EPA corrosion-resistance certification records, vehicle production databases, and customs trade data on aluminum extrusion flows. Bottom-up fabrication capacity modeling triangulates against top-down fleet procurement expenditure estimates.
Rate-of-change decomposition separates volume growth from value expansion across material substitution trends and premium configuration mix shifts. Segmentation dimensions span material type, mounting complexity, end-user procurement authority, and vehicle platform architecture. CAGRs derive from regression analysis of historical fleet expenditure patterns and forward projection of aluminum adoption curves. Industry-specific inputs include NHTSA pedestrian protection compliance cost trajectories and Section 232 tariff incidence modeling on carbon steel coil pricing.
The model assumes a particular technology adoption path; alternative pathways for engineering-grade polymer injection molding would alter the outlook toward lightweight composite substitution. Forecasts reflect assumptions regarding NHTSA regulatory stability and Mexican maquiladora cost advantages. Practitioners should monitor pedestrian protection standard revision timelines and aluminum tariff policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market