
 Automotive Window Seals Market | 2026-2036
Automotive Window Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Window Seals Market Analytics
Automotive OEM direct procurement is reconfiguring supplier relationships across the window seals value chain. Cooper Standard Automotive leverages its integrated extrusion and molding footprint to sustain long-term supply contracts with Detroit-based manufacturers. Hutchinson SA anchors its position through rubber-to-metal bonding expertise developed for premium European platforms. Toyoda Gosei Co., Ltd. dominates Asian OEM channels through just-in-time delivery networks calibrated to Japanese production cycles.
Automotive window seals are elastomeric closure profiles, typically extruded from EPDM rubber compounds with specific gravity ranging from 0.95 to 1.25 g/cm³, designed to prevent water ingress, wind noise, and thermal transfer at glass-to-body interfaces. Their primary industrial purpose centers on maintaining cabin environmental integrity while accommodating door frame tolerances across vehicle assembly processes. EPDM formulations command the material segment due to ozone resistance and compression set performance in under-hood adjacent applications. Door seals generate the largest volume pool within product type categories, though sunroof seals extract premium pricing from lower-volume luxury configurations. OEM installation channels control the majority value flow, while aftermarket replacement cycles create secondary demand tied to vehicle age distribution.
The US EPA regulates volatile organic compound emissions from rubber extrusion processes, compelling seal manufacturers to adopt water-based release agents and thermal oxidizer systems. EU REACH restrictions on polycyclic aromatic hydrocarbons in rubber compounding directly affect EPDM vulcanization chemistry sourced by European suppliers. China's GB standards for passenger vehicle sealing performance create divergent test protocols for export versus domestic-market production. Stakeholders must monitor regulatory divergence between emission-control jurisdictions and material-certification regimes to avoid stranded inventory in multi-region supply networks.
Market Dynamics
Electric vehicle platform architectures are redefining seal performance specifications as thermal management systems and battery enclosures demand tighter environmental sealing tolerances than conventional internal combustion vehicles.
Growth Catalysts
- EPDM recycling mandates:EU REACH regulations on polycyclic aromatic hydrocarbon limits are accelerating material reformulation investments across European supply chains.
- Just-in-time manufacturing:Japanese OEM production cycles are compressing inventory buffers and elevating supplier proximity requirements in Aichi and Kanagawa prefectures.
- Sunroof penetration:Premium vehicle configurations in Germany and South Korea are expanding addressable seal surface area per vehicle platform.
Market Restraints
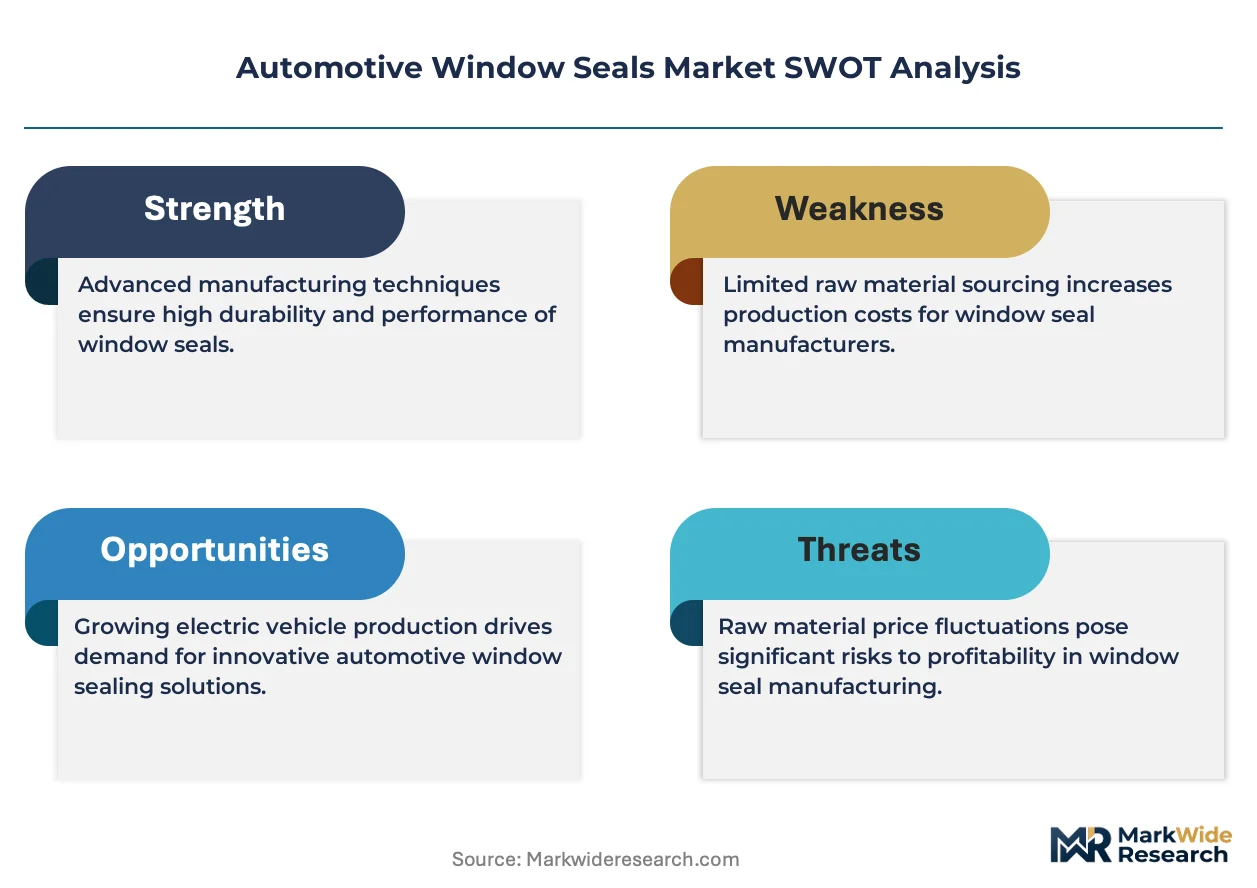
- Petrochemical feedstock volatility:EPDM rubber compound costs fluctuate with ethylene and propylene spot pricing, squeezing extrusion margins.
- Supply concentration:German automotive manufacturing corridors dominate premium seal demand, creating geographic demand risk.
- Silicone substitution:High-temperature engine-bay adjacent applications are migrating to fluorosilicone compounds in performance segments.
Strategic Opportunities
- Indian domestic production:PLI scheme incentives for automotive component manufacturing are drawing seal extrusion capacity toward Chennai and Pune industrial zones.
- Sensor integration:Convergence of conductive EPDM formulations with embedded pressure sensing enables smart seal diagnostics for predictive maintenance.
- Water-based release agents:US EPA volatile organic compound emission rules are creating first-mover advantage for compliant process technology suppliers.
Industry Challenges
- Rubber-to-metal bonding expertise:Premium European platform requirements demand specialized adhesive chemistry capabilities that concentrate among limited specialist suppliers.
- Multi-region certification timelines:Divergent GB standards for Chinese domestic versus export markets extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Window Seals Market |
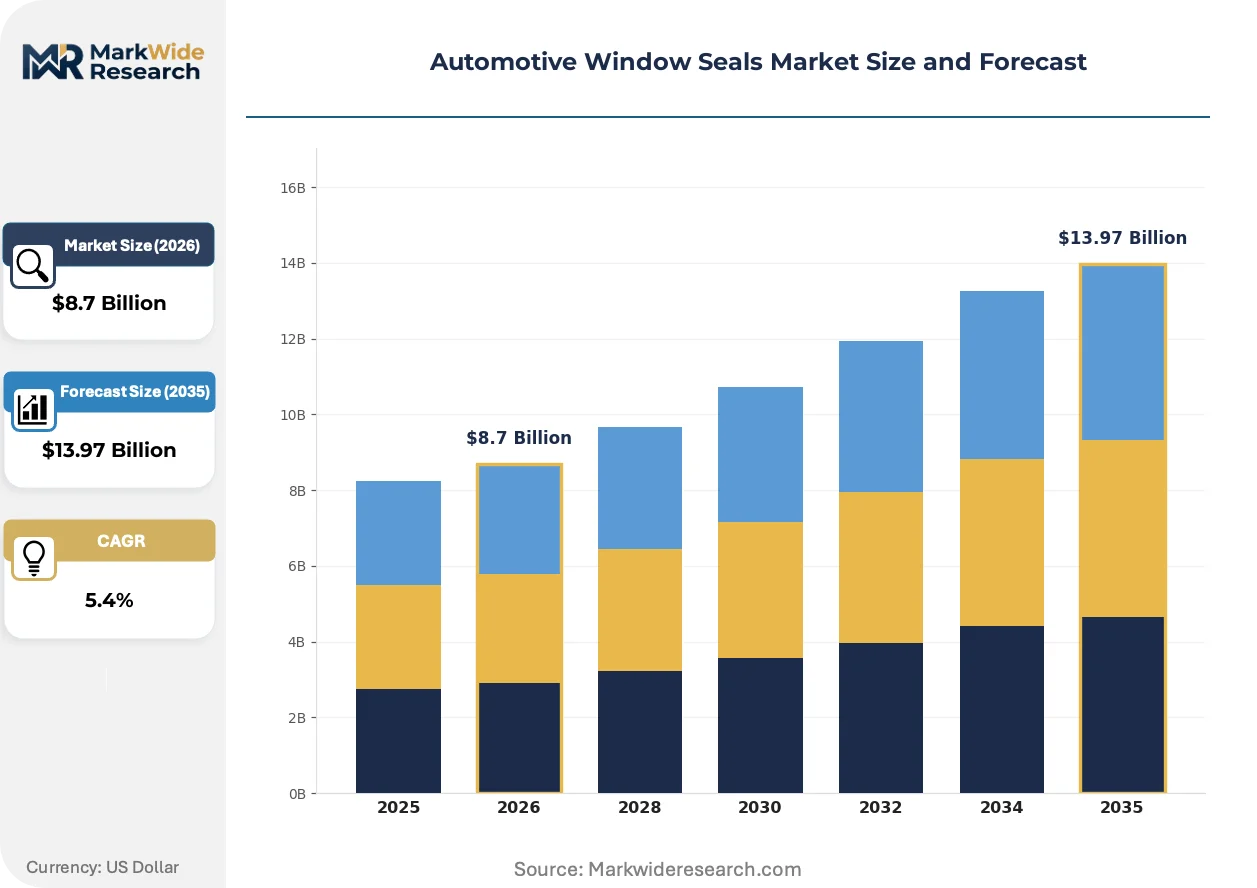
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Door Seals, Sunroof Seals, Quarter Window Seals, Windshield Seals Material: EPDM, PVC, Silicone, TPE Vehicle Type: Sedan, SUV, Hatchback, Truck Installation Type: OEM, Aftermarket, Semi-automated, Manual |
| Companies Covered | Cooper Standard Automotive, Hutchinson SA, Toyoda Gosei Co., Ltd., Trelleborg AB, Freudenberg SE, Nishikawa Rubber Co., Ltd., SaarGummi Automotive, Magna International Inc., Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Window Seals Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape compound formulation priorities across automotive sealing applications.
Thermoplastic vulcanizate compounds are migrating from experimental grades to production-scale window seal applications. Tier 1 suppliers in Stuttgart and Munich are qualifying TPV formulations for secondary seal locations to reduce part weight. This technology is migrating from niche luxury platforms toward mass-market electric vehicle programs as OEMs pursue cabin efficiency targets.
EU REACH restrictions on polycyclic aromatic hydrocarbons in rubber compounding are forcing reformulation of traditional sulfur-vulcanized EPDM systems. European suppliers are accelerating peroxide cure chemistry adoption to maintain export certification. German and Czech extrusion facilities face the steepest compliance timelines given their concentration of premium OEM contracts.
Direct OEM procurement of modular seal assemblies is consolidating tier relationships and compressing supplier counts per platform. Integrated extrusion-molding suppliers are displacing pure-play component vendors in Detroit and Wolfsburg sourcing decisions. This pattern is most pronounced in battery electric vehicle programs where seal performance warranties extend to powertrain coverage periods.
Automotive Window Seals Market Segmentation
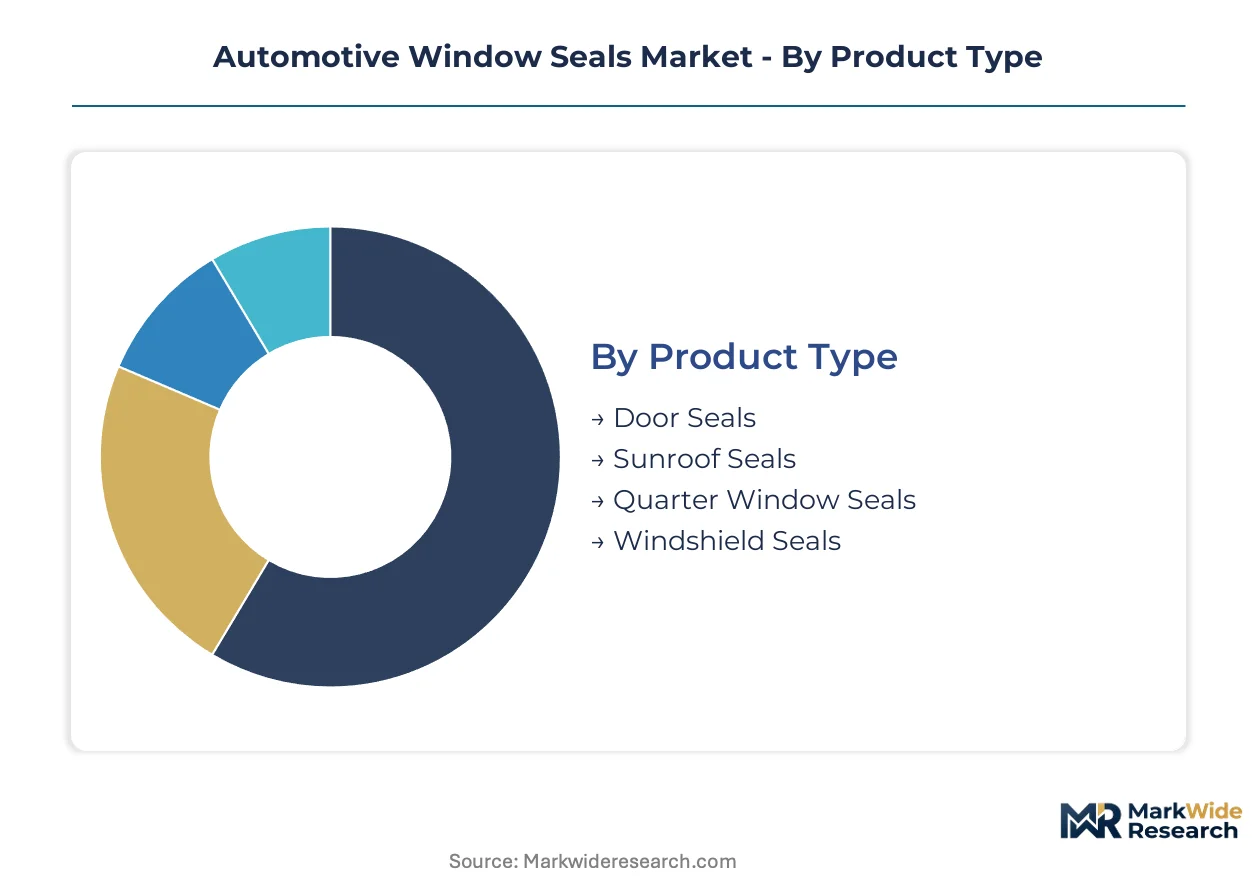
Automotive window seals fragment across four distinct taxonomies that govern procurement logic, technical specifications, and margin structures. Each segmentation axis reveals divergent cycle times, from door seals replaced every 7-10 years to sunroof seals commanding premium replacement frequencies in luxury configurations.
Product Type:
Door seals turn over on vehicle age depreciation cycles, while sunroof seals track premium platform refresh rates—creating a dual-speed replacement economy within the same vehicle.
- Door Seals:Extruded EPDM profiles with compression-molded corners form the highest-volume category, sealing primary cabin entry points against water and wind intrusion. German OEM procurement in Stuttgart and Wolfsburg concentrates demand for modular door seal assemblies with integrated carrier clips. Fleet operators in North American commercial segments drive aftermarket volume through accelerated wear cycles.
- Sunroof Seals:Complex multi-durometer constructions with drainage channel integration command premium pricing due to lower production volumes and tighter tolerance requirements. South Korean luxury platforms in Hwaseong and Asan expand addressable seal surface area per vehicle as panoramic roof penetration climbs.
- Quarter Window Seals:Secondary sealing profiles for fixed glass applications with reduced functional load compared to operable openings.
- Windshield Seals:Direct-glazing adhesive systems increasingly displace traditional rubber profiles in modern platform architectures.
Door seals dominate installed base volume. Sunroof seals are where expansion concentrates.
Material:
Cost tiers separate commodity compounds from performance grades, with regulatory chemistry restrictions now forcing reformulation investments that scramble traditional margin structures.
- EPDM:Sulfur-vulcanized and peroxide-cure formulations command the material mix through ozone resistance, thermal stability, and compression set performance in under-hood adjacent locations. EU REACH polycyclic aromatic hydrocarbon limits are accelerating peroxide chemistry adoption across Czech and German extrusion facilities. Ethylene and propylene feedstock volatility squeezes compound margins unpredictably.
- Silicone:Fluorosilicone variants capture high-temperature engine-bay adjacent applications where EPDM thermal limits fail. Japanese OEM specifications for turbocharged powertrains in Toyota City and Yokohama production networks specify silicone for thermal management proximity.
- PVC:Cost-driven formulations retain position in emerging market commercial vehicles with less stringent durability requirements.
- TPE:Thermoplastic vulcanizate compounds are migrating from experimental grades to production-scale secondary seal locations as Stuttgart and Munich suppliers qualify weight-reduction formulations.
EPDM anchors current production. TPE is climbing the fastest as OEMs pursue cabin efficiency targets.
Vehicle Type:
Application geometry and seal complexity vary dramatically—SUV body styles multiply sealing interfaces while sedans concentrate volume in standardized profiles.
- SUV:Elevated beltlines, panoramic roof options, and rear cargo access points expand total seal linear footage per vehicle platform. US domestic OEMs in Detroit and Lansing source integrated seal modules for three-row configurations with complex D-pillar geometries.
- Sedan:Traditional three-box architectures with standardized door counts and fixed rooflines maintain the highest production volume base. Chinese domestic market production in Shanghai and Wuhan sustains sedan-dominant seal demand despite segment share erosion elsewhere.
- Hatchback:Rear liftgate sealing requirements add complexity versus sedan trunk configurations.
- Truck:Commercial duty cycles and cab-bed separation create specialized sealing challenges for cabin integrity.
Sedan platforms retain volume concentration. SUV configurations are gaining share fastest across premium and mass-market electric vehicle programs.
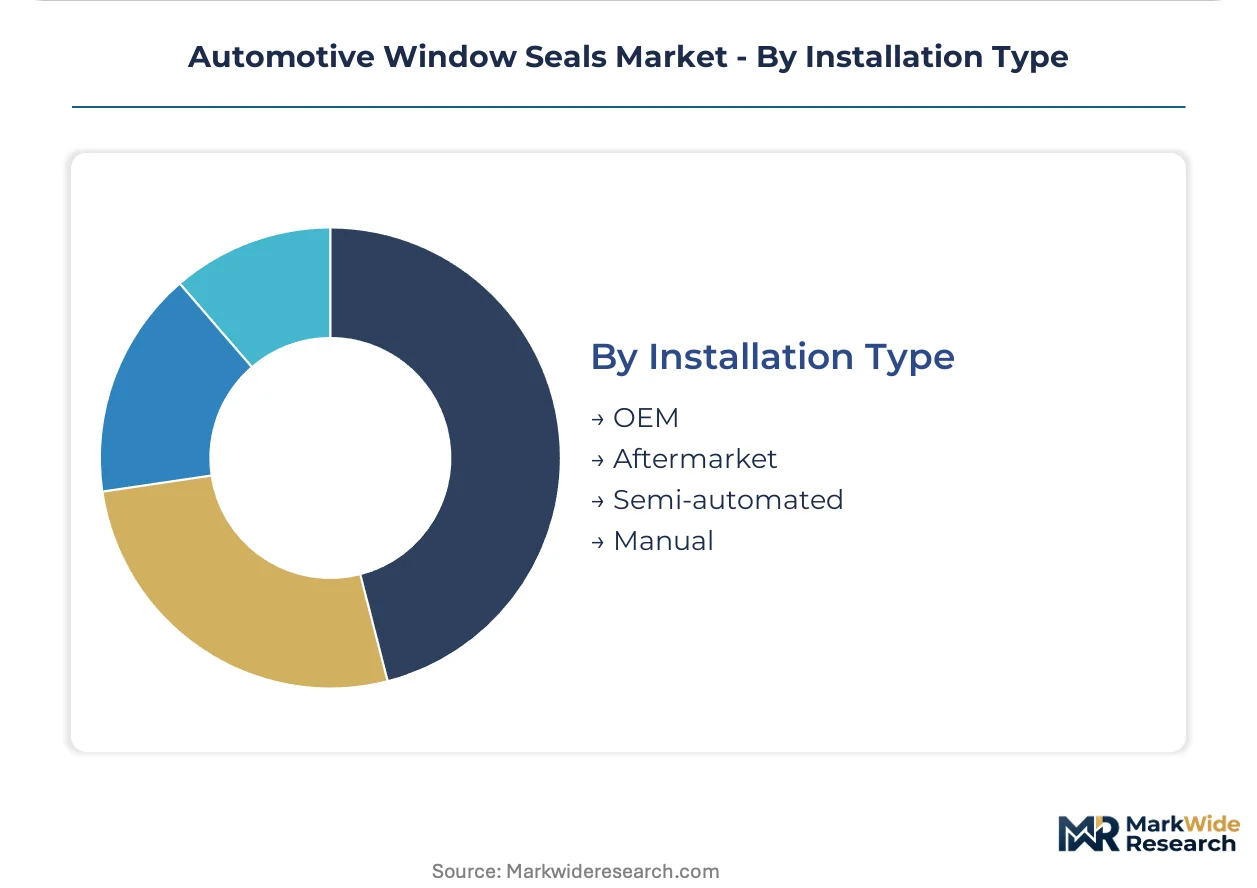
Installation Type:
Customer type determines specification authority and warranty liability—OEM direct procurement compresses supplier counts while aftermarket channels fragment across age-based replacement triggers.
- OEM:Direct platform engineering involvement, multi-year supply agreements, and extended warranty coverage through powertrain periods define this channel. Integrated extrusion-molding suppliers with rubber-to-metal bonding expertise capture consolidated sourcing decisions in Wolfsburg and Detroit battery electric vehicle programs.
- Aftermarket:Independent service channel demand tied to vehicle age distribution curves and collision repair volume. US EPA volatile organic compound emission rules from rubber extrusion processes are reshaping compliant product availability in domestic replacement channels.
- Semi-automated:Emerging installation protocols for modular seal assemblies in specific platform configurations.
- Manual:Traditional press-fit and adhesive application methods retained in repair environments and low-volume production.
OEM channels control specification authority. Aftermarket is where margin expansion concentrates as vehicle parc ages and electric vehicle penetration extends replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH regulations on polycyclic aromatic hydrocarbons anchor European compliance timelines, while divergent national standards reshape production footprints across major automotive manufacturing corridors.
Germany
Battery electric vehicle programs in Stuttgart and Wolfsburg are consolidating modular seal procurement around integrated extrusion-molding suppliers. EU REACH mandates on peroxide-cure chemistry adoption compress reformulation deadlines for Czech and German extrusion facilities. The Baden-Württemberg manufacturing corridor concentrates premium OEM contract negotiations.
United States
EPA volatile organic compound emission rules from rubber extrusion processes are reshaping compliant process technology adoption. Three-row SUV configurations in Detroit and Lansing source integrated seal modules with complex D-pillar geometries. Fleet operators in commercial segments accelerate aftermarket replacement cycles.
China
GB standards for passenger vehicle sealing performance create divergent test protocols for export versus domestic-market production. Shanghai and Wuhan sustain sedan-dominant seal demand despite segment share erosion elsewhere. The Yangtze River Delta concentrates capacity serving both domestic OEMs and export qualification programs.
Japan
Just-in-time manufacturing compresses inventory buffers and elevates supplier proximity requirements in Aichi and Kanagawa prefectures. METI industrial standards for turbocharged powertrain specifications specify silicone compounds for thermal management proximity. Toyota City production networks calibrate delivery timing to compressed Japanese OEM cycles.
India
PLI scheme incentives for automotive component manufacturing are drawing seal extrusion capacity toward Chennai and Pune industrial zones. BIS certification timelines extend product validation for domestic market entry. Maharashtra and Tamil Nadu industrial corridors concentrate emerging capacity investments.
Automotive Window Seals Market Competitive Landscape
Integrated extrusion-molding specialists and rubber-to-metal bonding experts split the market between scale-driven OEM contract capture and premium platform specification authority. Supplier counts per platform are compressing as direct procurement consolidates tier relationships. Three archetypes dominate: full-service system integrators, material-specialist compounders, and regional proximity-focused fabricators. Capacity expansion and peroxide-cure chemistry licensing represent the dominant competitive moves across European and Asian supply bases.
Among the integrated system suppliers, Cooper Standard Automotive, Hutchinson SA, and Toyoda Gosei Co., Ltd. occupy positions that exemplify the geographic clustering of OEM relationships. Cooper Standard represents the North American full-service archetype with Detroit-proximate manufacturing footprints. Hutchinson SA anchors European premium platform specification through rubber-to-metal bonding capabilities. Toyoda Gosei exemplifies the Japanese just-in-time delivery model calibrated to compressed production cycles in Aichi and Kanagawa.
| Leading Market Players |
|---|
| Cooper Standard Automotive |
| Hutchinson SA |
| Toyoda Gosei Co., Ltd. |
| Trelleborg AB |
| Freudenberg SE |
| Nishikawa Rubber Co., Ltd. |
| SaarGummi Automotive |
| Magna International Inc. |
| Saint-Gobain |
| Others |
Value Network & Pricing Analysis
Undercapacity in Czech and German extrusion facilities is tightening supplier pricing power as EU REACH peroxide-cure deadlines compress reformulation timelines. This utilization squeeze feeds directly into contract renegotiation leverage for integrated molders serving Stuttgart and Wolfsburg battery electric vehicle programs.
Pricing Analysis
German premium platforms command pricing spreads of 40-60% above mass-market Asian contracts for equivalent seal linear footage. Three-tier pricing structure across premium, standard, and economy levels stratifies by rubber-to-metal bonding complexity and compression set certification grade. Pricing pressure stems from ethylene and propylene feedstock volatility squeezing EPDM compound margins. Fleet operators in North American commercial segments exhibit highest price sensitivity, while luxury OEMs in South Korea prioritize performance specifications over unit cost.
Supply Chain Analysis
Export-control restrictions on fluorosilicone precursor chemicals limit compound flows from Japanese suppliers to European thermal management applications. Manufacturing concentrates in Germany, China, and Japan, with extrusion capacity clustering in Baden-Württemberg, Yangtze River Delta, and Aichi prefecture. Raw material supply draws from Saudi ethylene crackers, South Korean propylene derivatives, and Russian carbon black feedstocks. Single-source vulnerability concentrates in peroxide cure agent production. Distribution runs through Tier 1 modular assembly suppliers with direct OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rubber-to-metal bonding chemistry expertise has become the constraining asset in this market, with fewer than twelve qualified suppliers capable of meeting premium European platform specifications. This capability gap is reshaping competitive boundaries between integrated system houses and pure-play extruders.
For Market Incumbents: Harden peroxide-cure chemistry capabilities through licensing agreements with Czech and German specialty adhesive formulators before EU REACH enforcement windows close. Consolidate supplier counts around integrated extrusion-molding footprints to defend against silicone substitution in engine-bay adjacent applications. Capacity expansion in Chennai and Pune industrial zones captures PLI scheme incentives while hedging geographic demand concentration risk.
For New Entrants and Emerging Players: Build out thermoplastic vulcanizate compound expertise for secondary seal locations where Stuttgart and Munich OEMs are qualifying weight-reduction formulations. Target Indian domestic production incentives as the most penetrable geography, with BIS certification timelines creating defensible moats against established competitors. Pursue conductive EPDM formulation partnerships with sensor integration specialists for predictive maintenance applications.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across peroxide-cure chemistry licensing and compliant process technology investments. Long-term viability favors integrated suppliers with captive rubber-to-metal bonding capabilities rather than pure-play extruders facing margin compression. Acquisition target archetype: mid-cap European extruders with pending REACH compliance investments and established Wolfsburg or Stuttgart relationships. Monitor peroxide cure agent supply agreements as inflection signal for compound cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Peroxide-Cure Chemistry Licensing | EU REACH compliance deadlines in German extrusion facilities accelerate technology transfer negotiations. |
| Backward Integration into EPDM Compounding | Captive ethylene-propylene mixing capacity insulates margins from petrochemical feedstock volatility. |
| Sensor-Integrated Seal Development | Conductive EPDM formulations enable predictive maintenance revenue streams with OEM platform engineering. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives in Maharashtra and Tamil Nadu corridors attract seal extrusion capacity relocation. |
| Water-Based Release Agent Adoption | US EPA volatile organic compound rules create first-mover advantage for compliant process technology suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, customs and trade flow records, regulatory filing repositories, and OEM procurement disclosures. Primary interviews engaged Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and specialty chemical formulators. Secondary validation drew from IHS Markit registration data, ECHA REACH substance dossiers, SEC 10-K filings of listed automotive suppliers, and national automotive industry association reports. Bottom-up segment sizing triangulated against top-down production volume estimates.
Forecast inputs incorporate vehicle class, propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster dynamics across the analysis window. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include sunroof penetration trajectories in German and South Korean luxury platforms, EPDM recycling mandate implementation timelines, and electric vehicle thermal management sealing tolerance requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed extruders or accelerated silicone substitution in Japanese turbocharged powertrain specifications would shift outcomes. Material shifts in EU REACH enforcement intensity, ethylene-propylene feedstock price correlation breakdowns, or Indian PLI scheme incentive revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market