
 Automotive Intake Manifold Cover Market | 2026-2036
Automotive Intake Manifold Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intake Manifold Cover Market Analytics
Asian resin compounders is repositioning capacity toward high-heat nylon formulations for under-hood applications. Continental AG leverages backward integration into polymer compounding to secure feedstock consistency for its manifold cover programs. Robert Bosch GmbH anchors its position through precision injection molding scale across Central European plants. Denso Corporation specializes in thin-wall composite designs that reduce mass without sacrificing burst pressure tolerance.
An automotive intake manifold cover is a protective shroud, typically molded from glass-reinforced polyamide or cast aluminum, that seals the intake plenum and attenuates noise while managing thermal radiation from the engine block. The component must withstand continuous temperatures exceeding 150°C and resist hydrocarbon permeation to meet evaporative emissions protocols. Plastic variants lead volume share due to cost-positioning and corrosion immunity, though aluminum occupies premium applications where electromagnetic shielding or extreme thermal cycling demands metal integrity. OEM end users represent the dominant demand channel, with aftermarket providers capturing replacement volume for aging vehicle populations where cover degradation triggers air leak faults.
EPA emissions enforcement and the EU F-Gas Regulation shape material selection by restricting certain blowing agents and mandating permeation barriers in plastic formulations. NHTSA crashworthiness standards indirectly influence cover attachment geometry and fracture behavior to prevent engine bay projectile hazards. OEMs and tier-1 suppliers must monitor evolving Euro 7 particulate limits, as these may extend to gasoline direct injection systems and intensify thermal management requirements for adjacent components.
Market Dynamics
EPA Corporate Average Fuel Economy standards and Euro 7 emissions protocols are compressing development cycles for intake manifold cover suppliers, forcing simultaneous weight reduction and permeation barrier enhancement in single design generations.
Growth Catalysts
- Lightweighting mandates:OEM procurement of glass-reinforced polyamide formulations accelerates as manufacturers pursue fuel efficiency targets under NHTSA and EPA frameworks.
- China:Powertrain engineering clusters in Shanghai and Beijing drive specification intensity for high-heat nylon compounds in domestic passenger vehicle programs.
- Evaporative emissions protocols:Hydrocarbon permeation barriers in plastic formulations gain priority as regulators tighten testing procedures for under-hood components.
Market Restraints
- Resin feedstock volatility:Caprolactam and adipic acid price swings compress margin stability for compounders serving the polyamide supply chain.
- Tooling concentration:Precision injection mold fabrication concentrates among German and Japanese equipment builders, creating capacity bottlenecks for new program launches.
- Aluminum substitution ceiling:Electromagnetic shielding requirements in hybrid powertrains prevent full plastic displacement despite weight advantages.
Strategic Opportunities
- India:Underpenetrated demand for engineered polymer under-hood components creates whitespace as domestic OEMs expand gasoline direct injection production.
- Recycled content mandates:EU Green Deal circular economy requirements position post-industrial nylon regrind as a cost-advantaged feedstock source.
- Additive manufacturing convergence:Tool-less prototyping of complex thermal management geometries compresses design validation timelines for tier-1 suppliers.
Industry Challenges
- CAE simulation talent scarcity:Burst pressure and thermal cycling modeling expertise concentrates among senior engineers in Stuttgart, Detroit, and Nagoya engineering centers.
- Multi-material bonding certification:Vibration weld and laser weld validation protocols for hybrid aluminum-polyamide assemblies extend PPAP timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intake Manifold Cover Market |
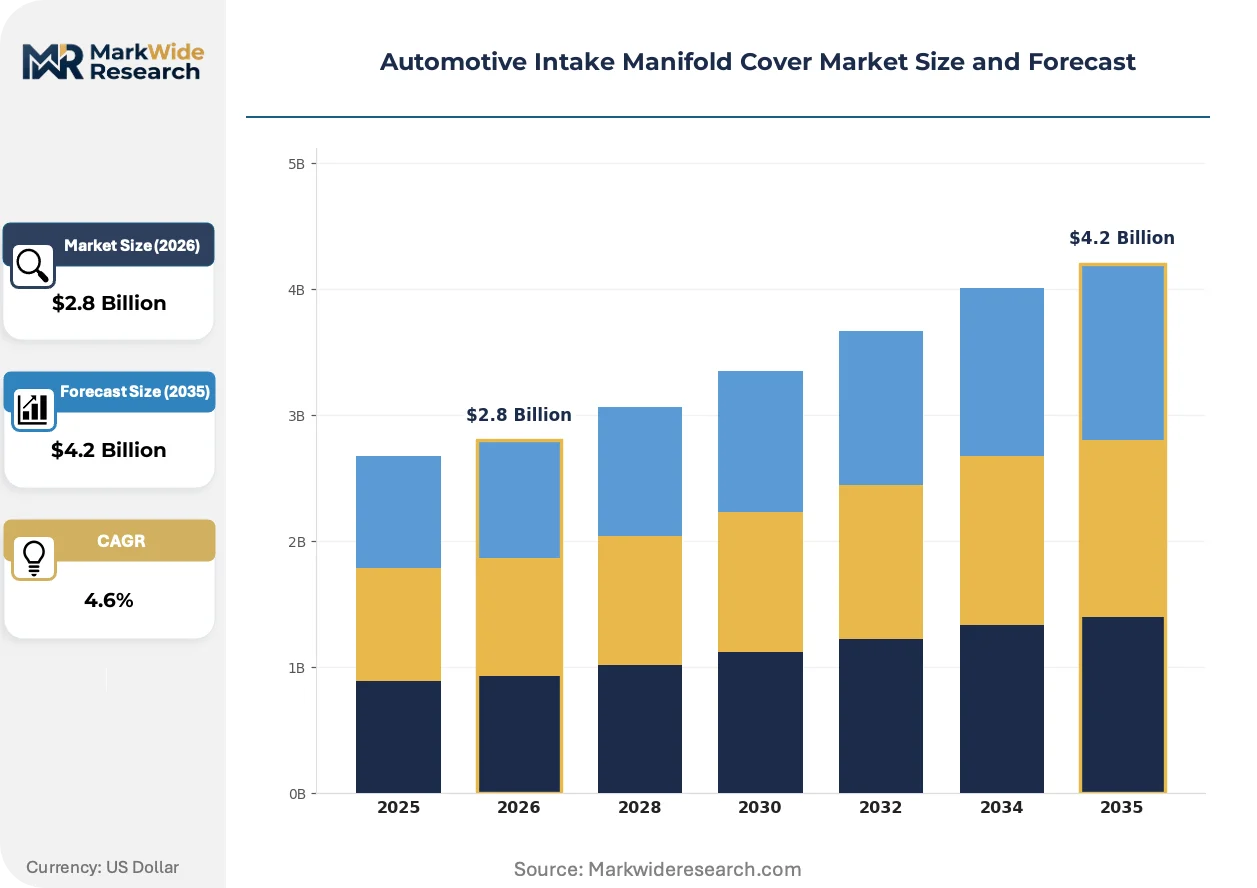
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Composite, Steel End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Vehicle Type: SUV, Sedan, Coupe, Hatchback Manufacturing Stage: Injection Molding, CNC Machining, Die Casting, Assembly |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, MAHLE GmbH, Magna International Inc., Valeo S.A., Tenneco Inc., Dana Incorporated, Marelli Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intake Manifold Cover Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape how intake manifold covers manage thermal, acoustic, and emissions performance simultaneously.
High-heat nylon 6,6 compounds with 35-50% glass fiber reinforcement are expanding into applications previously reserved for cast aluminum, as continuous-use temperature ratings climb toward 180°C. Tier-1 suppliers in Germany and Japan are qualifying these formulations for turbocharged gasoline direct injection engines where thermal shock resistance is critical. The technology is expanding into mass-market vehicle segments as OEMs consolidate platforms across multiple displacement classes.
Euro 7 particulate limits are extending coverage to gasoline direct injection systems, intensifying thermal management requirements for adjacent under-hood components including manifold covers. The regulation mandates tighter evaporative emissions control, driving specification of multi-layer co-injection molding with ethylene-vinyl alcohol barrier layers. European OEMs are responding by pre-qualifying compounded resins through ECHA REACH substance evaluation protocols ahead of 2025 implementation timelines.
Consolidated procurement of engine bay thermal management modules is displacing discrete component sourcing, with OEMs awarding system-level contracts to tier-1 suppliers capable of integrating covers, gaskets, and insulation in single assemblies. This bundling concentrates specification authority at Continental, Denso, and Bosch program offices. The shift is most visible in German and US premium vehicle platforms where platform sharing across multiple nameplates rewards modular design investment.
Automotive Intake Manifold Cover Market Segmentation
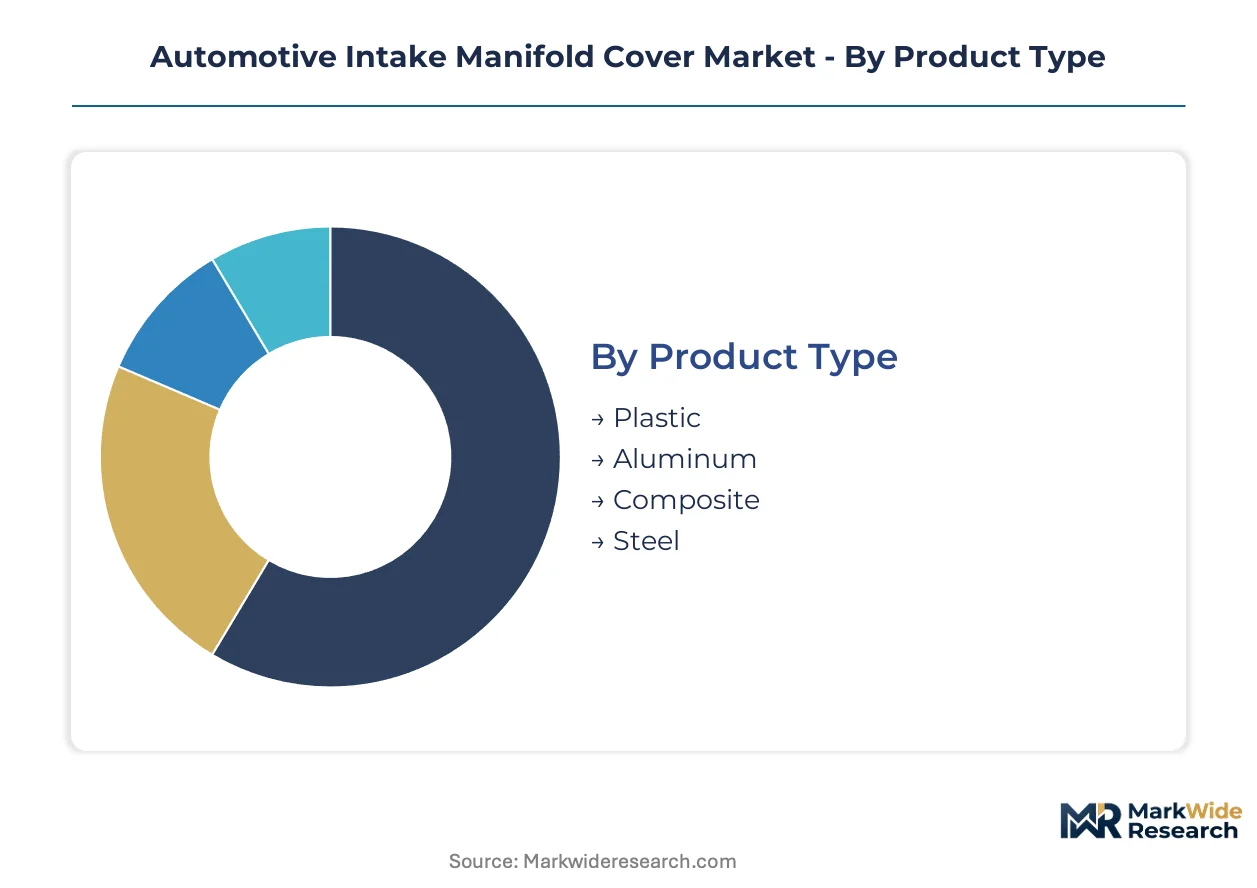
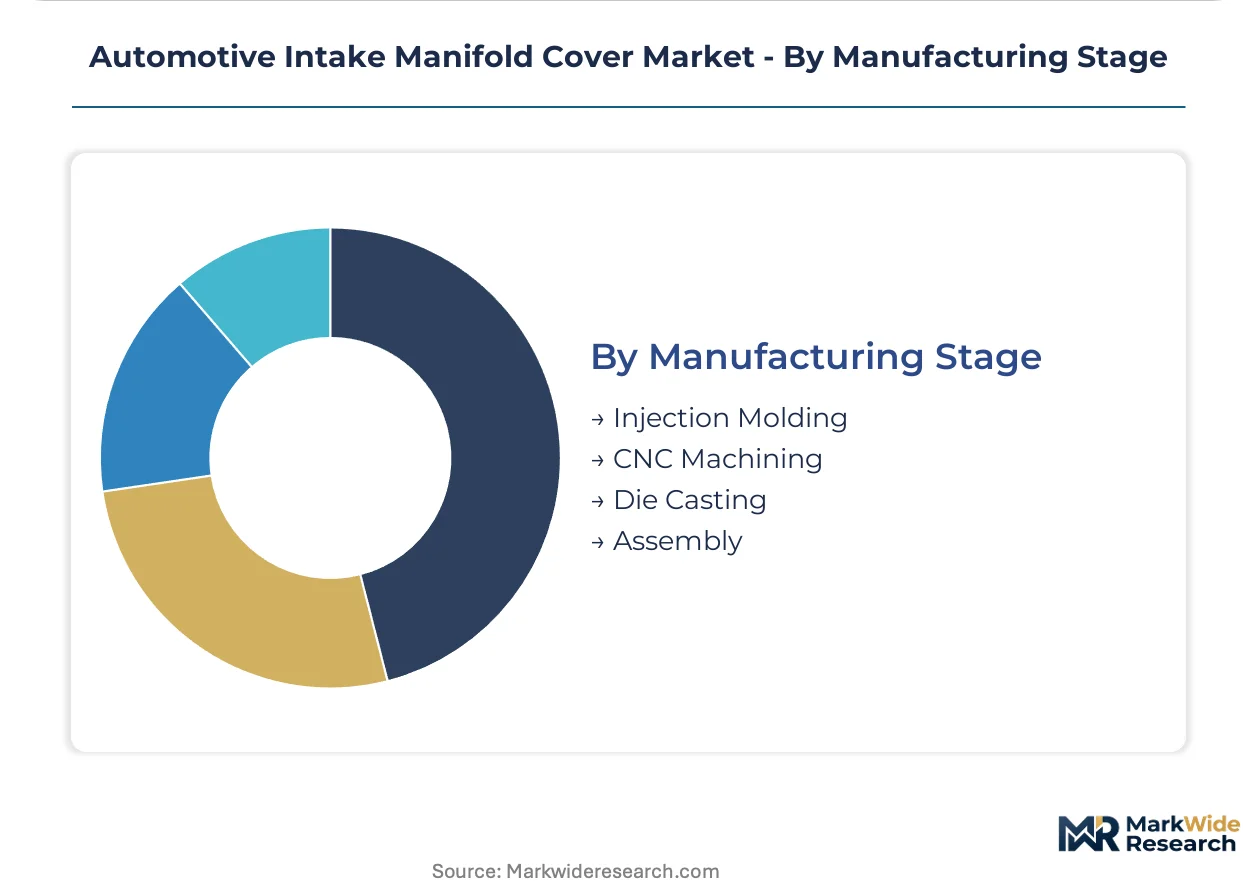
Segmentation in the automotive intake manifold cover market reveals how material selection, procurement channel, and manufacturing method intersect to determine cost position and thermal performance. Each dimension carries distinct regulatory and supply chain implications for suppliers positioning across OEM and aftermarket channels.
Product Type:
Standalone plastic covers dominate volume applications where thermal loads permit polymer substitution, while aluminum retains embedded positioning in hybrid powertrains requiring electromagnetic shielding.
- Plastic:Glass-reinforced polyamide formulations withstand continuous temperatures exceeding 150°C while offering corrosion immunity and acoustic attenuation. OEM procurement in Germany and China accelerates as EPA fuel economy standards compress development cycles for lightweight engine bay components.
- Aluminum:Cast aluminum construction delivers burst pressure tolerance and thermal cycling resistance for turbocharged direct injection architectures. Demand concentrates in premium vehicle platforms where electromagnetic shielding requirements in hybrid powertrains prevent full polymer displacement despite weight penalties.
- Composite:Hybrid material systems combining polymer matrices with metallic inserts address intermediate thermal and structural requirements.
- Steel:Stamped or formed steel variants persist in commercial vehicle and cost-optimized passenger car programs where extreme thermal management is secondary to material cost.
Plastic leads volumes today; aluminum is gaining share fastest in electrified powertrain segments.
End User:
Procurement authority concentrates differently across the value chain, with tier-1 suppliers and vehicle assemblers exercising divergent specification control depending on platform integration depth.
- OEMs:Original equipment manufacturers directly source manifold covers for powertrain platforms where thermal management module consolidation rewards single-supplier accountability. German and US premium OEMs pre-qualify compounded resins through ECHA REACH protocols ahead of Euro 7 implementation.
- Aftermarket Providers:Replacement volume captures aging vehicle populations where cover degradation triggers air leak faults and evaporative emissions failures. Demand clusters in the United States where extended vehicle lifecycles and state-level emissions enforcement sustain replacement part procurement.
- Tier-1 Suppliers:Continental, Denso, and Bosch anchor system-level contracts integrating covers, gaskets, and insulation in single assemblies.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities procure to OEM specification with limited design authority.
OEMs lead volumes today; aftermarket providers are expanding most quickly as vehicle parc ages.
Vehicle Type:
Engine bay packaging constraints and thermal load profiles vary substantially across body styles, driving specification divergence in material thickness and barrier layer configuration.
- SUV:Higher hood lines and larger engine bays accommodate thicker insulation packages and modular thermal management assemblies. Chinese domestic OEMs in Shanghai and Beijing drive specification intensity for high-heat nylon compounds in SUV gasoline direct injection programs.
- Sedan:Compact packaging demands thin-wall composite designs that reduce mass without sacrificing burst pressure tolerance.
- Coupe:Performance-oriented thermal management prioritizes rapid heat dissipation and acoustic refinement.
- Hatchback:Cost-optimized procurement favors plastic variants where continuous-use temperatures permit polymer substitution.
SUV leads volumes today; sedan is climbing the fastest as platform consolidation spreads advanced materials across mass-market segments.
Manufacturing Stage:
Process selection determines capital intensity, tooling lead time, and geometric complexity achievable for thermal management features.
- Injection Molding:Precision injection molding enables thin-wall geometries and integrated permeation barriers through multi-layer co-injection with ethylene-vinyl alcohol. Tooling fabrication concentrates among German and Japanese equipment builders, creating capacity bottlenecks for new program launches.
- CNC Machining:Subtractive processing of aluminum billets delivers tight tolerances for sealing surfaces and attachment points in low-volume premium applications.
- Die Casting:High-pressure aluminum casting achieves complex internal cooling passages for extreme thermal cycling environments.
- Assembly:Final integration of covers with gaskets, fasteners, and insulation completes thermal management module delivery to vehicle production lines.
Injection molding leads volumes today; die casting is expanding most quickly in hybrid powertrain thermal management applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China diverge in procurement intensity despite both driving specification authority for high-heat nylon compounds. The United States sustains aftermarket replacement volume through aging vehicle parc dynamics.
United States
Extended vehicle lifecycles and state-level emissions enforcement sustain aftermarket replacement procurement for aging manifold covers. NHTSA crashworthiness standards shape attachment geometry and fracture behavior to prevent engine bay projectile hazards. Detroit-area engineering centers concentrate CAE simulation expertise for burst pressure and thermal cycling validation.
Germany
Powertrain engineering clusters in Stuttgart and Munich drive specification intensity for glass-reinforced polyamide formulations across premium vehicle platforms. ECHA REACH substance evaluation protocols govern pre-qualification of compounded resins ahead of Euro 7 implementation. Continental and Bosch program offices anchor system-level contract awards for integrated thermal management modules.
China
Domestic OEM expansion in gasoline direct injection production accelerates demand for high-heat nylon compounds in Shanghai and Beijing engineering clusters. MIIT fuel efficiency mandates compress development cycles for lightweight engine bay components. Yangtze River Delta resin compounders reposition capacity toward under-hood applications with continuous-use temperature ratings exceeding 150°C.
Japan
Precision injection molding scale across Central European plants anchors supply consistency for thin-wall composite designs. METI industrial standards influence thermal management specifications for turbocharged direct injection architectures. Nagoya engineering centers concentrate burst pressure modeling expertise for hybrid aluminum-polyamide assembly validation.
India
Underpenetrated demand for engineered polymer under-hood components creates whitespace as domestic OEMs expand gasoline direct injection production. BIS material certification requirements shape qualification timelines for imported compounded resins. Tamil Nadu and Maharashtra automotive corridors attract tier-1 supplier investments for localized manifold cover fabrication.
Automotive Intake Manifold Cover Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold precision molding scale across complementary geographies. The vendor base concentrates among integrated system suppliers and component specialists serving distinct procurement channels. Three archetypes dominate: backward-integrated polymer compounders, precision injection molders, and modular thermal management integrators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as OEMs consolidate platform sourcing.
Within the integrated system supplier tier, Continental AG exemplifies backward integration into polymer compounding to secure feedstock consistency. Robert Bosch GmbH occupies a position defined by precision injection molding scale across Central European manufacturing footprints. Denso Corporation represents the thin-wall composite design specialization that reduces mass without sacrificing burst pressure tolerance. These three anchors illustrate how specification authority concentrates at program offices capable of delivering integrated thermal management modules rather than discrete components.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| MAHLE GmbH |
| Magna International Inc. |
| Valeo S.A. |
| Tenneco Inc. |
| Dana Incorporated |
| Marelli Holdings Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Backward integration into polymer compounding anchors Continental AG's supply position and pricing power, insulating its manifold cover programs from caprolactam volatility while compressing competitor margins on feedstock-insecure tiers. This captive supply model concentrates cost advantage among German and Japanese tier-1 suppliers serving EPA and Euro 7 compliance timelines.
Pricing Analysis
Capacity additions in China are reshaping price floors for glass-reinforced polyamide formulations as Yangtze River Delta compounders reposition toward under-hood applications. Three-tier pricing structure across premium OEM specification, mid-tier domestic supply, and economy aftermarket replacement segments stratifies the market. Price differentiation hinges on ECHA REACH pre-qualification status and burst pressure certification tier. Cost compression in standard-grade supply is intensifying because MIIT fuel efficiency mandates compress development cycles for domestic Chinese OEMs. Aftermarket providers exhibit highest price sensitivity due to aging vehicle parc economics, while German premium OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Bosch and Denso program offices mandate multi-supplier qualification for high-heat nylon compounds across German and Japanese resin compounders. Geographic supply concentration centers on Germany, China, and Japan where precision injection mold fabrication and polymer compounding capacity cluster. Raw material dependencies rest on caprolactam, adipic acid, and ethylene-vinyl alcohol barrier resin feedstocks. Single-source vulnerability concentrates in German and Japanese tooling equipment builders where capacity bottlenecks delay new program launches. Distribution runs through tier-1 thermal management module integrators to OEM assembly plants, with aftermarket channels feeding through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Euro 7 particulate limits and EPA Corporate Average Fuel Economy standards intensify material specification requirements and compress supplier development cycles simultaneously.
For Market Incumbents: Anchor specification authority through ECHA REACH pre-qualification of compounded resins ahead of regulatory implementation timelines. Defend against aluminum substitution in hybrid powertrains by qualifying next-generation nylon 6,6 formulations with 180°C continuous-use ratings. Prioritize captive polymer compounding capacity to secure margin position against resin feedstock volatility.
For New Entrants and Emerging Players: Direct-to-OEM digital specification platforms offer route to bypass tier-1 procurement gatekeepers in India's underpenetrated gasoline direct injection supply base. Target Tamil Nadu and Maharashtra automotive corridors where domestic OEM expansion creates whitespace for localized manifold cover fabrication. Pursue additive manufacturing tool-less prototyping capabilities to compress design validation timelines for tier-2 supplier qualification.
For Investors and Strategic Acquirers: Roll-up economics work for precision injection molding specialists because tooling concentration among German and Japanese equipment builders creates scarcity value for qualified manufacturing assets. Five-to-ten year viability hinges on positioning for thermal management module consolidation trends. Watch for Euro 7 enforcement intensity as signal for accelerated multi-layer co-injection molding capacity demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Continental AG secures feedstock consistency against caprolactam price swings. |
| Multi-Layer Co-Injection Molding Scale-Up | Denso qualifies ethylene-vinyl alcohol barrier layers for Euro 7 evaporative emissions compliance. |
| CAE Simulation Talent Acquisition | Bosch anchors burst pressure modeling expertise in Stuttgart engineering center. |
| India Manufacturing Footprint Expansion | Tier-1 suppliers localize fabrication to serve Mahindra and Tata gasoline direct injection programs. |
| Post-Industrial Nylon Regrind Sourcing | EU Green Deal circular economy requirements position recycled feedstock as cost-advantaged input. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market's powertrain engineering and procurement stakeholders. Triangulation combines interviews with OEM platform engineers, tier-1 supplier procurement leads, resin compounder technical directors, and aftermarket distributor operations managers with secondary validation from vehicle production databases, IHS Markit registration data, EPA enforcement disclosures, and ECHA REACH substance evaluation protocols. Bottom-up segment modeling and top-down macroeconomic cross-checks anchor volume and value estimates.
Granularity-level framing applies material type, end-user channel, vehicle class, and manufacturing process dimensions at country-level resolution across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers and regulatory milestone timing. Industry-specific forecast inputs include gasoline direct injection penetration curves, hybrid powertrain adoption patterns, and evaporative emissions testing protocol evolution.
Resin feedstock price volatility, regulatory enforcement timing shifts, and hybrid powertrain electromagnetic shielding specification changes are the dominant revision risks to modeled outputs. Deviation in Euro 7 implementation intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Rocker Panel Market