
 Automotive Foam Market | 2026-2036
Automotive Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Foam Market Analysis
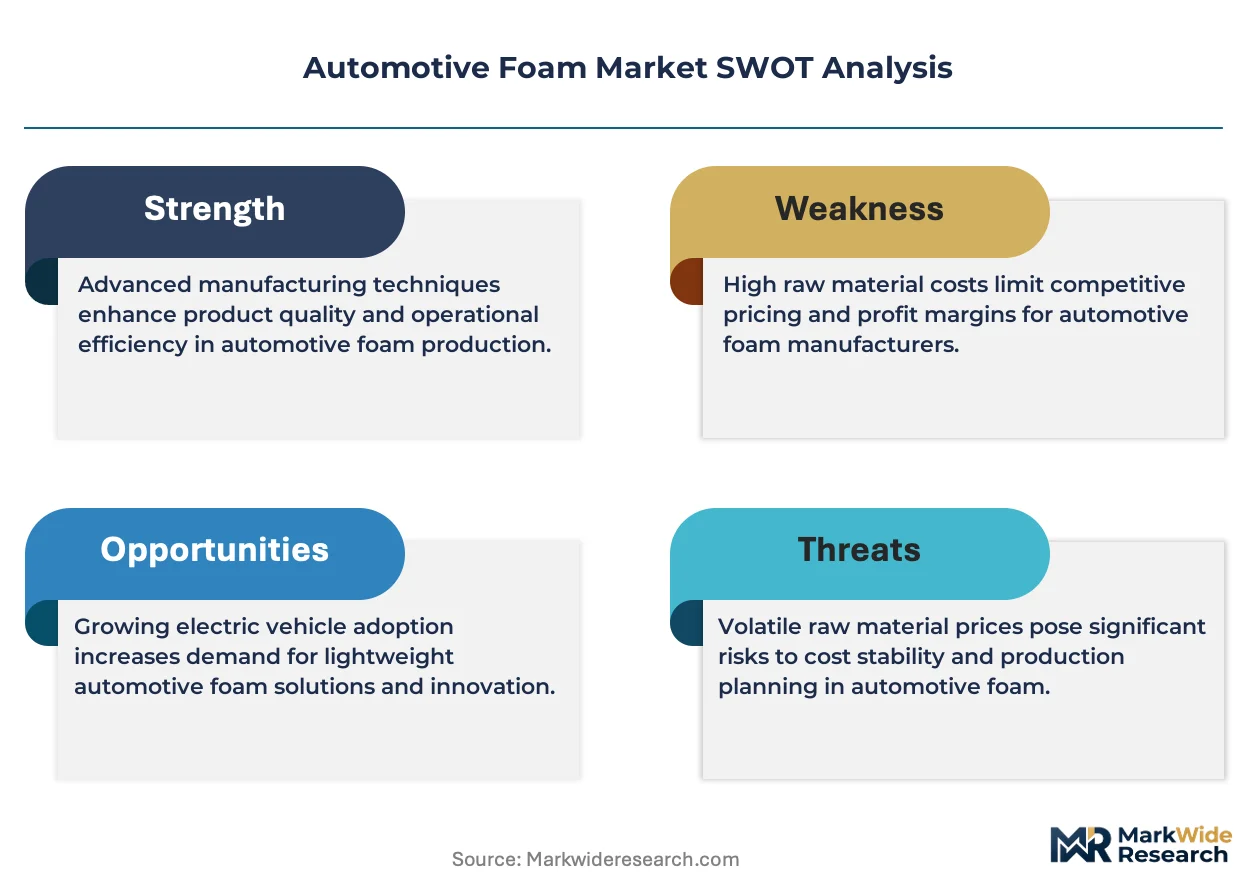
Software-defined thermal management subscriptions is rebalancing how automakers procure interior and battery-pack foam systems. BASF SE leverages its integrated polyurethane precursor network to sustain supply security for European OEM programs. Dow anchors North American demand through specialized foam grades engineered for electric vehicle battery enclosures. Covestro AG competes on low-emission foam chemistry leadership aligned with tightening interior air quality protocols.
Automotive foam encompasses cellular polymer structures—typically polyurethane, polyethylene, or polypropylene—with densities ranging from 15 to 200 kg per cubic meter, manufactured through injection molding, thermoforming, or spray application to deliver cushioning, thermal insulation, acoustic dampening, and structural energy absorption in vehicle architectures. Polyurethane foam dominates seating and interior trim applications due to established supply chains and tunable hardness profiles, while polyethylene foam is gaining structural share in battery pack insulation as electric vehicle thermal runaway protection requirements intensify. Spray foam technology commands premium positioning for complex cavity filling and acoustic optimization, though thermoforming retains cost advantages in high-volume interior component production.
The EPA regulates volatile organic compound emissions from automotive interior materials under federal air quality standards, while the EU F-Gas Regulation restricts fluorinated blowing agents in foam production, and China's GB standards mandate specific flammability ratings for passenger compartment materials. These frameworks compel foam producers to reformulate chemistries, validate alternative blowing agents, and maintain multi-jurisdiction certification portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven supply chain fragmentation.
Market Dynamics
Electric vehicle thermal management requirements are restructuring foam procurement priorities, with battery enclosure insulation now commanding dedicated supply lines separate from traditional seating and interior applications.
Growth Catalysts
- Battery Thermal Runaway Mandates:China's GB standards and the EU Battery Regulation now require multi-layer foam barriers between battery cells, creating dedicated procurement categories for flame-retardant polyurethane systems.
- Interior Air Quality Protocols:California's foam emission standards and the EU F-Gas Regulation are forcing reformulation cycles that favor suppliers with validated low-VOC chemistry portfolios.
- Seating Electrification:Heated and ventilated seat architectures require foam substrates with embedded conductive elements, expanding addressable content per vehicle in premium trim configurations.
Market Restraints
- Polyol Feedstock Volatility:Propylene oxide and TDI pricing swings compress foam producer margins, particularly for commodity-grade seating applications where pass-through mechanisms lag input cost movements by 6-9 months.
- Blowing Agent Transition Costs:The EU F-Gas Regulation's phasedown of HFC-245fa and similar agents forces capital-intensive retooling of continuous slabstock lines, concentrating compliance burden on mid-volume European producers.
- Structural Substitution in Battery Packs:Aerogel blankets and mica sheet composites are displacing foam in high-temperature zones of battery enclosures, constraining foam's addressable share of thermal protection value.
Strategic Opportunities
- India Automotive Production Scaling:The country's PLI scheme for advanced chemistry cell batteries is attracting cell manufacturing investment, creating localized demand for pack-level foam insulation as domestic EV assembly expands.
- Circular Foam Chemistry:Chemical recycling pathways for polyurethane via glycolysis and pyrolysis are reaching pilot scale, positioning early movers for extended producer responsibility frameworks under the EU Green Deal.
- Acoustic Foam Integration:Active noise cancellation hardware requires precisely tuned cavity-filling foam geometries, opening specification windows for spray-applied systems in luxury electric vehicle architectures.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Foam producers must maintain parallel testing protocols for EPA VOC standards, EU F-Gas compliance, and China's GB flammability ratings, stretching technical resources across fragmented approval timelines.
- Thermal-Mechanical Co-Design Complexity:Battery pack foam must simultaneously satisfy crush-strength specifications for crash safety and thermal conductivity targets for runaway propagation delay, requiring cross-functional engineering coordination that legacy seating suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Foam Market |
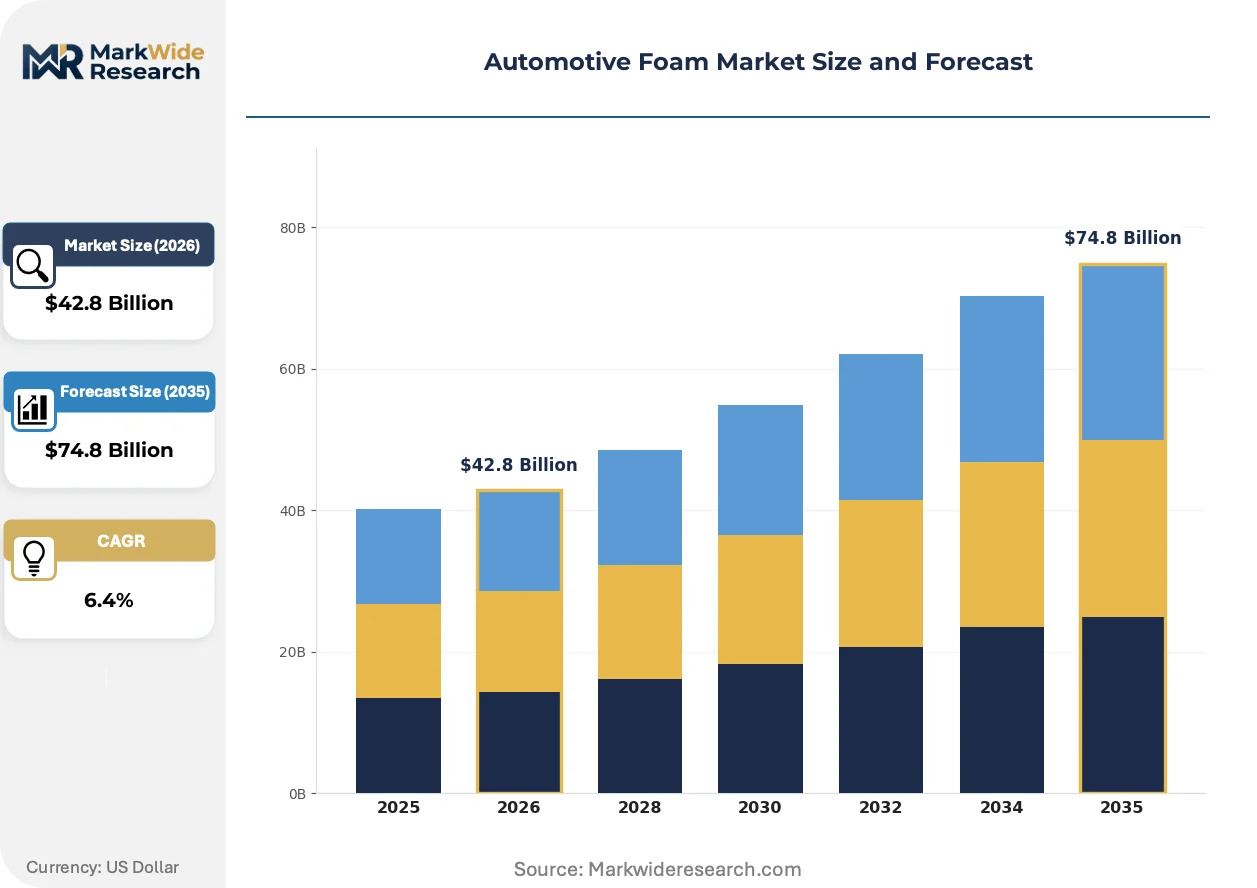
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polyethylene Foam, Polypropylene Foam, Natural Rubber Foam Technology: Injection Molding, Thermoforming, Compression Molding, Spray Foam Application: Seating, Interior Trim, Insulation, Soundproofing End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | BASF SE, Bridgestone Corporation, Dow, Covestro AG, Woodbridge, Johnson Controls, Recticel, Huntsman International LLC, Armacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Foam Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are converging to reshape how foam systems are specified, validated, and integrated into vehicle architectures across powertrain categories.
Bio-based polyol feedstocks derived from castor oil and soybean oil are absorbing incremental volume in European seating applications as OEM sustainability scorecards weight renewable content percentages in supplier selection criteria. BMW and Mercedes-Benz have established minimum bio-based thresholds for foam content in specific model lines, compressing the specification window for purely petroleum-derived systems. This feedstock transition is absorbing capital allocation that would otherwise expand conventional polyol capacity.
The EU F-Gas Regulation's phasedown schedule for fluorinated blowing agents is forcing accelerated adoption of hydro-olefin and water-blown alternatives across foam production lines serving European OEM programs. Formulators must revalidate physical property profiles—density, compression set, and fatigue resistance—under new blowing chemistries, extending qualification cycles by 12-18 months. Spray foam applications for acoustic cavity filling face the steepest reformulation burden due to precise cell structure requirements.
Fleet operators and leasing companies are consolidating foam procurement decisions at the platform level rather than delegating to individual plant engineering teams, compressing the number of approved suppliers per OEM group. This concentration is visible most acutely in Germany, where commercial fleet electrification timelines have accelerated and thermal management system standardization across van and truck platforms is prioritized. Tier-2 foam converters must now secure group-level technical approvals rather than plant-by-plant qualifications.
Automotive Foam Market Segmentation
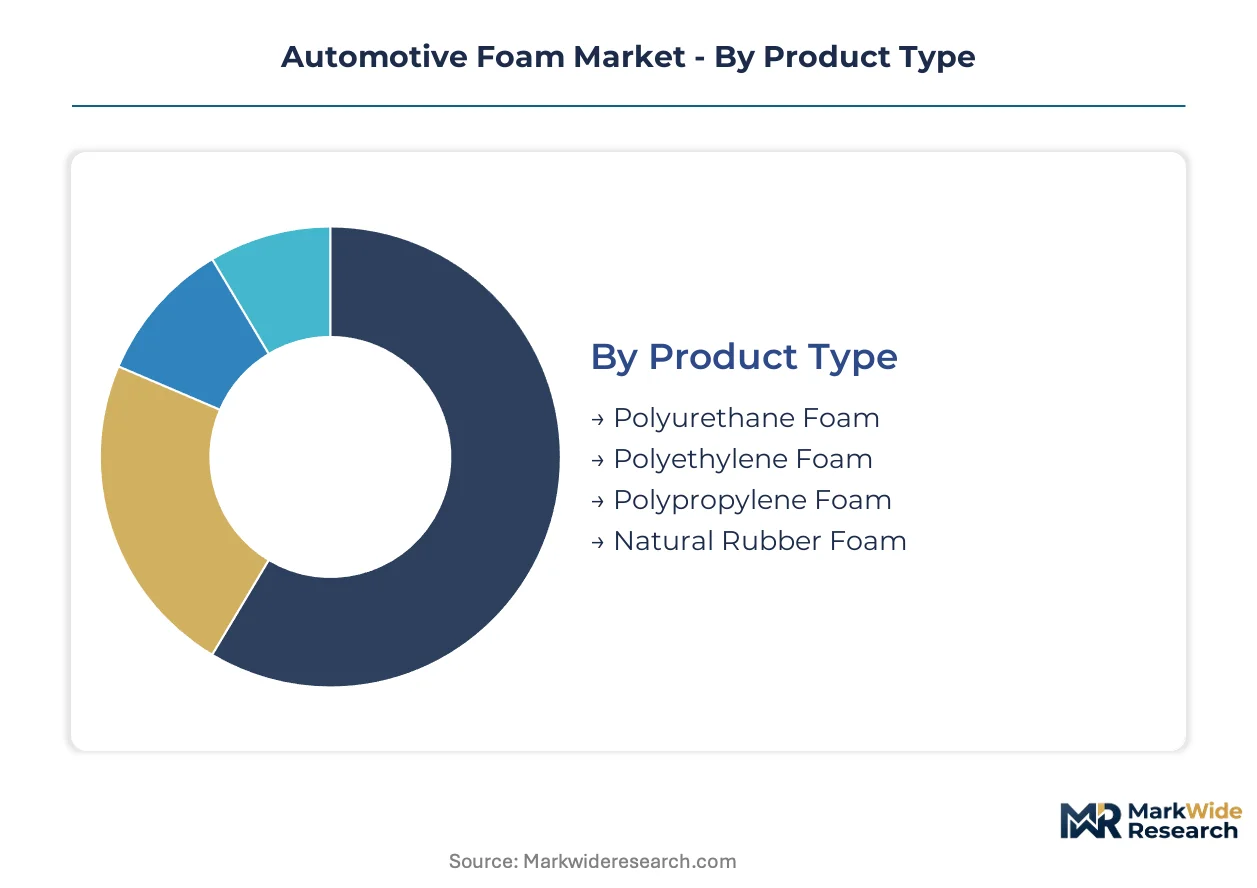
Segmentation reveals how automotive foam procurement splits across fundamentally different technical requirements. Battery thermal management systems now operate on separate specification tracks from traditional seating applications. Understanding these divisions exposes where reformulation investments concentrate and where substitution risks loom.
Product Type:
Upgrade cycles in electric vehicle architectures are pulling foam selection away from legacy comfort specifications toward thermal runaway containment performance.
- Polyurethane Foam:Open-cell structures dominate seating and interior trim with tunable hardness profiles from 25 to 80 Shore A. BASF SE and Covestro AG supply reformulated low-VOC grades to German OEMs facing EU F-Gas Regulation compliance deadlines.
- Polyethylene Foam:Closed-cell cross-linked structures deliver crush resistance and thermal stability for battery pack insulation layers. Chinese cell manufacturers under GB standards mandate multi-layer polyethylene barriers between pouch cells, creating dedicated procurement categories.
- Polypropylene Foam:Expanded bead structures serve bumper cores and load floor applications with superior chemical resistance to battery electrolyte exposure.
- Natural Rubber Foam:Latex-based cellular structures retain niche positioning in luxury seating where renewable content thresholds apply.
Polyurethane Foam sits at the top of the volume ranking, with Polyethylene Foam climbing the fastest.
Technology:
Process selection traces directly to part complexity, surface finish requirements, and the capital intensity of tooling transitions.
- Injection Molding:High-pressure polyurethane dispensing achieves complex geometries with Class A surface finishes for instrument panels and door panels. Thermoforming retains cost advantages in high-volume interior component production where design cycles extend across multiple model years.
- Thermoforming:Vacuum and pressure forming of foam sheets produces lightweight structural panels with predictable material yields. North American truck and SUV platforms specify thermoformed polyethylene trunk liners and load floors.
- Compression Molding:Matched-die processes consolidate fiber-reinforced foam composites for structural energy absorption in bumper systems.
- Spray Foam:Two-component polyurethane systems fill irregular cavities for acoustic optimization and thermal insulation. The EU F-Gas Regulation's HFC-245fa phasedown forces reformulation of spray systems with hydro-olefin blowing agents.
Thermoforming commands the highest production volumes, while Spray Foam expands most quickly in luxury electric vehicle architectures.
Application:
Application segmentation tracks the divergence between occupant-facing comfort systems and powertrain-protection functions.
- Seating:Multi-density polyurethane constructions combine support foam with comfort layers, now integrating conductive elements for heated and ventilated architectures. Mercedes-Benz and BMW specifications mandate minimum bio-based polyol content.
- Interior Trim:Dashboard, door panel, and headliner foams face California foam emission standards and EPA VOC regulations requiring low-aldehyde formulations.
- Insulation:Battery pack and HVAC thermal barriers now constitute a separate specification track with distinct flammability and conductivity requirements.
- Soundproofing:Acoustic cavity filling and dash insulation demand precise airflow resistance tuning for active noise cancellation compatibility.
Seating maintains volume leadership, with Insulation posting the steepest expansion trajectory.
End User:
Procurement authority concentration is reshaping how foam converters secure program approvals and pricing leverage.
- OEMs:Volkswagen Group, Stellantis, and General Motors consolidate foam specifications at platform level, compressing approved supplier lists. Direct OEM contracts now cover battery pack insulation previously sourced through Tier-1 integrators.
- Aftermarket Suppliers:Independent service channels for seat repair and replacement trim operate on shorter lead times with less stringent emission compliance requirements.
- Vehicle Assemblers:Contract manufacturers and joint venture plants in China apply parent-company specifications with localized sourcing mandates.
- Tier-1 Suppliers:Lear Corporation and Adient retain foam procurement authority for complete seat systems, though battery pack insulation increasingly bypasses this channel.
OEMs dominate procurement value, with Tier-1 Suppliers facing margin compression from direct material sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting automotive foam investment toward jurisdictions with manageable compliance costs and clustered OEM demand. Manufacturers weigh EU F-Gas phasedown timelines against China's GB standard enforcement density when locating new capacity.
China
Cell manufacturers under GB standards mandate multi-layer polyethylene barriers between battery cells, creating dedicated procurement categories for flame-retardant systems. MIIT oversees dual carbon goals that pressure domestic foam producers toward water-blown chemistry transitions. Production concentrates in the Yangtze River Delta where CATL and BYD anchor cell manufacturing clusters requiring localized thermal barrier supply.
Germany
The EU F-Gas Regulation's HFC-245fa phasedown forces accelerated hydro-olefin adoption across continuous slabstock lines serving Volkswagen Group and BMW platforms. KBA enforces type-approval protocols that extend foam qualification cycles by 12-18 months. Bavaria's chemical corridor hosts BASF SE and Covestro AG precursor networks sustaining supply security for European OEM programs.
United States
EPA VOC standards and California's foam emission standards compel low-aldehyde reformulations for interior applications while battery thermal management drives separate specification tracks. The Inflation Reduction Act's domestic content requirements pull foam converter investment toward Michigan and Ohio assembly corridors. Dow anchors North American demand through specialized grades engineered for electric vehicle battery enclosures.
India
The PLI scheme for advanced chemistry cell batteries is attracting cell manufacturing investment, creating localized demand for pack-level foam insulation as domestic EV assembly expands. BIS mandates flammability ratings that diverge from EU and US protocols, stretching certification resources. Tamil Nadu and Gujarat host emerging cell and vehicle assembly clusters where procurement localization is accelerating.
South Korea
METI-aligned battery safety protocols for thermal runaway containment drive specification complexity for foam barriers in pouch and prismatic cell architectures. Domestic OEMs consolidate foam procurement at platform level, compressing approved supplier lists. The Seoul Capital Area concentration of Hyundai-Kia engineering centers shapes regional demand for integrated thermal-mechanical co-design capabilities.
Automotive Foam Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with chemistry-integrated multinationals commanding battery thermal management categories while regional converters retain seating and trim applications. The vendor base organizes around three archetypes: integrated petrochemical players with precursor control, independent foam converters with formulation flexibility, and automotive Tier-1 suppliers with seat system integration authority. Consolidation pressure concentrates in European continuous slabstock capacity where F-Gas compliance costs disadvantage mid-volume producers. Cross-border M&A and backward integration into polyol supply are the dominant competitive moves reshaping competitive positioning.
Within the integrated chemistry tier, BASF SE and Covestro AG exemplify players with captive precursor networks and multi-jurisdiction certification portfolios. Dow occupies a position among North American petrochemical anchors with specialized foam grades for electric vehicle architectures. Recticel represents the independent European converter archetype navigating reformulation cycles under tightening emission protocols. These three companies illustrate how scale and chemistry integration separate winners from margin-compressed commodity suppliers.
| Leading Market Players |
|---|
| BASF SE |
| Bridgestone Corporation |
| Dow |
| Covestro AG |
| Woodbridge |
| Johnson Controls |
| Recticel |
| Huntsman International LLC |
| Armacell |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between low-VOC foam systems and commodity seating grades manifests in both pricing premiums and supply chain segmentation. European OEMs under EU F-Gas Regulation deadlines pay material surcharges for validated hydro-olefin chemistry portfolios, while North American truck platforms source thermoformed polyethylene trunk liners through consolidated distributor networks.
Pricing Analysis
Direct-to-OEM contract structures dominate battery thermal management foam procurement, compressing distributor margins to single-digit percentages versus double-digit markups in aftermarket seating channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with EPA-compliant low-aldehyde formulations commanding 15-20% premiums over commodity grades. Cost compression in commodity seating applications is intensifying because polyol feedstock volatility outruns pass-through mechanisms by 6-9 months. Fleet procurement consolidation at platform level renders small-volume converters most price-sensitive, while battery pack insulation buyers prioritize thermal-mechanical performance over unit cost.
Supply Chain Analysis
Returns and reformulation flows from EU F-Gas compliance cycles are creating secondary raw material channels for glycolysis-based chemical recycling pilots. Production gravity centers on Germany, China, and the United States, with BASF SE's Ludwigshafen complex and Dow's Michigan operations anchoring precursor supply for regional OEM programs. The supply chain draws from propylene oxide, TDI, and specialized hydro-olefin blowing agents as critical inputs. Single-source vulnerability concentrates in European continuous slabstock capacity where mid-volume producers face capital-intensive retooling timelines. Distribution runs through Tier-1 seat integrators for occupant-facing applications, while battery pack insulation increasingly bypasses this channel for direct OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive foam hinges on chemistry-integrated players capturing premium-tier battery thermal management specifications while commodity seating faces polyol cost compression.
For Market Incumbents: Anchor supply security through captive precursor networks serving Volkswagen Group and BMW platform consolidation. BASF SE's integrated polyurethane chemistry demonstrates how backward integration into polyol production defends margin position against feedstock volatility. Accelerate hydro-olefin blowing agent validation to meet KBA-extended qualification cycles before mid-volume European competitors complete retooling. For New Entrants and Emerging Players: Battery pack insulation procurement bypassing Tier-1 integrators represents the most penetrable channel for specialized foam converters. India's PLI scheme for advanced chemistry cell batteries creates localized demand as domestic EV assembly scales in Tamil Nadu and Gujarat. Pursue technical co-development partnerships with CATL and BYD engineering centers rather than competing on commodity seating specifications. For Investors and Strategic Acquirers: Consolidation pressure builds where EU F-Gas compliance costs disadvantage mid-volume European producers lacking chemistry integration. Long-term viability favors acquirers of reformulation-capable converters with multi-jurisdiction certification portfolios already validated under EPA VOC standards and China's GB flammability protocols. Watch for inflection when fleet procurement standardization across van and truck platforms accelerates in Germany.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Precursors | BASF SE's captive supply network secures margin protection against propylene oxide volatility for European OEM programs. |
| Hydro-Olefin Blowing Agent Transition | Reformulation investments align Covestro AG production with EU F-Gas Regulation phasedown timelines for HFC-245fa. |
| Battery Thermal Management Specialization | Dow's engineered grades for electric vehicle enclosures capture direct OEM procurement bypassing Tier-1 integrators. |
| Chemical Recycling Pilot Scaling | Glycolysis pathways for polyurethane recovery position early movers under EU Green Deal extended producer responsibility frameworks. |
| Platform-Level Procurement Consolidation | Volkswagen Group specification compression reduces approved supplier lists and concentrates volume with chemistry-integrated multinationals. |
Methodological Framework
Coverage spans China, Germany, the United States, India, and South Korea, with primary inputs from each market's production clusters. The analysis combines structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, foam converter plant managers, and chemical R&D directors with secondary validation from customs/trade data, vehicle production databases, SEC 10-K filings, and IHS Markit registration data. Bottom-up segment sizing triangulates against top-down market value estimates.
Rate-of-change decomposition separates volume growth from value-per-unit shifts across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from regression analysis of historical production data against regulatory mandate timelines and OEM electrification commitments. Forecast inputs incorporate battery thermal runaway specification evolution and blowing agent chemistry transition costs.
Revisions become necessary when regulatory enforcement density shifts, feedstock price volatility exceeds historical bands, or aerogel substitution accelerates in high-temperature battery zones. Forecasts reflect documented assumptions about OEM platform consolidation timing and chemical recycling scale-up trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market