
 Global Automotive Windows and Exterior Sealing Market | 2026-2036
Global Automotive Windows and Exterior Sealing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Windows and Exterior Sealing Market Intelligence
The IATF 16949 quality management standard is bifurcating the supplier landscape, separating certified component manufacturers from smaller, non-compliant entities. Hutchinson Sealing Systems leverages its extensive global manufacturing footprint to meet OEM requirements across diverse regions. Cooper Standard Automotive Inc. differentiates through material science innovation, particularly in advanced elastomers for EV applications. Magna International Inc. positions its sealing solutions within a broader, integrated systems portfolio for global automakers.
Automotive windows and exterior sealing systems are engineered components designed to prevent environmental intrusion into a vehicle's cabin and protect its structure. These products, often manufactured through co-extrusion processes using materials like EPDM rubber, provide critical barriers against water, air, and noise. Thermoplastic elastomers represent the fastest-growing technology segment due to their recyclability and design flexibility. Within product types, demand for complex weatherstrips and body seals with integrated sensors is outpacing traditional glass seals.
Product composition and performance are governed by a complex web of international standards. Regulations such as the US EPA's vehicle emissions standards, the EU's REACH directive on chemical substances, and China's GB standards for material safety directly influence material selection and component design. Supplier success will depend on navigating these disparate regulatory environments while investing in materials that meet evolving OEM demands for lightweighting and sustainability.
Market Dynamics
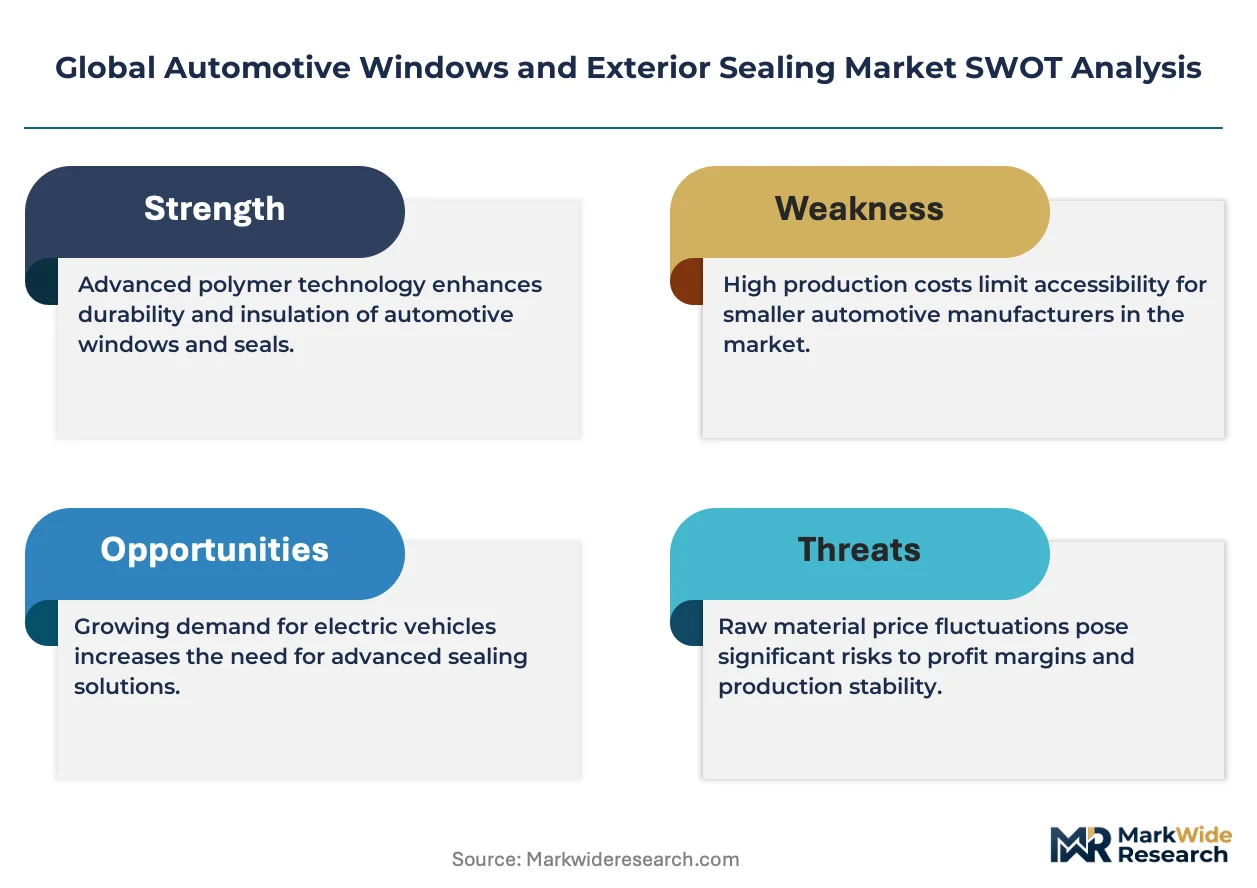
The transition to electric vehicles is the central force shaping the market. Heightened requirements for cabin quietness and battery thermal management are fundamentally altering material specifications and component complexity for all exterior sealing products.
Growth Catalysts
- Thermoplastic Elastomers:The material's inherent recyclability and design flexibility in co-extrusion processes are driving adoption by OEMs focused on sustainability and lightweighting initiatives.
- EU Noise Regulations:Mandates from the European Union limiting vehicle pass-by noise levels directly compel automakers to invest in superior acoustic sealing systems to ensure compliance.
- China's Production Volume:The immense scale of passenger car and EV manufacturing in China creates a massive, concentrated source of volume demand for all types of weatherstrips and body seals.
Market Restraints
- Raw Material Volatility:Fluctuations in the price and availability of key synthetic rubber feedstocks, particularly EPDM, create significant cost pressures and margin instability for seal manufacturers.
- Manufacturing Concentration:Specialized co-extrusion technology for complex, multi-durometer seals is concentrated among a few large suppliers, creating potential supply chain bottlenecks for OEMs.
- Acoustic Software Substitution:The advancement of in-cabin active noise cancellation software presents a long-term substitution threat, potentially reducing the need for highly engineered physical acoustic seals.
Strategic Opportunities
- Sensor Integration:There is a significant opportunity to embed sensors directly into sealing profiles for functions like obstacle detection and advanced driver-assistance systems, creating higher-value components.
- Sustainable Materials:Developing sealing solutions from bio-based polymers or with high-recycled content aligns with OEM ESG goals and regulations like the EU's Corporate Sustainability Reporting Directive.
- Emerging EV Hubs:Expanding manufacturing capabilities in growing automotive production centers across Southeast Asia and Mexico can capture demand from new EV assembly plants.
Industry Challenges
- Certification Burden:The rigorous process and continuous audits required for IATF 16949 certification represent a substantial operational and financial hurdle, particularly for smaller component suppliers.
- Capital Investment:Upgrading production lines for multi-material co-extrusion and automated finishing demands significant capital expenditure, limiting the ability of some firms to compete for advanced EV programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Windows and Exterior Sealing Market |
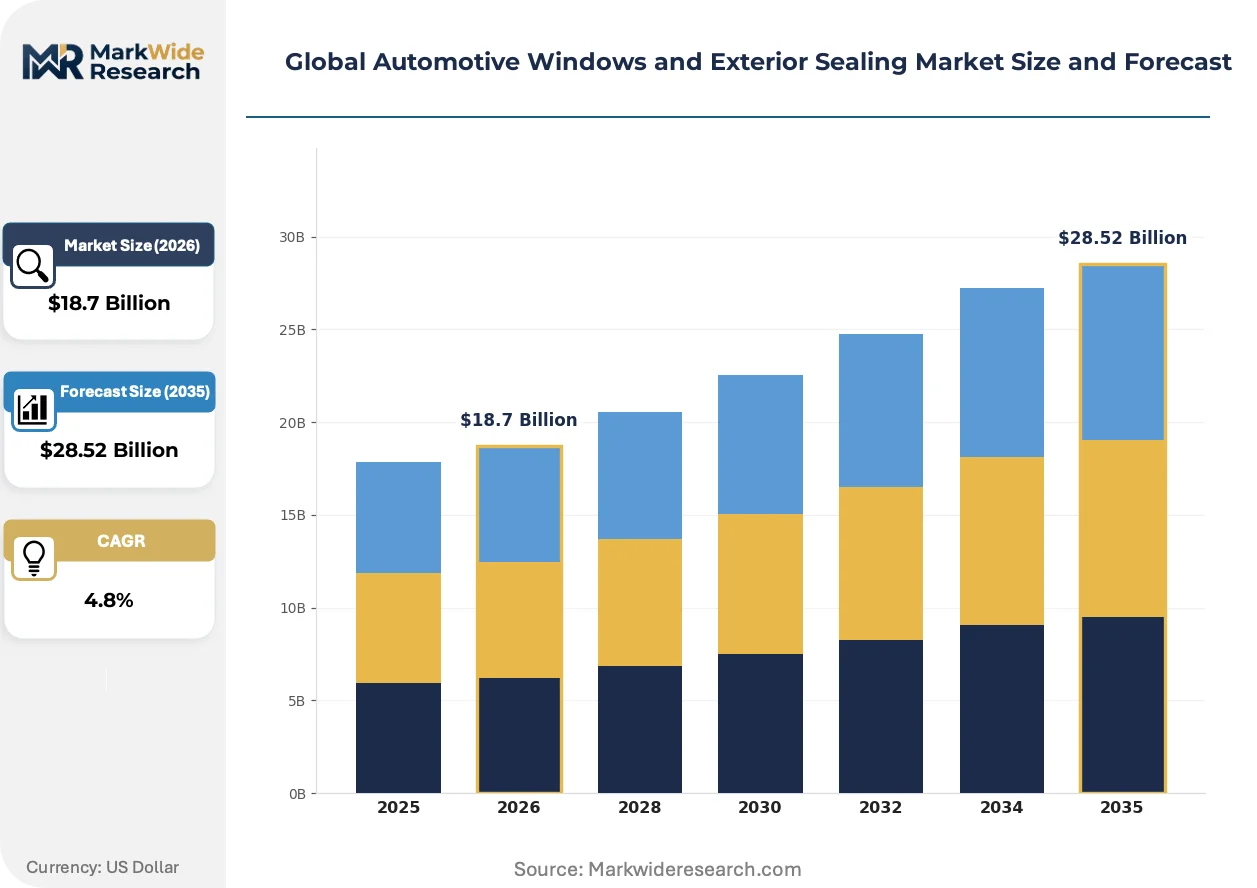
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Seals, Weatherstrips, Edge Molding, Body Seals, Trim Seals, Windshield Seals Technology: EPDM Rubber, Silicone, Thermoplastic Elastomers, Polyurethane Foam, Butyl Rubber, Neoprene Application: Passenger Cars, Commercial Vehicles, Specialty Vehicles, Off-Highway Equipment, Recreational Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Component Manufacturers |
| Companies Covered | Hutchinson Sealing Systems, Cooper Standard Automotive Inc., Magna International Inc., Rehau Group, Toyoda Gosei Co., Ltd., Minth Group Ltd, Sumitomo Riko Company Limited, ElringKlinger AG, Henniges Automotive North America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Windows and Exterior Sealing Market Strategic Shifts & Innovations
The market's evolution is defined by a dual focus on material science advancements for performance and sustainability. This pressure compels suppliers to innovate beyond traditional rubber formulations to meet the specific demands of next-generation vehicle platforms.
Thermoplastic elastomers (TPEs) provide superior recyclability and design flexibility compared to traditional materials. Automotive OEMs are rapidly adopting TPEs to achieve lightweighting objectives and meet circular economy goals, especially within electric vehicle body and glass run applications. This material shift is displacing conventional EPDM rubber in many non-dynamic sealing components where processing efficiency and sustainability are paramount.
China's GB standards for vehicle interior air quality (VIAQ) enforce strict limits on the emission of volatile organic compounds (VOCs) from interior components. This regulation directly impacts material selection for all cabin-facing seals, including door and window weatherstrips. Consequently, suppliers targeting the Chinese market must invest in low-VOC material formulations and processing techniques to ensure compliance.
A procurement model shift towards modular sourcing is altering supplier relationships. Automakers increasingly prefer to purchase complete, integrated sealing systems from a single Tier-1 partner rather than individual components from multiple vendors. This trend is most visible with European and North American OEMs, who use it to simplify assembly and delegate system-level engineering responsibility.
Global Automotive Windows and Exterior Sealing Market Segmentation
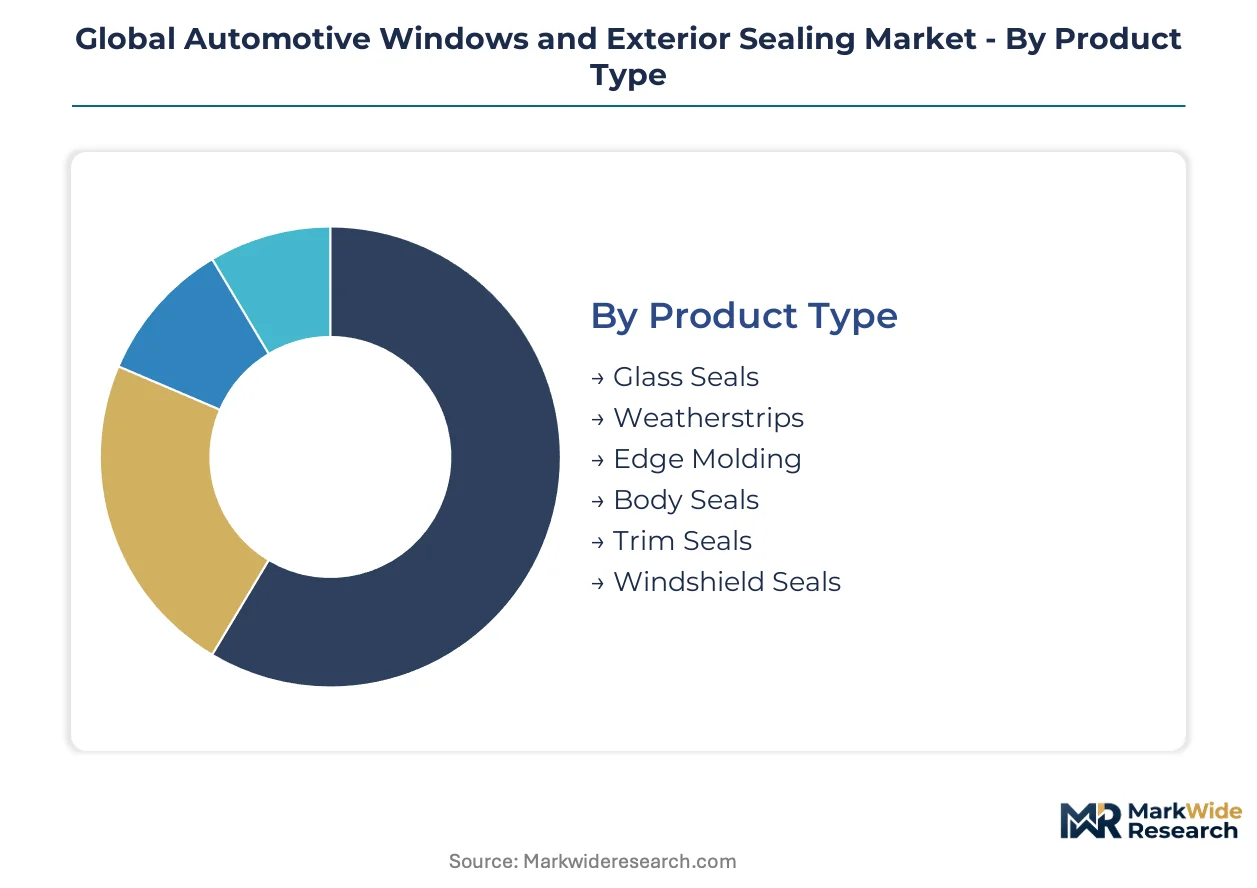
Market segmentation provides a structured view of the diverse requirements and technological approaches driving the automotive windows and exterior sealing industry. Understanding these distinct segments is crucial for suppliers to align their product development and market strategies with evolving OEM demands, particularly in the shift towards electric vehicles.
Product Type:
Regulatory standards for vehicle noise, such as the EU's pass-by noise mandates, and safety, including China's GB standards for material safety, directly influence the engineering and material specifications across different product types.
- Weatherstrips:These complex, multi-durometer profiles seal vehicle doors, windows, and trunks, preventing water, air, and noise intrusion. Demand for superior acoustic performance in weatherstrips is heightened by electric vehicle platforms requiring extremely quiet cabins.
- Body Seals:Designed to seal structural gaps and body panels, these components protect the vehicle's interior from environmental elements and contribute to overall body rigidity. Integration of sensors into body seals for advanced driver-assistance systems represents a significant value addition opportunity.
- Glass Seals:These seals secure fixed and movable glass components, including windshields and backlights, providing weather protection and contributing to vehicle aesthetics.
- Edge Molding:Decorative and protective trim elements, edge moldings are often used around vehicle windows and body lines to enhance appearance and offer minor sealing.
- Trim Seals:These components combine sealing and decorative functions, often found around door frames and interior panels, improving both cabin quietness and finish.
- Windshield Seals:Specifically engineered to bond and seal the windshield to the vehicle body, these seals are critical for structural integrity and occupant safety.
Established volume favors Weatherstrips; emerging adoption favors Body Seals.
Technology:
Material selection within sealing technology reflects a balance between cost, performance, and environmental compliance, influencing component design and manufacturing processes.
- Thermoplastic Elastomers:TPEs offer superior recyclability, design flexibility, and lightweighting benefits, making them highly attractive for OEMs focused on sustainability and efficiency. The material's co-extrusion capabilities support complex profile designs.
- EPDM Rubber:Ethylene Propylene Diene Monomer rubber remains a widely used material for automotive seals due to its excellent weather resistance, durability, and cost-effectiveness. EPDM is a staple for traditional sealing applications.
- Silicone:Known for its high-temperature resistance and flexibility, silicone is employed in niche sealing applications where extreme thermal conditions or specific chemical resistance are required.
- Polyurethane Foam:This material provides effective sealing against dust and noise, often used in gap fillers and acoustic baffles within vehicle structures.
- Butyl Rubber:Valued for its excellent impermeability to gases and moisture, butyl rubber finds application in specific sealing areas requiring high barrier properties.
- Neoprene:Offering good resistance to oils, chemicals, and weathering, neoprene is utilized in various automotive sealing components where these properties are critical.
Thermoplastic Elastomers are gaining share fastest due to sustainability goals and design flexibility.
Application:
The diverse application landscape for automotive sealing components dictates varying performance requirements and design considerations, from high-volume production to specialized niche markets.
- Passenger Cars:This segment represents the largest volume demand, driven by stringent requirements for cabin quietness, comfort, and advanced features in both internal combustion engine and electric vehicles. Demand for superior acoustic sealing systems is particularly high.
- Commercial Vehicles:Sealing solutions for commercial vehicles prioritize durability, resistance to harsh operating conditions, and robust performance over extended service lives. These applications often involve larger components.
- Specialty Vehicles:This category includes ambulances, police cars, and other customized vehicles, requiring seals tailored for specific equipment integration and operational demands.
- Off-Highway Equipment:Vehicles like construction machinery and agricultural equipment demand extremely robust seals capable of withstanding severe environmental exposure, dirt, and vibration.
- Recreational Vehicles:RVs and campers require effective sealing against weather and noise, with a focus on occupant comfort and longevity in various climates.
Passenger Car applications command significant market volume, while Off-Highway Equipment demands specialized sealing solutions.
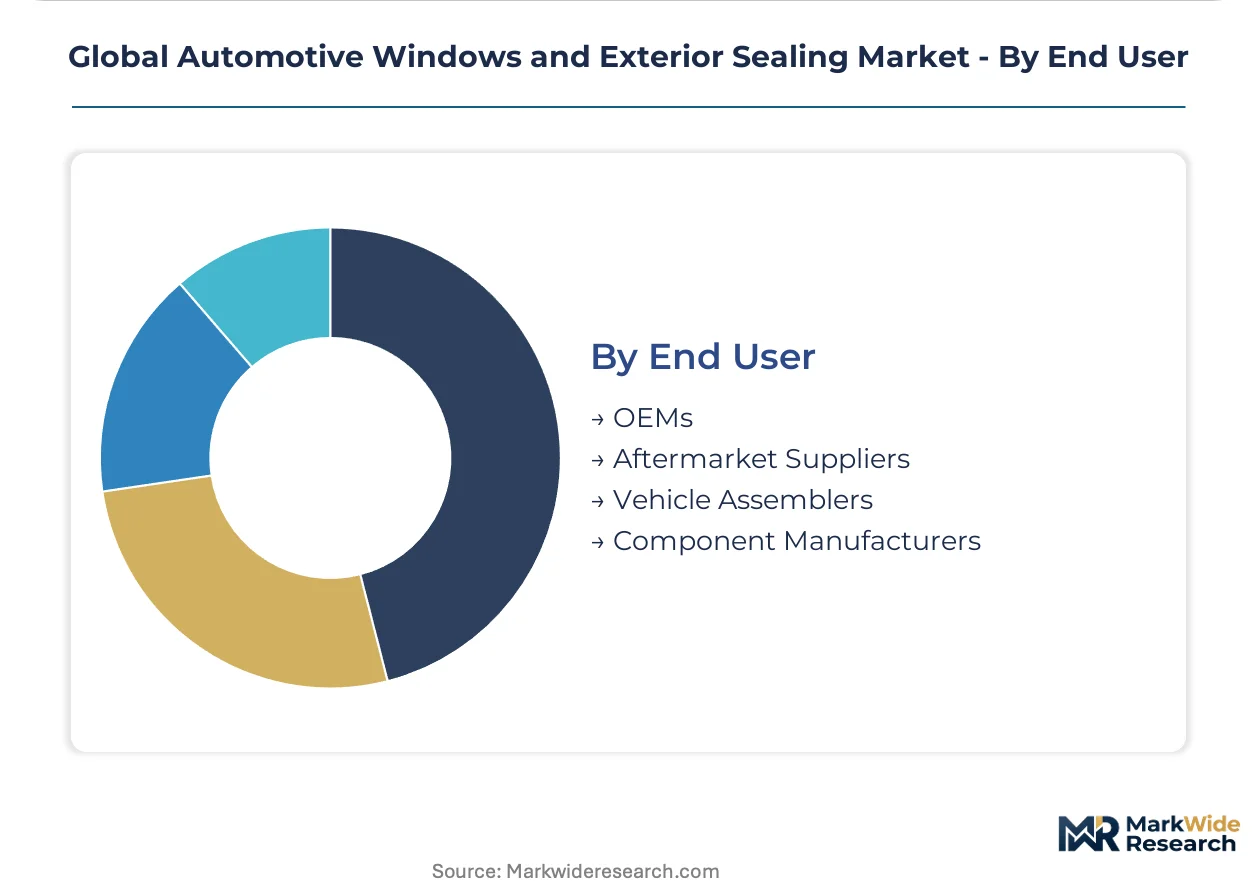
End User:
The distribution of sealing components varies across distinct end-user categories, each with unique procurement models and demand patterns.
- OEMs:Original Equipment Manufacturers represent the primary end-user segment, procuring sealing systems directly for integration into new vehicle production lines. Their requirements often involve complex, multi-functional components.
- Aftermarket Suppliers:These entities provide replacement sealing components for vehicle repair and maintenance, catering to the needs of older vehicles and accident repairs.
- Vehicle Assemblers:Companies that assemble vehicles from components sourced from various suppliers constitute this segment, focusing on efficient integration and system performance.
- Component Manufacturers:These firms produce individual sealing components that are then supplied to OEMs or other assemblers, often specializing in specific material or process technologies.
OEMs represent the primary channel for initial vehicle production, whereas Aftermarket Suppliers cater to vehicle maintenance and repair cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEMs represent the primary channel for initial vehicle production, driving significant demand for automotive windows and exterior sealing systems across key manufacturing hubs. The global transition to electric vehicles intensifies requirements for superior acoustic and thermal management, influencing material specifications worldwide. Regulatory frameworks, including noise standards and material safety directives, further shape regional market dynamics and supplier strategies.
China
China's immense scale of passenger car and EV manufacturing creates a massive, concentrated source of volume demand for all types of weatherstrips and body seals. The country's GB standards for vehicle interior air quality enforce strict limits on VOC emissions, directly impacting material selection for cabin-facing seals. Major automotive production clusters in the Yangtze River Delta and Pearl River Delta drive significant procurement for sealing components.
Germany
Demand for advanced sealing systems in Germany stems from its robust premium automotive manufacturing sector and stringent environmental regulations. EU noise regulations, such as pass-by noise mandates, compel German automakers to invest in superior acoustic sealing solutions. The Baden-Württemberg region, home to major car manufacturers, acts as a focal point for high-performance sealing component development.
United States
The United States market for automotive sealing components is driven by the large volume of passenger car production and the accelerating shift to electric vehicles. US EPA vehicle emissions standards influence material choices for lightweighting and sustainability. Automotive manufacturing centers in Michigan and the Southeast, including states like Tennessee and South Carolina, require extensive sealing solutions for new vehicle platforms.
Japan
Japan's mature automotive industry consistently demands high-quality sealing solutions for both domestic and export markets. JIS standards for material performance and durability guide product development for Japanese OEMs. The Chubu region, particularly around Nagoya, hosts a dense concentration of automotive manufacturers and their supply chains, creating steady demand for advanced seals.
Mexico
Mexico is emerging as a significant manufacturing hub for the automotive industry, attracting new EV assembly plants and expanding traditional production. The country's favorable trade agreements and competitive labor costs drive demand for sealing components from North American OEMs. Automotive clusters in states like Nuevo León and Guanajuato are seeing increased investment in component manufacturing capabilities.
Global Automotive Windows and Exterior Sealing Market Key Industry Players
Player mix skews toward large, established Tier-1 suppliers with extensive global footprints and specialized manufacturing capabilities. The market demonstrates a tiered structure, separating certified component manufacturers from smaller, non-compliant entities. Strategic archetypes include integrated system providers, material science innovators, and regional specialists. Companies often pursue global manufacturing footprint expansion and material science innovation as dominant competitive moves.
Hutchinson Sealing Systems, a global entity, exemplifies a Tier-1 supplier leveraging its extensive manufacturing footprint to meet OEM requirements across diverse regions. Cooper Standard Automotive Inc., a US-based corporation, positions itself through material science innovation, particularly in advanced elastomers for electric vehicle applications. Magna International Inc., a Canadian-based company, anchors the integrated systems provider archetype, offering sealing solutions within a broader portfolio for global automakers.
| Leading Market Players |
|---|
| Hutchinson Sealing Systems |
| Cooper Standard Automotive Inc. |
| Magna International Inc. |
| Rehau Group |
| Toyoda Gosei Co., Ltd. |
| Minth Group Ltd |
| Sumitomo Riko Company Limited |
| ElringKlinger AG |
| Henniges Automotive North America, Inc. |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for critical rubber feedstocks directly influence pricing power, reflecting the concentrated nature of specialized co-extrusion technology and raw material sourcing. This dynamic creates a direct linkage between supply chain resilience and component cost stability for OEMs.
Pricing Analysis
Cost-plus contracts, often indexed to key raw material prices like EPDM rubber or specific TPE polymers, dominate long-term supply agreements between Tier-1 suppliers and OEMs. Price differentiation stems from IATF 16949 certification levels and the complexity of integrated sensor components. Pricing pressure intensifies due to raw material volatility, particularly for synthetic rubber feedstocks. OEMs procuring standard weatherstrips exhibit higher price sensitivity compared to those requiring advanced acoustic or integrated sensor seals for electric vehicles.
Supply Chain Analysis
Port congestion and container availability challenges impact inbound logistics costs for raw materials sourced globally, affecting seal manufacturers. The supply chain for automotive sealing components draws heavily from manufacturing hubs in China, Germany, and Mexico. Key raw material dependencies include EPDM rubber and various thermoplastic elastomers. Manufacturing concentration of specialized co-extrusion technology among a few large suppliers presents a structural single-source vulnerability risk. Distribution primarily runs directly to Original Equipment Manufacturers for new vehicle production, supplemented by aftermarket channels for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Automotive Windows and Exterior Sealing Market presents a high-growth disruption, driven by the electric vehicle transition and its heightened demands for acoustic performance and lightweighting materials like TPEs.
For Market Incumbents: Shield existing market share by investing heavily in material science R&D, particularly for advanced thermoplastic elastomers and bio-based polymers. Mitigate acoustic software substitution threats through superior physical seal engineering and integrated sensor development. Reinforce IATF 16949 certification and expand global manufacturing capabilities in emerging EV production centers to meet OEM requirements. Focus on operational excellence to counter raw material volatility.
For New Entrants and Emerging Players: Lead with specialized material solutions, such as low-VOC formulations for the Chinese market or high-recycled content TPEs for European OEMs. Target white-space opportunities in sensor integration into body seals for advanced driver-assistance systems. Focus on emerging EV hubs in Southeast Asia and Mexico as penetrable geographies for new assembly plant demand. Develop agile co-extrusion capabilities to meet customized component needs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core automotive sealing divisions, offering specialized material or process expertise. The market's long-term viability hinges on the sustained global transition to electric vehicles and stringent environmental regulations. Acquisition targets should include innovators in thermoplastic elastomers or firms with advanced multi-material co-extrusion capabilities. Watch for accelerating OEM adoption rates of integrated sealing systems as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Bio-based TPEs | Aligns with OEM ESG goals and EU REACH directives for sustainable materials. |
| Global Manufacturing Expansion | Captures demand from new EV assembly plants in Mexico and Southeast Asia. |
| Sensor Integration Partnerships | Creates higher-value components for advanced driver-assistance systems. |
| IATF 16949 Certification Investment | Reinforces market position against non-compliant entities in competitive bids. |
| Automated Co-extrusion Line Upgrades | Meets demand for complex, multi-durometer seals required by EV platforms. |
Research Approach
Findings reconcile primary fieldwork against secondary review of vehicle production databases, regulatory filings, and industry association reports. Primary interviews involved OEM procurement managers, Tier-1 R&D leads, material science engineers, and aftermarket distributors. This approach provided a comprehensive understanding of market dynamics and allowed for bottom-up and top-down triangulation of data points.
The market segmentation modeled dimensions across product type, technology, application, end-user, and regional production clusters. The analytical framework projected market growth over the projection horizon, deriving compound annual growth rates from historical trends and future outlooks. Key industry-specific forecast inputs included electric vehicle adoption rates and raw material price forecasts.
The analysis sits within stated boundaries; outcomes outside sustained macroeconomic stability or regulatory continuity would require recalibration. Forecasts reflect assumptions regarding technological advancements and geopolitical stability. Unforeseen technological disruption, such as widespread active noise cancellation, or significant shifts in global trade policies represent potential risk factors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Solar Film Market