
 Automotive Door Seal Market | 2026-2036
Automotive Door Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Seal Market Analysis
OEM buyer consolidation among premium electric vehicle platforms is recalibrating volume allocation across the supply base. Sumitomo Riko leverages its polymer compounding expertise to sustain long-term contracts with Japanese automakers. Cooper Standard anchors North American supply through integrated extrusion and coating capabilities. Nishikawa Rubber differentiates via precision-molded profiles for acoustic performance in luxury cabins.
Automotive door seals are elastomeric compression profiles, typically extruded from EPDM or TPE compounds with specific Shore A hardness ratings between 50 and 80, designed to block water ingress, wind noise, and dust while maintaining closure force consistency across temperature cycles from minus 40 to 120 degrees Celsius. EPDM retains dominant share in thermal and UV-resistant applications, while TPE gains ground in recyclable lightweight designs demanded by electric vehicle platforms. Passenger vehicles generate the largest volume pool, though electric vehicles represent the fastest-expanding application segment as sealed cabin architectures become critical for aerodynamic efficiency and battery thermal management.
FDA material safety guidelines, EPA volatile organic compound emission limits, and REACH substance restrictions collectively elevate formulation complexity and testing burdens for compound suppliers. China's GB standards and MIIT vehicle certification requirements add parallel compliance layers for market access. Stakeholders must monitor regulatory divergence between jurisdictions as it directly determines which compound platforms qualify for multi-regional vehicle programs.
Market Dynamics
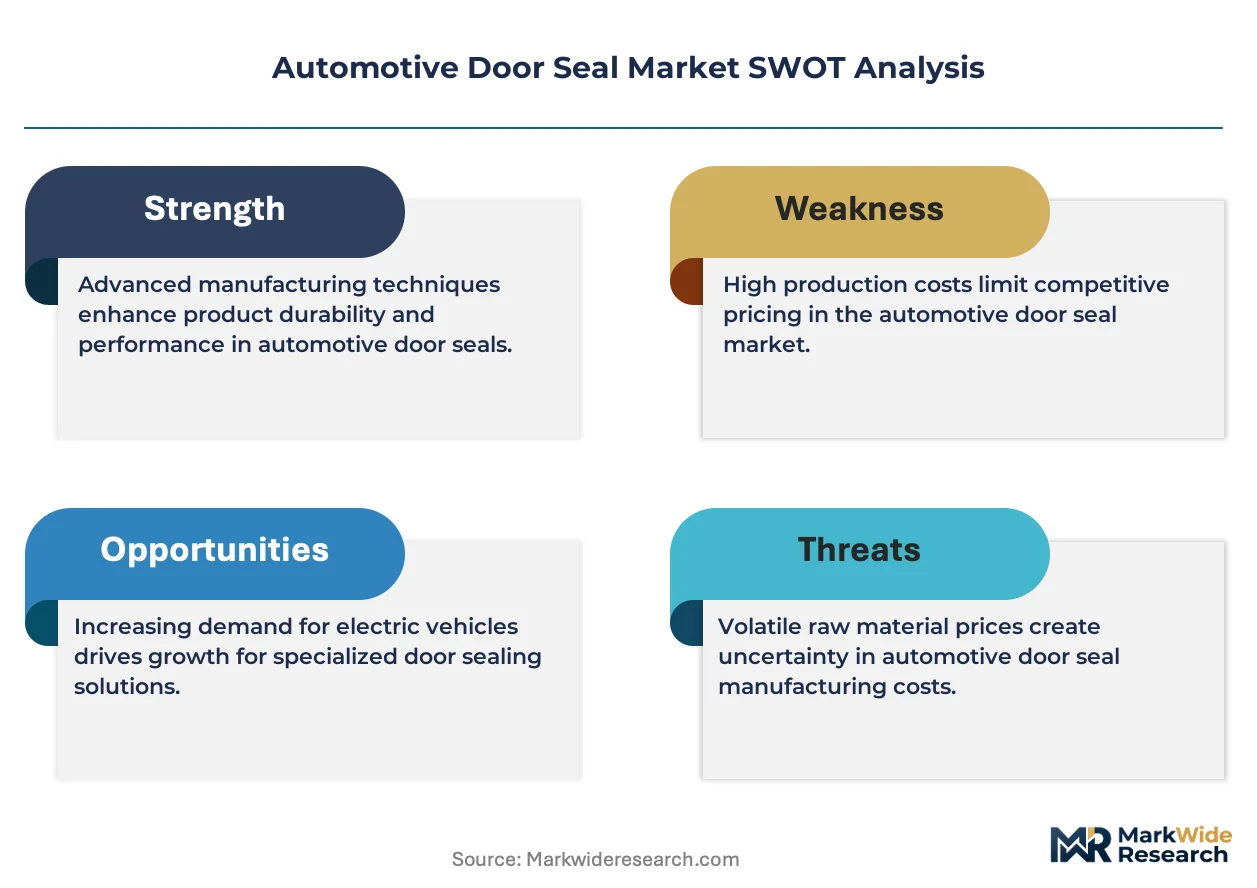
EPDM-to-TPE material transitions are compressing incumbent compound margins while forcing extrusion equipment upgrades across the supply base. Electric vehicle OEMs now specify recyclable sealing architectures that legacy EPDM formulations cannot satisfy without substantial reformulation investment.
Growth Catalysts
- REACH Substance Restrictions:ECHA's expanding SVHC candidate list is accelerating TPE adoption as OEMs pre-empt compliance risks in European vehicle programs.
- Electric Vehicle Thermal Management:Battery pack sealing requirements are expanding addressable seal length per vehicle by 40% versus internal combustion architectures.
- Germany:KBA certification protocols for acoustic performance are elevating specification thresholds that premium German OEMs export globally.
Market Restraints
- EPDM Feedstock Concentration:Ethylene-propylene monomer supply concentrates in Gulf Coast petrochemical complexes, exposing compounders to hurricane-related production interruptions.
- REACH Testing Burden:Substance of Very High Concern notification requirements add 18-24 month validation timelines for new compound introductions.
- TPE Shore A Limitations:Thermoplastic elastomers currently fail to match EPDM's compression set resistance below minus 30 degrees Celsius, restricting cold-climate applications.
Strategic Opportunities
- China MIIT Dual Carbon Goals:Domestic NEV mandates are creating captive demand for lightweight recyclable sealing systems in Changshu and Ningbo manufacturing clusters.
- Overmolding Convergence:Integration of sealing profiles with structural carrier plastics enables part-count reduction and assembly automation.
- Aftermarket Channel Digitization:B2B platform procurement of certified replacement seals is disintermediating traditional distributor networks in North America.
Industry Challenges
- Compound Formulation Expertise Gap:TPE compounding for automotive durability specifications requires polymer scientists with 10+ year development cycles, creating talent scarcity.
- Multi-Jurisdiction Certification Parallelism:Simultaneous EPA VOC, REACH SVHC, and China GB testing extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Seal Market |
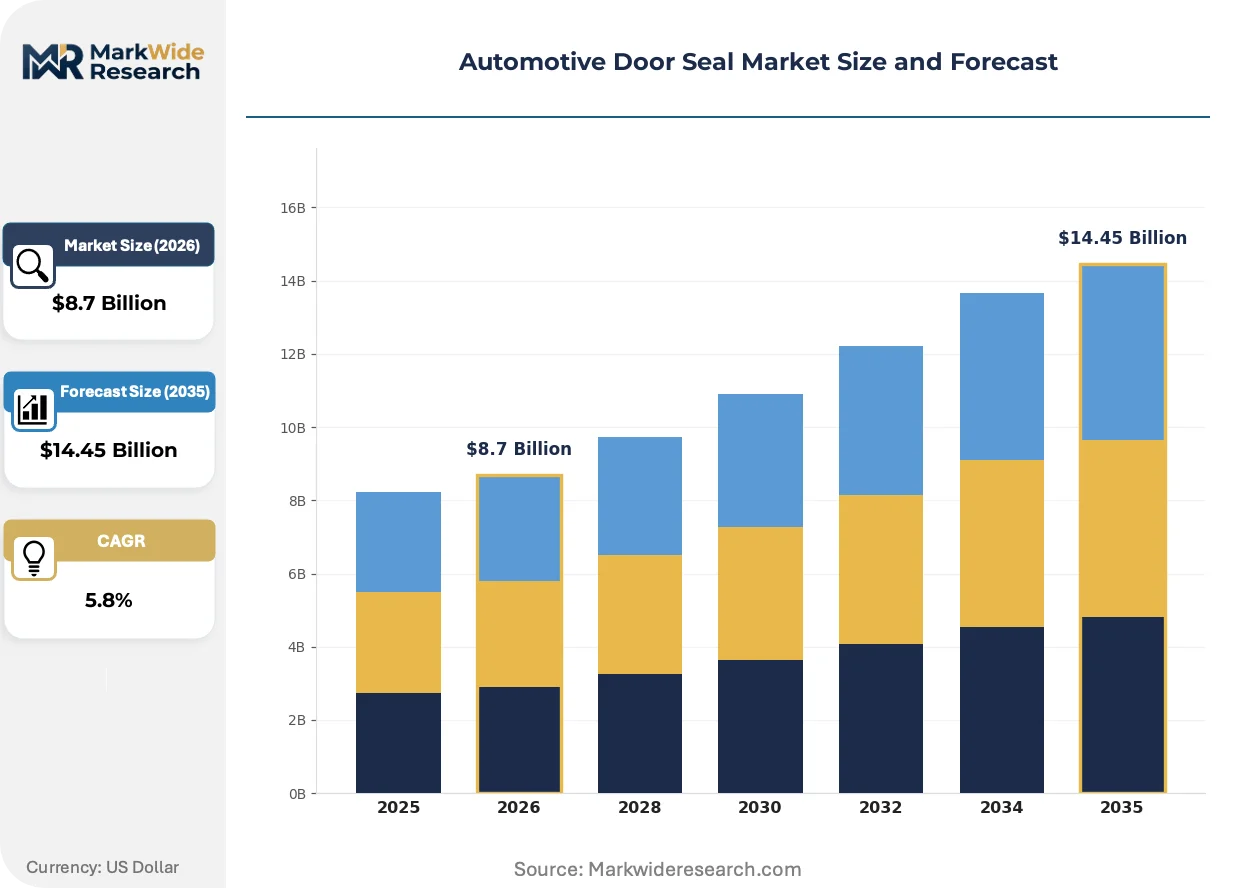
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, TPE, PVC, Silicone Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Installation Type: OEM, Aftermarket, Retrofit, Custom Connection Method: Adhesive, Mechanical Fasteners, Snap-fit, Interlocking |
| Companies Covered | Sumitomo Riko, Henniges Automotive, Cooper Standard, Nishikawa Rubber, Trelleborg AB, Toyoda Gosei, Magna International, Toyoda Rubber, Hutchinson SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Seal Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry constraints are converging to reshape competitive differentiation in automotive sealing. The transition from thermoset to thermoplastic architectures is redistributing value across compounders, toolmakers, and tier suppliers.
Co-extruded TPE-PP carrier systems are decentralizing the traditional metal-reinforced EPDM architecture by embedding structural rigidity directly into the thermoplastic matrix. Volkswagen Group and Hyundai-Kia platforms are specifying these designs for 2027 model year electric vehicles. This material integration is decentralizing the metal stamping and adhesive bonding steps that previously anchored seal assembly in supplier parks.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing reformulation of carbon black-reinforced EPDM compounds used in 60% of current passenger vehicle seals. Compounders must qualify alternative reinforcing fillers without sacrificing UV resistance or compression set performance. German OEM supply chains are responding fastest, with KBA-type-approved compounds now required for all vehicles sold in EU member states.
Consolidated electric vehicle platform procurement is compressing supplier qualification cycles from 36 months to 18 months as OEMs synchronize global seal specifications across multiple assembly plants. Tier 1 suppliers are responding by pre-positioning compound libraries and extrusion dies before platform awards. This behavioral shift is most visible in China, where MIIT NEV certification timelines leave minimal margin for iterative design validation.
Automotive Door Seal Market Segmentation
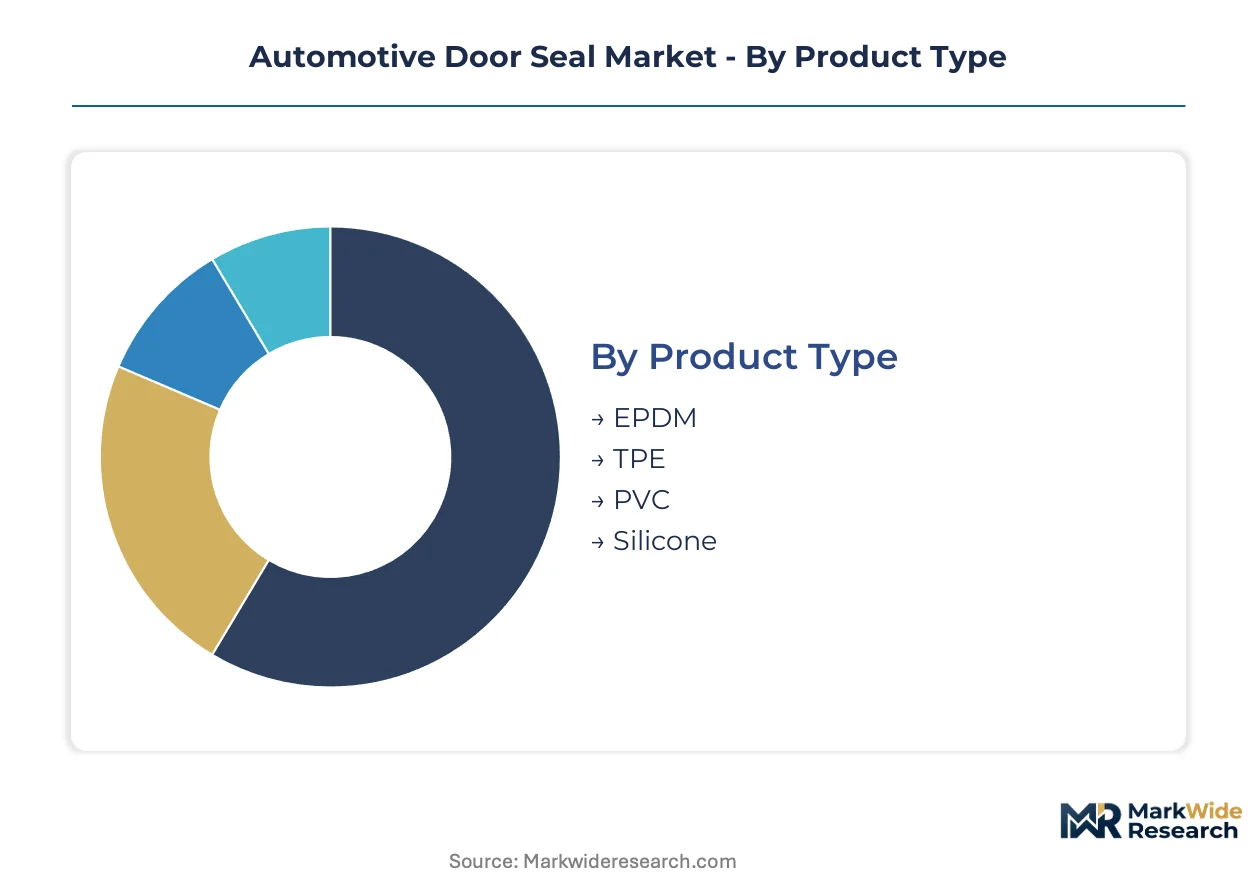
Automotive door seal procurement varies sharply by vehicle architecture and regulatory exposure. Material selection, installation channel, and connection geometry each impose distinct qualification burdens on compounders and extrusion houses.
Product Type:
Compound hardness and thermal envelope dominate OEM specification decisions.
- EPDM:Ethylene-propylene-diene monomer compounds deliver Shore A ratings from 50 to 80 with compression set resistance below minus 40 degrees Celsius. German OEMs anchor global demand through KBA-certified acoustic specifications that EPDM satisfies reliably.
- TPE:Thermoplastic elastomers enable closed-loop recycling for electric vehicle platforms. Changshu and Ningbo manufacturing clusters in China are absorbing TPE capacity fastest under MIIT dual carbon compliance mandates.
- PVC:Cost-positioned for economy vehicle segments with limited thermal cycling demands.
- Silicone:Extreme temperature stability for battery thermal management interfaces in premium electric architectures.
EPDM leads on scale; TPE leads on momentum.
Application:
Vehicle electrification intensity determines seal length and performance tier per unit.
- Passenger Vehicles:Volume anchor segment with standardized EPDM profiles across mass-market platforms. United States and Chinese assembly plants generate the largest procurement pools.
- Electric Vehicles:Battery pack sealing expands addressable seal length per vehicle substantially versus internal combustion architectures. Volkswagen Group and Hyundai-Kia platforms are specifying co-extruded TPE-PP carrier systems for upcoming model years.
- Commercial Vehicles:Heavy-duty thermal and UV exposure requirements favor reinforced EPDM formulations.
- Luxury Vehicles:Precision-molded acoustic profiles command premium positioning through German and Japanese OEM supply chains.
Passenger vehicles anchor volume; electric vehicles are climbing the fastest.
Installation Type:
Channel selection dictates margin structure and certification parallelism.
- OEM:Direct platform supply with 18-36 month qualification cycles. Tier 1 suppliers pre-position compound libraries before award decisions.
- Aftermarket:B2B platform procurement is disintermediating traditional distributor networks in North America. Digitized certification tracking enables faster replacement seal sourcing.
- Retrofit:Niche demand from vehicle life extension programs in regulated emissions markets.
- Custom:Low-volume specialty applications with extended design validation timelines.
OEM captures the margin; aftermarket is gaining share fastest.
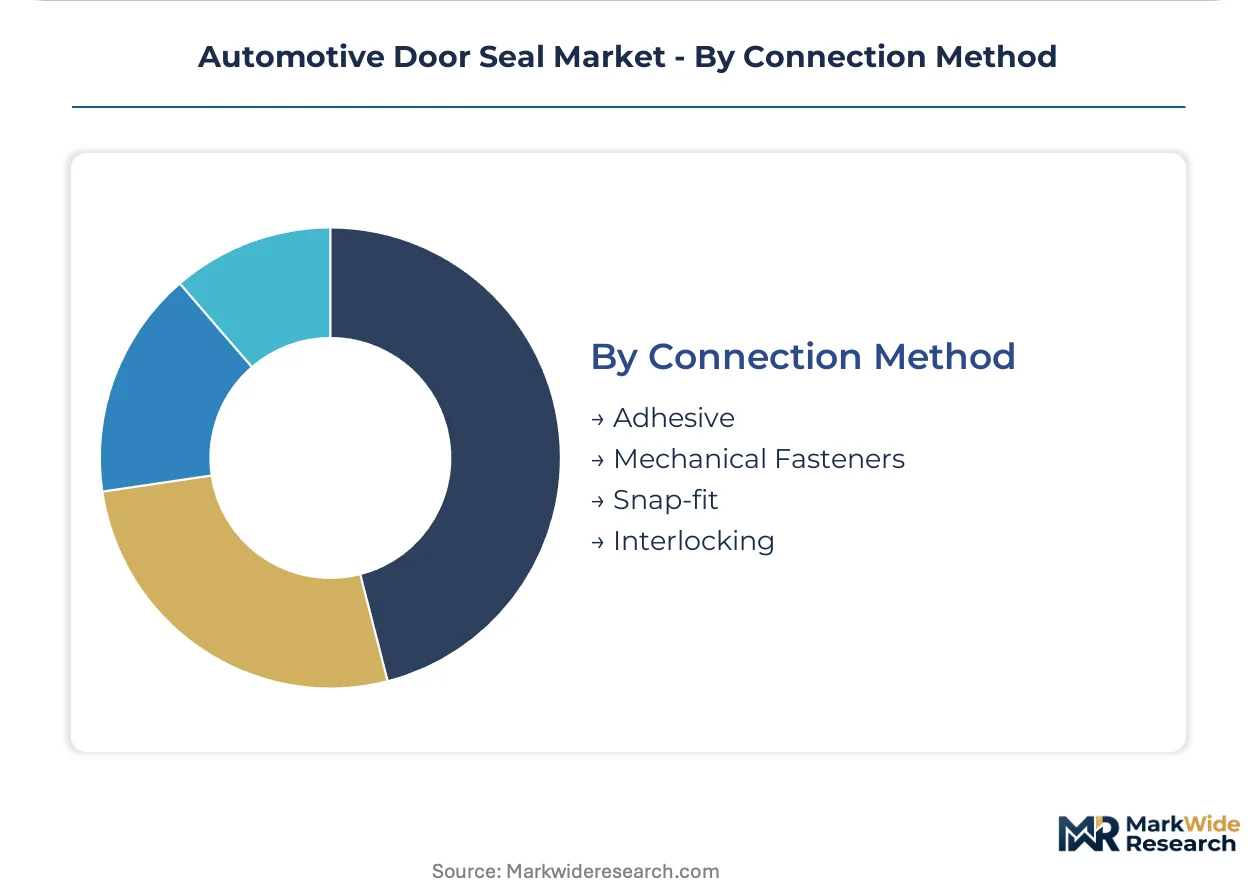
Connection Method:
Assembly automation compatibility now filters supplier selection at platform award stage.
- Adhesive:Traditional bonding with metal carriers requires surface preparation and curing stations that constrain line speed.
- Mechanical Fasteners:Removable serviceability for commercial vehicle maintenance intervals.
- Snap-fit:Tool-less installation enabling full automation in high-volume electric vehicle assembly plants.
- Interlocking:Modular profile systems for multi-variant platform flexibility.
Adhesive retains installed base; snap-fit shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA certification protocols command premium specification thresholds that Chinese MIIT dual carbon mandates are now matching in stringency, while United States EPA volatile organic compound limits create a third regulatory gravity center for seal compounders.
Germany
Premium OEM platform procurement and acoustic performance specifications drive seal demand. KBA certification protocols require type-approved compounds for all vehicles sold in EU member states. Stuttgart and Wolfsburg manufacturing clusters anchor capacity expansion for next-generation sealing systems.
China
Domestic NEV mandates and battery thermal management requirements expand seal length per vehicle substantially. MIIT dual carbon goals enforce lightweight recyclable sealing compliance. Changshu and Ningbo manufacturing clusters absorb TPE capacity fastest under these mandates.
United States
Integrated extrusion and coating capabilities anchor North American supply for electric vehicle platforms. EPA volatile organic compound emission limits elevate formulation complexity for compound suppliers. Detroit and Southeast automotive corridors concentrate OEM procurement decisions.
Japan
Polymer compounding expertise sustains long-term contracts with domestic automakers transitioning to electric architectures. METI industrial policy supports material science advancement in automotive applications. Toyota City and Yokohama production bases maintain precision-molded profile capabilities.
South Korea
Hyundai-Kia platform specifications for co-extruded TPE-PP carrier systems drive material transition demand. MFDS chemical safety oversight parallels REACH substance restrictions in scope. Ulsan and Asan manufacturing complexes scale seal production for 2027 model year electric vehicles.
Automotive Door Seal Market Vendor Landscape
Japanese producers anchor one tier; North American and European specialists hold integrated extrusion capabilities in another. The supply base organizes around compound formulation expertise, precision-molding capabilities, and platform-level procurement relationships. Three archetypes dominate: polymer compounders with captive R&D, integrated Tier 1 suppliers with extrusion-coating assets, and precision acoustic specialists serving luxury cabins. Competitive moves concentrate on pre-positioning compound libraries before platform awards and upgrading extrusion equipment for TPE compatibility.
Within the integrated Tier 1 tier, Cooper Standard and Magna International occupy positions defined by extrusion and coating capabilities. Among precision acoustic specialists, Nishikawa Rubber exemplifies the mold-to-cabin-performance archetype. Sumitomo Riko anchors the polymer compounding tier with sustained OEM relationships. These three represent distinct capability vectors that procurement teams evaluate during 18-month qualification cycles.
| Leading Market Players |
|---|
| Sumitomo Riko |
| Henniges Automotive |
| Cooper Standard |
| Nishikawa Rubber |
| Trelleborg AB |
| Toyoda Gosei |
| Magna International |
| Toyoda Rubber |
| Hutchinson SA |
| Others |
Supply Flow & Price Mechanics
EPDM ethylene-propylene monomer feedstock originating from Gulf Coast petrochemical complexes flows through compounders to OEM procurement tiers, with hurricane exposure and REACH compliance costs layering risk premiums onto European-bound volumes. TPE compounders in Changshu and Ningbo manufacturing clusters capture margin from recyclable lightweight specifications demanded by MIIT dual carbon mandates, compressing legacy EPDM price floors in domestic Chinese programs.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for thermoplastic elastomer compounds, forcing incumbent EPDM suppliers to defend position through KBA-certified acoustic grade premiums. Three-tier pricing structure across premium acoustic-certified, standard OEM-grade, and economy aftermarket levels stratifies by certification burden and thermal envelope performance. Cost compression in mass-market passenger vehicle segments intensifies as Volkswagen Group and Hyundai-Kia platforms consolidate global seal specifications. Aftermarket distributors exhibit highest price sensitivity due to B2B platform disintermediation, while luxury German OEMs accept premium positioning for precision-molded cabin profiles.
Supply Chain Analysis
MIIT domestic-content requirements for NEV certification and KBA type-approval protocols are reshaping sourcing decisions toward regional compound libraries. Raw material supply concentrates in Germany, China, and the United States, with ethylene-propylene monomer, carbon black reinforcing fillers, and TPE polymer resins as critical inputs. Single-source vulnerability in Gulf Coast petrochemical corridors exposes compounders to weather-related production interruptions. Distribution runs through Tier 1 integrated extrusion houses to OEM platform engineering teams, with aftermarket digitization bypassing traditional distributor networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive door seal market represents a late-cycle quality story as electric vehicle thermal management requirements elevate specification thresholds toward premium acoustic and recyclable architectures. Battery pack sealing expansions and sealed cabin aerodynamic demands are shifting procurement toward performance-tier contracts.
For Market Incumbents: Deploy pre-positioned compound libraries to compress 18-month qualification cycles before platform awards finalize. Integrate co-extrusion capabilities for TPE-PP carrier systems to match Volkswagen Group and Hyundai-Kia specifications. Defend against REACH Annex XVII reformulation costs by anchoring KBA-certified EPDM grades in German OEM supply chains. Capture backward integration into polymer compounding to insulate margin from ethylene-propylene monomer volatility.
For New Entrants and Emerging Players: Capture aftermarket channel digitization in North America where B2B platform procurement disintermediates legacy distributor networks. Target TPE compounding for Changshu and Ningbo manufacturing clusters under MIIT dual carbon compliance timelines. Penetrate the electric vehicle battery pack sealing segment where addressable seal length per vehicle expands substantially versus internal combustion architectures. Establish direct certification relationships with OEM platform engineering teams rather than Tier 1 intermediation.
For Investors and Strategic Acquirers: Consolidation pressure builds where TPE formulation expertise scarcity intersects with accelerated OEM qualification timelines. Five-to-ten year viability favors compounders with captive R&D and extrusion-coating integration over pure-play extrusion houses. Acquire targets possessing KBA-type-approved compound libraries and MIIT NEV certification track records. Monitor ECHA SVHC candidate list expansion as inflection indicator for TPE adoption velocity versus EPDM replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-extruded TPE-PP Carrier System Deployment | Volkswagen Group and Hyundai-Kia platform specifications for 2027 model year electric vehicles mandate this architecture. |
| REACH Annex XVII Reformulation Investment | Polycyclic aromatic hydrocarbon restrictions force carbon black alternative qualification without UV resistance sacrifice. |
| Aftermarket Channel Digitization | B2B platform procurement in North America disintermediates traditional distributor networks for certified replacement seals. |
| MIIT Dual Carbon Compliance Positioning | Changshu and Ningbo manufacturing clusters absorb TPE capacity fastest under domestic NEV mandates. |
| KBA Acoustic Certification Anchoring | German OEM supply chains require type-approved compounds for all vehicles sold in EU member states. |
Methodological Framework
Multiple input streams — primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, and aftermarket distribution heads; secondary validation through vehicle production databases, IHS Markit registration data, customs trade records, and ECHA regulatory filings; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates. Conversations with compound R&D directors and extrusion equipment manufacturers informed TPE transition velocity assumptions.
Historical production volumes were cross-referenced against panel input from automotive sealing specialists to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, material compound type, OEM tier positioning, and regional regulatory cluster. CAGRs were derived from elasticity analysis against vehicle build forecasts and content-per-vehicle expansion for battery thermal management applications. Electric vehicle platform standardization timelines and REACH SVHC notification backlogs served as industry-specific forecast inputs.
Regulatory divergence between EPA VOC limits, REACH substance restrictions, and MIIT certification protocols, alongside raw material supply interruptions and electric vehicle adoption trajectory shifts, are the dominant revision risks to modeled outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market