
 Europe Automotive Interiors Market | 2026-2036
Europe Automotive Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Interiors Market Foresight
Recycled PET and bio-based polyurethane foam is consolidating share across European seating and panel applications, displacing conventional petroleum-derived substrates on cost and compliance grounds. FORVIA Faurecia leverages its integrated foam-to-seat architecture to capture margin from OEM sustainability mandates. Adient PLC anchors production scale across Central European plants serving German premium brands. Grammer AG specializes in commercial-vehicle seating systems where durability specifications exceed passenger-car benchmarks.
Europe automotive interiors encompass cockpit modules, passenger compartments, and cargo-area trim engineered to tactile, acoustic, and safety specifications including flame-retardancy ratings and head-impact compliance. Dashboard assemblies integrate structural carriers of glass-mat thermoplastic or steel stampings with soft-touch skin layers formed through injection molding or slush molding processes. Seat cover demand in leather and fabric materials leads value contribution, while 3D printing technology in prototype and low-volume trim tooling represents the fastest-growing fabrication category. Foam material formulations dominate volume consumption across headliner and seating applications where NVH performance and occupant comfort define specification thresholds.
REACH restrictions on phthalate plasticizers and the EU Green Deal carbon-border adjustments are reshaping material qualification protocols for interior suppliers. ECHA substance-of-very-high-concern listings force reformulation of vinyl compounds and flame-retardant additives used in door panels and dashboard skins. Stakeholders must monitor pending CSRD disclosure requirements that will expose Scope 3 emissions from leather tanning and synthetic fiber supply chains to investor scrutiny.
Market Dynamics
REACH substance-of-very-high-concern listings and EU Green Deal carbon-border adjustments are forcing simultaneous reformulation of vinyl compounds, flame-retardant additives, and foam substrates across European interior supply chains.
Growth Catalysts
- EU Green Deal carbon-border mechanisms:The CBAM framework penalizes embedded emissions in imported synthetic leather and petroleum-based polymers, accelerating supplier qualification of bio-based alternatives.
- Premium electric vehicle cabin specifications:German OEMs mandate sustainable material content thresholds in seating and dashboard applications, pulling bio-polyurethane and recycled PET into standard configurations.
- Stuttgart-Munich supplier cluster density:Concentrated R&D infrastructure around FORVIA Faurecia and Adient PLC technical centers enables rapid prototype-to-production scaling for sustainability-compliant interiors.
Market Restraints
- Bio-based polyurethane feedstock volatility:Castor oil and soybean polyol prices fluctuate with agricultural commodity cycles, compressing margin predictability for foam suppliers against stable petroleum-based benchmarks.
- ECHA SVHC compliance timeline compression:Accelerated substance restriction schedules force premature tooling retirement and material requalification costs ahead of amortization schedules.
- Leather tanning supply concentration:Italian and Spanish tanneries dominate premium hide processing, creating bottleneck risk for OEMs targeting Scope 3 emission disclosures under CSRD rules.
Strategic Opportunities
- Central European commercial vehicle seating:Grammer AG's durability specifications for truck and bus applications remain underpenetrated by bio-based foam competitors, opening margin capture for compliant suppliers.
- CSRD-driven Scope 3 transparency mandates:The directive forces leather tanning and synthetic fiber supply chains into emissions disclosure, advantaging early-certified suppliers with documented low-carbon pathways.
- 3D printing convergence with slush molding:Additive manufacturing of prototype tooling compresses design iteration cycles for soft-touch dashboard skins, reducing time-to-qualification for sustainable material variants.
Industry Challenges
- Cross-functional sustainability talent scarcity:Shortage of chemists and materials engineers fluent in both REACH compliance protocols and automotive NVH specifications delays reformulation programs.
- Legacy vinyl tooling stranded asset risk:Existing slush molds and injection systems optimized for phthalate-plasticized compounds face accelerated obsolescence before depreciation completion.
- Multi-tier supply chain reconfiguration friction:Tier 2 foam compounders and Tier 3 chemical suppliers require simultaneous certification to new bio-based formulations, extending qualification timelines.
Report Scope
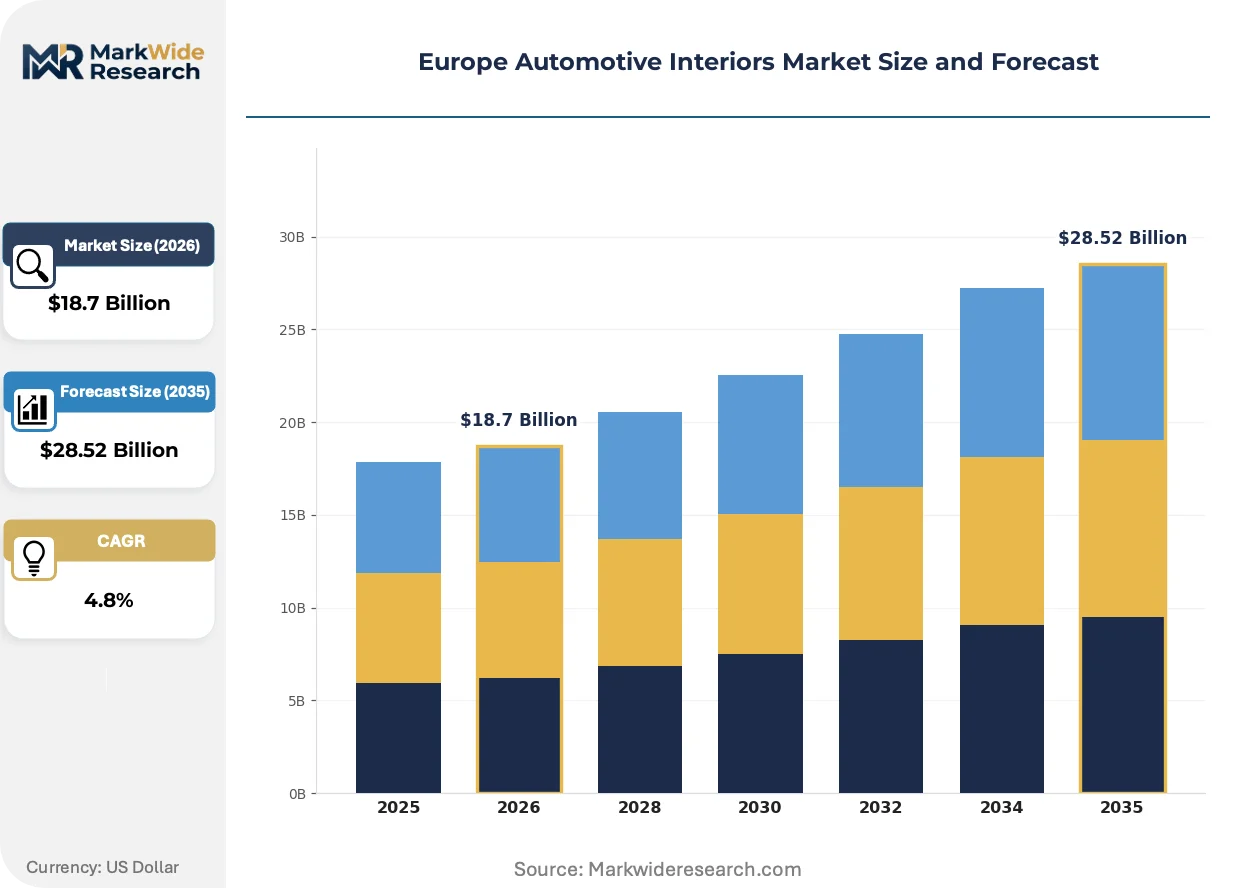
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Interiors Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Door Panel, Seat Cover, Headliner Material: Leather, Fabric, Vinyl, Foam End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Custom Builders Technology: Injection Molding, Sewn Upholstery, 3D Printing, Lamination |
| Companies Covered | Grupo Antolin, PRETTL Lighting & Interior GmbH, FORVIA Faurecia, SKA Sitze GmbH, Groclin S.A, Adient PLC, Grammer AG, EFI Automotive Group, Recaro Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Interiors Market Shifts & Advancements
Material science convergence with digital manufacturing is compressing development cycles for compliant interior systems, while regulatory disclosure mandates restructure supplier-buyer information flows.
Glass-mat thermoplastic composites are unifying structural carrier functions with acoustic damping properties in dashboard assemblies, eliminating separate NVH treatment layers. German premium OEMs specify these substrates for head-impact compliance without added mass. The technology is unifying previously separate engineering disciplines—structural, acoustic, and safety—into single-material solutions that reduce part count and assembly complexity.
REACH Annex XVII restrictions on phthalate plasticizers and short-chain chlorinated paraffins are eliminating legacy vinyl formulation pathways for door panels and seat trim. Compounders must qualify citrate or adipate ester alternatives with equivalent low-temperature flexibility and fogging performance. Italian and Spanish tanneries face parallel pressure from ECHA chromium VI limits, forcing wet-blue process modifications ahead of 2025 enforcement milestones.
Fleet sustainability scorecards are concentrating procurement authority within OEM central purchasing functions, displacing decentralized model-line sourcing. Tier 1 suppliers now face consolidated negotiation positions on bio-based content minimums and Scope 3 documentation. This pattern is most pronounced in Germany, where Volkswagen Group and Mercedes-Benz AG have established dedicated sustainable materials procurement desks with veto authority over conventional specifications.
Europe Automotive Interiors Market Segmentation
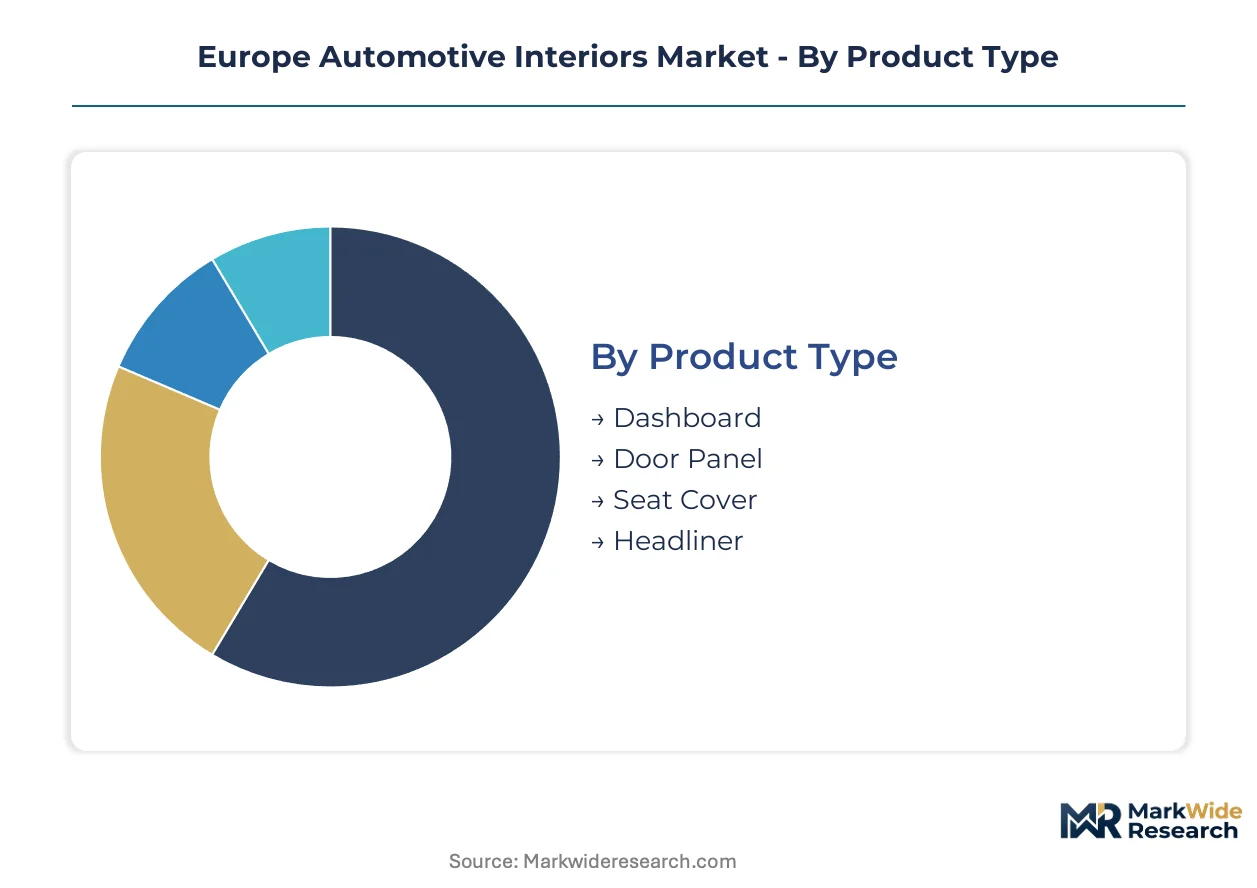
European automotive interiors segmentation reveals how sustainability mandates and manufacturing complexity reshape procurement priorities across distinct buyer profiles. Material specification thresholds now diverge sharply between premium OEM programs and cost-optimized aftermarket channels.
Product Type:
Premium German OEMs differentiate dashboard and seating investments from commodity trim based on occupant contact frequency and brand visibility.
- Dashboard:Glass-mat thermoplastic carriers integrate structural, acoustic, and head-impact functions into single-material solutions. Stuttgart and Munich technical centers specify these substrates for Mercedes-Benz and BMW electric vehicle architectures, eliminating separate NVH treatment layers while meeting EU safety directives.
- Seat Cover:Leather and fabric materials command the largest value share across European seating applications. Italian tanneries and German textile suppliers face consolidated procurement authority from Volkswagen Group and Mercedes-Benz AG sustainable materials desks, which now enforce bio-based content minimums with veto power over conventional specifications.
- Door Panel:Vinyl skin layers over structural carriers dominate volume production. REACH Annex XVII phthalate restrictions force compounders toward citrate or adipate ester alternatives with equivalent low-temperature flexibility.
- Headliner:Foam-backed fabric laminates provide acoustic damping and overhead trim finish. NVH performance specifications from FORVIA Faurecia and Adient PLC technical centers drive polyurethane foam formulation selection.
Volume sits with Seat Cover; growth tilts toward Dashboard as structural integration advances.
Material:
Feedstock origin—petroleum versus agricultural—now determines qualification status under EU Green Deal carbon-border mechanisms.
- Leather:Italian and Spanish tanneries process premium hides for German OEM cabins. ECHA chromium VI limits force wet-blue process modifications ahead of enforcement milestones, concentrating supply risk for Scope 3 disclosure requirements.
- Foam:Polyurethane formulations dominate headliner and seating volume consumption. Bio-based polyols from castor oil and soybean face agricultural commodity price volatility that compresses margin predictability against petroleum benchmarks.
- Fabric:Recycled PET textiles displace virgin synthetic fibers across European seating applications. Cost parity and REACH compliance accelerate substitution in FORVIA Faurecia and Adient PLC supply chains.
- Vinyl:Phthalate-plasticized compounds face accelerated obsolescence from SVHC listings. Legacy slush molds and injection systems risk stranded asset status before depreciation completion.
Volume concentrates in Foam; Fabric climbs the fastest on recycled feedstock adoption.
End User:
Centralized sustainability procurement functions now override decentralized model-line sourcing authority.
- OEMs:Volkswagen Group and Mercedes-Benz AG established dedicated sustainable materials desks with consolidated negotiation leverage. Fleet sustainability scorecards concentrate procurement authority, forcing Tier 1 suppliers to document Scope 3 emissions across leather tanning and synthetic fiber chains.
- Aftermarket Suppliers:Price-sensitive channels prioritize cost-optimized vinyl and fabric specifications without bio-based premiums. REACH compliance costs pass through less efficiently than in OEM direct supply.
- Vehicle Assemblers:Contract manufacturing operations for emerging electric vehicle brands source through Tier 1 integrators rather than direct material qualification.
- Custom Builders:Low-volume specialty and luxury coachbuilders specify Italian tannery leather and bespoke fabric combinations. CSRD disclosure requirements penetrate this segment more slowly than mass-market OEM channels.
Procurement volume aggregates with OEMs; custom builders expand most quickly on premium electric vehicle niche demand.
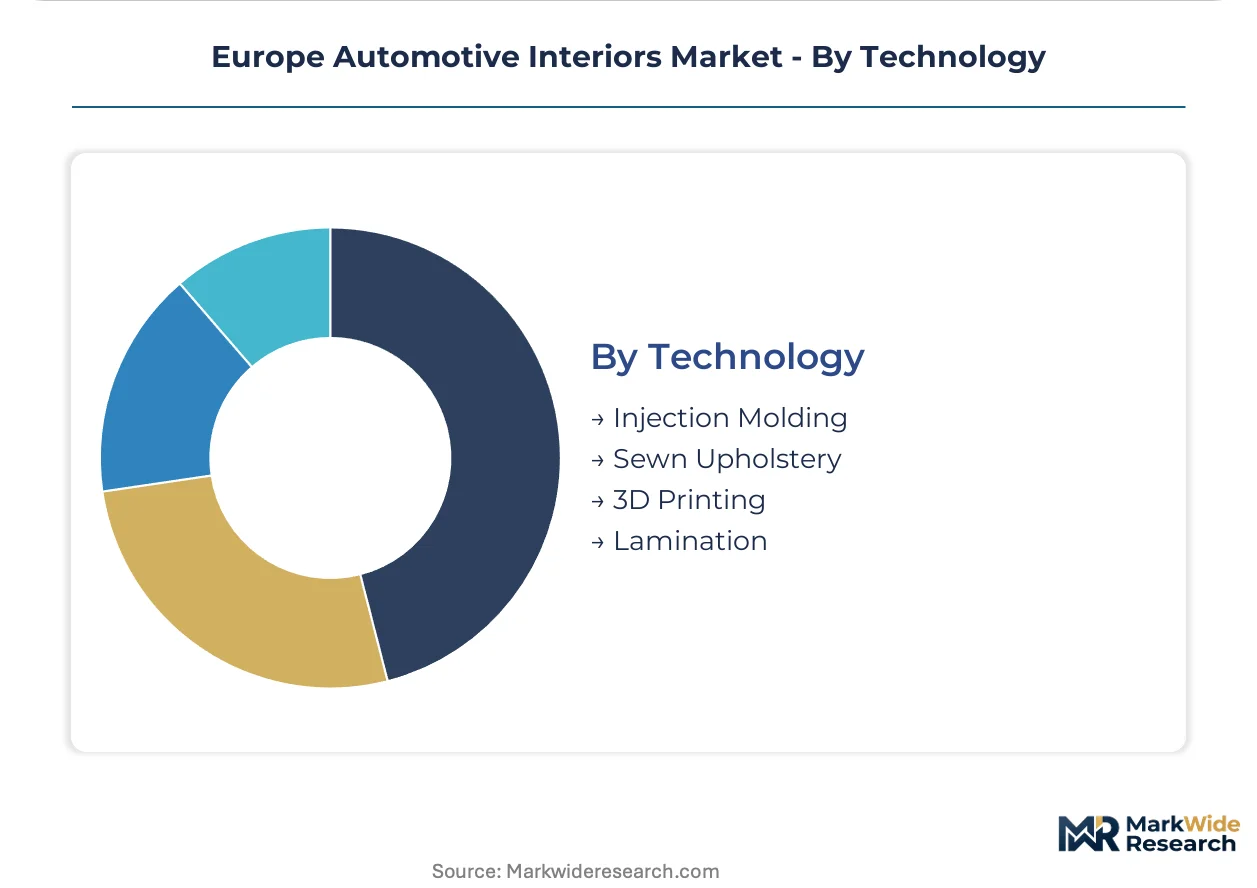
Technology:
Digital manufacturing convergence compresses prototype-to-production cycles for sustainable material variants.
- Injection Molding:Structural carriers for dashboard and door panel substrates rely on high-volume thermoplastic processing. Glass-mat composite formulations unify previously separate engineering disciplines into single-material solutions.
- 3D Printing:Additive manufacturing of prototype tooling reduces design iteration cycles for soft-touch dashboard skins. This fabrication category expands most quickly as German OEMs accelerate sustainable material qualification timelines.
- Sewn Upholstery:Seat cover assembly integrates leather and fabric materials with foam cushioning layers. Italian and Portuguese sewing operations serve premium German brand specifications.
- Lamination:Foam-to-fabric bonding for headliners and seat bases requires adhesive systems compliant with ECHA substance restrictions. Multi-tier certification from Tier 2 compounders extends qualification timelines.
Injection Molding anchors production volume; 3D Printing gains share fastest on prototype acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg and Bavaria special economic zones concentrate premium OEM supply chains, drawing Tier 1 interior suppliers into technical center clusters around Stuttgart and Munich. France, Italy, Poland, and Spain complete the regional map with distinct regulatory and industrial specializations.
Germany
Mercedes-Benz AG and Volkswagen Group sustainability desks mandate bio-based content thresholds across seating and dashboard specifications. The EU Green Deal carbon-border adjustment mechanism penalizes petroleum-based polymer imports, accelerating qualification of castor-oil polyurethane alternatives. Stuttgart-Munich technical corridors host FORVIA Faurecia and Adient PLC R&D facilities where prototype-to-production cycles compress for compliant interiors.
France
Renault Group and Stellantis electrification programs specify recycled PET textiles and glass-mat thermoplastic carriers for head-impact compliance. ECHA REACH Annex XVII restrictions on phthalate plasticizers force vinyl compound reformulation ahead of enforcement milestones. The Hauts-de-France region anchors PRETTL Lighting & Interior GmbH production serving cross-border German OEM supply chains.
Italy
Premium leather demand from German OEM cabins sustains tanning operations in Veneto and Tuscany despite ECHA chromium VI limits forcing wet-blue process modifications. Italian tanneries face concentrated Scope 3 disclosure pressure under CSRD rules. Lombardy-based Grupo Antolin coordinates dashboard and door panel supply across Mediterranean OEM programs.
Poland
Central European manufacturing cost advantages attract seating and trim assembly for export to German premium brands. EU structural funds support automation upgrades in Silesian and Greater Poland voivodeships where Grammer AG operates commercial-vehicle seating plants. REACH compliance costs pass through less efficiently than in direct OEM supply channels.
Spain
Seat SA and Stellantis Vigo operations source interior components through Barcelona-anchored supply chains. Catalonian compounders qualify citrate-ester vinyl alternatives for low-temperature flexibility specifications. Andalusian tanneries process hides for export to Italian finishing operations, extending supply chain length under CSRD traceability requirements.
Europe Automotive Interiors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated seat architects holding consolidated positions against fragmented trim suppliers. Three archetypes dominate: full-system integrators controlling foam-to-seat value chains, regional component specialists serving single OEM relationships, and commercial-vehicle durability experts. Competitive moves concentrate on backward integration into bio-based feedstocks and cross-border technical center expansion to compress qualification timelines.
Among Germany-based integrators, FORVIA Faurecia and Grammer AG exemplify divergent specialization vectors—passenger-car cabin systems versus commercial-vehicle durability benchmarks. Adient PLC anchors scale across Central European production networks. These three entities represent the tiered competitive structure where sustainability compliance capabilities now determine procurement access more than historical volume relationships.
| Leading Market Players |
|---|
| Grupo Antolin |
| PRETTL Lighting & Interior GmbH |
| FORVIA Faurecia |
| SKA Sitze GmbH |
| Groclin S.A |
| Adient PLC |
| Grammer AG |
| EFI Automotive Group |
| Recaro Group |
| Others |
Supply & Pricing Matrix
Volkswagen Group and Mercedes-Benz AG consolidated sustainable materials procurement authority is forcing Tier 2 compounders and Tier 3 chemical suppliers into simultaneous bio-based requalification, compressing margins through extended certification timelines and feedstock switching costs.
Pricing Analysis
Short lead-time premiums now apply to REACH-compliant vinyl compounds and bio-polyurethane foam as ECHA SVHC restriction deadlines compress qualification windows. Three-tier pricing structure across premium electric vehicle specifications, standard internal combustion platforms, and cost-optimized aftermarket channels reflects certification grade and volume scale differentiation. Price erosion runs through conventional petroleum-based substrates as carbon-border adjustment mechanisms penalize embedded emissions. Aftermarket suppliers exhibit highest price sensitivity due to inefficient compliance cost pass-through, while German OEM direct supply channels absorb premiums for documented Scope 3 transparency.
Supply Chain Analysis
Freight cost volatility between Italian tanneries and German assembly plants is amplifying landed cost uncertainty for premium leather specifications under CSRD traceability requirements. Supply concentrates in Germany's Stuttgart-Munich corridor, Poland's Silesian manufacturing zones, and Italy's Veneto-Tuscany tanning clusters. Raw material flows draw from castor oil and soybean polyol agricultural sources, recycled PET feedstock streams, and chrome-tanned hide processing. Single-source vulnerability sits with Italian wet-blue tannery concentration for Scope 3 disclosure-compliant leather. Distribution runs through Tier 1 integrator technical centers directly into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost burdens and CSRD disclosure mandates are accelerating supplier consolidation, eliminating smaller compounders lacking certification infrastructure and multi-tier traceability systems.
For Market Incumbents: Cement backward integration into castor oil and soybean polyol supply chains to insulate margin predictability against agricultural commodity cycles. Expand technical center capacity across Central European corridors to compress prototype-to-production timelines for bio-based foam qualification. Lock in long-term offtake agreements with Italian tanneries ahead of chromium VI enforcement milestones securing premium leather access. For New Entrants and Emerging Players: Launch via commercial vehicle seating specialization targeting Grammer AG durability benchmarks where bio-based foam penetration remains underdeveloped. Prioritize Polish and Spanish assembly operations serving German OEM export demand with lower compliance cost pass-through friction. Lead with 3D-printed prototype tooling capabilities to accelerate sustainable material qualification cycles for emerging electric vehicle brands. For Investors and Strategic Acquirers: The window for entry favors mid-cap compounders with documented REACH compliance pathways and established Tier 2 certification relationships. Long-term viability hinges on captive bio-based feedstock access and consolidated OEM procurement desk relationships. Watch for ECHA substance restriction acceleration announcements as inflection indicators for stranded asset risk in legacy vinyl tooling portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive castor oil and soybean polyol supply secures margin stability against petroleum benchmark volatility. |
| Technical Center Expansion in Central Europe | Polish and Czech R&D facilities compress qualification timelines for FORVIA Faurecia and Adient PLC supply chains. |
| CSRD-Compliant Scope 3 Documentation Systems | Emissions transparency infrastructure opens procurement access to Volkswagen Group and Mercedes-Benz AG sustainability desks. |
| 3D Printing Convergence with Slush Molding | Additive prototype tooling reduces design iteration cycles for soft-touch dashboard skin qualification. |
| Commercial Vehicle Seating Specialization | Grammer AG durability benchmarks in truck and bus applications remain underpenetrated by bio-based competitors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and ECHA compliance officers with validation against vehicle production databases, IHS Markit registration data, and ACC industry reports. Bottom-up material flow modeling triangulated against top-down OEM procurement spend analysis.
Granularity-level modeling segmented volume and value outputs across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from regression analysis of historical material substitution patterns and regulatory enforcement timeline impacts. Forecast inputs incorporated EU Green Deal carbon-border mechanism phase-in schedules and ECHA SVHC restriction acceleration scenarios.
REACH enforcement acceleration, agricultural commodity price spikes, and OEM procurement desk mandate tightening are the dominant revision risks to baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Front Windshield Market