
 Automotive Steering Wheel Covers Market | 2026-2036
Automotive Steering Wheel Covers Market Size, Share, and Industry Trends Forecast 2026-2036
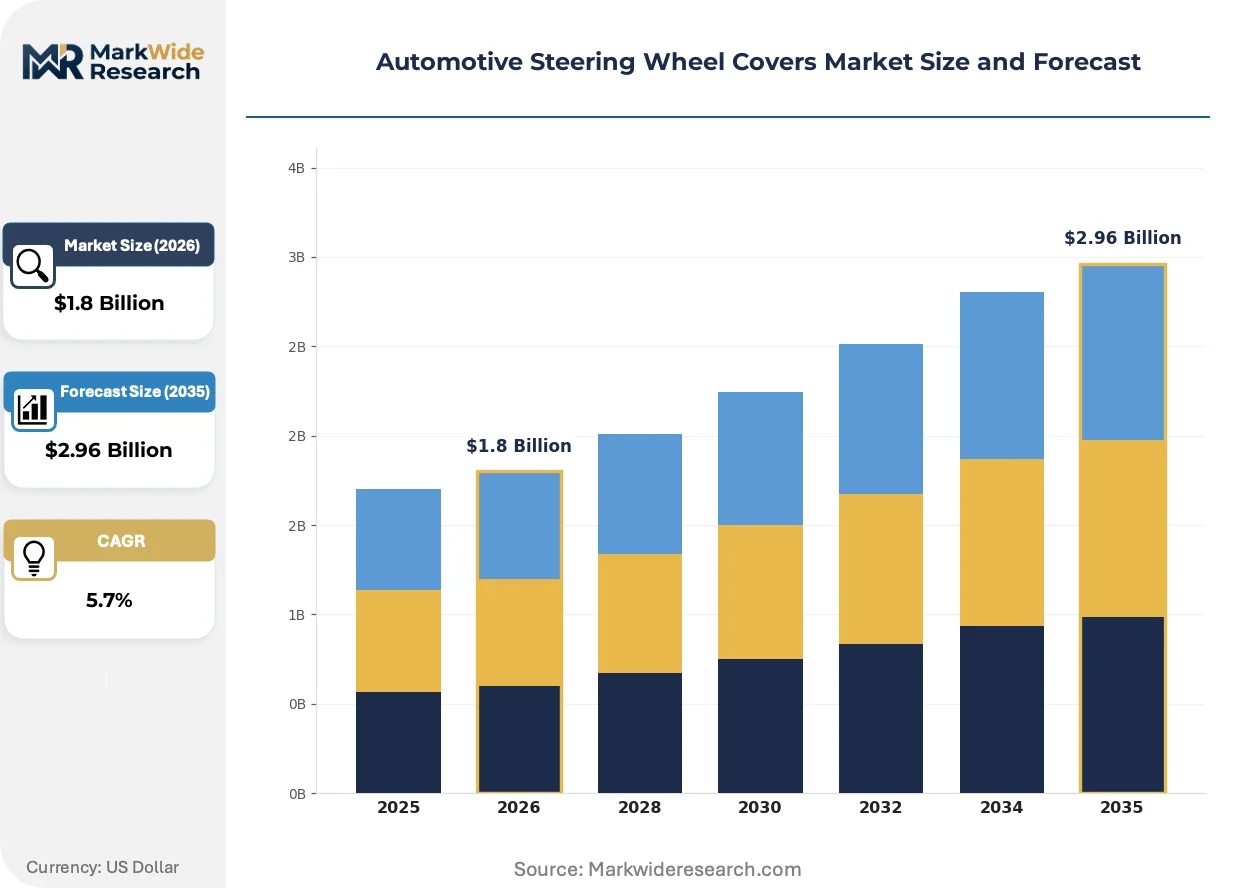
Automotive Steering Wheel Covers Market Outlook
China's Zhejiang province manufacturing corridor is narrowing the cost gap with legacy Southeast Asian suppliers for stitched leather wheel covers. Wheelskins leverages its domestic tanning partnerships to sustain margin stability across volatile hide markets. Mewant differentiates through precision-fit silicone molding technology that dominates the custom-fit channel. Valleycomfy anchors North American distribution through direct-to-consumer platform control, competing on fulfillment speed rather than price alone.
An automotive steering wheel cover is a removable or permanent sheath fabricated from leather, synthetic polymer composites, rubber compounds, or woven textiles, engineered to dimensions between 14 and 16 inches in diameter with grip coefficients measured by ISO 15534 ergonomic standards. Its primary commercial purpose spans occupant comfort modulation, surface protection against ultraviolet degradation and perspiration corrosion, and tactile interface customization for driver control confidence. Leather material commands the dominant margin pool due to raw material scarcity and artisan stitching labor intensity, while synthetic leather segments accelerate fastest as REACH-compliant polyurethane formulations displace PVC across European supply chains. The aftermarket provider channel leads volume throughput because collision repair networks and independent service shops bundle wheel cover replacement with interior refurbishment packages, whereas OEM fitment remains concentrated in premium vehicle trims where design style integration justifies factory installation.
The US NHTSA Federal Motor Vehicle Safety Standards govern steering assembly surface flammability and protrusion geometry, indirectly shaping cover material certification requirements for interstate commerce. China's SAMR enforces GB standards for interior volatile organic compound emissions that constrain adhesive selection in bonded-fit cover manufacturing. California's Proposition 65 labeling mandates create compliance friction for leather-tanned products entering that state, forcing suppliers to maintain dual SKUs or switch to chrome-free processing. Stakeholders must monitor evolving chemical disclosure regimes across multiple jurisdictions to determine whether regional formulation specialization or unified global product platforms deliver superior return on compliance investment.
Market Dynamics
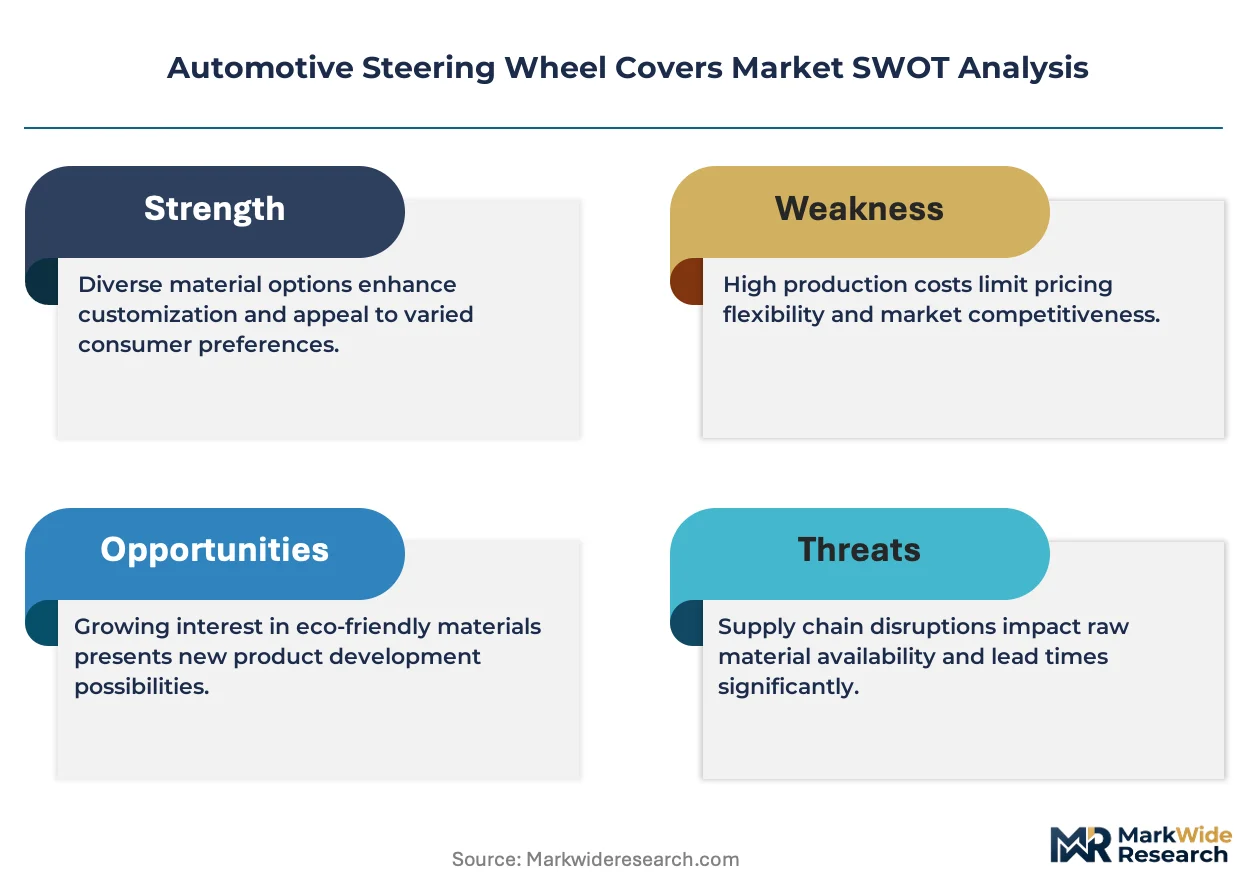
The EU's REACH chemical compliance framework is forcing polyurethane reformulation across synthetic leather supply chains, compressing margins for PVC-dependent producers while opening margin pools for compliant alternatives. This regulatory pressure intersects with aging fleet maintenance cycles in warm-climate markets to create asymmetric growth pockets.
Growth Catalysts
- REACH-compliant polyurethane formulations:European aftermarket service chains now mandate additive-free synthetic leather, pulling volume toward reformulated supply bases that invested early in chemical substitution.
- Aging fleet extension:Vehicle owners in sun-belt US states operate cars beyond 12-year lifespans, sustaining replacement-driven demand for UV-degraded steering wheel surface protection.
- Precision-fit silicone molding:Custom-fit channel buyers now specify dimensional tolerances measured by ISO 15534 ergonomic standards, creating premium attachment rates for technically capable suppliers.
Market Restraints
- Hide market volatility:Artisan-stitched leather covers face input cost instability from tanning capacity constraints and livestock supply fluctuations.
- Zhejiang manufacturing corridor concentration:Cost-competitive stitched leather production is narrowing toward a single Chinese province, creating geographic supply risk.
- California Proposition 65 friction:Chrome-tanned leather products entering the state require dual-SKU maintenance or costly processing switches, adding compliance overhead.
Strategic Opportunities
- Direct-to-consumer platform control:North American distributors can capture fulfillment-speed premiums by bypassing traditional automotive retail channels.
- GB standard-aligned adhesive selection:China's SAMR volatile organic compound emission rules create first-mover advantage for suppliers with pre-certified bonding systems.
- Silicone-leather hybrid convergence:Custom-fit precision molding is hybridizing with traditional leather aesthetics to unlock price points above either pure-play category.
Industry Challenges
- Chrome-free tanning skill scarcity:Leather processors lack technicians trained in alternative tanning chemistry required for California and EU market access.
- Multi-jurisdiction disclosure regimes:Suppliers must maintain parallel chemical documentation systems for NHTSA flammability, REACH additive thresholds, and GB emission standards.
- ISO 15534 certification timelines:Ergonomic grip coefficient testing for custom-fit covers extends product development cycles beyond mass-market alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Wheel Covers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Synthetic Leather, Rubber, Fabric Fit Type: Universal Fit, Custom Fit, Semi-Custom Fit, Slip-On End User: OEMs, Aftermarket Providers, Retailers, Individual Customers Design Style: Sport, Classic, Modern, Vintage |
| Companies Covered | Wheelskins, Mewant, Steisone, Valleycomfy, MotorTrend, FH Group, SEG Direct, BOKIN, BDK Auto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Wheel Covers Market Strategic Shifts
Material science convergence and regulatory chemical disclosure are actively compressing traditional segmentation boundaries. Suppliers now compete on formulation agility rather than manufacturing scale alone.
Silicone molding technology is hybridizing with leather surface lamination to create precision-fit covers that satisfy both ergonomic measurement standards and aesthetic customization demands. Aftermarket service chains in warm-climate US states are adopting these hybrid constructions fastest, replacing pure leather or pure synthetic SKUs. The structural consequence is margin compression for single-material suppliers unable to bridge both performance and tactile preference requirements.
REACH's tightening permissible thresholds for phthalate plasticizers and heavy metal additives is forcing wholesale polyurethane reformulation across European supply chains. Manufacturers serving the EU market must now certify additive-free synthetic leather or exit the region entirely. Aftermarket collision repair networks are most affected, as they rely on low-cost PVC covers bundled into interior refurbishment packages and face sourcing disruption.
Buyer concentration among direct-to-consumer platforms is disintermediating traditional automotive retail and wholesale distribution. Independent service shops now source covers through fulfillment-speed-oriented channels rather than distributor catalogs. This pattern concentrates most visibly in North American markets where platform-controlled logistics networks enable next-day replacement part availability.
Automotive Steering Wheel Covers Market Segmentation
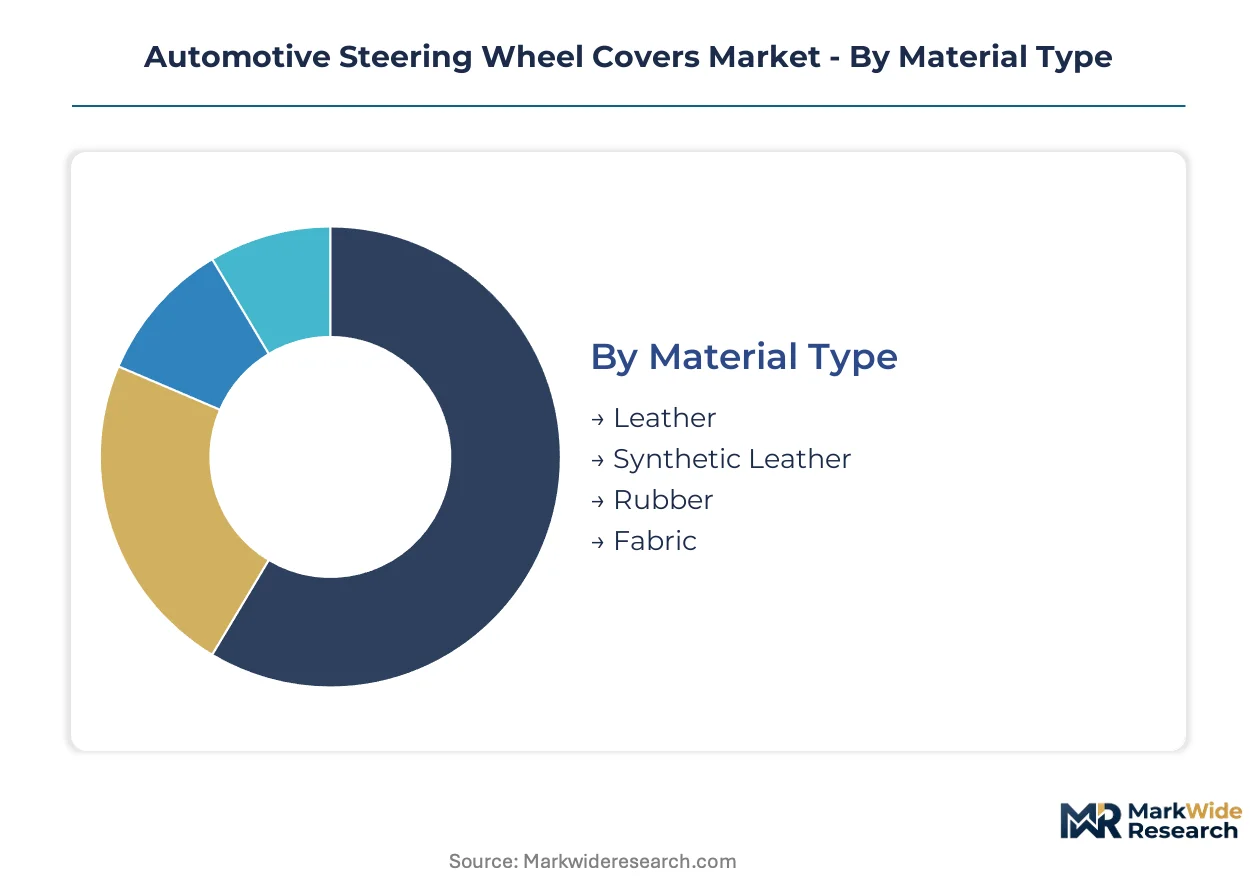
Aftermarket service intensity varies sharply across segment boundaries, with collision repair networks bundling wheel cover replacement into interior refurbishment packages while OEM fitment concentrates in premium vehicle trims. Material chemistry and dimensional precision create distinct margin pools that suppliers must navigate simultaneously.
Material Type:
After-sales service intensity peaks with leather covers requiring artisan stitching labor and hide sourcing relationships, while synthetic alternatives dominate high-frequency replacement cycles.
- Leather:Raw material scarcity and tanning capacity constraints compress margins for artisan-stitched covers. Demand concentrates in warm-climate US states where UV degradation accelerates replacement cycles and customization culture sustains premium price acceptance.
- Synthetic Leather:REACH-compliant polyurethane formulations displace PVC across European supply chains as aftermarket service chains mandate additive-free certification. Collision repair networks in sun-belt regions adopt these reformulated SKUs fastest to avoid sourcing disruption.
- Rubber:Molded compounds serve commercial fleet operators prioritizing grip coefficient durability over tactile aesthetics in heavy-use applications.
- Fabric:Woven textile covers occupy economy positioning for price-sensitive individual customers seeking basic surface protection.
Leather holds the largest share; momentum sits with synthetic leather as regulatory pressure accelerates chemical reformulation.
Fit Type:
Dimensional tolerance requirements stratify procurement patterns, with ISO 15534 ergonomic certification creating tiered supplier qualification barriers.
- Custom Fit:Precision silicone molding technology dominates this channel with dimensional tolerances measured by ISO 15534 ergonomic standards. Aftermarket collision repair networks in North America specify these covers for driver control confidence in aging fleet extensions.
- Universal Fit:Elasticized construction accommodates diameter ranges between 14 and 16 inches for mass-market penetration. Independent service shops source these SKUs through fulfillment-speed-oriented direct-to-consumer platforms rather than traditional distributor catalogs.
- Semi-Custom Fit:Adjustable lacing systems bridge the gap between universal elasticity and precision molding for mid-tier price positioning.
- Slip-On:Elastic sleeve construction targets individual customers seeking tool-free installation without professional service intervention.
Universal Fit generates the highest volume throughput; Custom Fit commands the steepest expansion trajectory as ergonomic certification becomes a procurement filter.
End User:
Channel control dynamics determine margin capture, with platform-controlled logistics disintermediating traditional automotive retail distribution.
- Aftermarket Providers:Collision repair networks and independent service shops bundle wheel cover replacement with interior refurbishment packages. These buyers now source through fulfillment-speed-oriented channels rather than distributor catalogs, concentrating volume in North American markets with next-day logistics capabilities.
- OEMs:Factory fitment remains concentrated in premium vehicle trims where design style integration justifies pre-installation. Design style integration requirements extend product development cycles compared to aftermarket alternatives.
- Retailers:Traditional automotive retail channels face disintermediation pressure as direct-to-consumer platforms capture fulfillment-speed premiums.
- Individual Customers:Customization culture in warm-climate states drives direct purchasing for UV-degraded steering wheel surface protection.
Aftermarket Providers dominate volume; OEMs retain the highest per-unit margin despite lower throughput.
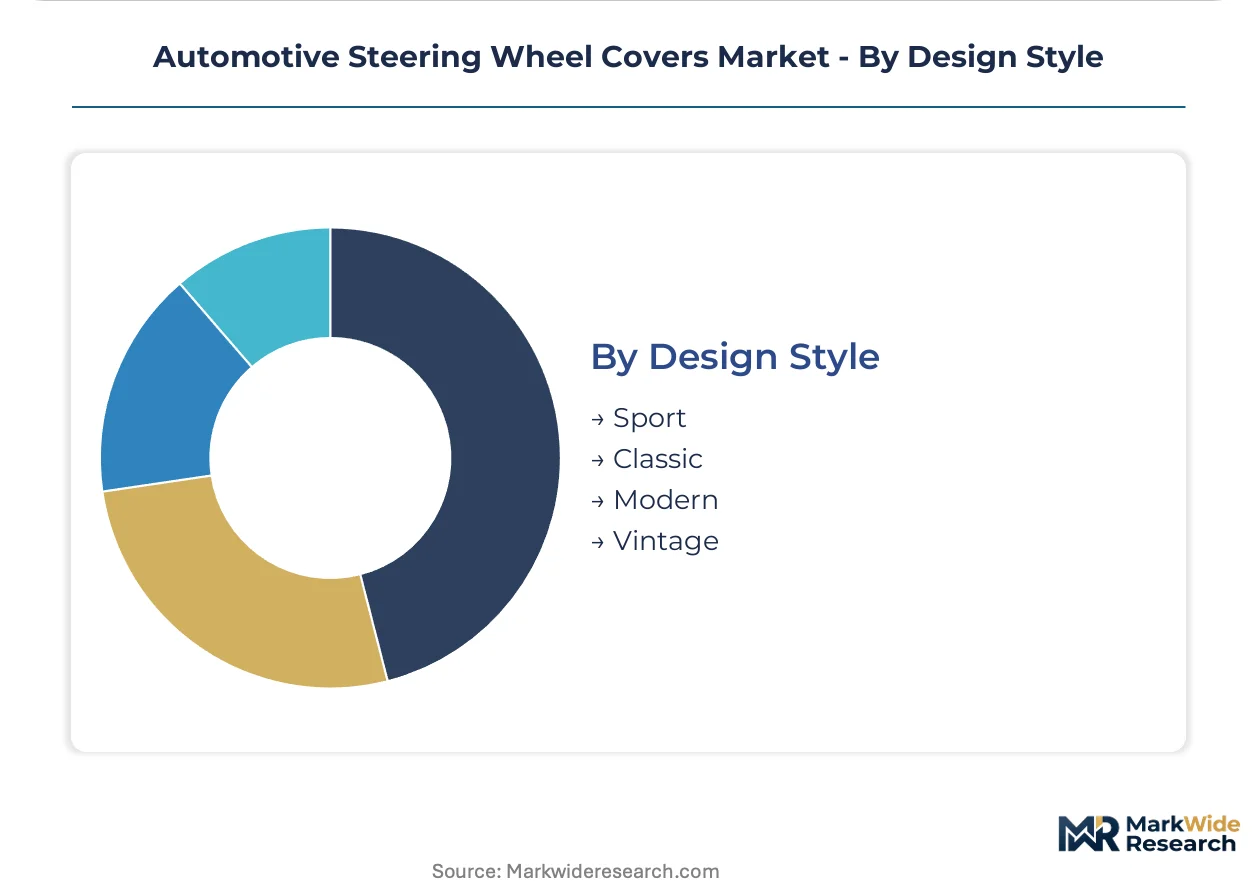
Design Style:
Aesthetic segmentation aligns with vehicle age cohorts and regional customization preferences rather than functional performance differentiation.
- Sport:Perforated leather construction with contrast stitching targets performance vehicle owners seeking tactile grip enhancement. Demand concentrates in California and Florida where warm-climate replacement cycles intersect with enthusiast culture.
- Classic:Smooth grain leather with minimal stitching appeals to luxury vehicle owners extending operational lifespans of aging premium fleets. Chrome-free tanning requirements for California Proposition 65 compliance add SKU complexity for this segment.
- Modern:Synthetic leather with geometric embossing serves mass-market buyers prioritizing surface protection over heritage aesthetics.
- Vintage:Distressed leather finishes and period-correct color matching address restoration specialists and collector vehicle owners.
Classic holds the largest share; Sport is gaining share fastest as enthusiast customization penetrates mainstream replacement behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stitched leather fabrication concentrates in Zhejiang province's manufacturing corridor, while polyurethane reformulation accelerates across European supply chains responding to chemical compliance mandates. Regional demand patterns diverge sharply between warm-climate replacement markets and regulatory-driven specification shifts.
United States
Sun-belt states sustain replacement cycles as vehicle owners operate aging fleets beyond twelve-year lifespans. NHTSA Federal Motor Vehicle Safety Standards govern steering assembly surface flammability for interstate commerce. California's Proposition 65 labeling mandates create compliance friction for chrome-tanned leather products entering the state.
China
Zhejiang province manufacturers narrow cost gaps with legacy Southeast Asian suppliers for stitched leather wheel covers. SAMR enforces GB standards for interior volatile organic compound emissions that constrain adhesive selection. The Yangtze River Delta industrial cluster hosts precision-fit silicone molding operations serving export markets.
Germany
Aftermarket collision repair networks mandate REACH-compliant polyurethane formulations, displacing PVC-dependent supply bases. ECHA oversees tightening permissible thresholds for phthalate plasticizers and heavy metal additives. Bavaria-based distributors control fulfillment-speed-oriented channels for next-day replacement part availability.
Japan
Precision-fit custom channel buyers specify dimensional tolerances measured by ISO 15534 ergonomic standards. METI coordinates domestic chemical disclosure alignment with international frameworks. The Kansai region maintains tanning partnerships sustaining margin stability across volatile hide markets.
United Kingdom
Direct-to-consumer platform control disintermediates traditional automotive retail distribution channels. The UK's post-EU chemical regulatory framework maintains REACH-equivalent additive thresholds for imported synthetic leather. Midlands-based service shops bundle wheel cover replacement with interior refurbishment packages.
Automotive Steering Wheel Covers Market Competitive Environment
Leather-centric artisans and synthetic formulation specialists split the market between premium tactile positioning and regulatory-compliant volume throughput. The vendor base organizes around three strategic archetypes: domestic tanning partnership holders, precision-fit silicone molders, and direct-to-consumer platform operators. Consolidation pressure concentrates among PVC-dependent producers facing REACH-mandated reformulation costs. Dominant competitive moves include geographic capacity relocation toward Zhejiang manufacturing corridors and backward integration into chrome-free tanning operations.
Within the leather partnership tier, Wheelskins exemplifies domestic tanning integration sustaining margin stability across volatile hide markets. Mewant occupies a position representing precision-fit silicone molding technology that dominates the custom-fit channel. Valleycomfy anchors North American distribution through direct-to-consumer platform control, competing on fulfillment speed rather than price alone. These three entities collectively illustrate the strategic divergence between material-scarcity positioning and logistics-centric market capture.
| Leading Market Players |
|---|
| Wheelskins |
| Mewant |
| Steisone |
| Valleycomfy |
| MotorTrend |
| FH Group |
| SEG Direct |
| BOKIN |
| BDK Auto |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's manufacturing corridor concentrates stitched leather capacity and compresses margin pools for artisan suppliers competing on cost. REACH-compliant polyurethane reformulation in Europe and hide market volatility create asymmetric pricing pressure across material tiers, while direct-to-consumer platform control in North America extracts fulfillment-speed premiums from traditional distribution markups.
Pricing Analysis
REACH dictates the pricing tier structure across the European aftermarket, separating additive-free polyurethane formulations from displaced PVC SKUs. Three-tier pricing structure across premium artisan leather, compliant synthetic, and economy fabric levels stratifies procurement, with certification grade and volume scale as primary differentiation drivers. Cost compression in synthetic leather tiers is intensifying because reformulation investment loads fixed costs onto smaller production batches. Collision repair networks show highest price sensitivity due to bundled refurbishment economics, while individual customization buyers in warm-climate states accept premium positioning.
Supply Chain Analysis
Contract manufacturing concentrates among Zhejiang-based stitched leather specialists and Yangtze River Delta silicone molding operations serving export markets. Geographic supply concentration centers on China for finished covers, with raw hide sourcing tethered to tanning partnerships in Japan and South Korea. Chrome-tanned leather feedstock and REACH-certified polyurethane resin constitute critical input dependencies. Single-source vulnerability runs through Zhejiang's provincial corridor concentration. Distribution runs through direct-to-consumer platforms disintermediating traditional automotive retail catalogs in North America and European aftermarket service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits across regulatory-driven material substitution and ergonomic certification tiers, as aging fleet maintenance and chemical compliance mandates create niche supplier qualification barriers that resist commoditization.
For Market Incumbents: Build chrome-free tanning capability as a regulatory moat against REACH and California Proposition 65 exclusion risk. Backward integration into captive hide processing secures margin stability across volatile livestock supply cycles. Precision-fit silicone molding certification creates technical stickiness with collision repair networks specifying ISO 15534 ergonomic standards. Capacity addition in Yangtze River Delta clusters maintains cost parity with Zhejiang competitors. For New Entrants and Emerging Players: Pursue hybrid silicone-leather construction as the most penetrable white-space between pure-play material categories. Aftermarket service chains in sun-belt US states offer fastest adoption velocity for technically differentiated SKUs bundling replacement speed with tactile customization. Direct-to-consumer platform launch with next-day fulfillment infrastructure bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH-mandated reformulation costs will force PVC-dependent producers to exit, concentrating volume among early-compliant formulation specialists. Acquisition target archetype: mid-scale polyurethane reformulators with pre-certified European supply relationships and direct-to-consumer logistics capabilities. Signal to watch is aftermarket service chain procurement policy shifts mandating additive-free certification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | Early polyurethane reformulation secures European aftermarket service chain procurement mandates against PVC displacement. |
| Chrome-Free Tanning Transition | Alternative chemistry adoption unlocks California and EU market access without dual-SKU maintenance overhead. |
| ISO 15534 Certification Program | Ergonomic grip coefficient testing creates qualification barriers protecting custom-fit channel margins. |
| Direct-to-Consumer Platform Buildout | Fulfillment-speed control captures replacement-driven demand from aging fleet owners bypassing traditional retail. |
| Zhejiang Manufacturing Footprint Expansion | Provincial corridor concentration narrows cost gaps with Southeast Asian legacy suppliers for stitched leather. |
Study Parameters
Desk research of customs trade records, automotive aftermarket distributor catalogs, and chemical regulatory filings preceded structured interviews with Tier 1 supplier procurement managers, aftermarket service chain operations directors, tanning facility technical leads, and direct-to-consumer platform logistics heads. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards documentation, ECHA REACH substance restriction updates, and SAMR GB standard emission protocols. Bottom-up volume modeling across material type and fit type segments triangulated against top-down regional demand aggregation.
Assumptions held fixed include regulatory enforcement timelines for REACH phthalate thresholds and NHTSA flammability certification requirements, with variable sensitivity on hide market price volatility and direct-to-consumer platform penetration rates across the projection horizon. Segmentation dimensions modeled encompass material chemistry, dimensional fit precision, end-user channel control, and regional regulatory cluster. CAGRs derived from replacement cycle frequency analysis weighted by fleet age demographics and climate-driven UV degradation patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on vehicle accessories or livestock feed cost inflation would shift the trajectory. Forecasts reflect documented assumptions without forward revision guarantees. Quarterly review of aftermarket service chain procurement policy updates and ECHA substance restriction proposal timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Automotive Convertible Top Market