
 Car Radiator Market | 2026-2036
Car Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
Car Radiator Market Analytics
Modular cooling pack integration is recalibrating how OEMs specify thermal management systems, bundling radiators with charge air coolers and condensers into single procurement units. Modine Manufacturing Company leverages its North American production footprint to anchor long-term supply agreements with heavy-duty truck builders. Denso Corporation competes through in-house production of aluminum microchannel tubing, controlling critical material inputs for its radiator lines.
A car radiator is a heat exchanger device, typically constructed from aluminum alloy cores with brazed tube-and-fin architecture or copper-brass tanks with soldered joints, designed to dissipate thermal energy from engine coolant into ambient airflow and maintain optimal operating temperatures for internal combustion and electrified powertrains. Crossflow configurations dominate passenger car applications due to packaging efficiency behind low-profile front fascias, while double-pass designs capture growing interest in performance and commercial segments where thermal load intensity demands extended coolant dwell time within the core. Aluminum material share continues to expand as OEMs prioritize mass reduction, though copper-brass retains niche positions in aftermarket replacement channels where repair shop familiarity and solderability sustain demand.
EPA fuel economy mandates and NHTSA safety standards jointly shape radiator design requirements in the United States, compelling thinner-core, higher-efficiency architectures that preserve frontal crash absorption zones. The European Union's F-Gas Regulation and REACH chemical restrictions influence coolant compatibility specifications and brazing flux formulations across supplier portfolios. Stakeholders must monitor how battery thermal management integration in electric vehicle platforms redirects engineering resources and capital allocation away from traditional engine-cooling architectures.
Market Dynamics
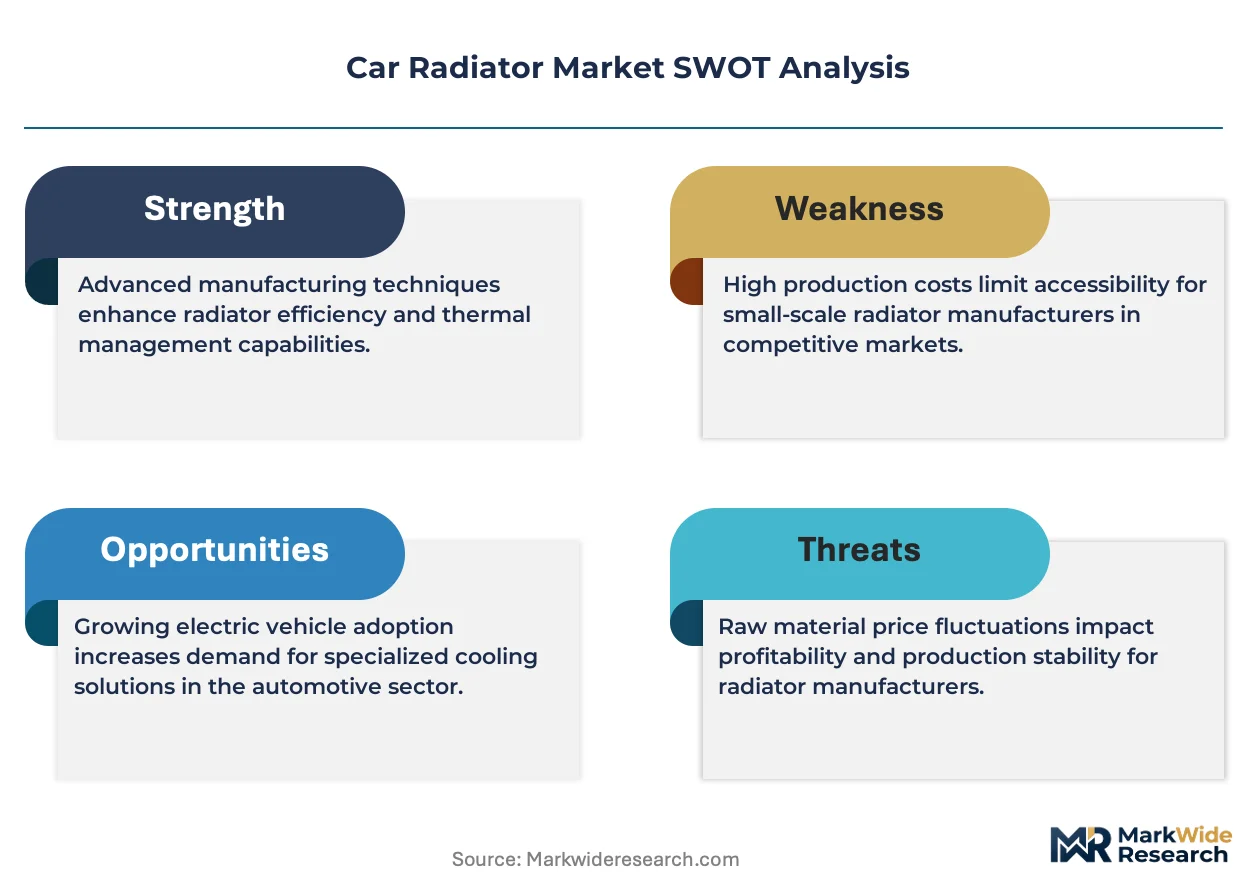
Material substitution from copper-brass to aluminum alloy architectures is compressing traditional supply chains and forcing Tier-2 suppliers to retool brazing capabilities or exit the value chain entirely.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Stringent mass-reduction mandates in the United States accelerate aluminum radiator adoption across light-duty vehicle platforms.
- China's domestic vehicle production scale:Local cooling module suppliers deepen integration with assembly plants, creating captive demand for regionally manufactured thermal components.
- Microchannel tube technology:Enhanced heat transfer efficiency enables thinner-core designs that preserve frontal crash absorption zones without sacrificing cooling capacity.
Market Restraints
- Aluminum price volatility:Input cost swings tied to energy-intensive smelting operations compress margin stability for mid-tier radiator fabricators.
- Copper-brass aftermarket entrenchment:Repair shop familiarity and solderability sustain legacy demand in replacement channels, slowing full material transition.
- REACH chemical restrictions:ECHA limitations on brazing flux formulations force reformulation investments across European supplier portfolios.
Strategic Opportunities
- Electric vehicle battery thermal management:Convergence of liquid-cooled battery packs with traditional cooling architectures creates integrated module demand.
- Modular cooling pack procurement:Bundled radiator-condenser-charge air cooler units open design-to-cost contracts with heavy-duty truck builders.
- India's automotive production expansion:PLI scheme incentives for component manufacturing attract radiator suppliers to establish localized brazing operations.
Industry Challenges
- Aluminum brazing technician scarcity:Controlled atmosphere brazing expertise concentrates at a handful of specialized facilities, constraining capacity expansion.
- Dual-platform engineering overhead:Simultaneous internal combustion and electrified powertrain programs split R&D resources and prolong validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Radiator Market |
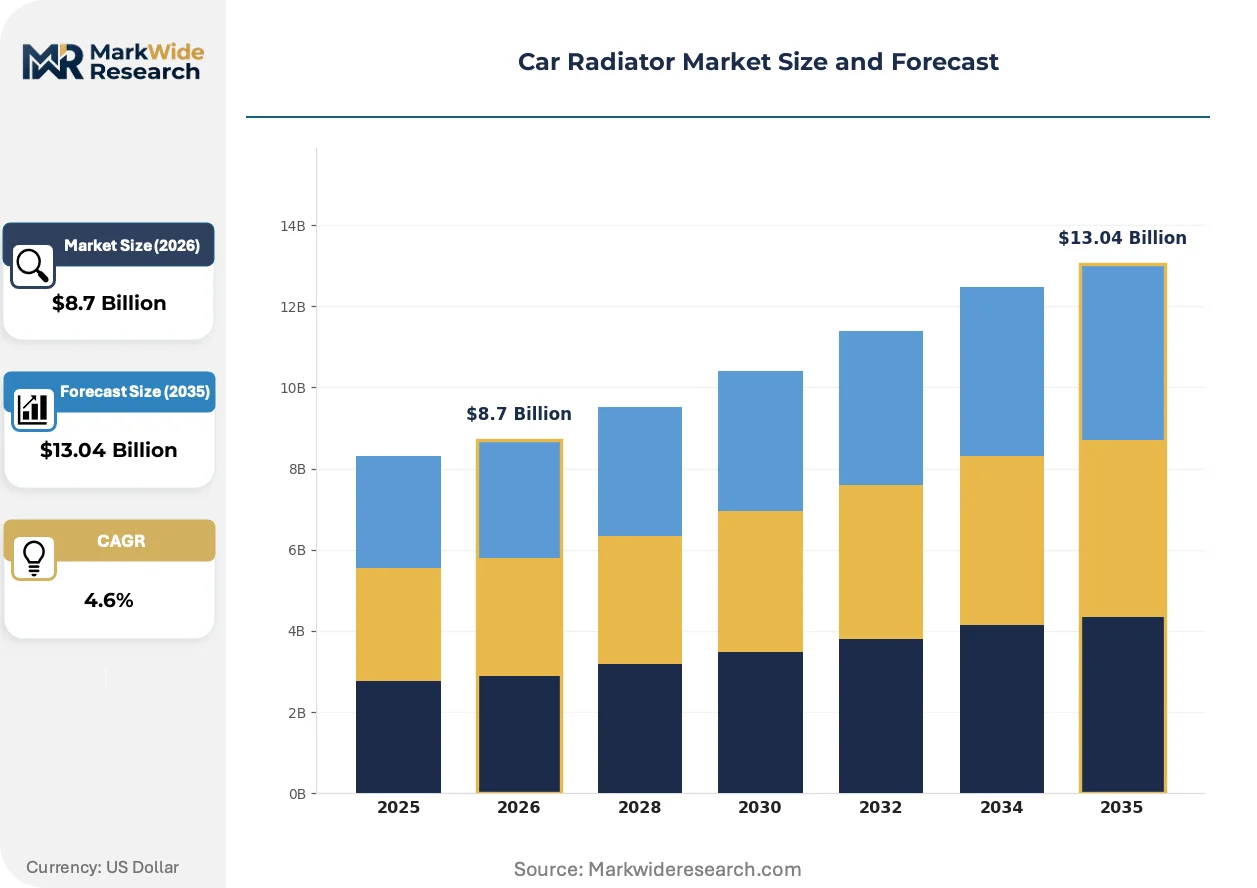
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crossflow, Downflow, Single Pass, Double Pass Material: Aluminum, Copper, Plastic, Composite Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles Cooling Method: Air Cooled, Liquid Cooled, Evaporative, Mixed |
| Companies Covered | Modine Manufacturing Company, T.RAD Co., Ltd., Denso Corporation, Nissens A/S, Hanon Systems Co., Ltd., Valeo S.A., Marelli Holdings Co., Ltd., Koyorad Co., Ltd., MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Radiator Market Evolving Landscape
Thermal management architectures are fragmenting across powertrain types, with engineering teams diverging toward specialized cooling circuits rather than universal platform designs.
Aluminum microchannel tube-and-fin construction is electrifying passenger car thermal systems. The architecture reduces core mass by one-third versus copper-brass equivalents. European and Asian OEMs now specify microchannel as baseline for subcompact and compact vehicle programs. This technology is electrifying competitive positioning by enabling suppliers without legacy soldering infrastructure to capture design wins.
The European Union's F-Gas Regulation is recalibrating coolant compatibility specifications across supplier portfolios. Low-global-warming-potential refrigerants demand modified seal materials and revised pressure ratings in integrated cooling modules. Heavy-duty commercial segments face the steepest reformulation timelines as fleet operators accelerate compliance ahead of enforcement windows.
Fleet procurement departments are consolidating thermal system specifications across vehicle classes to compress supplier qualification overhead. Standardized cooling module architectures replace bespoke designs in North American heavy-truck channels. This concentration is most visible in long-haul segments where total cost of ownership calculations dominate specification authority.
Car Radiator Market Segmentation
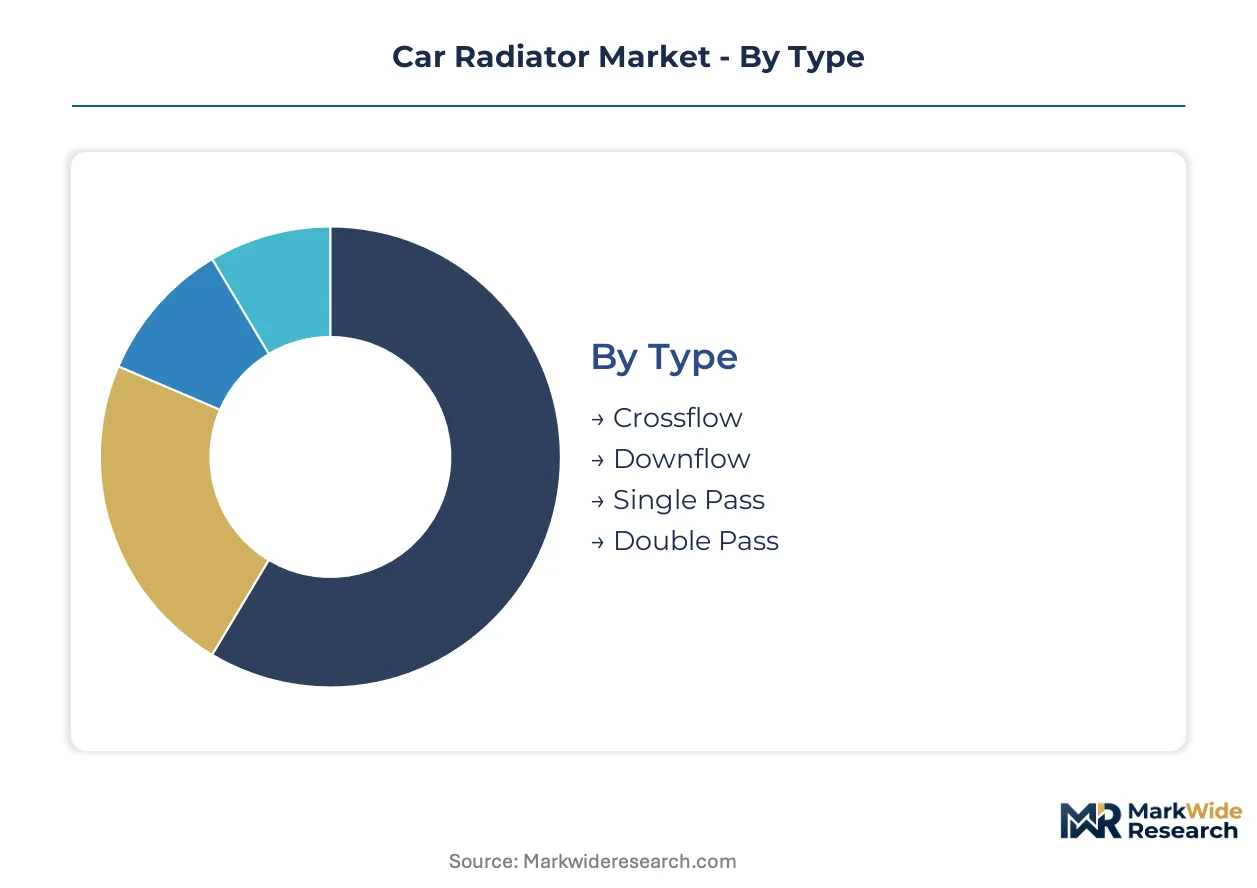
Radiator specification varies sharply across powertrain architectures and thermal load profiles. Material selection and flow configuration determine mass, efficiency, and compatibility with electrified cooling circuits. Procurement teams segment specifications to match warranty targets and platform lifecycle costs.
Type:
Flow path geometry governs packaging constraints and thermal exchange efficiency in front-end module design.
- Crossflow:Coolant traverses horizontally across the core while air flows vertically, enabling low-profile installations behind aerodynamic front fascias. Passenger car OEMs in Germany and Japan specify crossflow as baseline for compact and mid-size platforms where hood height reduction supports fuel economy targets.
- Double Pass:Coolant circulates through the core twice via a central tank partition, extending dwell time and heat rejection capacity without enlarging frontal area. Performance vehicle builders and heavy-duty truck manufacturers specify double-pass architectures where sustained high-load operation demands thermal headroom.
- Downflow:Vertical coolant movement from top tank to bottom tank suits traditional body-on-frame architectures with ample hood clearance.
- Single Pass:Straight-through coolant path minimizes pressure drop and cost in light-duty applications with moderate thermal loads.
Mature deployment sits with downflow configurations in legacy truck platforms. Newer deployment is concentrated in crossflow designs for electrified vehicle front-end packaging.
Material:
Material selection trades thermal conductivity against mass reduction and corrosion resistance across operating environments.
- Aluminum:Brazed aluminum microchannel construction reduces core mass substantially versus copper-brass equivalents while maintaining adequate heat transfer. EPA fuel economy mandates and similar efficiency regulations in the European Union accelerate aluminum specification across light-duty vehicle programs.
- Copper:Superior thermal conductivity and solderability sustain demand in aftermarket replacement channels where repair shop familiarity and field repairability outweigh mass considerations.
- Plastic:Glass-reinforced nylon end tanks replace metal in cost-sensitive applications where pressure and temperature ratings permit polymer substitution.
- Composite:Hybrid material systems combining aluminum cores with polymer tanks optimize weight and cost in specific platform applications.
Composite adoption climbs fastest in Asian compact vehicle programs. Copper retains entrenched positions in North American aftermarket service networks.
Vehicle Type:
Powertrain thermal load and packaging volume dictate radiator sizing and integration complexity.
- Passenger Cars:Sedan and hatchback platforms prioritize low-profile crossflow cores with aluminum microchannel construction to preserve crash absorption zones and aerodynamic efficiency.
- Commercial Vehicles:Heavy-duty trucks and buses demand double-pass or multi-core architectures with extended surface area to manage sustained high-output diesel and natural gas engine thermal rejection.
- SUVs:Larger frontal area permits bigger core dimensions, though unibody crossover platforms increasingly adopt passenger car cooling module specifications.
- Electric Vehicles:Battery thermal management integration redirects engineering resources toward liquid-cooled pack architectures that converge with traditional cooling circuits.
Passenger car specifications dominate production volume. Electric vehicle thermal systems are expanding most quickly as platforms scale.
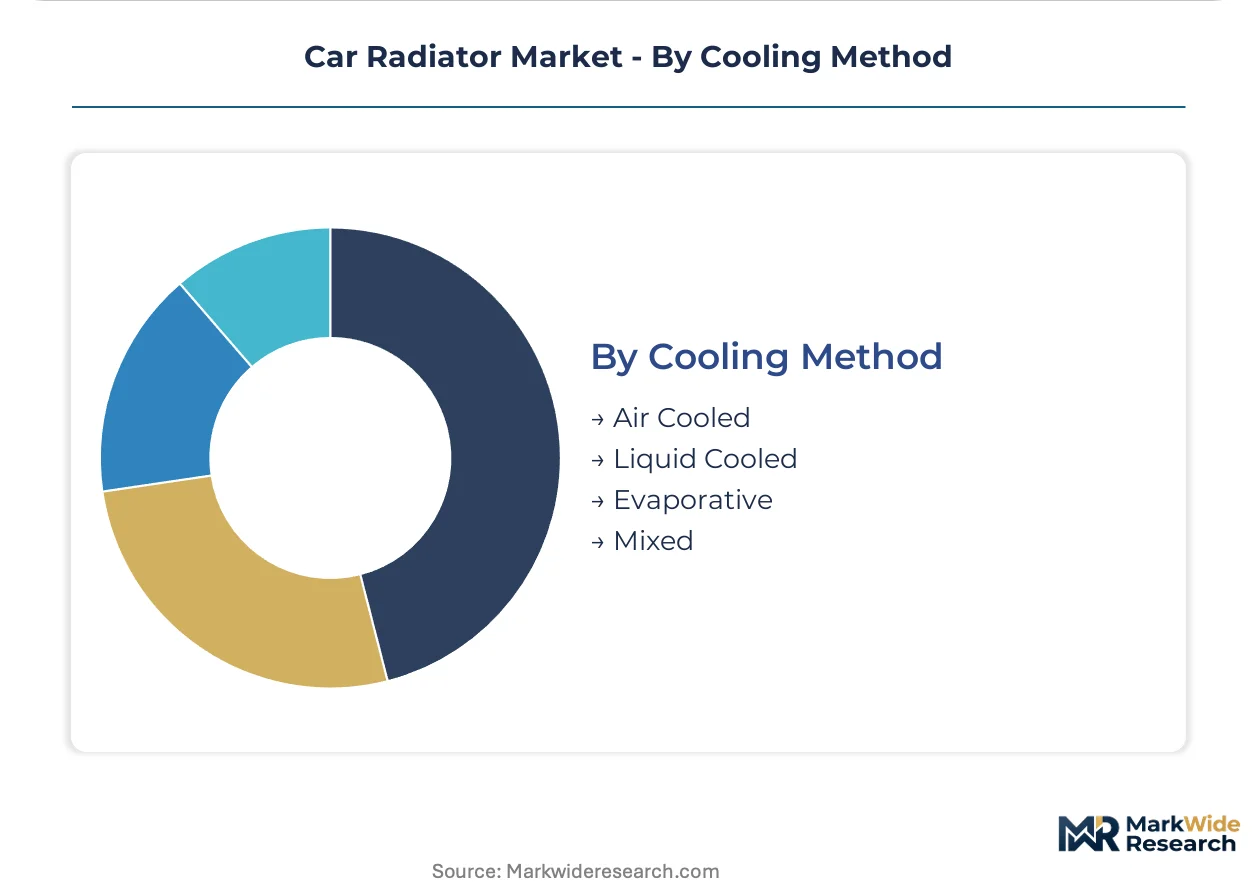
Cooling Method:
Thermal management strategy diverges between combustion powertrains and electrified architectures.
- Liquid Cooled:Engine coolant circulation through radiator cores remains standard for internal combustion and hybrid powertrains, with expansion into battery and power electronics cooling for electrified platforms.
- Air Cooled:Direct airflow over finned surfaces persists in small-displacement motorcycles, industrial equipment, and legacy vehicle applications where simplicity outweighs efficiency.
- Evaporative:Phase-change cooling with refrigerant loops supports high-performance applications and specialized thermal management in battery systems.
- Mixed:Hybrid cooling architectures combine liquid circuits for engine and battery with auxiliary air-cooled heat exchangers for power electronics and cabin conditioning.
Air-cooled deployment concentrates in emerging market two-wheeler and three-wheeler segments. Mixed architectures are gaining share fastest as hybrid and plug-in platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of automotive cooling modules consumed domestically, while the United States and Germany remain substantial import markets for specialized aluminum brazing components. Production capacity clusters near vehicle assembly plants to minimize logistics costs and enable just-in-time delivery schedules.
United States
Domestic heavy-duty truck builders anchor demand for double-pass radiator architectures in the Midwest industrial corridor. EPA Corporate Average Fuel Economy standards compel thinner-core designs that preserve frontal crash absorption zones per NHTSA safety protocols. Detroit-area thermal module suppliers coordinate directly with Ford, General Motors, and Stellantis assembly plants in Michigan and Ohio.
Germany
Premium passenger car OEMs in Bavaria and Baden-Württemberg specify aluminum microchannel construction for compact and mid-size vehicle platforms. The European Union's F-Gas Regulation and REACH chemical restrictions from ECHA mandate reformulated brazing fluxes and modified seal materials in integrated cooling modules. Stuttgart and Munich host concentrated engineering centers where suppliers co-develop thermal management systems with Mercedes-Benz, BMW, and Porsche.
China
Domestic vehicle production scale in the Yangtze River Delta and Pearl River Delta generates captive demand for regionally manufactured radiators. MIIT fuel efficiency standards and dual carbon goals accelerate aluminum substitution away from legacy copper-brass designs. Shanghai and Guangzhou cooling module suppliers deepen integration with BYD, Geely, and SAIC assembly plants through localized brazing operations.
Japan
Hybrid powertrain proliferation in the Kanto and Chubu regions sustains demand for compact crossflow radiators with integrated battery cooling circuits. METI energy efficiency guidelines prioritize mass reduction in thermal components for both domestic consumption and export markets. Toyota City and Nagoya industrial clusters concentrate controlled atmosphere brazing expertise at specialized supplier facilities.
India
Automotive production expansion in Maharashtra, Gujarat, and Tamil Nadu attracts radiator suppliers establishing localized manufacturing footprints. PLI scheme incentives for component manufacturing reduce import dependence for aluminum microchannel tubing and brazed core assemblies. Pune and Chennai industrial corridors host emerging thermal module operations serving Maruti Suzuki, Hyundai, and Tata Motors assembly plants.
Car Radiator Market Competitive Landscape
The competitive structure tilts toward diversified thermal systems conglomerates with captive aluminum processing capabilities. Tier-1 suppliers with in-house microchannel tube production control critical material inputs and capture design wins through integrated module offerings. Three archetypes dominate: full-system thermal specialists, aluminum component fabricators with backward integration into upstream materials, and diversified automotive suppliers leveraging existing OEM relationships. Consolidation pressure intensifies as capacity expansion in controlled atmosphere brazing requires capital commitments that mid-tier fabricators cannot sustain.
Among diversified thermal systems conglomerates, Denso Corporation and Modine Manufacturing Company exemplify archetypes with differentiated geographic footprints and production specializations. Valeo S.A. and MAHLE GmbH occupy positions as European-headquartered suppliers with established heavy-duty truck and passenger car module portfolios. Japanese specialists T.RAD Co., Ltd. and Koyorad Co., Ltd. represent fabricators with concentrated expertise in aluminum brazing architectures for Asian OEM platforms.
| Leading Market Players |
|---|
| Modine Manufacturing Company |
| T.RAD Co., Ltd. |
| Denso Corporation |
| Nissens A/S |
| Hanon Systems Co., Ltd. |
| Valeo S.A. |
| Marelli Holdings Co., Ltd. |
| Koyorad Co., Ltd. |
| MAHLE GmbH |
| Others |
Value Network & Pricing Analysis
Aluminum-brazing capability divergence between certified Tier-1 module integrators and legacy solder-dependent fabricators manifests in three-tier pricing stratification across premium, standard, and economy levels, with supply chain configurations clustering around controlled atmosphere brazing facilities in Germany, Japan, and China to minimize freight exposure to dense aluminum microchannel tubing.
Pricing Analysis
Margin tightening in mid-tier radiator fabrication reflects aluminum price volatility tied to energy-intensive smelting operations. Contract-based long-term offtake agreements dominate procurement between OEMs and Tier-1 suppliers, with price differentiation hinging on ISO-certified brazing quality and volume scale commitments. Aftermarket channels show greatest price sensitivity due to repair shop familiarity with copper-brass solderability, while premium EV thermal module contracts exhibit pricing softness as battery cooling integration demands engineering co-investment.
Supply Chain Analysis
Freight cost optimization drives supply chain clustering near vehicle assembly corridors in Michigan, Bavaria, and Guangdong. Raw material dependencies center on aluminum ingot from Canada and Australia, brazing flux formulations subject to ECHA REACH restrictions, and precision microchannel extrusion equipment from Japan. Single-source vulnerability concentrates in controlled atmosphere brazing furnace capacity, with distribution running through just-in-time sequencing to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car radiator market functions as a consolidation play where aluminum brazing capital intensity and dual-platform engineering overhead force mid-tier fabricators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into aluminum microchannel tubing production to capture margin erosion from volatile ingot pricing. Denso Corporation's captive tube manufacturing model offers a template for defending design-win positions against emerging Asian module suppliers. Prioritize certification investment in EPA-compliant thin-core architectures before NHTSA safety protocol revisions tighten further. For New Entrants and Emerging Players: India's PLI scheme for component manufacturing opens a window for establishing localized brazing operations serving Maruti Suzuki and Hyundai assembly plants. Target the heavy-duty commercial aftermarket in North America where copper-brass solderability sustains replacement demand and incumbent capacity concentrates on OEM programs. Pursue design-to-cost contracts with fleet operators standardizing thermal specifications across vehicle classes. For Investors and Strategic Acquirers: Re-rating potential sits with aluminum component fabricators possessing captive tube production and established OEM relationships given the convergence of battery thermal management with traditional cooling architectures. Focus acquisition screening on mid-tier suppliers with underutilized controlled atmosphere brazing capacity and geographic proximity to scaling EV production clusters. Watch aluminum price stabilization as the inflection signal for margin recovery in downstream module assembly.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microchannel Tubing | Captive supply of precision extrusions insulates Denso and Modine from aluminum price volatility. |
| Modular Cooling Pack Standardization | Bundled radiator-condenser-charge air cooler units compress supplier qualification overhead for fleet procurement. |
| Controlled Atmosphere Brazing Capacity Expansion | Specialized furnace investments in Pune and Chennai capture India's PLI-scheme automotive production growth. |
| Battery Thermal Management Convergence | Liquid-cooled pack integration redirects engineering resources from legacy engine-cooling architectures. |
| REACH-Compliant Flux Reformulation | ECHA chemical restrictions force European suppliers to redesign brazing processes for integrated cooling modules. |
Research Methodology
Multi-period observation of EPA fuel economy standard implementation, MIIT efficiency mandate progression, and aluminum price index movements anchored the trend analysis, supplemented by interviews with OEM thermal platform engineers, Tier-1 supplier procurement directors, aftermarket distributor operations heads, and controlled atmosphere brazing facility managers. Secondary validation drew from NHTSA safety protocol filings, ECHA REACH substance restriction updates, vehicle production databases, and SEC 10-K disclosures from listed thermal systems suppliers. Bottom-up segment sizing triangulated against top-down OEM program volume estimates.
Segment-weighting approaches modeled vehicle class, propulsion architecture, material specification, and regional production cluster dimensions across the projection horizon. CAGRs derived from installed base turnover analysis, content-per-vehicle trajectories for aluminum microchannel adoption, and regulatory mandate compliance timelines. Forecast inputs incorporated EPA Corporate Average Fuel Economy trajectory assumptions and China's dual carbon goal implementation pace.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management or air-cooled cell architectures would alter the outlook for liquid-cooling module demand. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailer Axle Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Sideloaders Market
Vehicle Components
HCV Axles Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
RV Battery Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Exhaust Manifolds and Downpipes Market