
 Automotive Exhaust Emission Control Device Market | 2026-2036
Automotive Exhaust Emission Control Device Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Emission Control Device Market Intelligence
The original equipment manufacturer (OEM) direct supply channel is tilting towards partnerships focused on integrated exhaust systems. This shift favors suppliers with deep system-level expertise. Faurecia leverages its scale in complete exhaust line manufacturing to secure long-term OEM contracts. Tenneco Inc. competes through its broad portfolio covering both original equipment and aftermarket segments. Johnson Matthey specializes in advanced catalyst technologies, particularly for next-generation gasoline and diesel engines.
An automotive exhaust emission control device is an after-treatment system designed to neutralize harmful pollutants from internal combustion engine exhaust. These devices often utilize a ceramic or metallic substrate coated with precious metals to catalyze chemical reactions, converting NOx, CO, and hydrocarbons into less harmful substances. Catalytic converters remain the dominant product type, especially for passenger vehicles. Diesel particulate filters and selective catalytic reduction units represent the fastest-growing segment, driven by tightening regulations for commercial trucks and off-road vehicles.
Regulatory mandates are the primary market force, with standards set by the US EPA, the EU's upcoming Euro 7 framework, and China's MEE. These regulations impose strict limits on particulate matter and nitrogen oxide emissions, compelling automakers to adopt more complex and efficient control technologies. The strategic imperative for suppliers is to balance investment in advanced ICE after-treatment systems against the long-term industry transition toward battery electric vehicles.
Market Dynamics
The central structural force shaping the market is the dual pressure on automakers to invest in advanced after-treatment systems for internal combustion engines to meet near-term regulations, while simultaneously allocating capital for the long-term industry transition to electrification.
Growth Catalysts
- Stringent Emission Mandates:The implementation of new standards, including the EU's Euro 7 framework and China's VI regulations, compels the adoption of more sophisticated and efficient emission control devices across passenger and commercial vehicles.
- Commercial Vehicle Fleet Upgrades:Demand from the commercial trucks segment is accelerating as fleet operators upgrade vehicles to comply with tightening regulations on NOx and particulate matter, particularly for diesel engines.
- Manufacturing Hub Expansion:The concentration of automotive production in emerging manufacturing clusters, especially in India and Mexico, creates localized demand for after-treatment systems as global OEMs expand their operations.
Market Restraints
- BEV Substitution Threat:The accelerating industry-wide pivot toward battery electric vehicles (BEVs) acts as a long-term structural restraint, capping the total addressable market for internal combustion engine-related components.
- Precious Metal Price Volatility:Device manufacturing depends on precious metals like platinum, palladium, and rhodium for catalytic coatings, exposing suppliers to significant input cost volatility and margin pressure.
- Performance and Cost Trade-offs:Engineering systems to meet progressively stricter emission limits without compromising engine performance, fuel efficiency, or vehicle affordability remains a persistent technical and commercial barrier.
Strategic Opportunities
- Off-Highway Vehicle Regulations:Extending advanced after-treatment technologies to non-road mobile machinery, such as agricultural and construction equipment, offers a significant growth avenue as emission standards tighten for this segment.
- System Integration with Powertrain Controls:Developing integrated solutions that combine after-treatment hardware with engine control unit (ECU) software allows for optimized performance and creates higher-value offerings for OEMs.
- Aftermarket and Retrofit Services:A substantial opportunity exists in the aftermarket for retrofitting older commercial vehicle fleets with modern emission control devices to meet evolving regional and municipal clean air mandates.
Industry Challenges
- Dual-Technology R&D Investment:Suppliers face the challenge of allocating significant R&D capital to enhance ICE after-treatment systems while simultaneously investing in technologies for future electric and hydrogen-powered vehicles.
- Accelerated Compliance Timelines:The compressed timeframe between the finalization of new emission standards and their enforcement dates puts immense pressure on suppliers' design, testing, and validation cycles.
- Supply Chain Realignment:Shifting production and logistics to support new automotive assembly plants in different geographic regions requires complex supply chain reconfiguration and investment in local capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Emission Control Device Market |
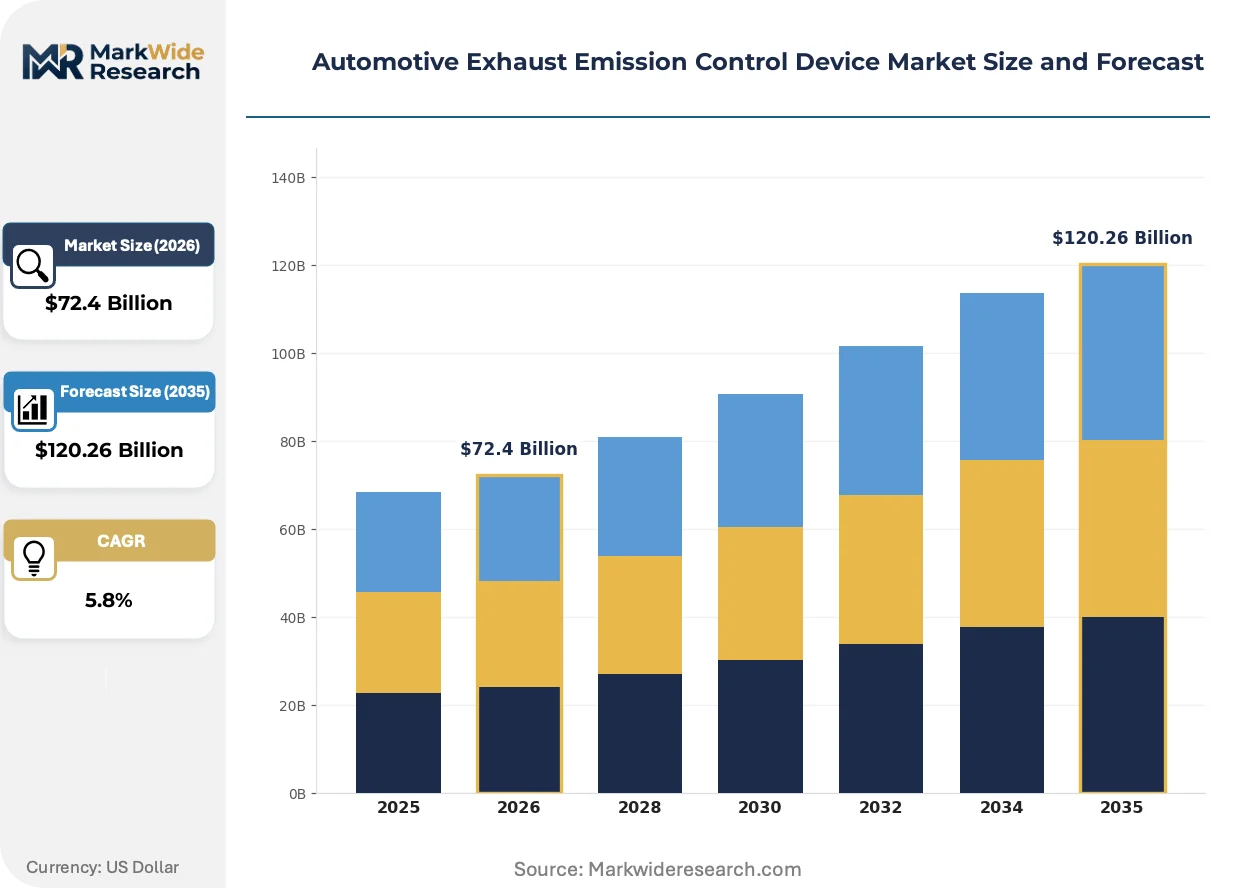
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $120.26 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catalytic Converters, Diesel Particulate Filters, Exhaust Gas Recirculation Systems, Selective Catalytic Reduction Units Technology: Ceramic, Metallic, Membrane, Nanostructured, Coated Substrates Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-Road Vehicles, Marine Engines End User: OEMs, Aftermarket Retailers, Fleet Operators, Vehicle Maintenance Providers |
| Companies Covered | Bosal, Tenneco Inc., Denso Corporation, CDTi Advanced, Faurecia, Johnson Matthey, Eberspächer, Bosch Rexroth, Continental Emitech GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Emission Control Device Market Strategic Shifts & Innovations
The market is being reshaped by the need to achieve near-zero emissions from internal combustion engines. This imperative drives innovation in catalyst chemistry, system design, and digital monitoring to ensure compliance throughout a vehicle's operational life.
Advanced onboard diagnostic systems integrated with smart sensors are gaining traction for real-time emissions monitoring. Automakers are incorporating these technologies across both passenger cars and heavy-duty trucks to ensure continuous compliance. This fusion of sensor data with powertrain management is digitizing the entire exhaust control loop, enabling predictive maintenance alerts and verifying in-use performance.
Regulatory frameworks like the US EPA's Clean Trucks Plan are creating new technology requirements. The rule's stringent limits on nitrogen oxides from heavy-duty engines are forcing the adoption of more complex after-treatment architectures, such as dual-dosing selective catalytic reduction (SCR) systems. The commercial vehicle segment is most affected, prompting significant redesigns of exhaust systems to meet the new standards.
OEMs' purchasing behavior is evolving from sourcing discrete components to procuring complete, pre-validated exhaust system modules. This trend favors large, system-level suppliers over smaller, component-focused manufacturers, as it simplifies assembly and reduces integration risk for the automaker. This procurement shift is particularly evident in the high-volume automotive manufacturing hubs of Mexico and India.
Automotive Exhaust Emission Control Device Market Segmentation
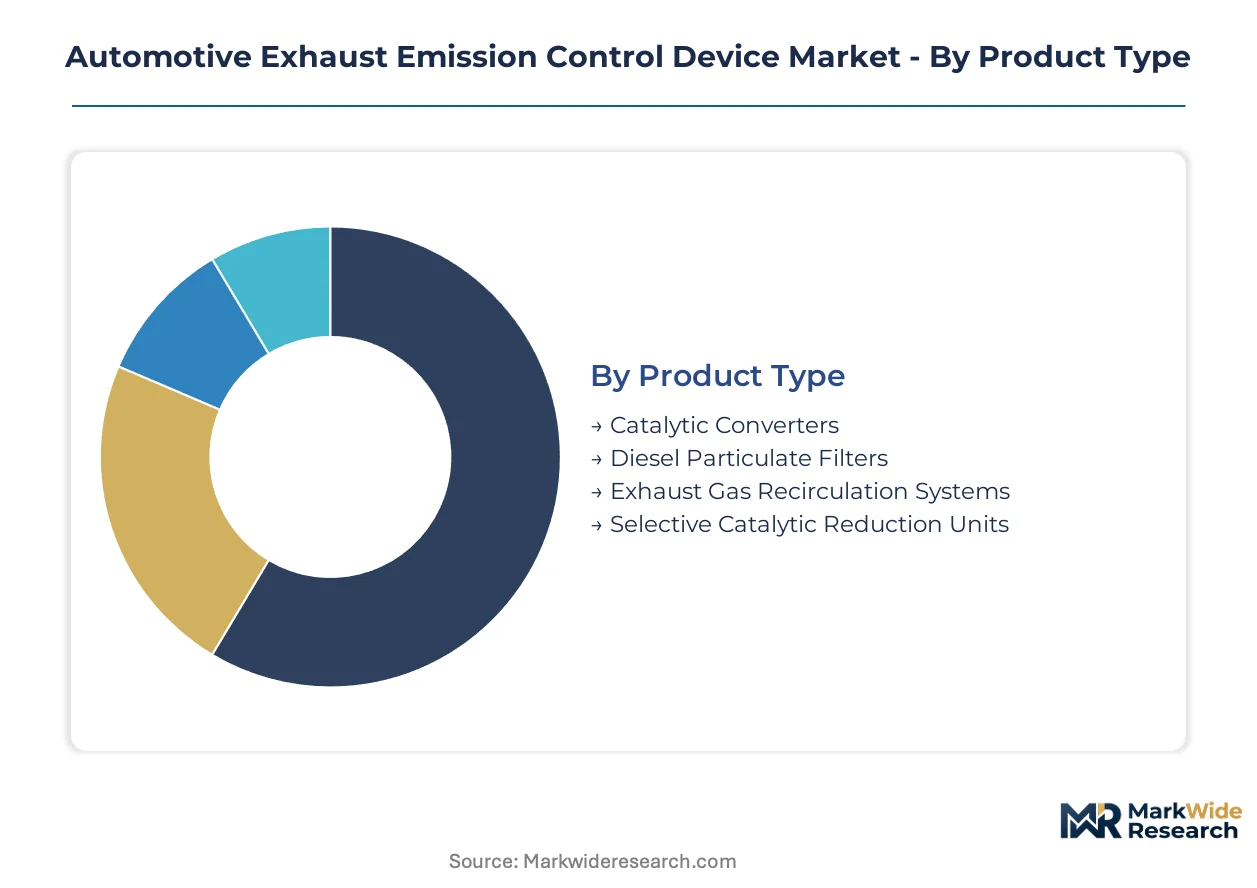
The Automotive Exhaust Emission Control Device Market segments delineate the diverse technologies, applications, and end-user demands shaping industry dynamics. Understanding these categories provides clarity on where innovation is concentrated and how regulatory pressures translate into specific product needs. Each segment reflects unique technical requirements and commercial pathways for market participants.
Product Type:
The product type segmentation reveals a spectrum from mature, established technologies to rapidly evolving solutions addressing new regulatory pressures.
- Catalytic Converters:This device utilizes a ceramic or metallic substrate coated with precious metals to convert nitrogen oxides, carbon monoxide, and hydrocarbons into less harmful substances. Demand concentrates in the passenger vehicle segment, driven by their established efficacy and widespread regulatory mandates across regions like the US EPA and Europe.
- Selective Catalytic Reduction Units:These systems inject a liquid-reductant agent, typically urea, into the exhaust stream to convert nitrogen oxides into diatomic nitrogen and water vapor. Their adoption is accelerating in commercial trucks and off-road vehicles due to stringent NOx limits imposed by regulations such as the EU's Euro 7 framework and China VI.
- Diesel Particulate Filters:Captures and stores diesel particulate matter (soot) from the exhaust gas, periodically regenerating to burn off the collected soot.
- Exhaust Gas Recirculation Systems:Reduces nitrogen oxide emissions by recirculating a portion of an engine's exhaust gas back into the engine cylinders.
Catalytic Converters handle the majority of throughput; Selective Catalytic Reduction Units are the fastest mover on share.
Technology:
Technology choices often reflect a trade-off between manufacturing cost, performance requirements, and material availability across diverse applications.
- Coated Substrates:This technology involves applying a layer of catalytic material, often containing precious metals like platinum, palladium, and rhodium, onto a structural support. It is critical across all emission control devices, with demand concentrating in advanced after-treatment systems for Euro 7 compliance.
- Nanostructured:This approach employs materials engineered at the nanoscale to enhance catalytic activity, increase surface area, and improve efficiency in converting pollutants. This advanced technology sees investment for next-generation gasoline and diesel engines, particularly for meeting ultra-low emission vehicle standards.
- Ceramic:Provides a robust and high-temperature resistant porous structure, typically a honeycomb design, serving as the substrate for catalytic coatings.
- Metallic:Offers lower thermal inertia and thinner walls compared to ceramic substrates, allowing for faster light-off temperatures and reduced pressure drop.
- Membrane:Used in some advanced separation processes for exhaust gas treatment, though less common than catalytic converters for primary pollutant reduction.
Nanostructured innovation is driving performance gains, while Ceramic substrates offer cost efficiencies.
Application:
Application segments delineate where emission control devices are deployed, ranging from high-volume personal transport to heavy-duty industrial uses.
- Commercial Trucks:This segment includes heavy-duty and medium-duty vehicles, experiencing accelerated demand for advanced after-treatment systems due to tightening regulations on NOx and particulate matter. This is particularly evident from the US EPA's Clean Trucks Plan and China VI.
- Passenger Vehicles:This category comprises cars and light commercial vehicles, representing the largest volume application for emission control devices, primarily catalytic converters. Regulatory mandates from the EU's Euro 7 framework continue to drive technology upgrades for these vehicles.
- Off-Road Vehicles:Encompasses agricultural, construction, and mining equipment, which are increasingly subject to stringent emission standards, creating new growth avenues for after-treatment technologies.
- Two-Wheelers:Includes motorcycles and scooters, where emission control devices are implemented to meet regional air quality standards, particularly in densely populated urban areas in India.
- Marine Engines:Applies to propulsion systems in boats and ships, facing evolving international and regional emission limits for NOx and sulfur oxides, necessitating specialized control solutions.
The largest volume segment is Passenger Vehicles, with Off-Road Vehicles exhibiting specialized demand.
End User:
End user dynamics reflect distinct purchasing behaviors and supply chain relationships that influence product distribution and service models.
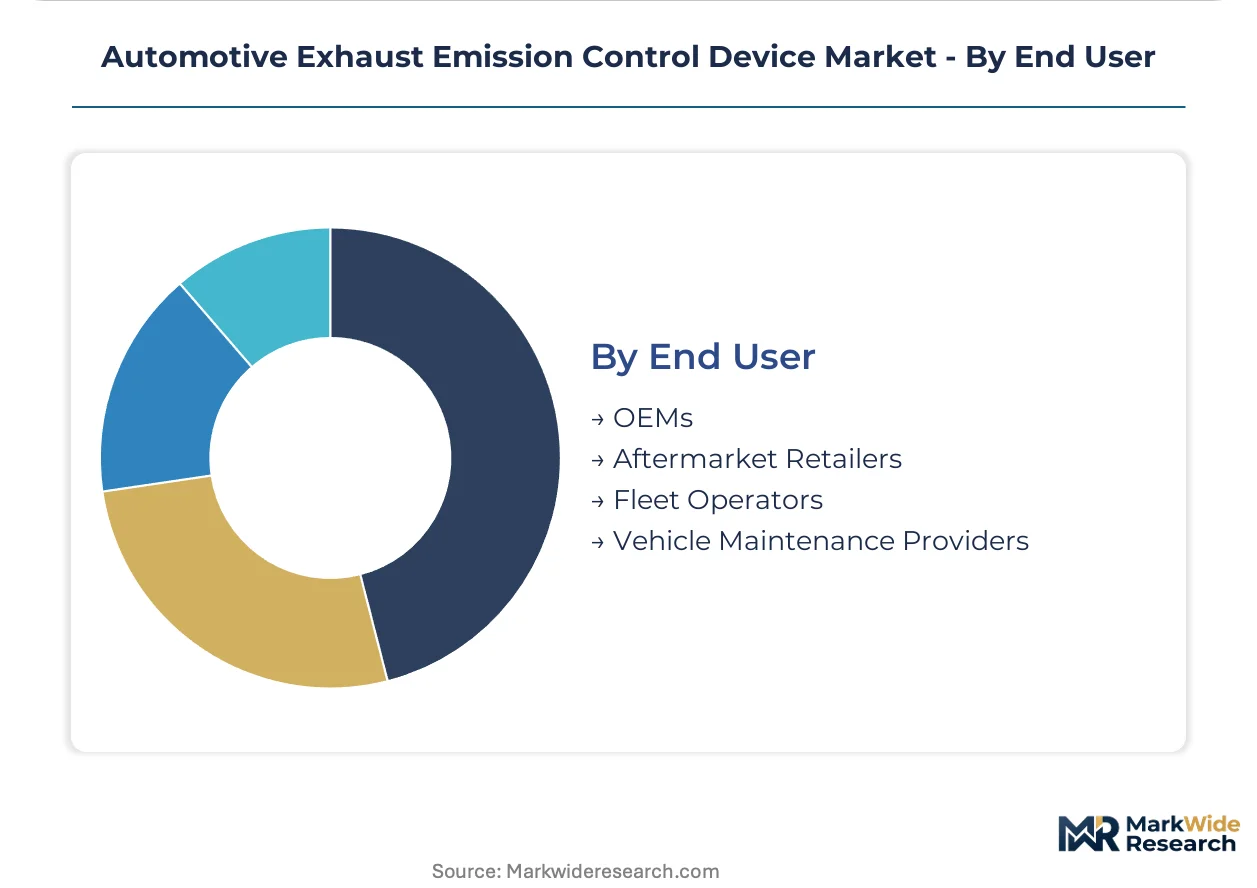
- OEMs:Original Equipment Manufacturers procure emission control devices directly for integration into new vehicle production lines. This channel increasingly seeks integrated exhaust system modules, favoring suppliers with deep system-level expertise and the ability to manage complex supply chains in manufacturing hubs like Mexico.
- Fleet Operators:These entities manage large numbers of commercial vehicles and are a significant end-user segment for both original equipment and aftermarket solutions. Their demand is driven by the need to upgrade existing fleets to comply with evolving regional and municipal clean air mandates, particularly for diesel engines.
- Aftermarket Retailers:Distributes replacement and upgrade emission control components to independent repair shops and individual consumers, catering to maintenance and repair needs for older vehicles.
- Vehicle Maintenance Providers:Includes authorized service centers and independent garages that install, maintain, and repair emission control devices, ensuring vehicles meet operational and regulatory standards.
Direct OEM engagement secures the largest market share, while Fleet Operators represent a critical aftermarket opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive manufacturing network underwrites the demand for emission control devices. This network facilitates the distribution of vehicles and components across continents. Regulatory convergence and localized production drive technology adoption in key regions.
China
China's extensive high-speed rail network connects major industrial centers, supporting the automotive supply chain. Stringent China VI regulations compel automakers to implement advanced after-treatment systems. The Yangtze River Delta region, with its automotive manufacturing hubs, concentrates demand for these sophisticated devices.
Germany
Germany's robust autobahn system ensures efficient logistics for automotive component suppliers. The EU's upcoming Euro 7 framework mandates significant reductions in vehicle emissions across the region. Bavarian automotive clusters, including Munich and Stuttgart, focus on integrating cutting-edge emission control technologies into new vehicle platforms.
India
India's developing port infrastructure supports the export and import of automotive components and finished vehicles. The country's Bharat Stage (BS) emission standards, similar to Euro norms, drive demand for catalytic converters and DPFs. The Chennai-Bengaluru industrial corridor is a hub for automotive production, attracting investment in local after-treatment system manufacturing.
Mexico
Mexico's extensive rail links facilitate cross-border trade with the United States, essential for its automotive industry. US EPA regulations, impacting vehicles exported from Mexico, necessitate advanced emission control technologies. The Bajío region, a significant automotive manufacturing cluster, sees high OEM demand for integrated exhaust system modules.
United States
The United States' vast interstate highway system is critical for the distribution of vehicles and their components. The US EPA's Clean Trucks Plan imposes strict limits on NOx emissions for heavy-duty engines. Detroit's automotive manufacturing base and surrounding areas continue to innovate in after-treatment systems for both light and heavy vehicles.
Automotive Exhaust Emission Control Device Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified players and specialized technology providers. This landscape includes vertically integrated manufacturers and niche innovators. Several strategic archetypes exist, including full-system integrators, advanced catalyst specialists, and aftermarket component suppliers. Competitive moves often involve strategic partnerships to secure long-term OEM contracts and significant investment in advanced R&D for next-generation technologies. Companies also pursue geographic expansion into emerging automotive manufacturing clusters to localize production.
Within the integrated exhaust system segment, Tenneco Inc. exemplifies a broad portfolio approach, spanning both original equipment and aftermarket solutions. Faurecia, a large-scale manufacturer, represents a system-level supplier focused on complete exhaust line solutions for global OEMs. Johnson Matthey, a UK-based company, anchors the advanced catalyst technology segment, specializing in precious metal formulations critical for next-generation gasoline and diesel engines. These firms collectively demonstrate the industry's drive toward integrated solutions and specialized material science, meeting diverse market demands from passenger vehicles to commercial trucks.
| Leading Market Players |
|---|
| Bosal |
| Tenneco Inc. |
| Denso Corporation |
| CDTi Advanced |
| Faurecia |
| Johnson Matthey |
| Eberspächer |
| Bosch Rexroth |
| Continental Emitech GmbH |
| Others |
Cost & Logistics Intelligence
Mexico's extensive rail links, critical for cross-border automotive trade, influence component cost dynamics, shaping both regional supply concentration and downstream price differentiation for after-treatment systems. This infrastructure impacts device affordability across North American manufacturing hubs.
Pricing Analysis
Contract-based long-term offtake agreements, often incorporating volume-based discounts, define the dominant pricing model for automotive emission control devices supplied to OEMs. Pricing differentiation primarily stems from the level of certification compliance, such as Euro 7 or China VI standards, and the volume scale of the order. Pricing softness reflects the dual-technology investment challenge faced by suppliers, who must fund both ICE after-treatment and electrification. Fleet operators exhibit higher price sensitivity compared to OEMs procuring critical compliance components.
Supply Chain Analysis
Export controls on advanced materials and technologies could limit the flow of specialized catalytic coatings, impacting global supply. The supply chain concentrates manufacturing in China, Mexico, and Germany, leveraging established automotive production ecosystems. Device production relies heavily on precious metals like platinum, palladium, and rhodium, making it vulnerable to commodity price volatility. OEM direct supply represents the primary distribution model, particularly for integrated exhaust system modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a critical substitution defense for internal combustion engine technology, with incumbents navigating the long-term structural threat posed by battery electric vehicles. Strategic investments are essential to prolong the viability of conventional powertrains.
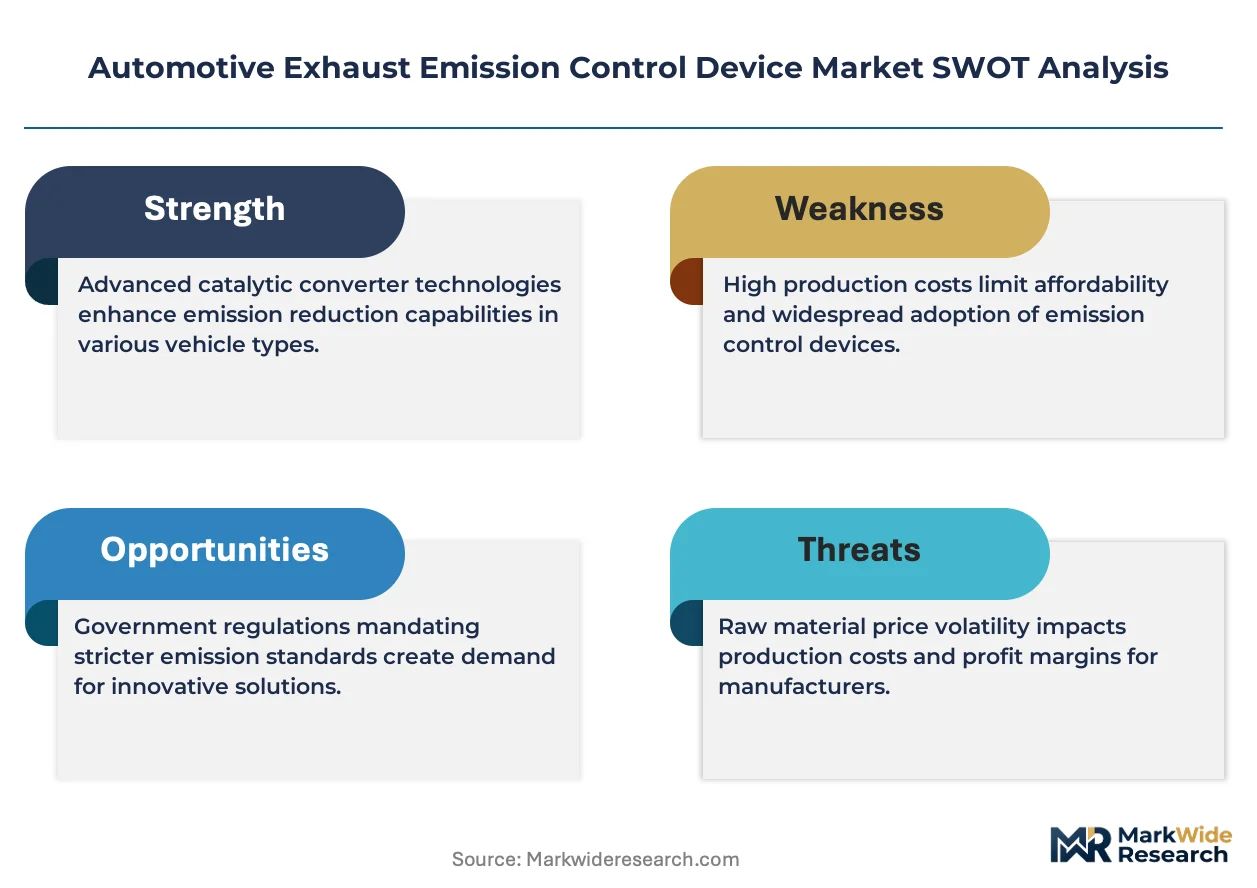
For Market Incumbents: Harden existing OEM relationships through integrated system offerings and co-development of next-generation after-treatment solutions. Prioritize investment in advanced catalyst R&D to meet ultra-low emission standards, countering the BEV substitution threat. Secure long-term contracts for precious metal supply to mitigate input cost volatility. Expand localized production capabilities in high-volume automotive manufacturing hubs like India and Mexico.
For New Entrants and Emerging Players: Establish a beachhead in niche segments, such as off-highway vehicles, where emission standards are tightening and competition is less entrenched. Focus on developing specialized retrofit solutions for older commercial vehicle fleets to meet evolving regional clean air mandates. Leverage digital monitoring and analytics for optimized performance in these underserved applications, offering a distinct value proposition.
For Investors and Strategic Acquirers: The Euro 7 framework reshapes the acquisition landscape, favoring firms with proven compliance technologies and advanced material science expertise. Long-term viability hinges on a balanced portfolio addressing both advanced ICE after-treatment and future electric vehicle components. Target specialized catalyst manufacturers or system integrators with strong OEM ties. The pace of commercial truck BEV adoption serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| System Integration with Powertrain Controls | Automakers gain optimized performance and higher-value offerings through combined hardware and software solutions. |
| Advanced Catalyst R&D | Suppliers meet stringent Euro 7 and China VI regulations for next-generation gasoline and diesel engines. |
| Geographic Manufacturing Expansion | Localizing production in India and Mexico supports global OEM assembly plants and reduces logistics costs. |
| Aftermarket Retrofit Solutions | Fleet operators achieve compliance for older commercial vehicles, extending their operational lifespan under new mandates. |
| Dual-Technology Investment | Companies balance capital allocation between enhancing ICE after-treatment and developing solutions for electric vehicles. |
Research Approach
The analysis maps key sub-sectors, including catalytic converters, SCR units, and DPFs, each validated through extensive primary interviews with OEM procurement leads, Tier 1 R&D directors, and fleet operators. Secondary validation draws from government emission reports, automotive industry association data, and company financial filings. This approach employs both bottom-up market sizing and top-down market share analysis.
Assumptions regarding regulatory timelines and vehicle production volumes were held fixed across the analysis window, while technological adoption rates were varied. The analytical framework incorporates segmentation by product type, technology, application, end user, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends and projected impacts of new emission standards, with vehicle electrification forecasts as a key input.
Stress conditions across precious metal price volatility and global vehicle sales were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement and technological progression. Material shifts in global economic growth or BEV adoption pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Australia Automotive Composites Market