
 Automotive Catalyst Market | 2026-2036
Automotive Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Catalyst Market Intelligence
The customer base for automotive catalysts is broadening beyond traditional passenger vehicle OEMs to include specialized manufacturers of commercial and agricultural machinery. BASF SE leverages its extensive chemical production scale to serve these diverse vehicle segments. Johnson Matthey sustains its market position through deep R&D in platinum group metal (PGM) chemistry. Umicore competes on the basis of its closed-loop material recycling capabilities, which addresses PGM scarcity and circular economy demands.
An automotive catalyst is a device that converts toxic gases from engine exhaust into less harmful substances. It typically utilizes a ceramic substrate coated with a washcoat containing platinum group metals like platinum, palladium, and rhodium. Three-Way Catalysts designed for gasoline engines remain the dominant product type by volume. The passenger vehicles application constitutes the largest market, while catalysts for commercial vehicles represent a high-margin niche due to more complex aftertreatment system requirements.
Emissions regulations from bodies like the US EPA and China's Ministry of Ecology and Environment (MEE) directly mandate the use and performance of catalysts. Frameworks such as the EU Green Deal are pushing for lower pollutant limits, compelling innovation in catalyst efficiency. Suppliers must now decide whether to focus on optimizing PGM-based systems for stricter internal combustion engine rules or pivot R&D toward solutions for hybrid vehicles.
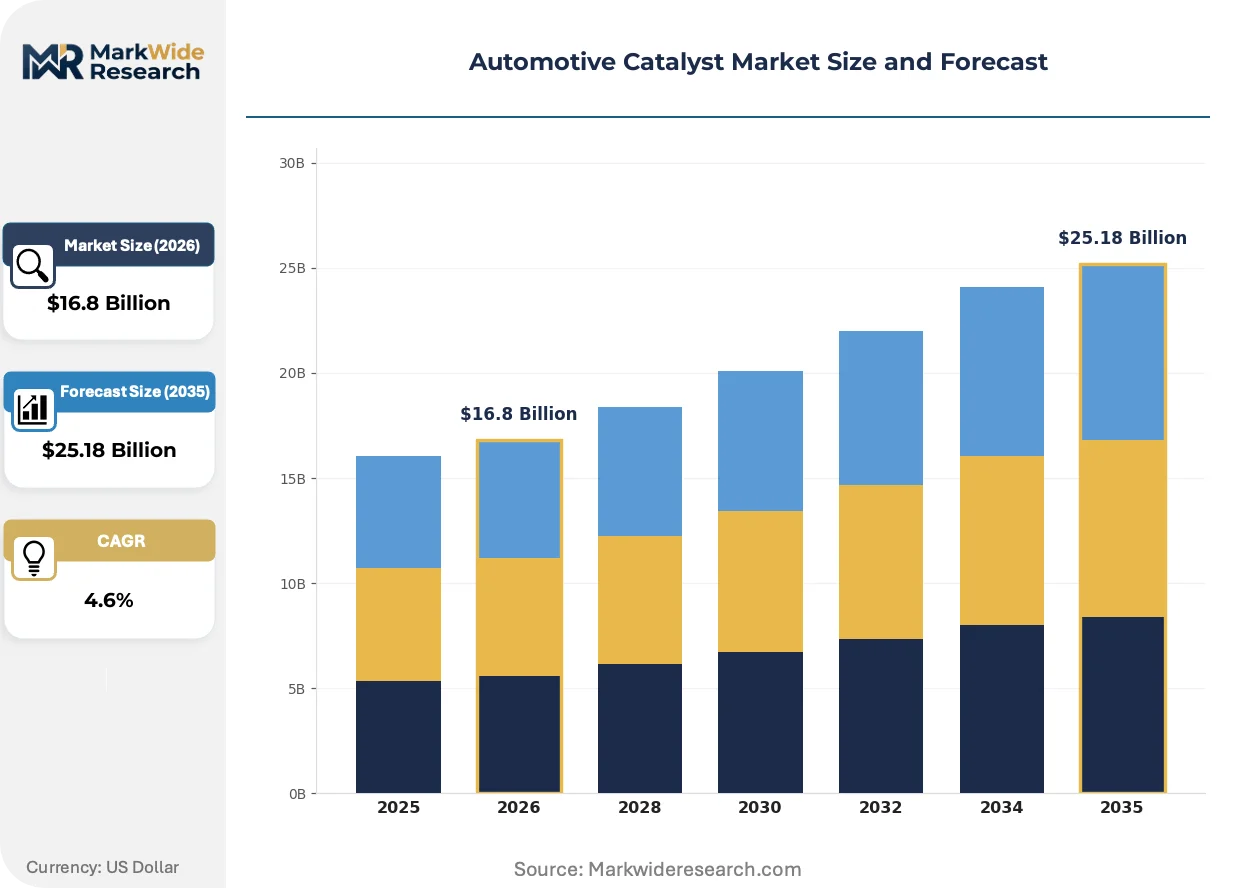
Market Dynamics
The automotive catalyst market is defined by the dual pressures of tightening emissions regulations for internal combustion engines and the long-term strategic pivot towards vehicle electrification. This dynamic forces suppliers to invest in near-term PGM-based catalyst optimization while planning for a future with reduced ICE volume.
Growth Catalysts
- Stricter Emissions Mandates:Regulations such as China's GB standards and India's BS-VI norms compel the adoption of more sophisticated and higher-value catalysts to meet lower pollutant limits for NOx and particulate matter.
- Commercial Vehicle Segment:Demand from heavy-duty trucks and buses is expanding, as these vehicles require complex and robust aftertreatment systems, including SCR and diesel particulate filters, to comply with global emissions rules.
- Closed-Loop Recycling:The push for a circular economy and the high cost of PGMs are driving investment in advanced recycling technologies, creating a secondary supply source and a new service-based revenue stream for catalyst manufacturers.
Market Restraints
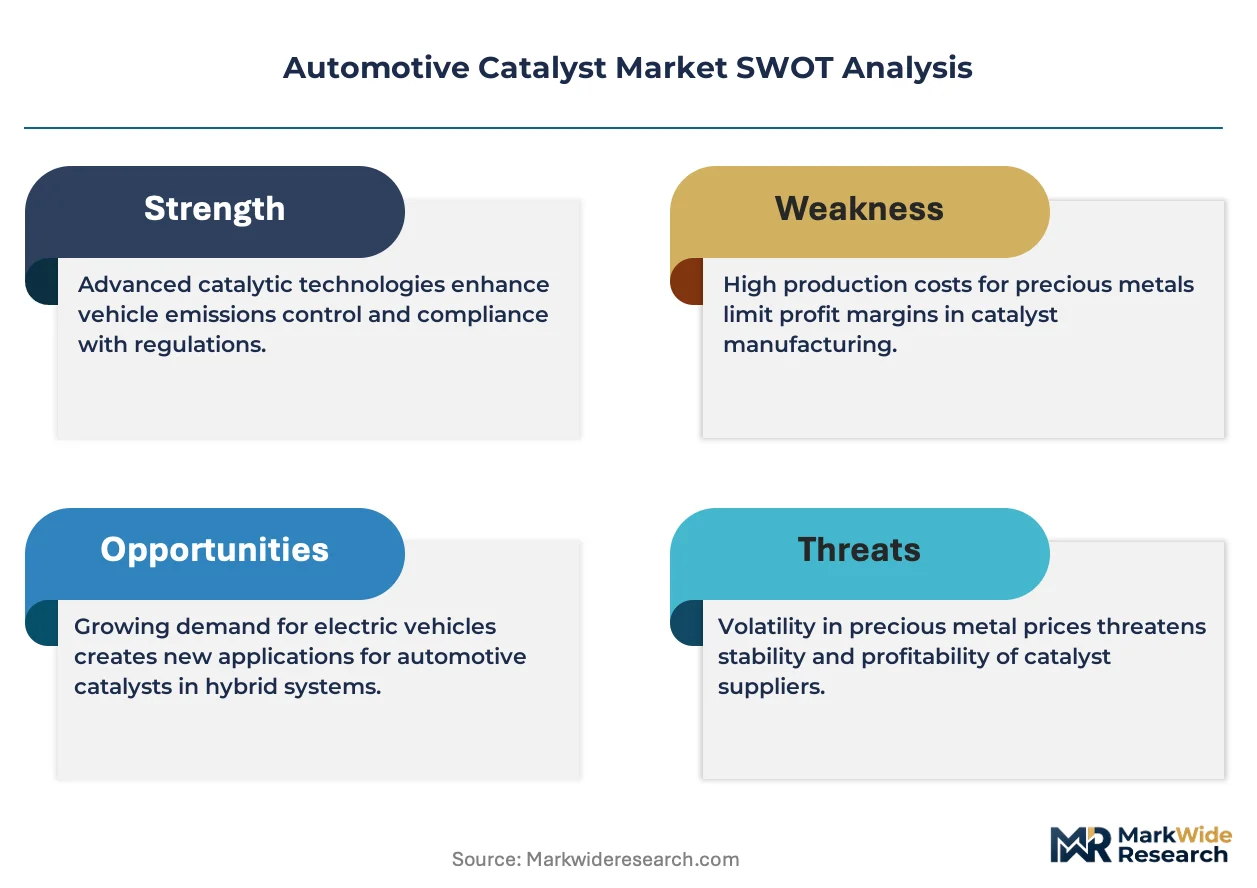
- PGM Price Volatility:The market is highly exposed to the price fluctuations and supply concentrations of platinum group metals like rhodium and palladium, which are essential active materials and subject to geopolitical supply risks.
- BEV Substitution Threat:The accelerating transition to battery electric vehicles (BEVs) represents a fundamental long-term restraint, as these vehicles have no exhaust system and therefore eliminate the need for catalysts.
- Technical Performance Limits:Existing catalysts exhibit reduced efficiency during engine cold-start phases, a performance gap known as "light-off" time that is becoming a key target for new regulatory frameworks like the proposed Euro 7 standards.
Strategic Opportunities
- Hybrid Vehicle Systems:Catalysts designed for hybrid electric vehicles (HEVs) present an opportunity, as their unique engine operating cycles require specialized formulations to maintain efficiency during frequent engine on-off transitions.
- Non-Road Mobile Machinery:Expanding emissions regulations to cover agricultural, construction, and mining equipment in regions like Europe and North America opens a new and growing application segment for diesel oxidation catalysts and SCR systems.
- Alternative Fuel Catalysts:The development of catalysts for engines running on alternative fuels like hydrogen, ammonia, or synthetic e-fuels provides a pathway for innovation and market entry beyond traditional gasoline and diesel applications.
Industry Challenges
- High R&D and Capex Burden:Suppliers face significant capital expenditure to develop and validate new catalyst formulations that meet evolving standards from bodies like the US EPA while simultaneously investing in non-catalyst technologies.
- Complex Validation Cycles:Bringing a new catalyst system to market involves lengthy and costly validation and certification processes with both OEMs and regulatory agencies, slowing the pace of innovation deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Catalyst Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Way Catalysts, Diesel Oxidation Catalysts, Lean NOx Traps, Soot Filters Technology: Ceramic Substrate, Metallic Substrate, Coated Supports, Monolithic Catalysts Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Replacement Service Providers |
| Companies Covered | BASF SE, Johnson Matthey, Umicore, Cataler Corporation, Forvia SE, Clariant International, Corning Incorporated, Heraeus Holding, Tenneco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Catalyst Market Strategic Shifts & Innovations
A fundamental re-evaluation of material science is underway. Catalyst development is splitting into two distinct paths: maximizing the efficiency of scarce platinum group metals for the final generation of combustion engines and exploring novel, lower-cost materials for hybrid and alternative fuel applications.
Advanced Substrate and Washcoat Design
New catalyst designs feature increasingly complex washcoat layers and substrate structures to maximize the active surface area while minimizing the use of expensive PGMs. Commercial vehicle and premium passenger car OEMs are the primary adopters of these high-performance solutions. This innovation is modularizing the catalyst system, enabling suppliers to tailor specific catalyst bricks to different engine platforms and regional emissions requirements without complete system redesigns.
Broadening Regulatory Scope
The European Green Deal, through its proposed Euro 7 standards, exemplifies a significant regulatory expansion. It aims to regulate previously unmonitored pollutants like ammonia from SCR systems and non-exhaust particulates from brakes and tires, impacting vehicle design far beyond the engine. This shift most directly affects passenger cars sold in the European Union, compelling a holistic approach to pollution control that integrates catalyst performance with other vehicle systems.
Sourcing Model Consolidation
A shift is occurring where automotive OEMs increasingly prefer to source complete, pre-validated aftertreatment modules rather than individual catalyst components. This trend favors large, integrated Tier 1 suppliers who can offer a full system engineering and validation service, disrupting the business model for smaller, specialized component manufacturers. This pattern is particularly evident in North America and Europe, where platform consolidation by major automakers makes standardized, modular sourcing more efficient.
Automotive Catalyst Market Segmentation
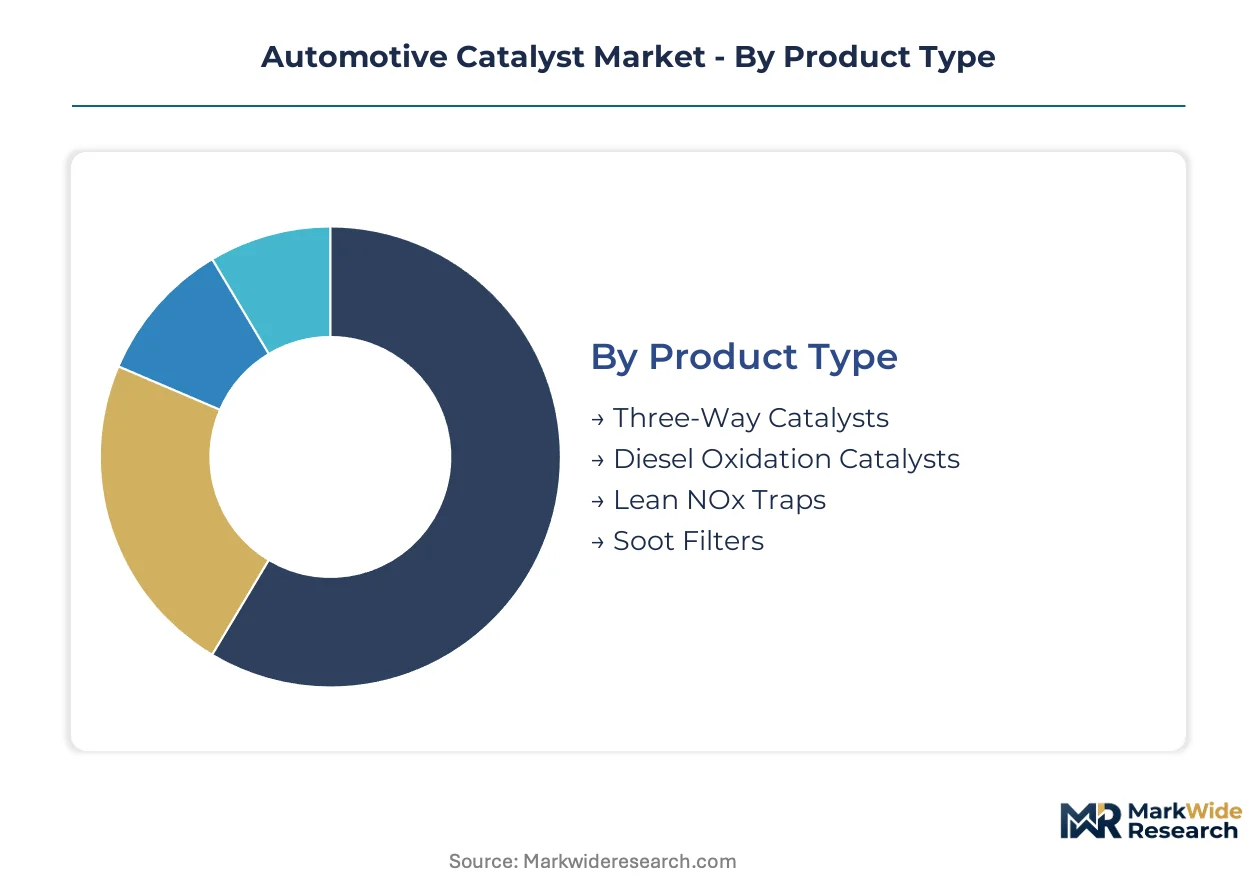
The automotive catalyst market segments across distinct product types, underlying technologies, diverse applications, and varied end-user categories. Understanding these segments is critical for manufacturers to align product development with evolving regulatory landscapes and specific vehicle demands.
Product Type:
Developing advanced catalyst formulations often requires substantial upfront investment in material science and engineering, defining the entry barriers for specific product types.
- Three-Way Catalysts:These devices convert carbon monoxide, unburnt hydrocarbons, and nitrogen oxides into less harmful substances simultaneously, primarily used in gasoline engines. Demand is concentrated in global passenger vehicle markets, driven by stringent emissions standards like Euro 7 and China's GB standards.
- Diesel Oxidation Catalysts:These catalysts oxidize carbon monoxide and hydrocarbons in diesel exhaust, playing a crucial role in reducing particulate matter precursors. Their adoption is expanding rapidly in commercial vehicles and heavy-duty machinery across North America and Europe due to robust emissions regulations.
- Lean NOx Traps:Designed for lean-burn gasoline and diesel engines, these systems store NOx during lean operation and release it for reduction during brief rich phases. Their use is specific to certain engine architectures aiming for advanced NOx control.
- Soot Filters:These are specialized filters, often combined with catalytic coatings, designed to trap and periodically regenerate accumulated particulate matter from diesel engine exhaust. They are mandated for most new diesel vehicles in regulated markets.
Most installed capacity flows through Three-Way Catalysts. Expansion is steepest in Diesel Oxidation Catalysts.
Technology:
Catalyst technologies differentiate based on their operational stability and efficiency across diverse engine environments.
- Ceramic Substrate:Characterized by a honeycomb structure made from materials like cordierite, offering high surface area, low thermal expansion, and cost-effectiveness. This technology is widely adopted in passenger vehicles across Asia-Pacific for its balance of performance and manufacturing efficiency.
- Metallic Substrate:Composed of thin metallic foils, providing superior durability, higher thermal conductivity, and reduced pressure drop compared to ceramic alternatives. Its application is growing in premium passenger cars and heavy-duty commercial vehicles in Europe, where robust performance under extreme conditions is critical.
- Coated Supports:These involve applying a washcoat, containing active catalytic materials like platinum group metals, onto the substrate surface to maximize reactive sites. This process is fundamental to the performance of all modern automotive catalysts.
- Monolithic Catalysts:This term refers to the complete, integrated catalyst unit, typically featuring a single, continuous structure with numerous parallel channels. Their design optimizes gas flow and contact with the catalytic washcoat for efficient conversion.
Cost-effectiveness drives procurement in Ceramic Substrate technologies, while performance demands elevate Metallic Substrate adoption.
Application:
The market's revenue streams are significantly shaped by the volume requirements and specific regulatory demands of various vehicle applications.
- Passenger Vehicles:This segment includes cars, SUVs, and light-duty trucks, representing the largest volume demand for automotive catalysts, predominantly Three-Way Catalysts. Stricter emissions standards like the proposed Euro 7 in the EU are compelling continuous innovation in this segment.
- Commercial Vehicles:Comprising heavy-duty trucks, buses, and vans, this application segment demands robust and complex aftertreatment systems, including SCR and DPFs, due to higher engine loads and longer operating hours. Regulations such as India's BS-VI norms drive significant investment here.
- Construction Equipment:This category covers off-road machinery like excavators and loaders, which increasingly require advanced emissions control systems to operate in regulated zones. Specific regulations in North America and Europe are driving catalyst integration for these powerful engines.
- Agricultural Machinery:Tractors and other farm equipment are also subject to expanding emissions regulations, particularly for NOx and particulate matter, necessitating durable catalyst solutions. This segment is gaining share most rapidly in regions implementing new off-road emissions controls.
Regulatory stringency is highest for Passenger Vehicles, while Commercial Vehicles present the most specialized engineering challenges.
End User:
Supply chain dynamics vary significantly across end-user segments, reflecting different procurement models and integration levels.
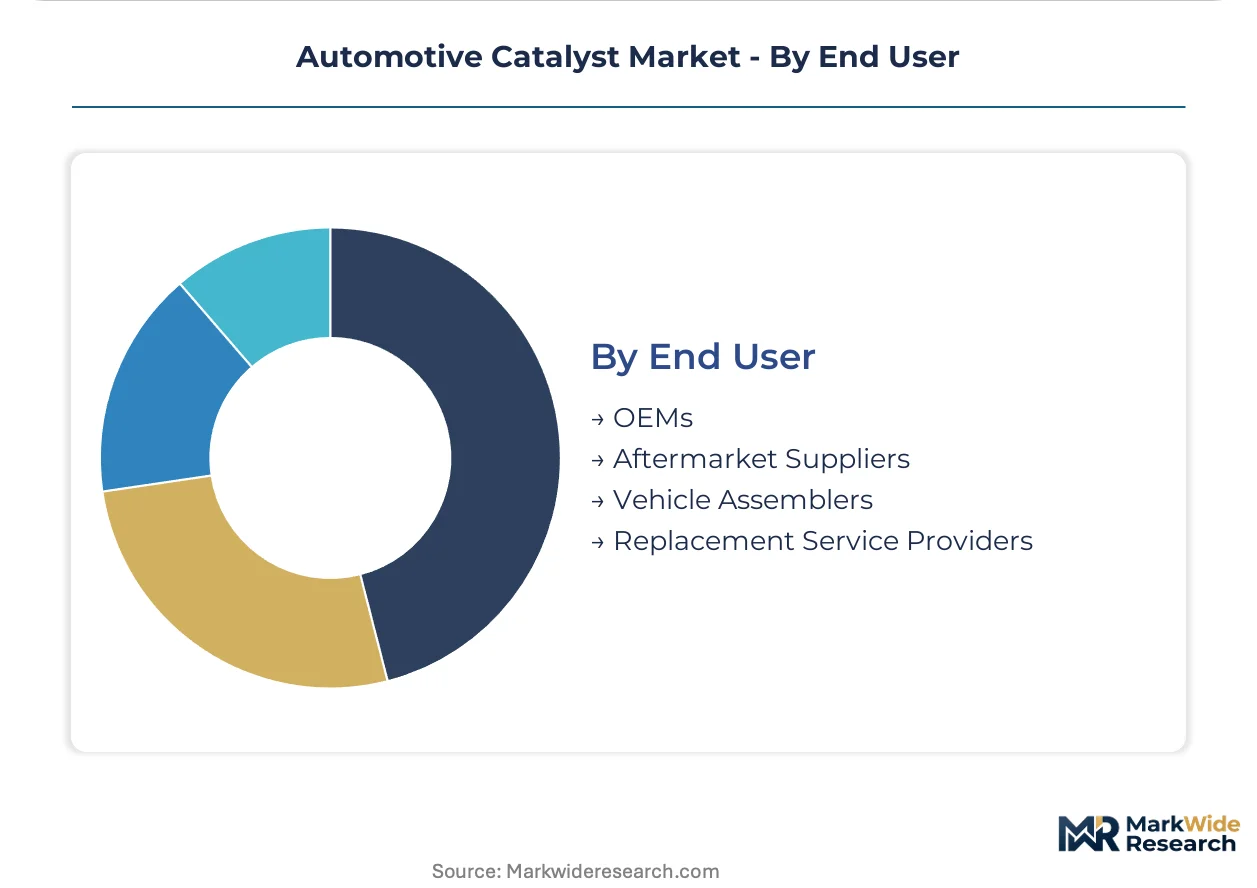
- OEMs:Original Equipment Manufacturers are the primary buyers, integrating catalysts into new vehicles during the manufacturing process. Their procurement involves lengthy validation cycles and deep technical collaboration with catalyst suppliers.
- Aftermarket Suppliers:These companies provide replacement catalyst units for vehicles already in operation, catering to a diverse range of models and ages. Their business model relies on efficient distribution and competitive pricing for maintenance and repair.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, often sourcing pre-assembled modules and components from various suppliers. Their role emphasizes integration and adherence to design specifications.
- Replacement Service Providers:This segment includes garages, dealerships, and independent repair shops that install replacement catalysts for vehicle owners. Their operations are localized and driven by consumer demand for repairs and compliance.
Long-term relationships characterize engagement with OEMs, whereas Aftermarket Suppliers rely on broad distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's stringent GB standards drive significant demand for advanced catalyst systems, the United States market balances robust environmental regulations from the US EPA with a diverse vehicle fleet. Each region presents unique challenges and opportunities for catalyst manufacturers navigating global emissions targets.
China
Demand for automotive catalysts in China is propelled by the rapid adoption of China's GB standards, which align with global best practices for emissions control. The country's dual carbon goals also push for cleaner internal combustion engine (ICE) technologies, even amid electrification. Manufacturing hubs in Shanghai and Guangdong concentrate significant production capacity and R&D for catalyst integration.
United States
The United States market for automotive catalysts is shaped by regulations from the US EPA, mandating the performance of three-way catalysts and diesel aftertreatment systems. Demand stems from both passenger vehicles and a growing commercial fleet requiring robust solutions. Automotive production centers in Michigan and the Southeast continue to integrate advanced catalyst technologies into new vehicle platforms.
Germany
Germany's automotive catalyst sector benefits from a strong premium passenger vehicle market and the strictures of the EU Green Deal and proposed Euro 7 standards. These regulations compel innovation in catalyst efficiency and the reduction of previously unregulated pollutants. Major automotive manufacturing regions like Bavaria and Baden-Württemberg are centers for catalyst R&D and advanced system integration.
India
India's automotive catalyst market experiences substantial growth due to the nationwide implementation of BS-VI norms for both passenger and commercial vehicles. This regulatory push requires sophisticated diesel oxidation catalysts and SCR systems, especially for heavy-duty applications. Production clusters in Chennai and Pune are expanding their capabilities to meet the escalating demand for emission control components.
Japan
Japan maintains a high demand for automotive catalysts, driven by its own stringent domestic emissions standards and a focus on fuel efficiency in its large passenger vehicle market. The country's commitment to hybrid vehicle technologies creates specific requirements for catalysts optimized for frequent engine start-stop cycles. Major industrial areas around Tokyo and Nagoya host significant R&D and manufacturing facilities for catalyst innovation.
Automotive Catalyst Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the automotive catalyst market. The industry structure features a blend of large chemical and materials companies alongside specialized PGM processors and recycling firms. Strategic archetypes include integrated chemical producers, precious metal refiners, and dedicated aftertreatment system suppliers. Companies primarily engage in extensive R&D investment and strategic partnerships to meet evolving regulatory demands.
Among firms anchoring advanced material science, BASF SE leverages its extensive chemical production scale to serve diverse vehicle segments. Johnson Matthey sustains its market position through deep R&D in platinum group metal chemistry, essential for high-performance catalysts. Umicore competes on the basis of its closed-loop material recycling capabilities, addressing PGM scarcity and circular economy demands within the industry.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey |
| Umicore |
| Cataler Corporation |
| Forvia SE |
| Clariant International |
| Corning Incorporated |
| Heraeus Holding |
| Tenneco Inc. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal, with its stringent emissions targets, gates both qualified catalyst supply and premium-tier pricing access for advanced aftertreatment systems. This mandate necessitates significant R&D investment and complex validation processes for manufacturers.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard catalyst components, particularly for high-volume passenger vehicle applications. The dominant pricing structure for original equipment manufacturers is contract-based long-term offtake, ensuring supply stability for new vehicle platforms. Price differentiation stems from PGM content optimization and specific regulatory certification levels, such as Euro 7 compliance. Pricing softness for basic catalysts reflects the increasing efficiency in manufacturing, while specialized aftertreatment systems maintain higher margins. Aftermarket suppliers remain highly price-sensitive, balancing cost with performance for replacement units.
Supply Chain Analysis
Single-source vulnerability sits with platinum group metal (PGM) suppliers, particularly for rhodium and palladium, which are concentrated in regions like South Africa and Russia. The automotive catalyst supply chain draws from these critical raw materials, along with ceramic and metallic substrates. Geopolitical supply risks for PGMs represent a significant structural risk for catalyst manufacturers. Distribution runs through integrated Tier 1 suppliers who deliver complete aftertreatment modules to OEMs, while replacement units for the aftermarket utilize broad, localized distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive catalyst market presents a margin-expansion story, driven by the increasing complexity and value of catalysts required to meet tightening global emissions standards.
For Market Incumbents: Deploy advanced material science R&D to optimize PGM usage and explore alternative catalytic materials. This move helps mitigate the threat of PGM price volatility while addressing the long-term strategic pivot towards electrification. Deepen collaboration with major OEMs to co-develop integrated aftertreatment modules, securing design-in wins for future vehicle platforms and leveraging existing validation expertise.
For New Entrants and Emerging Players: Euro 7 standards in Europe open a window for innovative solutions targeting previously unregulated pollutants like ammonia from SCR systems. Target niche applications such as non-road mobile machinery or specialized hybrid vehicle catalysts, where performance demands are high and established solutions may not be fully optimized. A focused go-to-market angle could involve partnering with smaller, specialized engine manufacturers or alternative fuel vehicle developers.
For Investors and Strategic Acquirers: Roll-up economics work for specialized material science firms because of the high R&D burden and lengthy validation cycles required for new catalyst technologies. The long-term viability of the segment remains strong, particularly for commercial vehicles and hybrid powertrains over the next decade. Acquisition targets should include companies with proprietary PGM-reduction technologies or advanced closed-loop recycling capabilities. The signal to watch is the pace of regulatory adoption for alternative fuel emissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in PGM-reduction R&D | Reduces reliance on volatile platinum group metal supply, improving cost stability for manufacturers. |
| Expand closed-loop recycling capabilities | Addresses PGM scarcity and circular economy demands, creating new revenue streams for Umicore. |
| Develop catalysts for alternative fuels | Captures emerging market opportunities in hydrogen and ammonia engines, diversifying product portfolios. |
| Strengthen OEM integration partnerships | Secures long-term supply contracts and design-in positions for complex aftertreatment systems. |
| Target non-road mobile machinery segment | Leverages expanding emissions regulations in agricultural and construction equipment for new applications. |
Research Approach
Coverage spans China, United States, Germany, India, and Japan, with primary inputs from each region informing the market analysis. This approach combines in-depth primary interviews with OEM platform engineers, Tier 1 aftertreatment system procurement leads, PGM refiners, and regulatory affairs specialists. Secondary validation leverages sources including US EPA reports, EU Green Deal documents, China's MEE publications, and relevant industry association reports from bodies like ACEA and JAMA. Bottom-up and top-down triangulation ensures data consistency and accuracy.
The forecast framework modeled market dimensions at a granular level across product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical data analysis and projected market dynamics over the projection horizon. Key industry-specific forecast inputs include platinum group metal price trends and the anticipated adoption rates of battery electric vehicles, influencing future catalyst demand.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme PGM price shocks or accelerated BEV transition. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements within the automotive industry. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Automotive Key Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market