
 Submarine Propulsion Systems Market | 2026-2036
Submarine Propulsion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Propulsion Systems Market Analytics
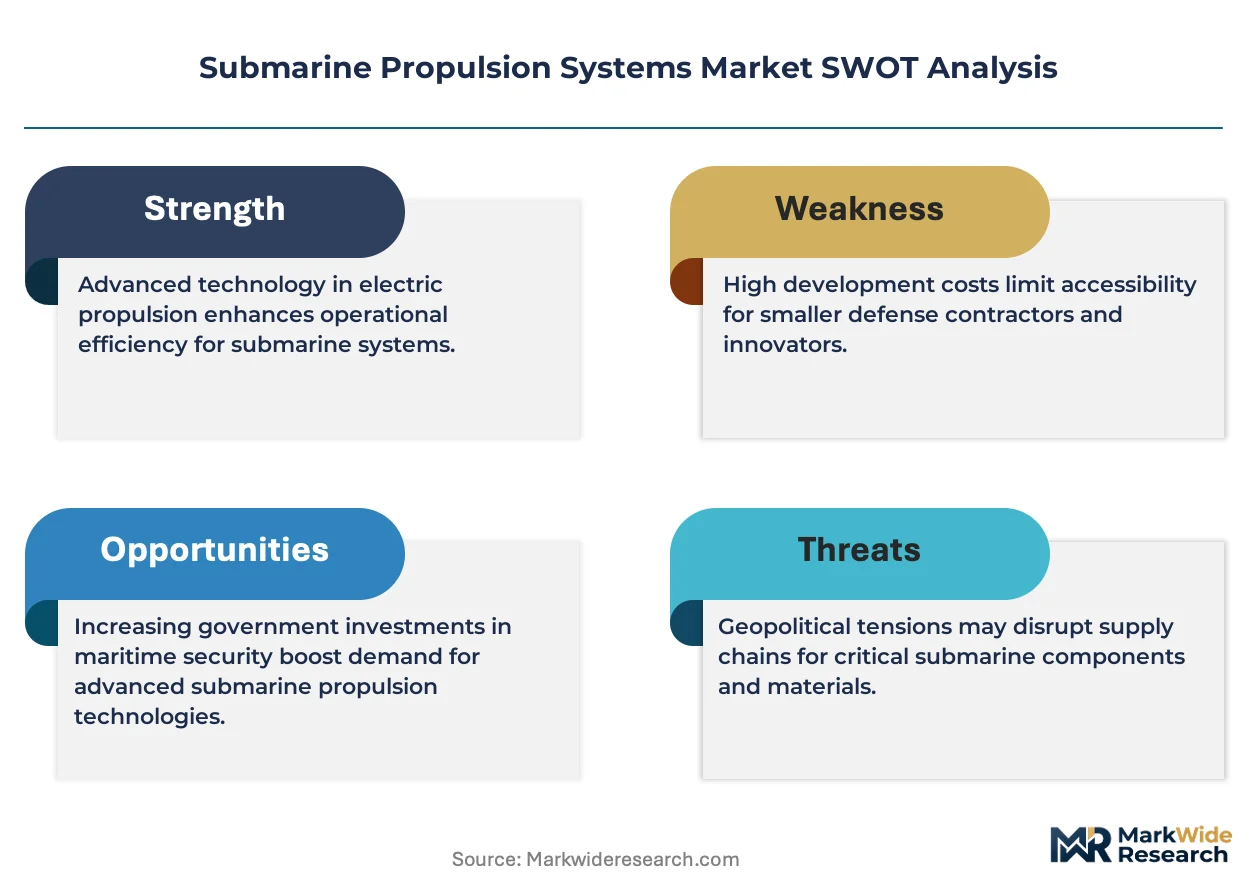
Defence export credit and sovereign-backed leasing is tilting procurement economics toward state-supported champions rather than purely commercial vendors. Rolls Royce plc leverages its nuclear reactor heritage to anchor long-term reactor-through-life contracts with British and Australian operators. Siemens AG competes on integrated electric drive architectures that reduce acoustic signatures across European and Asian platforms. Naval Group sustains its position through captive design-to-build control over entire propulsion chains for French and export programs.
Submarine propulsion systems encompass the integrated machinery—nuclear reactors, diesel generators, battery banks, fuel cells, motors, and waterjets—that generates and transmits thrust for submerged and surface transit. These systems must deliver sustained power output while minimizing radiated noise, thermal signatures, and atmospheric exhaust to preserve stealth. Nuclear power sources dominate strategic deterrent platforms where unlimited submerged endurance justifies reactor complexity and cost. Air-independent propulsion and fuel cell segments are expanding fastest among non-nuclear navies seeking diesel-submarine range without snorkel exposure. Conventional diesel-electric systems retain volume in cost-constrained fleets where battery energy density improvements extend submerged operating hours.
The US Navy's Naval Reactors program, the UK Ministry of Defence's Submarine Delivery Agency, and Australia's nuclear-powered submarine task force under AUKUS are reshaping certification requirements and technology transfer rules for reactor-grade propulsion. These frameworks restrict market access to pre-qualified suppliers and mandate decade-long support commitments that lock out new entrants. Stakeholders must monitor how regulatory alignment across Washington, London, and Canberra reshapes supplier eligibility and intellectual property boundaries for next-generation platforms.
Market Dynamics
The submarine propulsion systems market pivots on the AUKUS security pact, which mandates nuclear reactor technology transfer from the US and UK to Australia while erecting decade-long certification barriers that freeze out non-aligned suppliers.
Growth Catalysts
- Fuel cell technology maturation:Proton-exchange membrane fuel cells are extending submerged endurance for diesel-electric submarines, eliminating snorkel exposure that compromises stealth during battery recharge cycles.
- AUKUS framework activation:The trilateral pact is accelerating reactor-grade propulsion demand across Royal Australian Navy procurement, with flow-on certification alignment pressure affecting UK and US supplier pipelines.
- Indo-Pacific maritime doctrine tightening:South Korea, India, and Australia are expanding submarine fleet targets under territorial water security mandates, concentrating demand for air-independent propulsion systems.
Market Restraints
- Reactor-grade steel supply concentration:Specialized forgings for pressure hulls and reactor vessels source from a shrinking base of qualified foundries in the US, UK, and France, creating single-source vulnerability.
- Naval Reactors certification timeline:The US Navy's rigorous reactor qualification protocol extends development cycles to 15-20 years, blocking rapid technology iteration for non-nuclear propulsion alternatives.
- Lithium-ion battery thermal runaway risk:High-energy density battery banks for conventional submarines face operational safety constraints that limit charge rates and depth ratings compared to fuel cell alternatives.
Strategic Opportunities
- Indian indigenous submarine construction:The Indian Navy's Project 75I program invites foreign technology partnerships for air-independent propulsion integration into domestically built hulls, opening design-to-build contracts.
- Modular propulsion architecture:Containerized fuel cell and battery modules are enabling mid-life propulsion system upgrades without full hull reconstruction, extending platform service life for aging European fleets.
- EU Green Deal industrial alignment:European defense procurement directives are favoring hydrogen fuel cell propulsion pathways that dual-use civilian marine technology, reducing dedicated military R&D burden.
Industry Challenges
- Nuclear reactor operator certification scarcity:The US Navy's Naval Nuclear Propulsion Information program restricts reactor design knowledge to cleared personnel pools, creating talent bottlenecks for AUKUS expansion.
- Legacy diesel-electric platform integration:Retrofitting air-independent propulsion into existing hulls requires structural reinforcement and ballast recalculation that extends dry-dock time and cost.
- Reactor-through-life contract margin compression:Sovereign customers are demanding fixed-price support spanning 30-year platform lifecycles, transferring operational risk to propulsion system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Propulsion Systems Market |
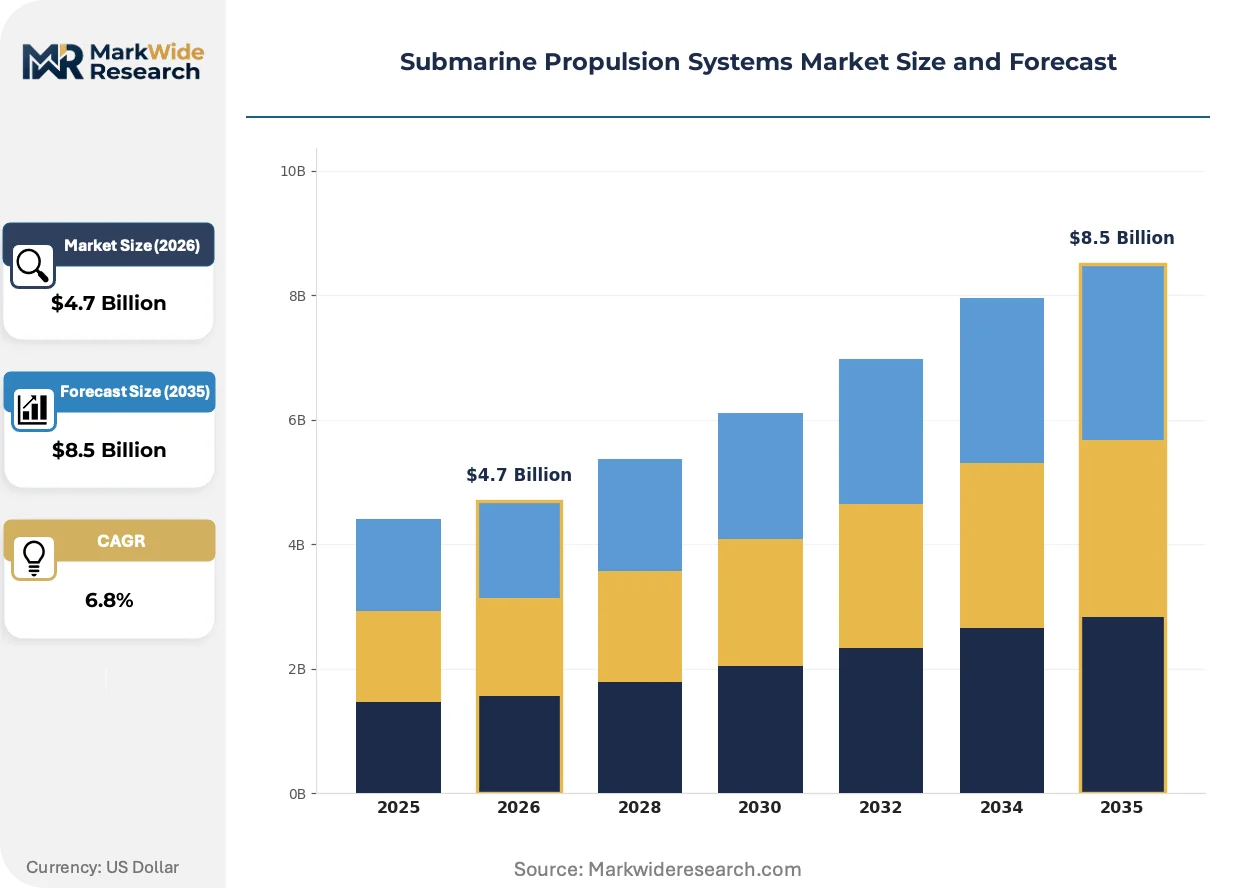
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Nuclear, Diesel-Electric, Battery, Fuel Cell System Type: Conventional, Air-Independent, Hybrid, Integrated End User: Naval Forces, Defense Contractors, Research Institutions, Commercial Operators Technology: Propeller Drive, Pump-Jet, Magnetohydrodynamics, Electric Drive |
| Companies Covered | Rolls Royce plc, Naval Group, Siemens AG, General Dynamics Corporation, Thyssenkrupp AG, Saab AB, BWX Technologies, Ultra Electronics Holdings plc, Navantia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Propulsion Systems Market Evolving Landscape
Digital twin technology is compressing propulsion system development timelines while regulatory alignment across AUKUS partners is hardening supplier qualification barriers. Buyer behavior is shifting toward sovereign capability mandates that privilege technology transfer over turnkey procurement.
Solid-oxide fuel cell stacks are digitizing submarine propulsion control architecture by enabling real-time power load balancing across multiple energy sources. Naval architects at shipyards in France and Germany are integrating these systems with lithium-titanate battery banks to eliminate mechanical switching transients. The resulting digital power management backbone is digitizing maintenance forecasting, compressing unplanned dry-dock intervals.
The EU F-Gas Regulation is phasing down fluorinated greenhouse gas use in marine refrigeration and fire suppression systems, forcing propulsion system designers to specify alternative heat transfer fluids for reactor secondary loops. This regulatory pressure cascades into material specification changes for European submarine programs, with French and German yards accelerating natural refrigerant adoption. The compliance burden falls heaviest on conventional propulsion segments where thermal management system redesign must integrate with existing hull architectures.
Naval procurement offices are consolidating vendor relationships around sovereign capability building, displacing pure equipment sales with technology transfer mandates. South Korea's Defense Acquisition Program Administration now requires domestic production thresholds for critical propulsion subsystems, compelling foreign suppliers to license manufacturing to Korean heavy industry partners. This structural preference shift is most visible in Australia's AUKUS implementation, where reactor technology transfer agreements override traditional offset negotiations.
Submarine Propulsion Systems Market Segmentation
Propulsion architecture selection determines submerged endurance, acoustic signature, and platform lifecycle economics. Procurement patterns diverge sharply between nuclear-certified navies and conventional fleets seeking air-independent alternatives. Technology transfer mandates from sovereign customers now reshape supplier participation across every segment boundary.
Power Source:
Platform endurance requirements span from coastal patrol missions to multi-month deterrent patrols, driving divergent fuel and reactor choices.
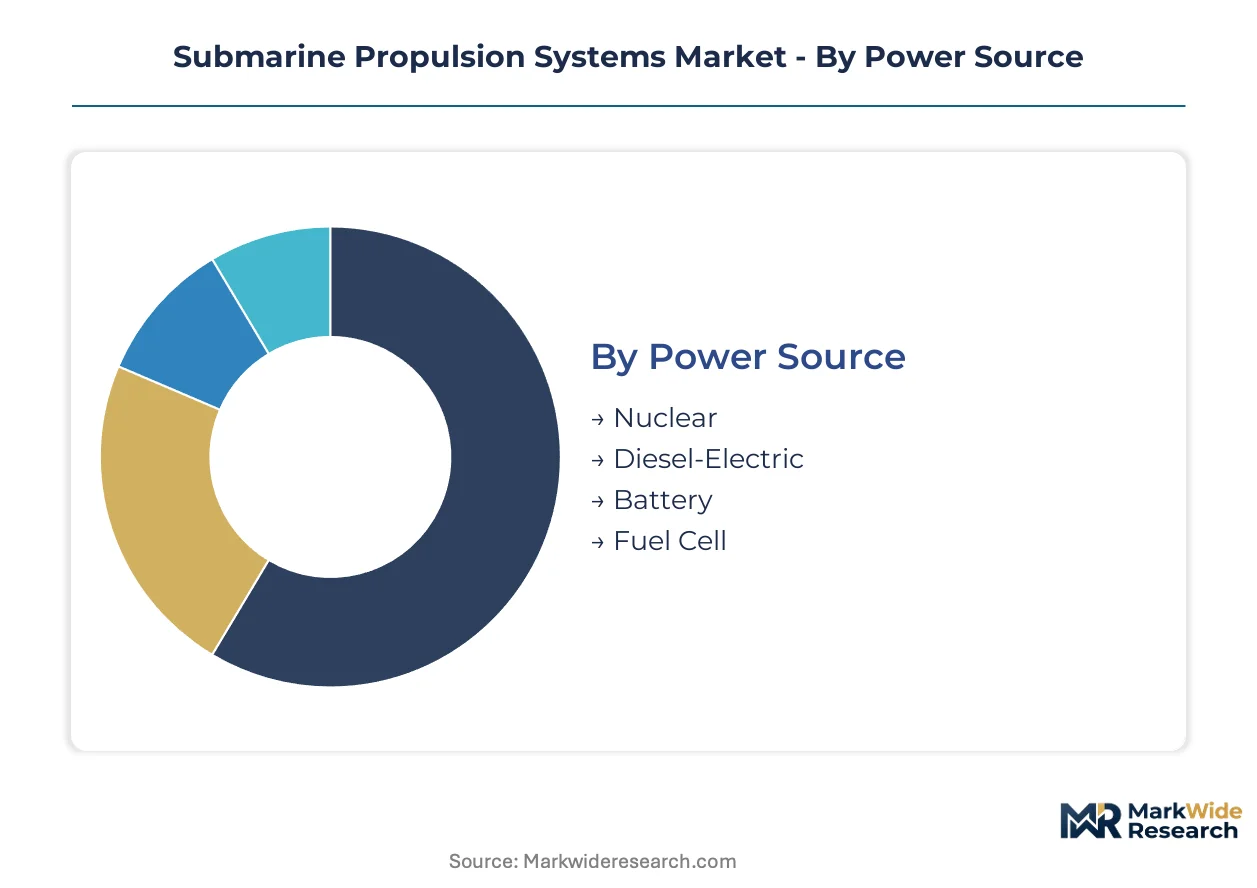
- Nuclear:Pressurized water reactors deliver unlimited submerged range for strategic deterrent and attack submarines. The US Navy's Naval Reactors program and the UK's Submarine Delivery Agency anchor demand through AUKUS reactor transfer protocols, with Australia's nuclear-powered submarine task force expanding the certified supplier pool under decade-long qualification timelines.
- Fuel Cell:Proton-exchange membrane and solid-oxide systems eliminate snorkel exposure during battery recharge cycles. South Korea's Defense Acquisition Program Administration and India's Project 75I program concentrate procurement for air-independent propulsion integration into domestically built hulls.
- Diesel-Electric:Conventional diesel generator sets paired with lead-acid or lithium-ion battery banks retain cost advantages for coastal defense fleets. Cost-constrained navies in Southeast Asia specify these systems where submerged endurance requirements remain modest.
- Battery:Advanced lithium-titanate and lithium-ion energy storage extends submerged operating hours without atmospheric exhaust. Thermal runaway risk management constraints limit charge rates and depth ratings compared to fuel cell alternatives.
The dominant share belongs to Nuclear, while Fuel Cell is closing the gap fastest.
System Type:
Architecture maturity determines dry-dock modification feasibility and mid-life upgrade economics for aging European fleets.
- Air-Independent:Closed-cycle diesel, Stirling engine, and fuel cell systems enable diesel-submarine range without snorkel exposure. Naval Group and Thyssenkrupp Marine Systems anchor European supply for retrofit programs into existing hulls requiring structural reinforcement and ballast recalculation.
- Integrated:Unified electric drive architectures reduce acoustic signatures by eliminating mechanical reduction gears. Siemens AG competes on these systems across European and Asian platforms where signature management overrides procurement cost.
- Conventional:Mechanical drive trains connecting diesel engines directly to propeller shafts persist in legacy platform support. Extended dry-dock intervals and spare parts availability constrain procurement to established supplier relationships.
- Hybrid:Modular containerized fuel cell and battery modules enable mid-life propulsion upgrades without full hull reconstruction. The EU Green Deal industrial alignment favors hydrogen fuel cell pathways that dual-use civilian marine technology.
Air-Independent architectures command premium positioning, yet Integrated systems are expanding most quickly through new-build procurement.
End User:
Sovereign capability mandates privilege technology transfer over turnkey procurement across state-funded acquisition programs.
- Naval Forces:National submarine fleets specify propulsion systems through defense export credit and sovereign-backed leasing arrangements. The Royal Australian Navy, Indian Navy, and Republic of Korea Navy anchor regional demand under tightened maritime security doctrines.
- Defense Contractors:Prime platform integrators source propulsion subsystems under fixed-price support contracts spanning 30-year platform lifecycles. Rolls Royce plc leverages nuclear reactor heritage to anchor long-term reactor-through-life contracts with British and Australian operators.
- Research Institutions:Naval research laboratories and university consortia prototype next-generation propulsion concepts. The US Navy's Naval Reactors program restricts reactor design knowledge to cleared personnel pools, creating access barriers for experimental programs.
- Commercial Operators:Submersible tourism and seabed mining ventures specify modified naval propulsion architectures. Regulatory alignment for civilian nuclear marine propulsion remains underdeveloped outside Russian icebreaker precedents.
Naval Forces retain procurement volume leadership, though Defense Contractors are consolidating influence through integrated platform delivery.
Technology:
Thrust generation methods trade acoustic performance against propulsive efficiency and manufacturing complexity.
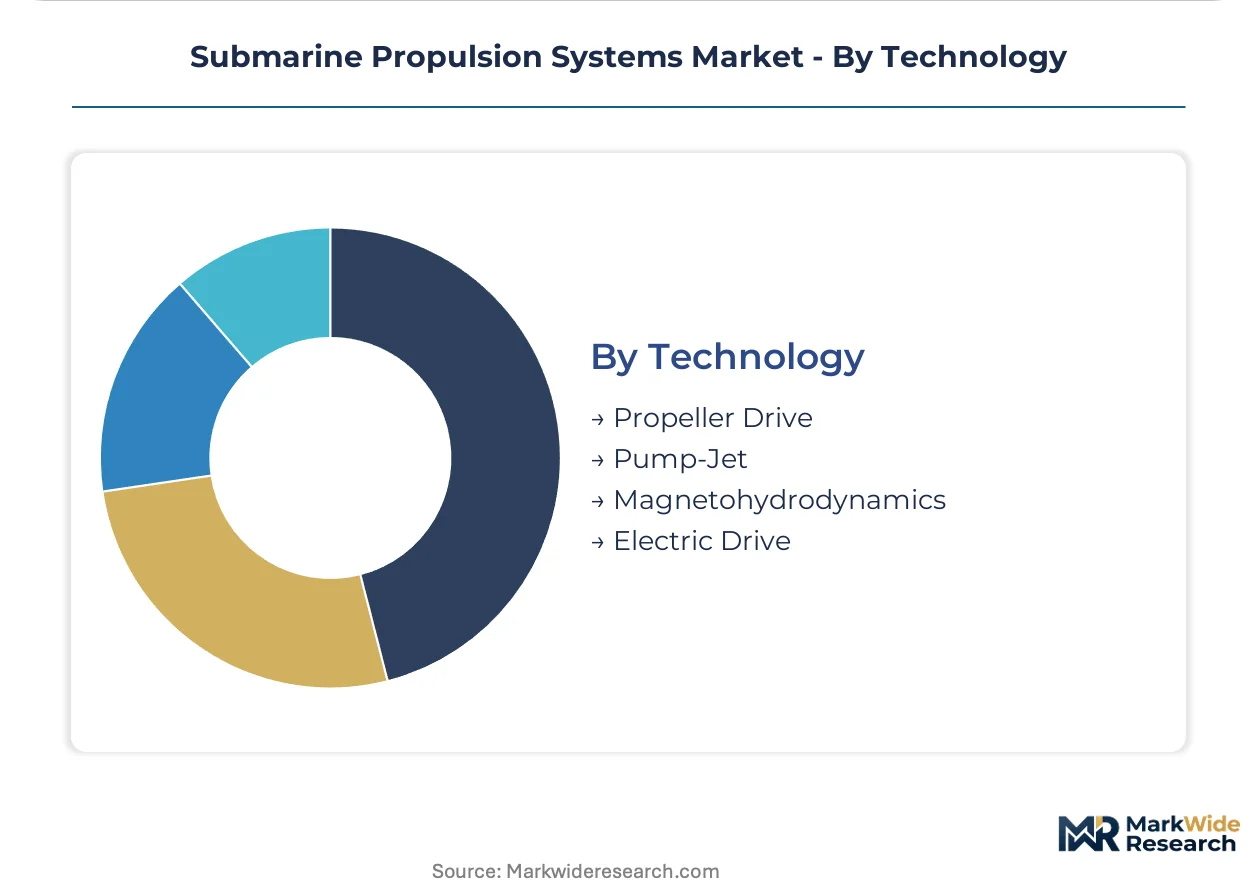
- Pump-Jet:Shrouded rotor systems eliminate cavitation noise and improve shallow-water maneuverability. Naval Group integrates these with captive design-to-build control over entire propulsion chains for French and export programs.
- Electric Drive:Motor-in-pod configurations decouple power generation from thrust production, enabling flexible hull architecture. Digital twin technology compresses development timelines for these distributed power systems.
- Propeller Drive:Conventional open propellers persist where hydrodynamic efficiency and manufacturing simplicity outweigh signature constraints. Legacy platform support sustains demand for seven-blade skewback designs.
- Magnetohydrodynamics:Electromagnetic seawater propulsion eliminates moving parts entirely. Technical immaturity and superconducting magnet cooling requirements restrict deployment to experimental prototypes.
Pump-Jet configurations dominate new-build strategic platforms, while Electric Drive is gaining share fastest through conventional submarine modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine propulsion systems trade flows reflect pronounced asymmetry between technology exporters and fleet importers. Sovereign capability mandates are redrawing procurement geography as reactor-grade nations restrict transfer protocols while conventional navies accelerate indigenous build programs.
United States
Naval Reactors program certification anchors the supplier base through AUKUS technology transfer agreements to Australia. The US Navy's Submarine Force Atlantic and Pacific fleets sustain demand for pressurized water reactor through-life support contracts concentrated at Newport News Shipbuilding and Electric Boat facilities in Virginia and Connecticut.
United Kingdom
Rolls Royce plc's reactor heritage positions the UK as the secondary AUKUS technology source alongside US transfer protocols. The Submarine Delivery Agency's Barrow-in-Furness complex and Derby manufacturing cluster coordinate reactor-grade steel procurement under decade-long qualification timelines that freeze out non-aligned vendors.
France
Naval Group's captive design-to-build control over entire propulsion chains sustains export competitiveness for conventional and nuclear platforms. The EU F-Gas Regulation is forcing natural refrigerant adoption at Cherbourg and Toulon facilities, cascading into thermal management system redesigns for reactor secondary loops.
South Korea
Defense Acquisition Program Administration domestic production thresholds for critical propulsion subsystems are compelling foreign suppliers to license manufacturing to Korean heavy industry partners. DSME and HHI shipyards in Geoje and Ulsan are integrating air-independent propulsion into KSS-III program hulls under tightened maritime security doctrines.
India
Project 75I program invitations for foreign technology partnerships are opening design-to-build contracts for air-independent propulsion integration. Mazagon Dock and L&T Shipbuilding facilities in Mumbai and Hazira face structural reinforcement and ballast recalculation challenges when retrofitting AIP into existing hull architectures.
Submarine Propulsion Systems Market Competitive Landscape
On the supply side, the industry is consolidating around sovereign-backed champions rather than purely commercial vendors. The vendor base stratifies into reactor-grade incumbents with Naval Reactors certification, integrated platform specialists with captive propulsion chains, and subsystem contractors competing on electric drive architectures. Dominant competitive moves include decade-long reactor-through-life contract capture and technology transfer licensing under offset mandates.
Within the reactor-grade tier, Rolls Royce plc and BWX Technologies exemplify suppliers leveraging nuclear heritage to anchor long-term support agreements. Siemens AG occupies a position among electric drive specialists competing on signature reduction across European and Asian platforms. Naval Group sits within the integrated platform tier where design-to-build control over entire propulsion chains sustains French and export program participation.
| Leading Market Players |
|---|
| Rolls Royce plc |
| Naval Group |
| Siemens AG |
| General Dynamics Corporation |
| Thyssenkrupp AG |
| Saab AB |
| BWX Technologies |
| Ultra Electronics Holdings plc |
| Navantia |
| Others |
Value Network & Pricing Analysis
Reactor-grade steel supply concentration determines both pricing tier spreads and supply chain shape. Single-source vulnerability at qualified foundries in the US, UK, and France compresses margins for conventional propulsion vendors while nuclear-certified incumbents capture premium through decade-long reactor-through-life contracts.
Pricing Analysis
Naval procurement offices anchor pricing stratification across premium, standard, and economy tiers based on certification grade and sovereign backing. Premium reactor-grade systems command fixed-price support spanning 30-year lifecycles, while conventional diesel-electric and fuel cell segments face cost compression from lithium-ion battery thermal management constraints. Price erosion runs through non-nuclear tiers as South Korean and Indian domestic production thresholds force technology transfer licensing. Defense contractors exhibit lowest price sensitivity due to sovereign-backed leasing arrangements, whereas Southeast Asian coastal fleets remain most cost-constrained.
Supply Chain Analysis
Extended payment terms from sovereign customers strain supplier working capital across European and Asian shipyards. Manufacturing concentrates in France, Germany, and South Korea for integrated platform delivery, with reactor-grade forgings sourcing exclusively from US, UK, and French qualified foundries. Critical dependencies include high-strength steel alloys, superconducting magnets for experimental propulsion, and proton-exchange membrane fuel cell stacks. Tariff exposure on dual-use marine components cascades through EU Green Deal compliance pathways. Distribution runs through naval procurement agencies and prime platform integrators rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology transfer mandates fragment procurement authority, creating niche entry points for subsystem specialists alongside integrated platform incumbents. Sovereign capability requirements displace turnkey sales with design-to-build partnerships across Indo-Pacific markets.
For Market Incumbents: Build certification moats through Naval Reactors program alignment and AUKUS reactor-through-life contract capture. Deepen backward integration into reactor-grade steel sourcing to offset single-source foundry vulnerability. Expand Derby and Barrow-in-Furness manufacturing clusters to meet Australian demand under decade-long qualification timelines. For New Entrants and Emerging Players: Build out modular fuel cell and battery architectures for European mid-life upgrade programs. Target India's Project 75I air-independent propulsion integration where structural reinforcement requirements favor specialized engineering partnerships. Lead with containerized propulsion modules that minimize dry-dock reconstruction for aging hulls. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors electric-drive subsystem specialists over mechanical-legacy vendors. Long-term viability hinges on fuel cell maturation and sovereign procurement persistence. Monitor AUKUS certification alignment as the inflection signal for reactor-grade supplier pool expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor-Through-Life Contract Capture | Rolls Royce plc anchors 30-year support agreements with British and Australian operators. |
| Air-Independent Propulsion Integration | Naval Group and Thyssenkrupp Marine Systems retrofit existing hulls under EU Green Deal alignment. |
| Domestic Production Threshold Compliance | South Korean shipyards license foreign fuel cell manufacturing to DSME and HHI partners. |
| Modular Containerized Upgrade Architecture | European fleets extend platform service life without full hull reconstruction. |
| Digital Twin Development Compression | Siemens AG reduces acoustic signature testing cycles for integrated electric drive systems. |
Research Methodology
Desk research of defense procurement databases, naval shipyard production records, and regulatory filing precedents preceded structured interviews with submarine program managers, propulsion system engineers, naval architects, and sovereign procurement officers. Secondary validation drew from AUKUS framework documentation, EU F-Gas Regulation compliance disclosures, and customs trade data for reactor-grade steel movements. Bottom-up segment sizing triangulated against top-down fleet modernization budget allocations.
The forecast framework held AUKUS technology transfer timelines and Indo-Pacific maritime doctrine tightening as fixed boundary conditions while varying fuel cell cost curves and battery energy density improvement rates. Segmentation modeling spanned power source architecture, system type integration level, end-user procurement authority, and thrust generation technology. CAGR derivation weighted historical platform delivery patterns against announced fleet expansion targets and indigenous construction program schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed shipbuilders or accelerated Indian technology localization would shift outcomes. Macroeconomic defense budget compression, regulatory restriction on dual-use marine technology exports, or breakthrough magnetohydrodynamics maturation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Fender Market
Marine
Electric Outboard Engines Market
Marine
Shipbuilding Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Electric Boat and Ship Market
Marine
Boat Hook Market
Marine
Deep-V Boat Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Marine Shaft Power Meter Market
Marine
Electric Ship Market
Marine
Boat Ladder Market
Marine
Marine Fuel Injector Market
Marine
Marine Beacon Market
Marine
Marine Shackle Market
Marine
Sea Scooter Market
Marine
Marine Lighting Market