
 Vehicle Speed Monitoring System Market | 2026-2036
Vehicle Speed Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Speed Monitoring System Market Outlook
European sensor manufacturing is shifting toward higher-resolution LiDAR and optical modules for next-generation enforcement. Kapsch TrafficCom AG leverages its Vienna engineering base to dominate fixed-location installations across Austria and beyond. Sensys Gatso Group anchors its position through in-house production of radar detection hardware. Robert Bosch GmbH differentiates via R&D intensity in automotive-grade speed sensing for integrated vehicle systems.
A vehicle speed monitoring system comprises electronic hardware and software that detects, records, and transmits velocity data using Doppler radar, GPS triangulation, or optical image processing, with detection thresholds typically calibrated from 5 km/h to 300 km/h and accuracy margins within ±1 km/h for enforcement-grade units. Its primary purpose spans traffic law enforcement, fleet fuel optimization, insurance risk scoring, and autonomous vehicle validation. Radar systems retain the largest installed base among product types due to decades of regulatory certification, while GPS trackers represent the fastest-growing category as logistics companies mandate real-time velocity visibility across distributed fleets. Telematics units concentrate margin pools through recurring software subscriptions layered over hardware sales.
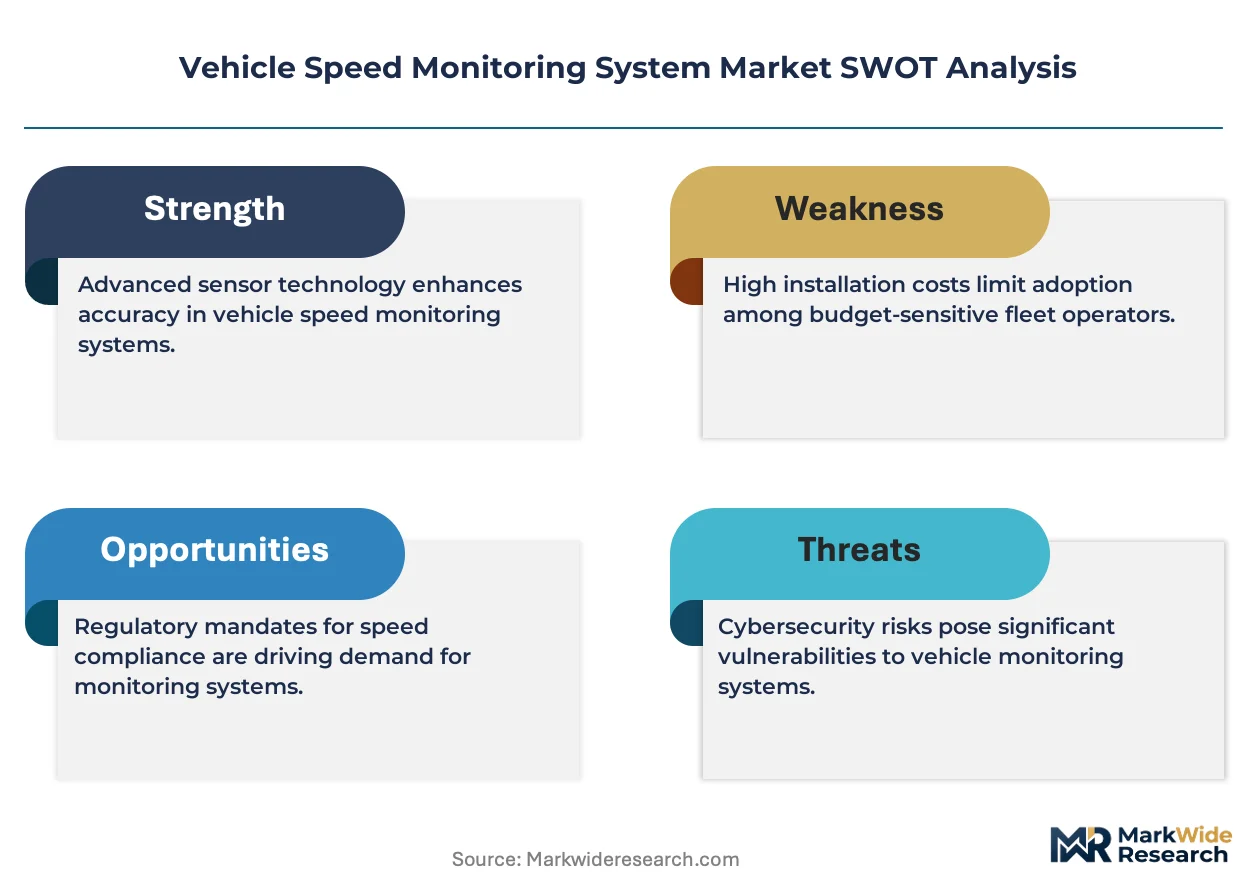
The EPA and NHTSA shape US demand through Corporate Average Fuel Economy standards and automated enforcement guidance, while the EU AI Act and GDPR constrain how optical speed cameras process biometric data in Europe. REACH compliance adds material costs for LiDAR sensor housings and printed circuit boards sold into European markets. Stakeholders must monitor how divergent privacy frameworks between jurisdictions fragment product design requirements and certification timelines.
Market Dynamics
LiDAR sensor miniaturization is compressing unit economics for enforcement-grade hardware while fleet telematics mandates from the EPA and NHTSA force retrofit cycles across US commercial vehicle pools.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Fleet operators in the United States face escalating penalties for non-compliance, accelerating hardware refresh cycles for integrated speed monitoring and fuel optimization systems.
- Optical image processing:Higher-resolution camera modules enable multi-lane speed detection from single mounting points, reducing infrastructure deployment costs for municipal traffic authorities.
- Germany's enforcement corridor density:The country's federal motorway network maintains the highest fixed-installation penetration in Europe, sustaining procurement volumes for radar-LiDAR hybrid units.
Market Restraints
- LiDAR semiconductor supply concentration:Indium gallium arsenide photodetectors and vertical-cavity surface-emitting lasers concentrate production among specialized foundries in Taiwan and South Korea, creating input cost volatility.
- EU AI Act biometric processing constraints:Optical speed cameras capturing facial or bodily features face algorithmic audit requirements and purpose-limitation rules that extend certification timelines.
- GPS jamming and spoofing vulnerabilities:Fleet telematics reliant on satellite triangulation encounter reliability degradation in urban canyons and deliberate interference zones, limiting enforcement-grade substitution.
Strategic Opportunities
- India's national highway expansion:The Golden Quadrilateral and North-South East-West Corridor upgrades create greenfield demand for automated enforcement infrastructure without legacy system replacement burdens.
- Insurance risk scoring integration:Usage-based auto insurance platforms in the United Kingdom and Germany are incorporating real-time velocity telemetry as a primary rating variable.
- Edge AI and 5G convergence:On-device inference combined with low-latency cellular backhaul enables instantaneous violation processing, eliminating centralized server bottlenecks.
Industry Challenges
- Embedded systems firmware certification:Automotive-grade speed sensors require ISO 26262 functional safety validation, stretching development cycles for suppliers without existing automotive supply relationships.
- Interoperability with legacy tolling infrastructure:Municipal agencies operate mixed-vendor environments where proprietary communication protocols obstruct unified data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Speed Monitoring System Market |
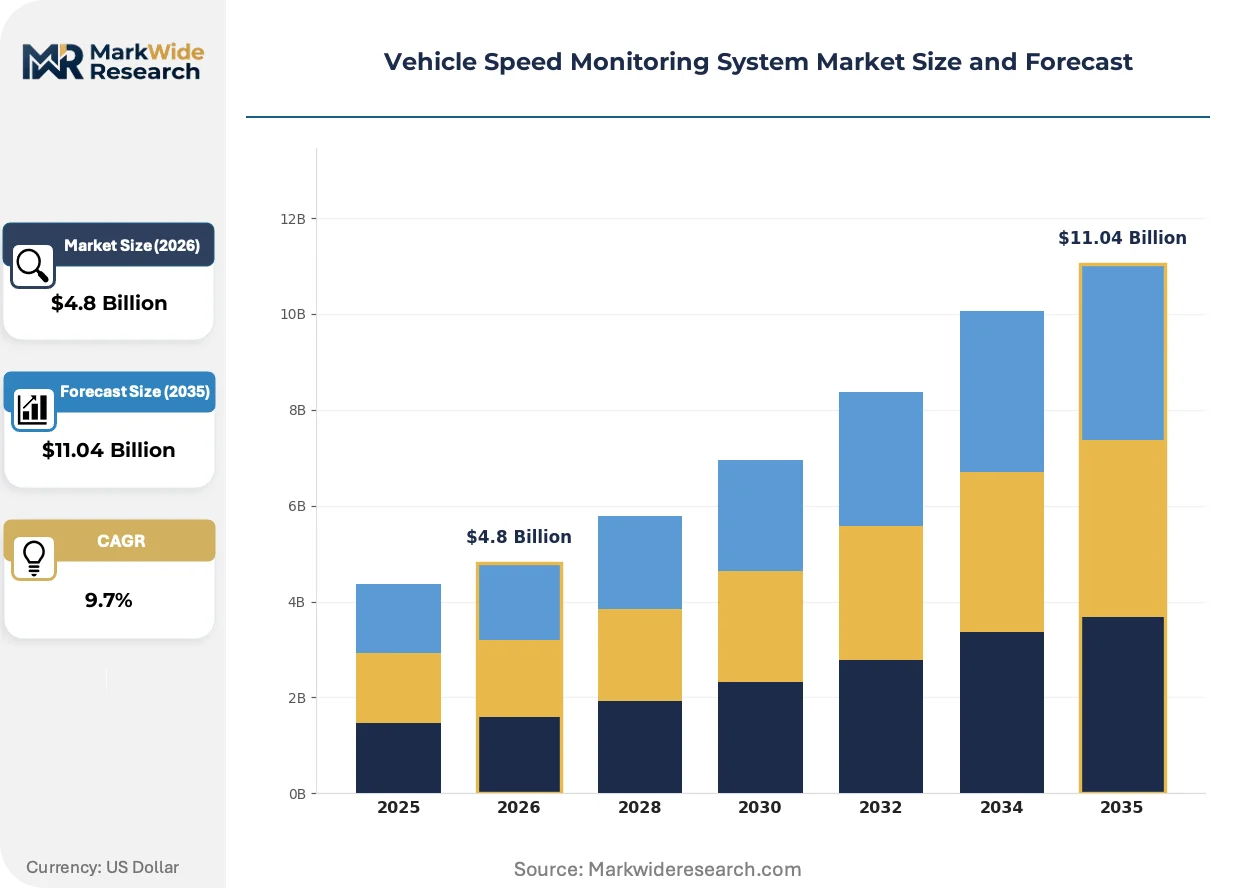
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, GPS Trackers, Telematics Units, Dash Cameras Technology: Wireless, GPS, Optical, LiDAR End User: Logistics Companies, Fleet Operators, Government Agencies, Individual Drivers Installation: On-Board Diagnostics, Mobile Units, Fixed Locations, Integrated Systems |
| Companies Covered | Siemens AG, Kapsch TrafficCom AG, Sensys Gatso Group, Verra Mobility, Siemens Mobility, Continental AG, Robert Bosch GmbH, Denso Corporation, American Traffic Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Speed Monitoring System Market Strategic Shifts
Edge computing architectures are redistributing processing loads from centralized servers to roadside and vehicle-mounted units, collapsing latency for real-time enforcement decisions while fragmenting vendor competitive positions.
Frequency-modulated continuous-wave LiDAR is decentralizing speed detection authority from fixed gantries to patrol vehicles and even consumer dashcams. Municipal police departments in California and Texas are piloting mobile units that match stationary system accuracy without right-of-way construction. This diffusion is compressing the addressable market for traditional fixed-installation specialists while expanding the total deployable base.
REACH compliance for sensor housings is forcing material substitutions across European supply chains. Original equipment manufacturers face restricted substance declarations and extended supplier qualification periods for recycled aluminum enclosures and halogen-free printed circuit boards. German component suppliers report 14-18 month redesign cycles to maintain CE marking eligibility.
Fleet procurement departments are unbundling hardware acquisition from software subscriptions, treating telematics platforms as separable service contracts. Large logistics operators in the United States now source speed monitoring hardware through industrial distributors while negotiating data analytics separately with cloud-native software vendors. This bifurcation is most visible among for-hire trucking fleets with over 500 power units.
Vehicle Speed Monitoring System Market Segmentation
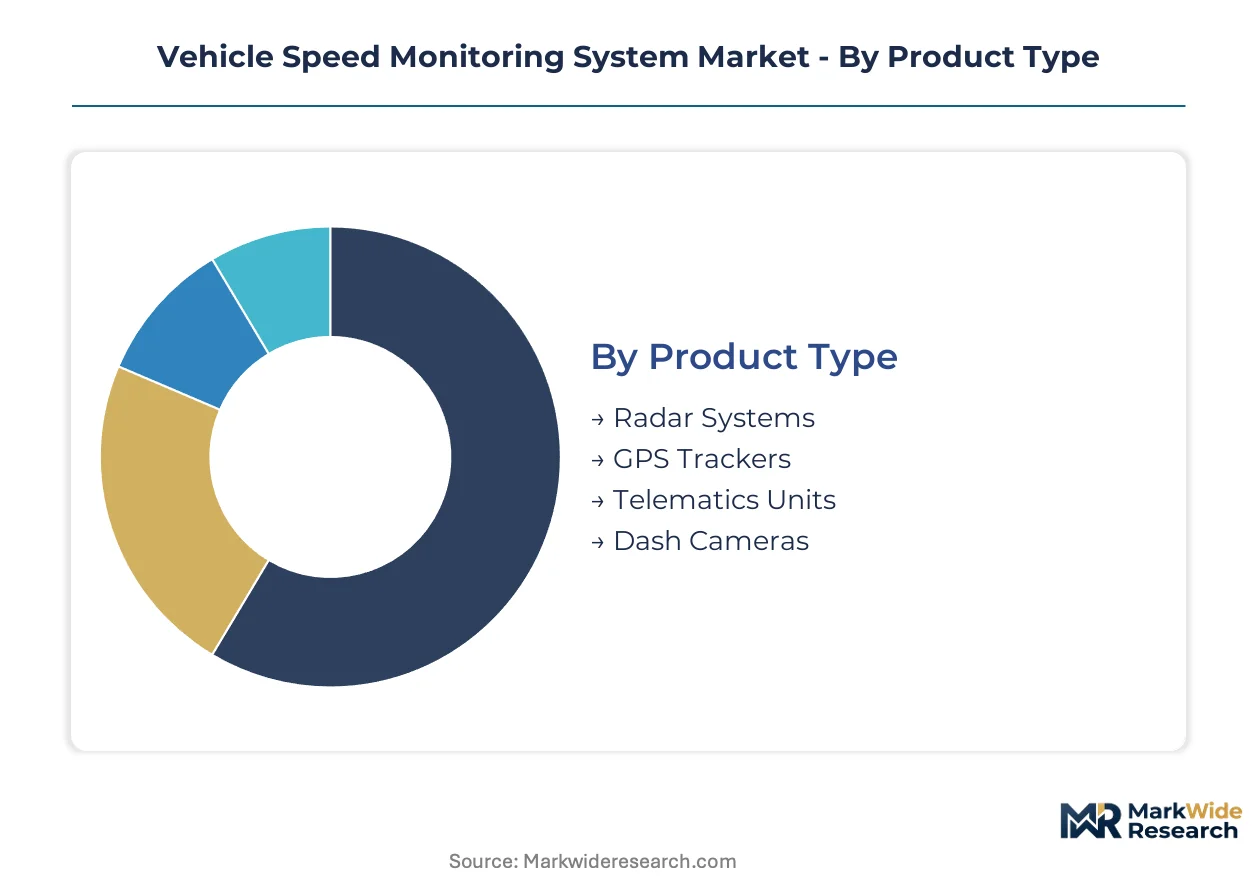
Hardware refresh cycles and regulatory mandates fragment procurement patterns across product tiers. Fleet operators prioritize integrated systems while enforcement authorities favor discrete detection modules with standalone certification paths.
Product Type:
Replacement timelines diverge sharply between enforcement-grade fixed installations and portable fleet hardware, with municipal agencies running 7-10 year depreciation schedules against logistics operators' 3-4 year technology refresh mandates.
- Radar Systems:Doppler-based velocity detection using K-band or Ka-band radio frequencies achieves ±1 km/h accuracy at ranges exceeding 300 meters. Germany's federal motorway network sustains procurement volumes for enforcement-grade units as KBA certification requirements lock in incumbent suppliers.
- GPS Trackers:Satellite triangulation modules transmit real-time velocity data through cellular backhaul for distributed fleet visibility. Logistics operators across the United States mandate these units under EPA fuel economy compliance programs, with subscription revenue pools exceeding hardware margins.
- Telematics Units:Integrated speed, location, and engine diagnostics platforms consolidate multiple sensor inputs.
- Dash Cameras:Consumer-grade optical recording devices with velocity overlay functionality.
Volume placements concentrate in Radar Systems; the faster expansion belongs to GPS Trackers.
Technology:
Cost tiers separate mature radio-frequency approaches from emerging optical and laser-based detection, with semiconductor bill-of-materials driving 40-60% price spreads between entry-level and premium implementations.
- Wireless:Radio-frequency communication protocols enable roadside-to-vehicle or vehicle-to-cloud data transmission without physical tethering.
- GPS:Satellite positioning systems calculate velocity through sequential coordinate differentiation, vulnerable to urban canyon multipath and deliberate jamming.
- Optical:Machine-vision cameras process license plate and vehicle imagery for speed determination across multiple lanes. EU AI Act algorithmic audit requirements extend certification timelines for biometric-capable units.
- LiDAR:Frequency-modulated continuous-wave laser systems deliver centimeter-range precision for mobile enforcement applications. Taiwan and South Korean foundry concentration for indium gallium arsenide photodetectors creates input cost volatility.
Procurement volumes favor Wireless implementations; LiDAR climbs the fastest on patrol vehicle adoption.
End User:
Customer type determines specification rigor, with government agencies demanding ISO 26262 functional safety validation that consumer-facing segments bypass entirely.
- Logistics Companies:For-hire trucking fleets with 500+ power units unbundle hardware acquisition from software analytics, sourcing sensors through industrial distributors while negotiating cloud-native platforms separately.
- Fleet Operators:Private commercial vehicle pools face EPA Corporate Average Fuel Economy penalties that accelerate integrated speed monitoring refreshes.
- Government Agencies:Municipal traffic authorities and federal enforcement bodies mandate enforcement-grade accuracy with judicial admissibility standards.
- Individual Drivers:Consumer purchasers prioritize price accessibility over calibration precision.
Contract values peak with Government Agencies; Logistics Companies expand their installed base most rapidly.
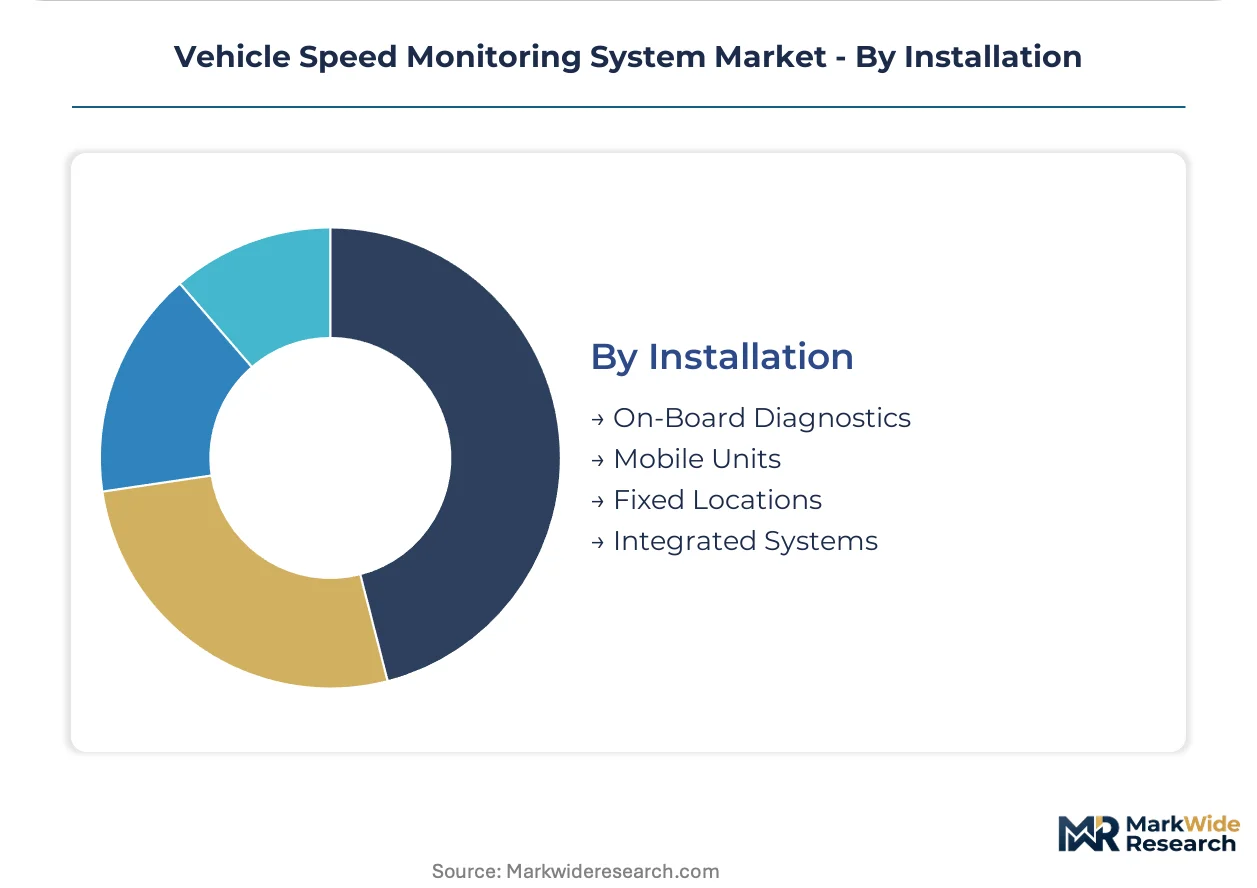
Installation:
Physical deployment configuration shapes maintenance economics, with fixed gantries requiring civil engineering against plug-and-play portability premiums.
- On-Board Diagnostics:Vehicle-integrated ports extract engine-speed data for correlation with GPS-calculated velocity.
- Mobile Units:Patrol-vehicle-mounted radar-LiDAR hybrids enable enforcement without right-of-way construction. California and Texas police departments pilot these against stationary system accuracy benchmarks.
- Fixed Locations:Gantry-mounted installations on Germany's autobahn network carry 14-18 month redesign cycles for REACH-compliant sensor housings.
- Integrated Systems:Factory-installed automotive-grade speed sensing requires existing OEM supply relationships for ISO 26262 validation.
Deployment volumes cluster in Fixed Locations; Mobile Units gain share fastest on enforcement flexibility demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium gallium arsenide photodetector foundries in Taiwan and South Korea supply critical LiDAR components that determine enforcement-grade hardware availability across major automotive and traffic management markets.
United States
Fleet operators accelerate integrated telematics adoption as EPA Corporate Average Fuel Economy standards impose escalating penalties for non-compliance. NHTSA automated enforcement guidance shapes municipal procurement specifications. California and Texas police departments pilot mobile radar-LiDAR hybrid units that match stationary system accuracy.
Germany
The federal motorway network sustains Europe's highest fixed-installation penetration for enforcement-grade speed monitoring systems. KBA certification requirements lock in incumbent suppliers for radar-based infrastructure. Kapsch TrafficCom leverages its Vienna engineering base to dominate fixed-location installations across Austria and beyond.
India
National highway expansion through the Golden Quadrilateral and North-South East-West Corridor upgrades creates greenfield demand for automated enforcement infrastructure. The Ministry of Road Transport and Highways mandates speed detection systems on new expressway segments. Industrial corridors around Delhi-Mumbai and Chennai-Bengaluru anchor deployment clusters.
Japan
METI industrial standards drive automotive-grade sensor specifications for integrated vehicle systems. Domestic OEM supply relationships enforce ISO 26262 functional safety validation requirements. The Nagoya-Toyota industrial corridor concentrates manufacturing of precision radar modules for export markets.
United Kingdom
Usage-based auto insurance platforms incorporate real-time velocity telemetry as a primary rating variable. GDPR and EU AI Act constraints extend certification timelines for optical speed cameras processing biometric data. London and the Southeast concentrate telematics platform development for commercial fleet applications.
Vehicle Speed Monitoring System Market Competitive Environment
Global majors compete with regional champions across certification authority and enforcement-grade accuracy standards. The vendor base separates into three tiers: integrated automotive suppliers with OEM supply relationships, traffic infrastructure specialists with regulatory certification depth, and telematics platform vendors with recurring software revenue models. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud-native analytics providers, plus geographic expansion through municipal agency procurement relationships.
Within the traffic infrastructure specialist tier, Kapsch TrafficCom AG and Sensys Gatso Group exemplify European regulatory certification depth. Robert Bosch GmbH occupies a position among integrated automotive suppliers leveraging R&D intensity in automotive-grade speed sensing. Verra Mobility represents the North American enforcement services archetype with municipal agency relationships.
| Leading Market Players |
|---|
| Siemens AG |
| Kapsch TrafficCom AG |
| Sensys Gatso Group |
| Verra Mobility |
| Siemens Mobility |
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| American Traffic Solutions |
| Others |
Value Chain & Pricing Dynamics
REACH compliance for sensor housings and halogen-free printed circuit boards gates qualified supply access for enforcement-grade hardware, with German component suppliers reporting 14-18 month redesign cycles that prop premium-tier pricing for CE-marked installations.
Pricing Analysis
Warranty and calibration service bundling separates enforcement-grade procurement from unbundled fleet hardware transactions. Three-tier pricing structure across judicial-certified, commercial-grade, and consumer tiers reflects ISO 26262 validation depth and KBA certification status. Cost compression in commercial telematics intensifies because logistics operators now source hardware through industrial distributors while negotiating analytics separately. Government agencies exhibit lowest price sensitivity due to judicial admissibility requirements; individual drivers show highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from municipal procurement departments require qualification of multiple LiDAR photodetector suppliers. Taiwan and South Korean foundries anchor indium gallium arsenide photodetector output; German engineering bases concentrate radar module assembly. Input cost volatility hinges on vertical-cavity surface-emitting laser wafer availability. Distribution runs through municipal agency tender processes for enforcement infrastructure and industrial distributors for fleet hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium gallium arsenide photodetector foundry capacity constraints prop enforcement-grade hardware pricing, creating a supply-constrained market structure where qualified component access determines competitive viability.
For Market Incumbents: Cement KBA and EPA certification authority through captive production of radar detection hardware in German and US engineering corridors. Add ISO 26262 validation capacity to defend against automotive OEM supply relationship encroachment. Deepen backward integration into LiDAR semiconductor sourcing to offset Taiwan and South Korean foundry concentration risk.
For New Entrants and Emerging Players: Begin with India's Golden Quadrilateral highway expansion corridor, where greenfield enforcement infrastructure demand lacks incumbent supplier lock-in. Target mobile radar-LiDAR hybrid units for California and Texas police department pilot programs. Pursue cloud-native telematics platform partnerships with for-hire trucking fleets above 500 power units.
For Investors and Strategic Acquirers: EPA fuel economy penalty escalation is the leading indicator that fleet telematics refresh cycles will sustain hardware demand. Position for 5-10 year horizon through traffic infrastructure specialists with municipal agency procurement relationships and regulatory certification depth. Watch for EU AI Act algorithmic audit completion timelines as inflection signal for optical camera market access.
| Strategic Initiative | Industry Significance |
|---|---|
| LiDAR Semiconductor Backward Integration | Captive photodetector supply from Taiwan and South Korean foundries reduces input cost volatility for enforcement-grade units. |
| Edge AI Certification Investment | ISO 26262 functional safety validation unlocks automotive OEM supply relationships for integrated vehicle systems. |
| Municipal Agency Procurement Partnership | Direct relationships with German KBA and US NHTSA shape enforcement infrastructure specifications and tender access. |
| Telematics Platform Unbundling | Separating hardware distribution from cloud-native analytics subscription captures logistics fleet procurement shifts. |
| India Highway Corridor Deployment | Golden Quadrilateral greenfield installations bypass legacy system replacement burdens facing European markets. |
Study Parameters
Multi-period observation of EPA penalty escalation schedules, EU AI Act implementation timelines, and LiDAR foundry capacity utilization anchored the trend analysis, supplemented by interviews with municipal traffic authority procurement officers, fleet operations managers at for-hire trucking companies, radar module engineering directors, telematics platform product managers, and automotive OEM supply chain leads. Secondary validation drew from NHTSA automated enforcement guidance documents, KBA certification registries, REACH substance restriction databases, SEC filings by traffic infrastructure vendors, and customs records for LiDAR component trade flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across product and technology segments.
Input-output matrices mapped enforcement-grade hardware, fleet telematics units, and consumer dashcam volumes against regulatory mandate schedules and replacement cycle assumptions across the projection horizon. Segmentation dimensions modeled include product type, detection technology, end-user category, and installation configuration alongside regional regulatory cluster differentiation. CAGRs derived from logistic curve penetration modeling against enforcement corridor density and fleet operator compliance deadlines. Forecast inputs incorporated LiDAR miniaturization cost curves and 5G cellular backhaul deployment pace.
Underlying measurement precision varies by segment; government agency procurement data carries tighter precision than consumer dashcam estimates where retail channel reporting fragments. Forecasts reflect documented assumptions regarding EPA penalty enforcement consistency and EU AI Act biometric processing rule finalization. Deviation in indium gallium arsenide photodetector foundry output or REACH substance restriction scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market