
 Traffic Control Device Tape Market | 2026-2036
Traffic Control Device Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Control Device Tape Market Analytics
Modular kit configurations of cones, barriers, and marking tapes is restructuring how municipal buyers evaluate total cost of ownership against single-item procurement. 3M leverages its reflective technology leadership to dominate premium specification tiers. Nitto Denko sustains competitive pressure through advanced adhesive formulations engineered for extreme temperature cycling. Advance Tapes specializes in rapid-deployment barrier systems favored by emergency services contractors.
Traffic control device tape comprises pressure-sensitive adhesive films engineered with retroreflective glass bead or prismatic layers, typically meeting minimum coefficients of retroreflection measured in candela per lux per square meter for nighttime visibility assurance. The product serves to delineate work zones, channelize traffic flows, and enhance pedestrian safety in temporary or semi-permanent roadway configurations. Marking tapes command the largest volume share within the product type dimension, while reflective technology captures the dominant value pool due to stringent nighttime visibility mandates. Weather-resistant formulations represent the fastest-expanding technology segment as agencies in hurricane-prone geographies prioritize extended outdoor durability. Municipalities constitute the most concentrated end-user category, though event management applications are gaining traction as outdoor venue operators professionalize crowd control protocols.
The US Federal Highway Administration's Manual on Uniform Traffic Control Devices establishes binding specifications for retroreflective performance, color retention, and adhesive integrity that shape manufacturer R&D priorities and certification costs. State-level DOT procurement rules in Texas, California, and Florida impose additional qualification testing that filters market access for smaller suppliers. Stakeholders must monitor evolving state supplement amendments to federal standards and pre-position inventory ahead of anticipated compliance deadline clusters.
Market Dynamics
Federal compliance deadlines for retroreflective performance standards are compressing replacement cycles across municipal procurement, forcing rapid inventory turnover and favoring suppliers with pre-certified product lines.
Growth Catalysts
- Smart Intersection Upgrades:Municipalities in Texas, Florida, and California are expanding budgets for intelligent traffic systems that integrate high-visibility marking tapes with sensor networks.
- MUTCD Compliance Deadlines:The US Federal Highway Administration's updated retroreflectivity mandates are accelerating product replacement across state DOT inventories.
- Glass Bead Technology:Advances in microprismatic retroreflection are extending nighttime visibility coefficients beyond legacy bead-based formulations.
Market Restraints
- Petrochemical Input Volatility:Pressure-sensitive adhesive formulations depend on acrylic resin feedstocks subject to crude oil price swings.
- Supplier Concentration:Premium prismatic film production concentrates among three specialized converters in the Midwest and Southeast.
- Substitution by Delineators:Rigid channelizing devices are displacing temporary tape in high-wind work zones where adhesive failure risks liability.
Strategic Opportunities
- Hurricane Belt Durability:Weather-resistant formulations command price premiums in Florida and Gulf Coast states where extended outdoor exposure degrades standard tapes.
- Event Management Vertical:Outdoor venue operators in California are professionalizing crowd control protocols and specifying DOT-grade reflective tapes for temporary pedestrian channelization.
- Modular Kit Integration:Bundled procurement of cones, barriers, and marking tapes is opening contract channels previously dominated by single-item vendors.
Industry Challenges
- Certification Timeline Compression:State DOT qualification testing in Texas and California extends product launch cycles by 8-14 months for new adhesive formulations.
- Retroreflectivity Measurement Expertise:Municipal procurement offices lack trained personnel to verify candela per lux per square meter specifications, creating acceptance disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Control Device Tape Market |
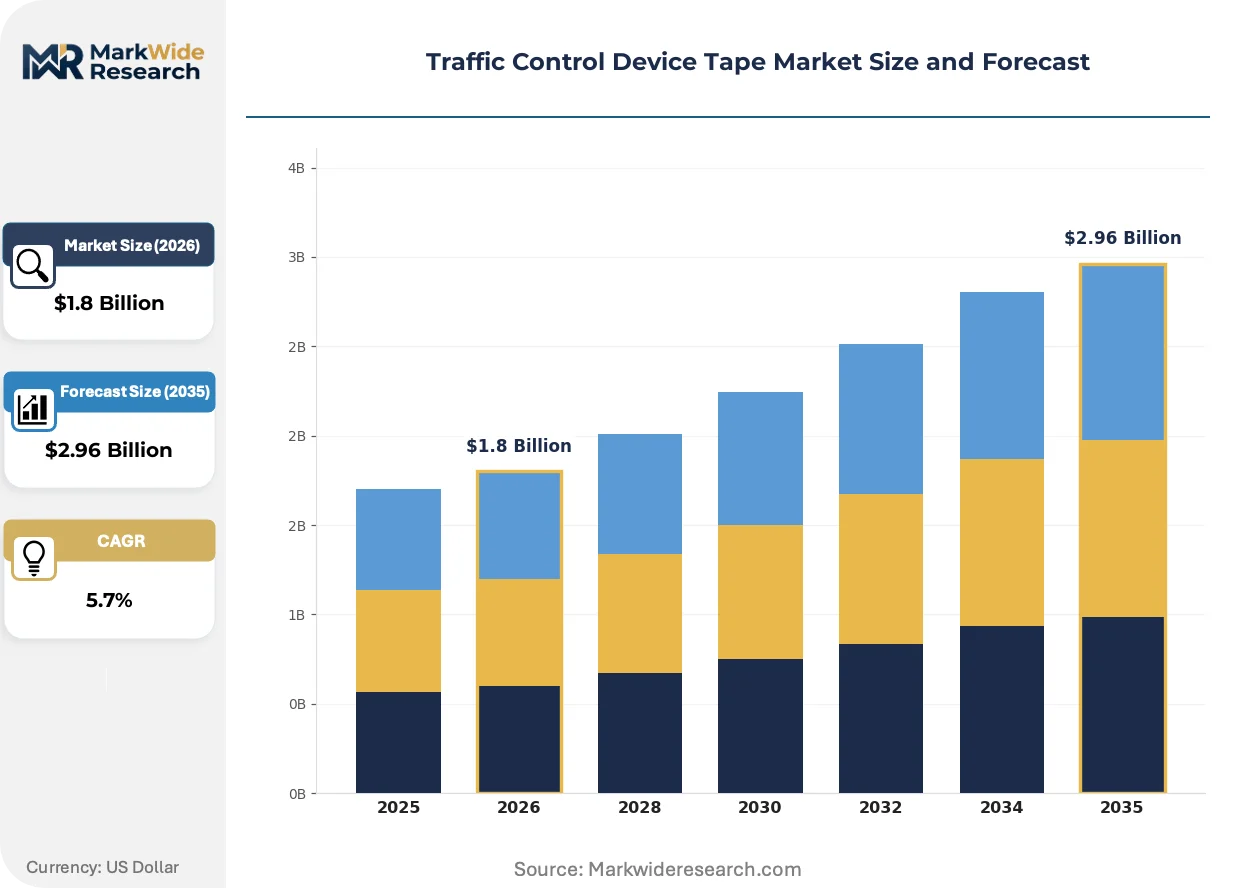
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cones, Barriers, Marking Tapes, Signs Application: Construction, Event Management, Road Safety, Parking Technology: Reflective, Non-Reflective, Anti-Slip, Weather-Resistant End User: Municipalities, Contractors, Events Organizers, Emergency Services |
| Companies Covered | 3M, Kruse Adhesive Tape, Nitto Denko, Vibac, Advance Tapes, Harris Industries, Hultafors Group, Scapa Group, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Control Device Tape Market Evolving Landscape
Retroreflective technology is advancing through material science breakthroughs that extend durability while regulatory pressure tightens performance verification protocols. Municipal buyers are professionalizing specification practices.
Microprismatic retroreflection is electrifying the premium product tier by delivering coefficient values three to four times higher than glass bead alternatives. State DOTs in California and Texas are specifying prismatic layers for high-speed corridor applications where nighttime visibility failures carry severe liability. The technology is electrifying competitive segmentation by creating a distinct specification tier above commodity marking tapes.
The US Federal Highway Administration's updated MUTCD retroreflectivity mandates are binding state DOTs to measurable nighttime performance thresholds with documented compliance dates. Manufacturers face stepped-up third-party verification costs and accelerated R&D cycles to maintain certified product lines. Municipal procurement offices in Florida are responding by pre-qualifying suppliers with existing FHWA compliance documentation.
Bundled procurement contracts are consolidating vendor relationships as Texas DOT and large municipal buyers shift from single-item purchasing to multi-year framework agreements covering cones, barriers, and marking tapes. Distributors with kit assembly capabilities are displacing pure-play tape suppliers in competitive bidding. California emergency services contractors favor this model for rapid-deployment inventory management.
Traffic Control Device Tape Market Segmentation
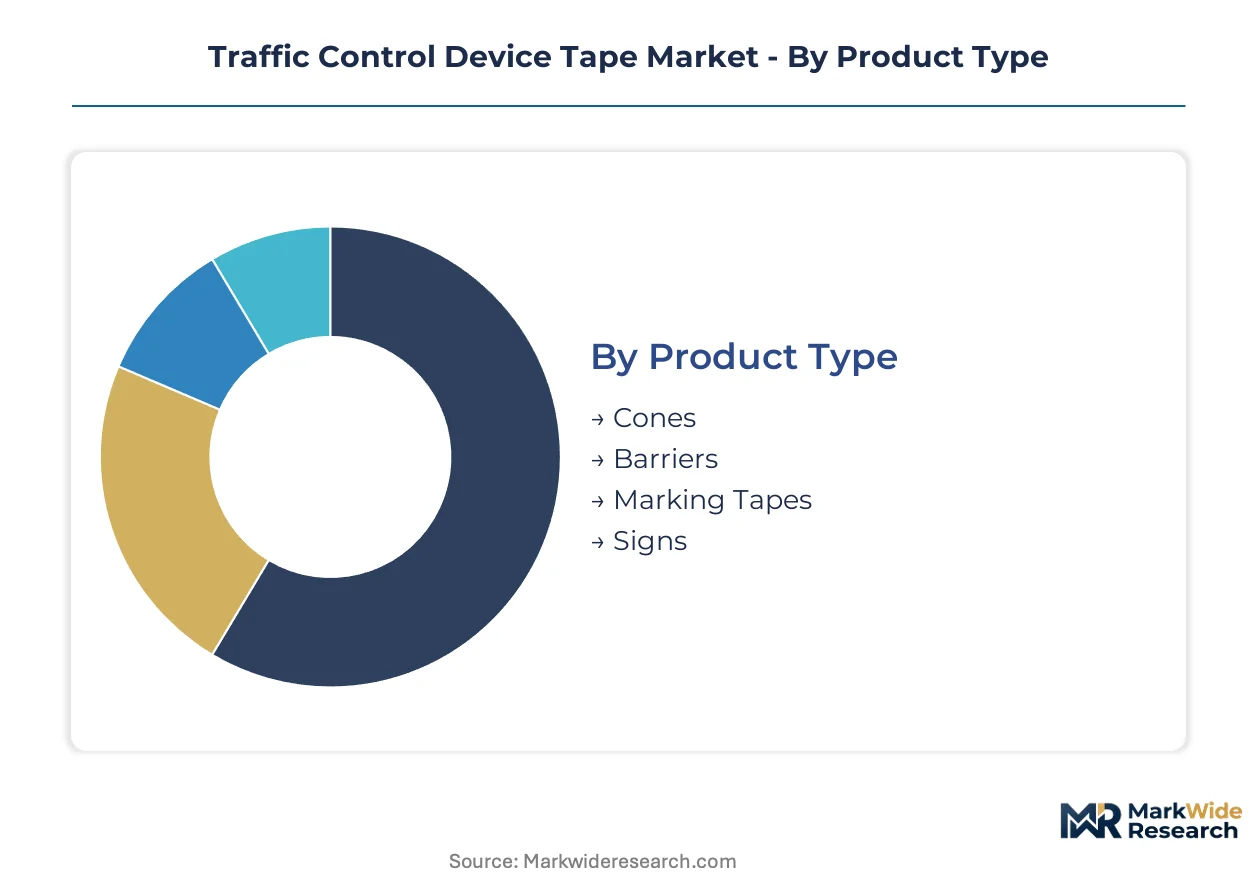
Traffic control device tape segmentation reveals how procurement decisions split between standalone consumables and integrated safety systems. Buyers evaluate total cost of ownership differently across these divides, reshaping supplier positioning and contract structures.
Product Type:
Integration depth varies sharply: marking tapes and cones function as standalone deployables, while barriers and signs increasingly embed into coordinated channelization systems with shared mounting hardware.
- Marking Tapes:Pressure-sensitive adhesive films with retroreflective glass bead or prismatic layers deliver nighttime visibility for temporary lane delineation. Texas and California DOTs specify these for high-speed corridor work zones where FHWA retroreflectivity mandates apply. Procurement concentrates in bulk rolls for municipal maintenance fleets.
- Barriers:Rigid plastic or water-filled channelizing devices provide physical protection in high-wind conditions where adhesive tapes risk detachment. Florida emergency services contractors favor rapid-deployment barrier systems for hurricane response staging areas. These integrate with tape systems through shared ballast and connection hardware.
- Cones:Collapsible vinyl or rubber traffic cones serve short-duration applications with minimal setup requirements.
- Signs:Roll-up or rigid panel signs supplement tape delineation with regulatory messaging at work zone entry points.
Volume placements concentrate in marking tapes; the faster expansion belongs to barriers.
Application:
Cost tier stratification separates commodity municipal procurement from premium event management specifications where liability exposure drives DOT-grade material requirements.
- Road Safety:Permanent and semi-permanent installations on public highways demand certified retroreflective performance meeting FHWA Manual on Uniform Traffic Control Devices standards. State DOTs in Texas, Florida, and California dominate procurement volume with multi-year framework agreements. Compliance documentation requirements filter supplier participation.
- Event Management:Outdoor venue operators in California professionalize crowd control with specification-grade reflective tapes for temporary pedestrian channelization. Music festivals and sporting events drive demand for rapid-deployment kits combining tape, cones, and barriers. Premium pricing applies versus municipal procurement.
- Construction:General contractors deploy temporary traffic control for utility work and building site access.
- Parking:Commercial lot operators use non-reflective marking for low-speed vehicle guidance.
Construction captures baseline volume; event management climbs the fastest.
Technology:
Performance tiering creates three distinct specification levels: premium prismatic for high-speed corridors, standard glass bead for general municipal use, and economy non-reflective for daytime-only applications.
- Reflective:Glass bead and microprismatic formulations deliver candela per lux per square meter performance for nighttime visibility assurance. Microprismatic layers command price premiums three to four times above bead alternatives in California and Texas high-speed specifications. FHWA compliance deadlines accelerate replacement cycles.
- Weather-Resistant:Enhanced adhesive formulations and substrate materials withstand extended outdoor exposure in hurricane-prone geographies. Florida and Gulf Coast municipalities prioritize these for reduced replacement frequency. Premium pricing reflects extended service life claims.
- Non-Reflective:Basic vinyl or polymer films serve daytime-only applications with minimal visibility requirements.
- Anti-Slip:Textured surface treatments improve pedestrian traction in wet conditions for event management deployments.
Reflective technology holds dominant volume; weather-resistant formulations gain share fastest.
End User:
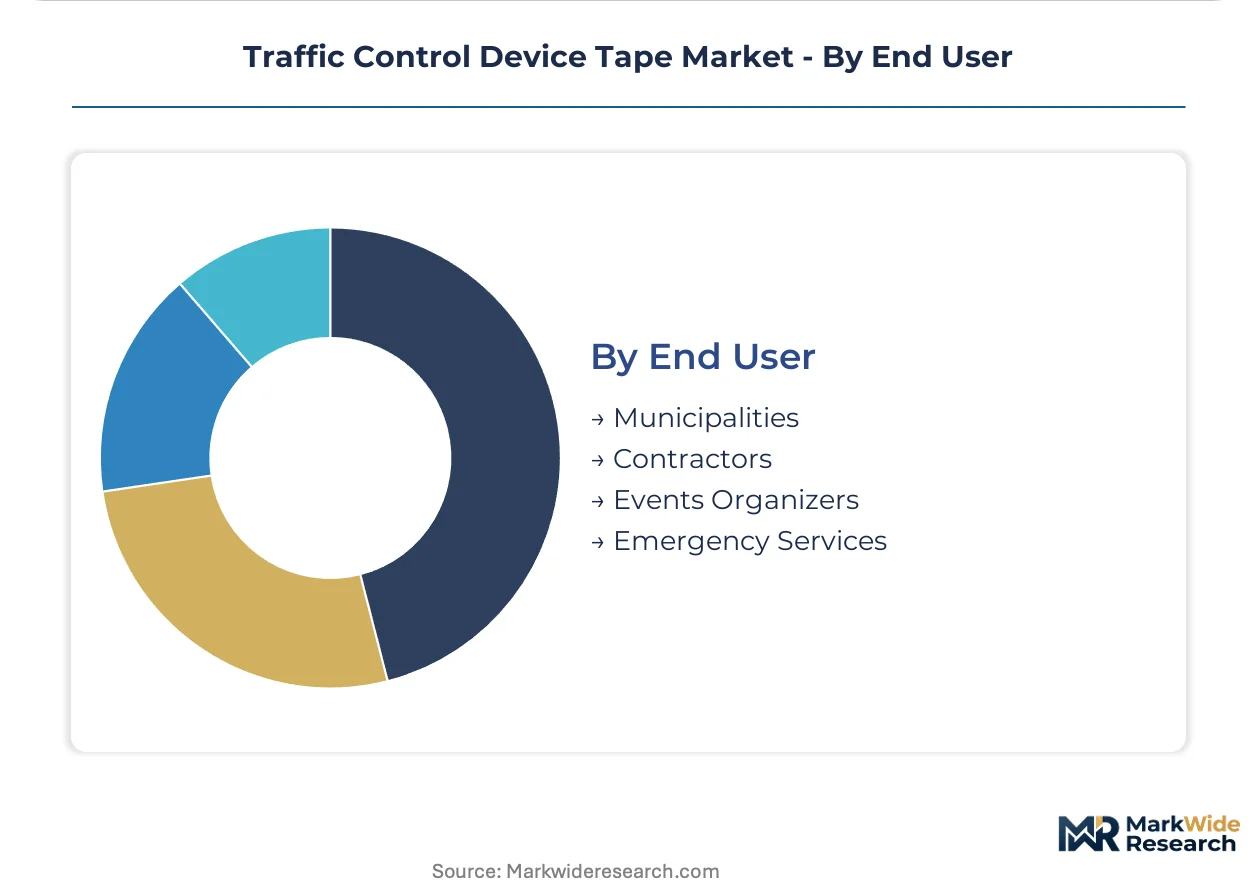
Customer type determines procurement channel and specification rigor: municipalities enforce certified compliance, while emergency services prioritize deployment speed over documentation depth.
- Municipalities:City and county transportation departments enforce FHWA-compliant specifications with documented retroreflectivity testing. Texas, Florida, and California DOTs concentrate procurement volume through competitive bidding with 8-14 month qualification timelines for new adhesive formulations. Budget expansion in these three states outpaces national averages.
- Emergency Services:Fire departments and disaster response agencies favor rapid-deployment barrier and tape systems with minimal setup requirements. Florida hurricane response contractors specify pre-assembled kits for staging area deployment. Speed of deployment outweighs certification documentation in procurement criteria.
- Contractors:Road construction and utility maintenance firms purchase through distributor relationships with volume pricing.
- Events Organizers:Venue operators and festival producers specify DOT-grade materials for liability protection despite temporary installation duration.
Contractors move baseline volume; emergency services expand most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of retroreflective films concentrates among specialized converters in the United States Midwest and Southeast, while consumption patterns track state DOT budget cycles most aggressively in Texas, Florida, and California. This geographic mismatch between manufacturing capacity and demand intensity shapes inventory logistics and distributor positioning across North America.
United States
Texas, Florida, and California DOTs dominate procurement volume through multi-year framework agreements for smart intersection upgrades. The Federal Highway Administration's updated MUTCD compliance deadlines are compressing replacement cycles nationwide. Houston and Dallas-Fort Worth metropolitan areas concentrate emergency services contractor demand for rapid-deployment barrier systems.
Canada
Provincial transportation ministries in Ontario and Quebec are adopting FHWA-aligned retroreflectivity standards for cross-border highway consistency. Infrastructure Canada programs are expanding municipal maintenance budgets for marking tape replacement. The Greater Toronto Area anchors distributor consolidation as bundled procurement contracts gain traction.
Mexico
Federal highway modernization programs are importing specification-grade reflective tapes for toll road upgrades. State governments in Nuevo León and Jalisco are professionalizing work zone safety protocols. Monterrey industrial corridors are attracting adhesive tape converters serving both domestic demand and re-export to Central America.
Germany
The KBA enforces stringent retroreflective performance standards for temporary traffic control materials on federal autobahns. Industrial clusters in North Rhine-Westphalia host precision film coating operations supplying European DOTs. Bavarian municipal buyers are specifying weather-resistant formulations for alpine climate durability.
China
MIIT standards for highway safety products are tightening retroreflective performance thresholds for domestic manufacturers. Yangtze River Delta provinces concentrate glass bead and prismatic film production capacity. Guangdong infrastructure investment is accelerating demand for DOT-grade marking tapes in smart city pilot zones.
Traffic Control Device Tape Market Competitive Landscape
The competitive structure tilts toward technology-differentiated specialists rather than commodity producers. Three to five specialized converters dominate premium prismatic film production, while regional adhesive formulators compete on price for standard glass bead applications. Two strategic archetypes define positioning: reflective technology leaders commanding specification-tier pricing, and rapid-deployment system integrators capturing bundled procurement contracts. Dominant competitive moves include vertical integration into coating operations and strategic partnerships with state DOT pre-qualification consultants.
Within the technology-leader tier, 3M and Nitto Denko occupy positions anchored by reflective material science capabilities and advanced adhesive formulations respectively. Advance Tapes represents the rapid-deployment system integrator archetype, bundling tape with barriers and cones for emergency services procurement channels. These three companies exemplify how competitive positioning splits between specification-driven premium tiers and speed-to-deploy operational models.
| Leading Market Players |
|---|
| 3M |
| Kruse Adhesive Tape |
| Nitto Denko |
| Vibac |
| Advance Tapes |
| Harris Industries |
| Hultafors Group |
| Scapa Group |
| Berry Global |
| Others |
Value Network & Pricing Analysis
FHWA retroreflectivity compliance deadlines gate qualified supply and premium-tier pricing access, compressing state DOT procurement timelines and filtering smaller adhesive formulators from certified product participation. Municipal buyers in Texas and California now pre-qualify suppliers with existing compliance documentation, creating pricing power concentration among pre-certified converters.
Pricing Analysis
Price erosion across standard glass bead tiers traces to acrylic resin feedstock volatility and commoditized municipal procurement. Three-tier pricing structure across prismatic premium, glass bead standard, and non-reflective economy levels separates specification-grade compliance from basic daytime marking. Price differentiation centers on FHWA certification tier and volume scale in multi-year framework agreements. Contractors prove most price-sensitive; emergency services contractors accept premium pricing for deployment speed.
Supply Chain Analysis
Distribution runs through specialized converters in the US Midwest and Southeast feeding state DOT distributors and emergency services contractors. Raw material dependencies center on retroreflective glass beads, microprismatic films, and pressure-sensitive acrylic adhesives. Single-source vulnerability concentrates in premium prismatic film production among three specialized Midwest converters. Tariff exposure on Asian-sourced glass beads and petrochemical-derived adhesives amplifies input cost uncertainty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FHWA compliance deadlines compress qualification timelines, forcing smaller adhesive formulators without pre-certified product lines toward exit or acquisition.
For Market Incumbents: Deploy backward integration into coating operations to secure captive supply of prismatic films and reduce exposure to Midwest converter concentration. Invest in accelerated state DOT pre-qualification consulting to compress 8-14 month certification timelines in Texas and California. Defend against rigid delineator substitution in high-wind corridors by bundling tape with ballasted barrier systems. For New Entrants and Emerging Players: Capture event management vertical white space in California outdoor venue operations where DOT-grade specifications apply but procurement documentation requirements remain lighter than municipal channels. Target hurricane belt weather-resistant formulations in Florida and Gulf Coast states where extended durability commands price premiums and incumbent coverage gaps persist. Enter through rapid-deployment kit partnerships with emergency services distributors rather than direct state DOT bidding. For Investors and Strategic Acquirers: State DOT pre-qualification announcement clustering is the leading indicator that adhesive formulator distress will accelerate, creating acquisition opportunity windows. Long-term viability favors vertically integrated converters with in-house prismatic film production and established FHWA compliance documentation. Monitor Texas DOT framework agreement renewal cycles for distressed supplier signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prismatic Film Coating | Reduces single-source dependency on Midwest converters and secures margin control for FHWA-certified product lines. |
| State DOT Pre-Qualification Investment | Compresses 8-14 month certification barriers in Texas and California, locking out smaller adhesive formulators. |
| Modular Kit Assembly Capability | Captures bundled procurement contracts displacing pure-play tape suppliers in municipal and emergency services channels. |
| Weather-Resistant Formulation R&D | Addresses Florida and Gulf Coast hurricane belt durability premiums with extended service life claims. |
| Emergency Services Distributor Partnership | Opens rapid-deployment channels where deployment speed outweighs certification depth in procurement criteria. |
Research Methodology
Multi-period observation of state DOT budget allocations, FHWA compliance deadline clustering, and adhesive formulation patent filings anchored the trend analysis, supplemented by interviews with municipal procurement officers, emergency services contractors, reflective film coating plant managers, and DOT specification engineers. Secondary validation drew from FHWA MUTCD documentation, state DOT supplement amendments, US customs trade data on glass bead imports, and SEC filings of listed adhesive material suppliers. Bottom-up volume triangulation across product type segments was cross-checked against top-down state DOT expenditure forecasts.
Input-output matrices modeled retroreflective performance tier adoption, application vertical penetration, and end-user procurement channel shifts across the projection horizon. Segmentation dimensions included product type, reflective technology tier, application vertical, and end-user category. CAGRs were derived from elasticity-weighted regression against state DOT budget expansion rates and compliance-driven replacement cycle compression. Industry-specific forecast inputs incorporated petrochemical feedstock price indices and hurricane season severity correlations for weather-resistant formulation demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FHWA standard amendment timing and acrylic resin supply disruptions. Forecasts reflect documented assumptions on state budget continuity and certification timeline stability. Practitioners should monitor Texas and California DOT supplement amendment announcements and Midwest converter capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Truck Axle Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Grille Guard Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Truck Suspension System Market