
 Automotive Towbar Market | 2026-2036
Automotive Towbar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Towbar Market Intelligence
The EU Green Deal is pivoting automotive accessory procurement toward lower-emission, lightweight towing solutions across member states. Westfalia-Automotive GmbH leverages its German engineering heritage to dominate detachable towbar production with TÜV-certified systems. Horizon Global Corporation anchors North American distribution through dense aftermarket channel control. Thule Group AB differentiates via premium brand positioning in the recreational vehicle accessory ecosystem.
An automotive towbar is a chassis-mounted coupling device, typically forged from high-tensile steel or extruded aluminum alloy, designed to transmit trailer loads through a vehicle's frame while maintaining statutory ground clearance. Its primary commercial purpose centers on enabling legally compliant towing for cargo, leisure, and utility applications across passenger and light commercial fleets. Fixed towbars retain cost leadership in fleet and commercial segments where permanent installation justifies durability over convenience. Detachable towbars command expanding share among premium SUV owners seeking aesthetic preservation when towing is inactive. Aluminum material grades gain traction as OEMs pursue mass reduction to offset trailer payload penalties against CO2 targets.
Type approval frameworks including ECE R55 in Europe, NHTSA Federal Motor Vehicle Safety Standard 223 in the United States, and Australia's ADR 62/02 govern towbar design, testing protocols, and market access. These standards enforce minimum breakaway strengths, fatigue cycles, and marking requirements that elevate compliance costs for new entrants while protecting incumbent specialists. Stakeholders must monitor evolving homologation reciprocity between jurisdictions as regional trade agreements reshape certification burden distribution.
Market Dynamics
EU F-Gas Regulation and vehicle emissions frameworks are compressing permissible towbar weights, forcing aluminum-forged designs to displace traditional steel across OEM supply chains.
Growth Catalysts
- Caravan Tourism Expansion:Recreational vehicle ownership across Western Europe sustains premium detachable towbar demand as camping infrastructure densifies in Germany and France.
- ECE R55 Type Approval:Harmonized European testing protocols for breakaway strength and fatigue cycles reduce cross-border certification costs for compliant manufacturers.
- Lightweight Material Substitution:Extruded aluminum alloys enable mass reduction that offsets trailer payload penalties against tightening CO2 fleet targets.
Market Restraints
- Steel Price Volatility:High-tensile steel input costs fluctuate with scrap metal and energy pricing, compressing margins on fixed towbar production lines.
- TÜV Certification Concentration:German technical inspection associations control premium market access, creating bottleneck risk for non-domestic entrants seeking credibility.
- Homologation Fragmentation:NHTSA Federal Motor Vehicle Safety Standard 223, Australia's ADR 62/02, and ECE R55 maintain non-reciprocal testing requirements that duplicate compliance spend.
Strategic Opportunities
- Electric Vehicle Towing Compatibility:Range-conscious EV buyers seek aerodynamic, quick-detach systems that minimize drag penalty during non-towing operation.
- Aftermarket Channel Digitization:Direct-to-consumer fitment databases and VIN-matched configuration tools bypass traditional distributor markup layers.
- EU Green Deal Procurement:Public fleet tenders increasingly weight lifecycle carbon metrics, favoring suppliers with verified aluminum sourcing and regional manufacturing.
Industry Challenges
- Homologation Engineer Scarcity:Specialized expertise in ECE R55 fatigue testing and documentation is concentrated among aging specialists in Stuttgart and Munich engineering consultancies.
- Legacy Fleet Integration:Retrofit demand from aging commercial vehicle pools requires backward-compatible mounting interfaces that conflict with modular platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Towbar Market |
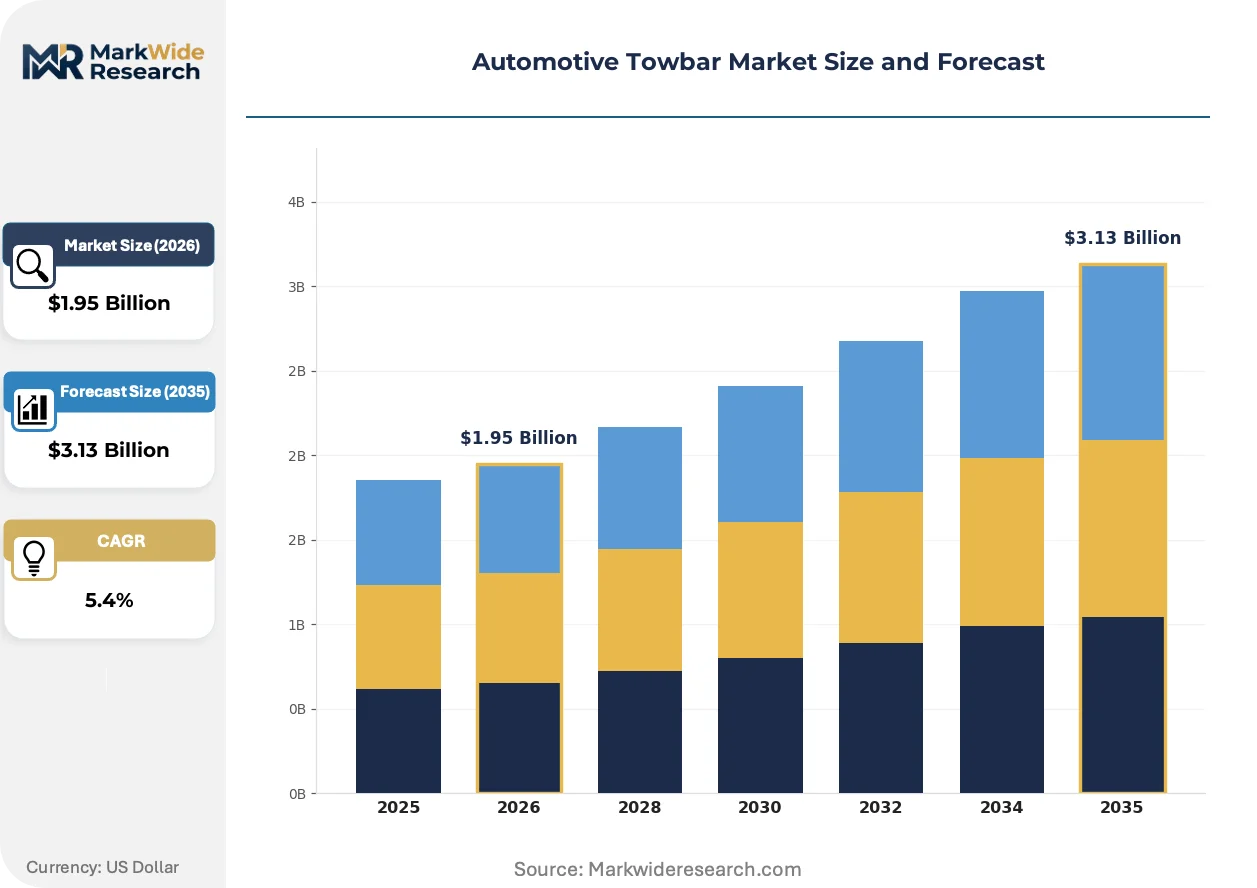
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Towbars, Detachable Towbars, Swan Neck Towbars, Adjustable Towbars Material: Steel, Aluminum, Polymer, Composite Vehicle Type: SUVs, Trucks, Vans, Passenger Cars Installation Method: Bolted, Welded, Clamp-on, Universal Fit |
| Companies Covered | Westfalia-Automotive GmbH, Hayman Reese Pty Ltd., Horizon Global Corporation, GDW N.V., PCT Automotive Ltd., Bosal International N.V., CURT Manufacturing LLC, Thule Group AB, Brink Group B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Towbar Market Strategic Shifts & Innovations
Active safety systems and powertrain electrification are rewiring towbar design priorities, shifting engineering resources from static load capacity toward dynamic vehicle integration.
Aluminum extrusion with integrated sensor mounting points is integrating crash-avoidance radar and camera hardware directly into towbar neck structures. Premium SUV manufacturers in Germany and the United Kingdom are specifying these smart-ready variants for new platform launches. This convergence is integrating towbars into ADAS architecture, elevating them from passive mechanical components to active safety system substrates.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant containment requirements that indirectly pressure total vehicle mass budgets. Towbar suppliers must now document aluminum grade provenance and recycled content ratios for OEM sustainability scorecards. Light commercial fleets in France and Italy face the steepest compliance timelines, driving expedited supplier qualification processes.
Recreational buyers increasingly self-install detachable systems using manufacturer-provided torque-limited tools and smartphone-guided alignment applications. Traditional workshop channel dependence is eroding among caravan owners aged 35-50 across Scandinavia and the Low Countries. Germany retains higher professional fitment rates due to TÜV inspection stringency, but digital configuration confidence is compressing service revenue pools elsewhere.
Automotive Towbar Market Segmentation
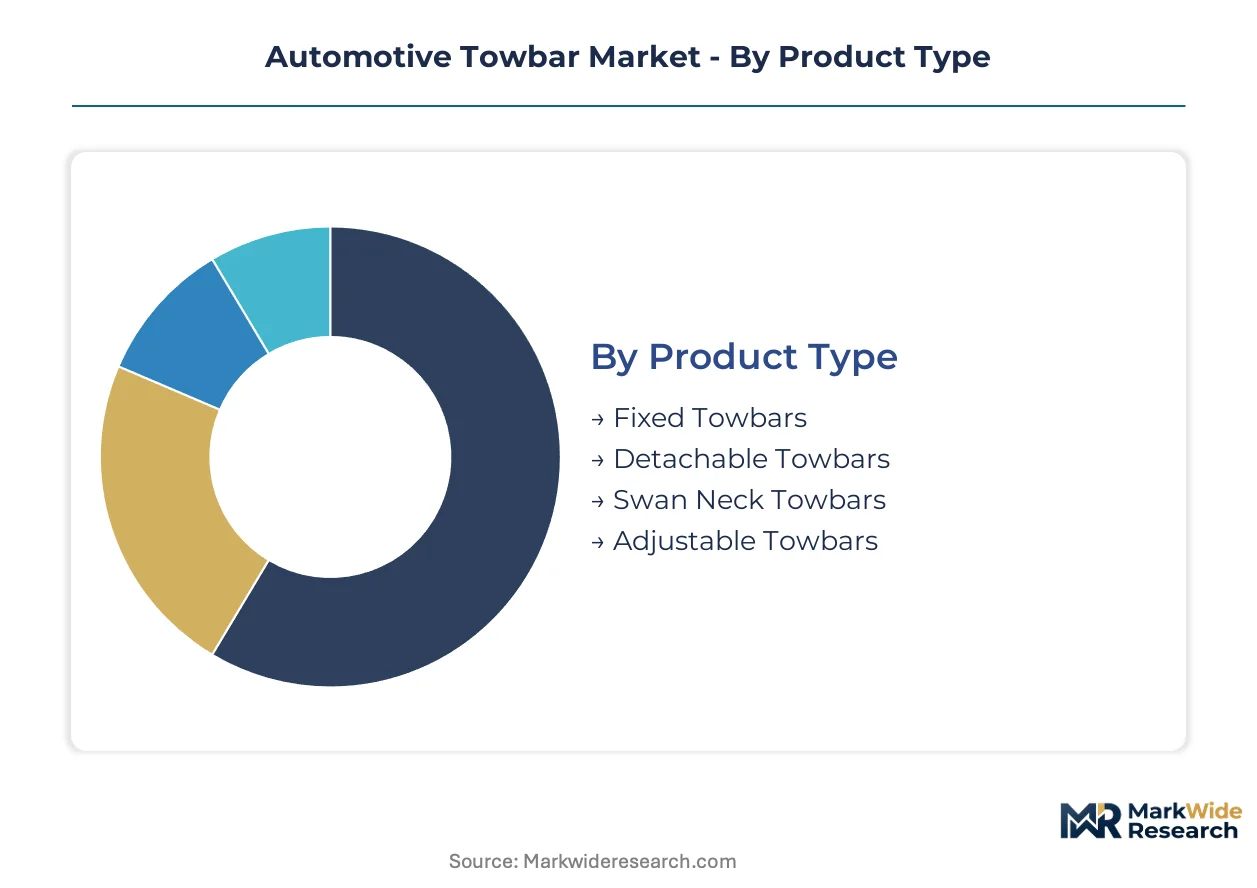
Towbar purchasing decisions pivot on installation permanence, material weight trade-offs, and vehicle platform compatibility. Fleet operators, recreational buyers, and OEM procurement teams each prioritize distinct performance attributes that fragment supplier specialization across the value chain.
Product Type:
Installation permanence drives buyer selection between convenience and structural integrity for commercial versus leisure applications.
- Fixed Towbars:Permanent steel or aluminum assemblies bolted directly to vehicle chassis rails deliver maximum load ratings for commercial fleet operators. Demand concentrates in French and Italian light commercial vehicle pools where ECE R55 certification mandates documented fatigue resistance for continuous heavy-duty cycling.
- Detachable Towbars:Quick-release neck mechanisms enable aesthetic preservation when towing is inactive, commanding premium positioning among German SUV owners. Camping infrastructure density in Bavaria and Baden-Württemberg sustains uptake as caravan tourism expands across Western Europe.
- Swan Neck Towbars:Integrated ball-and-neck designs reduce protrusion depth for parking sensor compatibility.
- Adjustable Towbars:Variable height mechanisms accommodate diverse trailer couplings across mixed-use fleets.
Volume sits with fixed systems in commercial applications; growth tilts toward detachable configurations in premium consumer segments.
Material:
Mass reduction imperatives under EU emissions frameworks are reallocating procurement specifications across OEM supply chains.
- Steel:High-tensile forged grades retain cost leadership in fixed towbar production for price-sensitive fleet segments. Scrap metal and energy price volatility compress margins on legacy production lines serving Eastern European commercial vehicle assemblers.
- Aluminum:Extruded alloys enable mass reduction that offsets trailer payload penalties against tightening CO2 fleet targets. German premium SUV manufacturers specify aluminum-forged variants for new platform launches to satisfy EU Green Deal sustainability scorecards.
- Polymer:Reinforced thermoplastic housings protect electrical connections in corrosive environments.
- Composite:Carbon fiber reinforced structures serve prototype and motorsport applications with extreme weight sensitivity.
Steel dominates installed base volume; aluminum claims the steepest expansion trajectory as electrified powertrains intensify mass constraints.
Vehicle Type:
Platform architecture and payload ratings determine towbar specification hierarchies across passenger and commercial categories.
- SUVs:Elevated ride heights and reinforced frame rails support higher braked trailer ratings, making these platforms the primary attach point for detachable systems. German, UK, and Swedish manufacturers lead specification of smart-ready variants with integrated ADAS sensor mounting.
- Trucks:Heavy-duty frame constructions accommodate gooseneck and fifth-wheel alternatives that exceed conventional towbar load envelopes.
- Vans:Transverse engine layouts and unibody construction limit maximum ratings but sustain volume in last-mile delivery fleets.
- Passenger Cars:Compact chassis constraints restrict towing capacity to lightweight trailers in Southern European markets.
Commercial volume aggregates in van and truck categories; SUV applications generate the fastest-growing revenue pool.
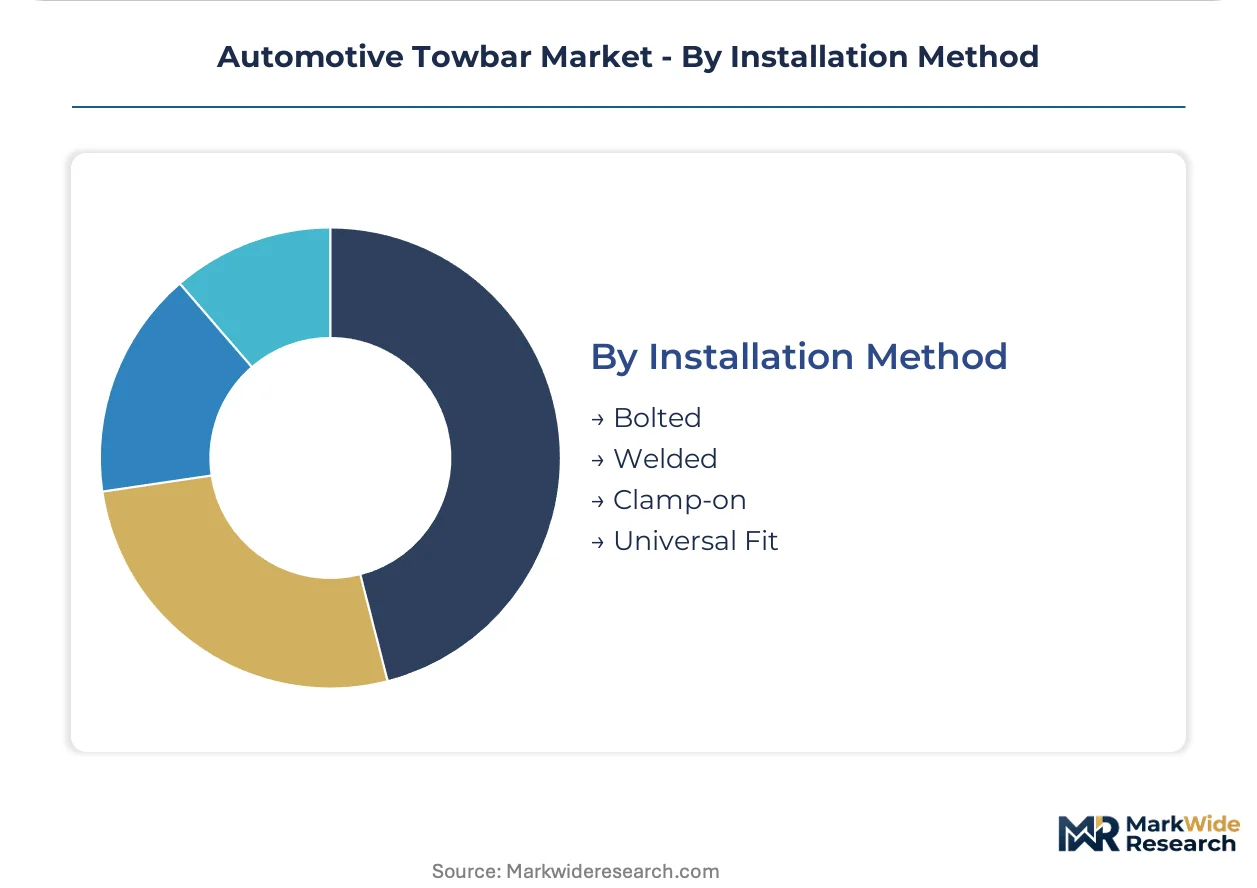
Installation Method:
Fitment labor intensity and regulatory inspection requirements shape channel economics across do-it-yourself and professional service routes.
- Bolted:Chassis rail mounting with torque-specified hardware enables reversible installation and TÜV-compliant documentation for German vehicle owners. Scandinavian and Benelux recreational buyers increasingly self-install using manufacturer-provided torque-limited tools and smartphone-guided alignment applications.
- Welded:Permanent fusion to frame structures delivers maximum load transfer for agricultural and construction equipment towing.
- Clamp-on:Temporary attachment systems serve rental fleet and emergency recovery applications without permanent modification.
- Universal Fit:Adjustable bracketry accommodates multiple vehicle platforms in aftermarket distribution with reduced SKU complexity.
Bolted methods capture the majority of permanent installations; universal fit systems are gaining share fastest in digital direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European towbar engineering concentration, hosting specialist consultancies that validate ECE R55 fatigue testing protocols for OEM supply chains.
Germany
Bavarian camping infrastructure density sustains premium detachable towbar uptake among SUV owners. TÜV certification requirements enforce strict documentation standards that protect incumbent specialists. Stuttgart engineering clusters dominate ECE R55 validation services, creating bottleneck access for foreign entrants seeking credibility.
United States
Aftermarket channel density supports broad fixed towbar distribution across light commercial fleets. NHTSA Federal Motor Vehicle Safety Standard 223 governs breakaway strength testing distinct from European protocols. Midwest manufacturing corridors concentrate stamping and forging capacity for domestic OEM supply.
France
Light commercial fleet electrification timelines accelerate aluminum-forged procurement specifications. EU Green Deal sustainability scorecards weight lifecycle carbon metrics in public tender evaluations. Lyon industrial zones host aluminum extrusion specialists serving premium SUV platform launches.
United Kingdom
Smart-ready towbar variants with integrated ADAS sensor mounting gain specification from premium SUV manufacturers. Vehicle certification agency alignment with ECE R55 reduces cross-border homologation friction. Midlands manufacturing bases retain steel forging heritage for commercial vehicle applications.
Australia
ADR 62/02 maintains non-reciprocal testing requirements that duplicate compliance spend for imported systems. Recreational towing culture sustains aftermarket demand across remote territory touring applications. Melbourne engineering consultancies specialize in fatigue cycle documentation for regional type approval.
Automotive Towbar Market Key Industry Players
The competitive structure tilts toward engineering-led specialists with proven type approval track records. Incumbent dominance reflects concentrated homologation expertise rather than scale economies. Three archetypes occupy distinct positions: TÜV-certified German system houses, North American aftermarket distributors with dense channel control, and Nordic recreational accessory platforms with premium brand positioning. Strategic moves center on aluminum grade qualification for OEM sustainability scorecards and direct-to-consumer fitment database deployment.
Among German engineering-led specialists, Westfalia-Automotive GmbH and Brink Group B.V. occupy positions anchored by TÜV validation heritage and ECE R55 documentation depth. North American aftermarket presence concentrates around Horizon Global Corporation, which exemplifies channel-scale archetypes with broad distribution infrastructure. These three represent contrasting competitive vectors: certification credibility, manufacturing scale, and route-to-market density.
| Leading Market Players |
|---|
| Westfalia-Automotive GmbH |
| Hayman Reese Pty Ltd. |
| Horizon Global Corporation |
| GDW N.V. |
| PCT Automotive Ltd. |
| Bosal International N.V. |
| CURT Manufacturing LLC |
| Thule Group AB |
| Brink Group B.V. |
| Others |
Cost & Logistics Intelligence
Aluminum extrusion adoption for ECE R55-compliant towbar necks simultaneously compresses per-unit material costs and concentrates forging capacity among German and Austrian system houses. This technology transition rewards incumbents with qualified alloy grades while locking out price-competitive Asian suppliers lacking TÜV validation heritage.
Pricing Analysis
TÜV certification grade anchors value-based pricing across the automotive towbar market. Three-tier pricing structure across premium detachable, standard fixed, and economy universal-fit levels segments buyers by installation permanence and documentation depth. Price differentiation stems from fatigue-test documentation stringency and aluminum grade provenance. Cost compression in economy steel fixed towbars is intensifying because Eastern European fleet procurement teams prioritize breakaway strength ratings over brand heritage. Light commercial operators exhibit highest price sensitivity; German premium SUV owners demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with high-tensile steel scrap suppliers in Germany and Poland. Geographic supply concentration clusters in Germany, Austria, and the Czech Republic for ECE R55-validated forging and extrusion capacity. Raw material dependencies center on 6000-series aluminum billets, high-tensile steel scrap, and torque-specified fastener grades. Supply chain risk from regulatory restriction manifests in EU F-Gas Regulation mass budgets that disqualify non-compliant aluminum sourcing. Distribution runs through OEM direct supply agreements and dense aftermarket distributor networks across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Homologation engineer scarcity in Stuttgart and Munich engineering consultancies props pricing for TÜV-certified towbar systems, constraining supply expansion regardless of aluminum forging capacity additions.
For Market Incumbents: Anticipate aluminum grade qualification races as EU Green Deal sustainability scorecards harden recycled content requirements. Defensive consolidation should prioritize backward integration into aluminum extrusion to secure billet supply. Threat from Chinese forged steel competitors lacking ECE R55 documentation depth demands certification investment as the priority lever. For New Entrants and Emerging Players: The 40-60% price-point gap between premium German detachable systems and economy Eastern European fixed towbars opens white-space at the mid-tier aluminum fixed segment. Most penetrable target sits with French and Italian light commercial fleets facing accelerated electrification timelines. Go-to-market angle should emphasize direct-to-consumer VIN-matched fitment databases that bypass traditional distributor markup layers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive Tier 1 suppliers seeking towbar integration capabilities for ADAS-equipped platform launches. Long-term viability favors specialists with documented ECE R55 fatigue testing heritage and aluminum grade qualification track records. Signal to watch is OEM sustainability scorecard adoption rates accelerating supplier consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Grade Qualification | EU Green Deal scorecards reward verified recycled content ratios from Austrian and German extruders. |
| Direct-to-Consumer Fitment Database | VIN-matched configuration tools bypass distributor markup and capture caravan owner self-install demand. |
| ADAS Sensor Integration | Smart-ready towbar variants with radar mounting points penetrate premium SUV platform specifications. |
| TÜV Certification Investment | Documentation depth protects pricing power against unvalidated competitors from Eastern Europe. |
| Backward Integration into Extrusion | Captive aluminum billet supply secures mass reduction roadmaps under tightening CO2 fleet targets. |
Research Approach
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and TÜV validation engineers underwrites the qualitative findings. Primary interviews with these stakeholders combined trade data from German automotive industry associations, ECE R55 type approval registries, and customs extrusion import records. Secondary validation drew from EU F-Gas Regulation implementation documents, vehicle production databases, and aluminum industry sustainability disclosures. Bottom-up towbar unit estimates and top-down accessory spending allocations triangulate market sizing.
Rate-of-change decomposition across vehicle class, propulsion architecture, installation method, and regional regulatory cluster anchors the forecast framework. Segmentation dimensions modeled include fixed versus detachable product types, steel versus aluminum material grades, and bolted versus welded installation methods across the projection horizon. CAGRs derive from fitted growth curves applied to penetration rates by vehicle segment. Industry-specific inputs encompass EU fleet CO2 target stringency indices and caravan tourism infrastructure investment pipelines.
Inputs from TÜV validation registries and OEM platform engineering disclosures were available through the study window; gaps in real-time aluminum scrap pricing volatility introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding regulatory timeline adherence and electrified powertrain towing compatibility adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Actuators Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Turkey Automotive Plastic Compounding Market