
 Automotive Exhaust System Market | 2026-2036
Automotive Exhaust System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust System Market Intelligence
OEM buyer concentration is hardening as top automakers consolidate supplier rosters toward full-system integrators. Tenneco Inc. leverages its monolith coating capabilities to anchor long-term platform contracts with North American truck manufacturers. Eberspächer sustains engineering leadership in heated exhaust components through dedicated R&D centers in Germany and China.
An automotive exhaust system channels combustion gases away from the engine, incorporating catalytic substrates with precious-metal washcoats that facilitate reduction and oxidation reactions at operating temperatures exceeding 400°C. Its primary commercial purpose is emissions compliance and acoustic attenuation before atmospheric release. Catalytic converters command the deepest margin pools due to platinum-group-metal content and precision substrate manufacturing, while hybrid system integration represents the fastest-growing technology segment as electrified powertrains require thermal management of dual exhaust streams. Passenger cars remain the volume anchor, though heavy trucks generate superior per-unit value through larger substrate volumes and multiplex after-treatment stages.
The US EPA and California Air Resources Board enforce tailpipe standards that directly determine catalyst cell density and sensor architecture requirements for market access. Euro 7 proposals from the European Commission mandate real-world emission monitoring, forcing hardware redesigns for cold-start performance. Stakeholders must monitor how China's Ministry of Ecology and Environment aligns domestic standards with European test cycles, as this alignment determines which suppliers qualify for the world's largest vehicle production base.
Market Dynamics
OEM procurement consolidation is compressing supplier margins as automakers reduce approved vendor lists and award full-system contracts to integrators with captive coating and substrate capabilities. This concentration dynamic is restructuring competitive positioning across the value chain.
Growth Catalysts
- Euro 7 cold-start mandates:The European Commission's real-world emission monitoring requirements are forcing hardware redesigns that expand substrate volume and sensor density in new vehicle platforms.
- Platinum-group-metal recovery:Advanced washcoat formulations with higher palladium loading are extending catalyst service intervals while meeting tighter particulate thresholds.
- China's MEE alignment:The Ministry of Ecology and Environment's harmonization with European test cycles is qualifying European suppliers for the world's largest vehicle production base.
Market Restraints
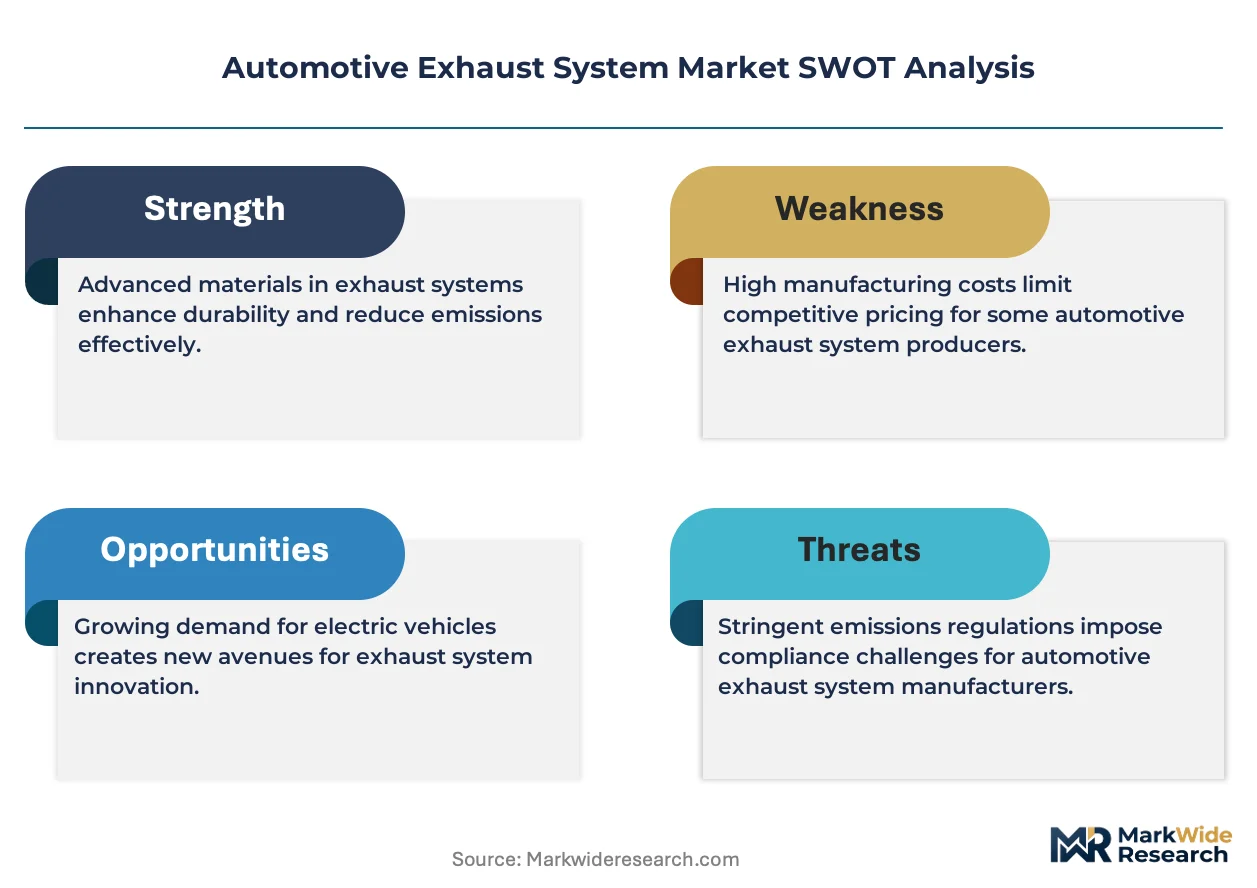
- Rhodium supply concentration:South African mining output constraints and Russian export friction are creating input cost volatility for three-way catalyst formulations.
- Substrate manufacturing bottlenecks:Cordierite and silicon carbide monolith production is concentrated among three global suppliers, creating single-source risk for tier-two integrators.
- Hybrid thermal management complexity:Dual exhaust stream architectures in electrified powertrains require parallel development paths that fragment engineering resources.
Strategic Opportunities
- India's BS-VI Phase II enforcement:The country's tightening particulate matter limits for commercial vehicles is opening procurement windows for suppliers with heavy-duty after-treatment expertise.
- Sensor-catalyst convergence:Integration of NOx and particulate matter sensors directly into substrate housings is creating value-added system architectures.
- California ZEV credit arbitrage:CARB's enhanced compliance credit values for near-zero emission powertrains are incentivizing premium catalyst configurations in light-truck segments.
Industry Challenges
- Computational fluid dynamics talent scarcity:Exhaust system thermal modeling requires specialized simulation expertise that competes with battery thermal management hiring pools.
- Homologation timeline compression:Euro 7's real-driving emissions testing protocols are extending certification cycles by eight to twelve months for new platform launches.
- Legacy ICE service part rationalization:Declining internal combustion production volumes are complicating aftermarket inventory planning and warranty reserve calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust System Market |
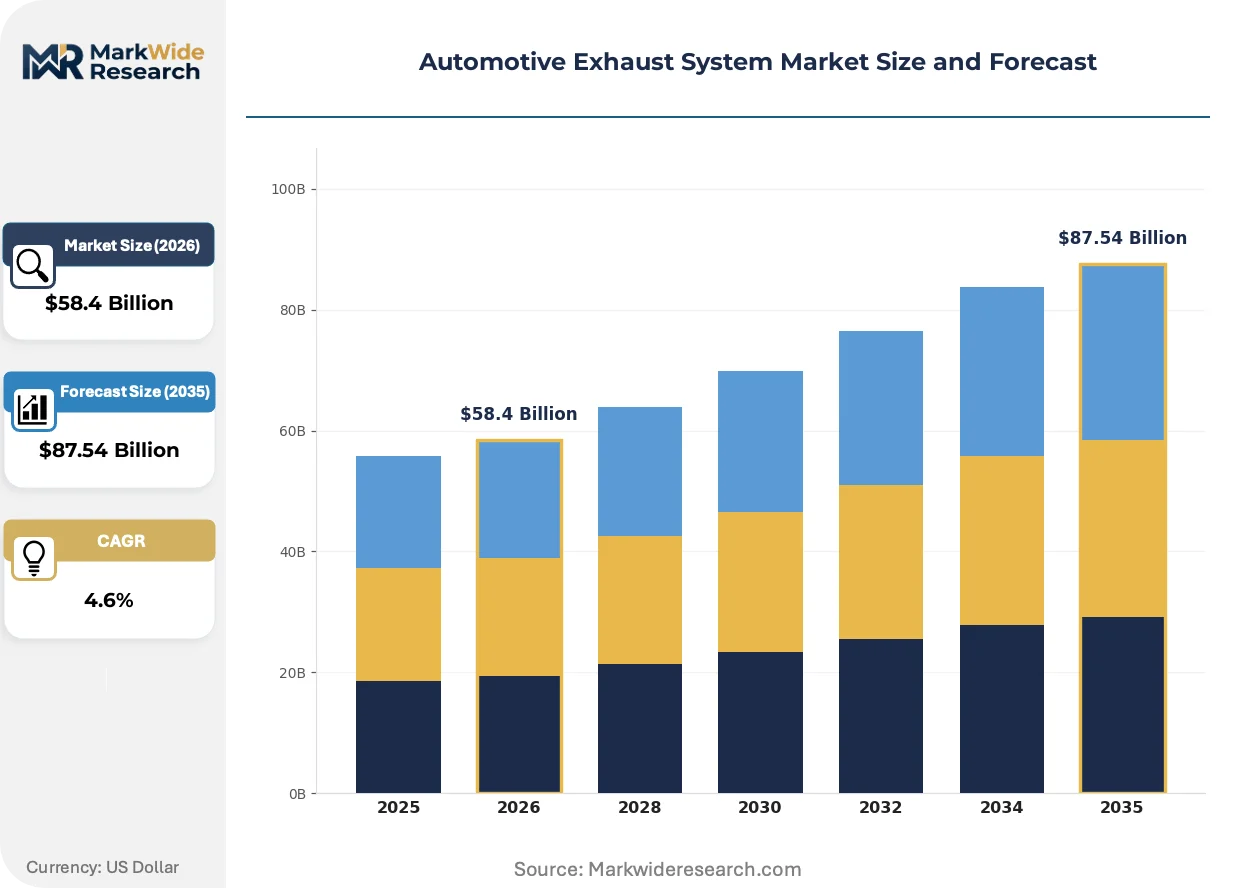
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $87.54 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Exhaust Manifolds, Catalytic Converters, Mufflers, Resonators Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Buses Material: Stainless Steel, Aluminized Steel, Titanium, Cast Iron Technology: Direct Injection, Turbocharging, Hybrid Systems, Supercharging |
| Companies Covered | Forvia Faurecia, Tenneco Inc., Continental AG, Eberspächer, Futaba Industrial Co., Ltd., BENTELER International, BOSAL, Sejong Industrial Co., Ltd., Friedrich Boysen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust System Market Strategic Shifts & Innovations
Active thermal management architectures are displacing passive exhaust configurations as electrified powertrains impose new temperature control requirements. This shift is compressing development cycles and unifying previously separate engineering disciplines.
Electrically heated catalysts are unifying cold-start emission control with battery thermal management in plug-in hybrid architectures. European luxury OEMs are adopting these systems for 48-volt mild-hybrid platforms ahead of Euro 7 enforcement. The technology is unifying exhaust and powertrain thermal domains, eliminating separate pre-catalyst heating hardware and reducing system mass.
The EPA's Tier 3 particulate matter standards are mandating gasoline particulate filters across light-duty segments previously exempt from diesel-style after-treatment. Cell density requirements above 600 cpsi are compressing substrate manufacturing yields and qualifying only advanced cordierite formulations. Passenger car platforms in the United States are responding with close-coupled filter-catalyst combinations that package within existing tunnel clearances.
Fleet operators are consolidating supplier relationships through direct sourcing contracts that bypass traditional tier-one integrators. Large commercial buyers in Germany and the United States are negotiating platform-level agreements with coating specialists for standardized after-treatment modules. This channel compression is most visible in heavy-truck segments where total cost of ownership calculations dominate specification decisions.
Automotive Exhaust System Market Segmentation
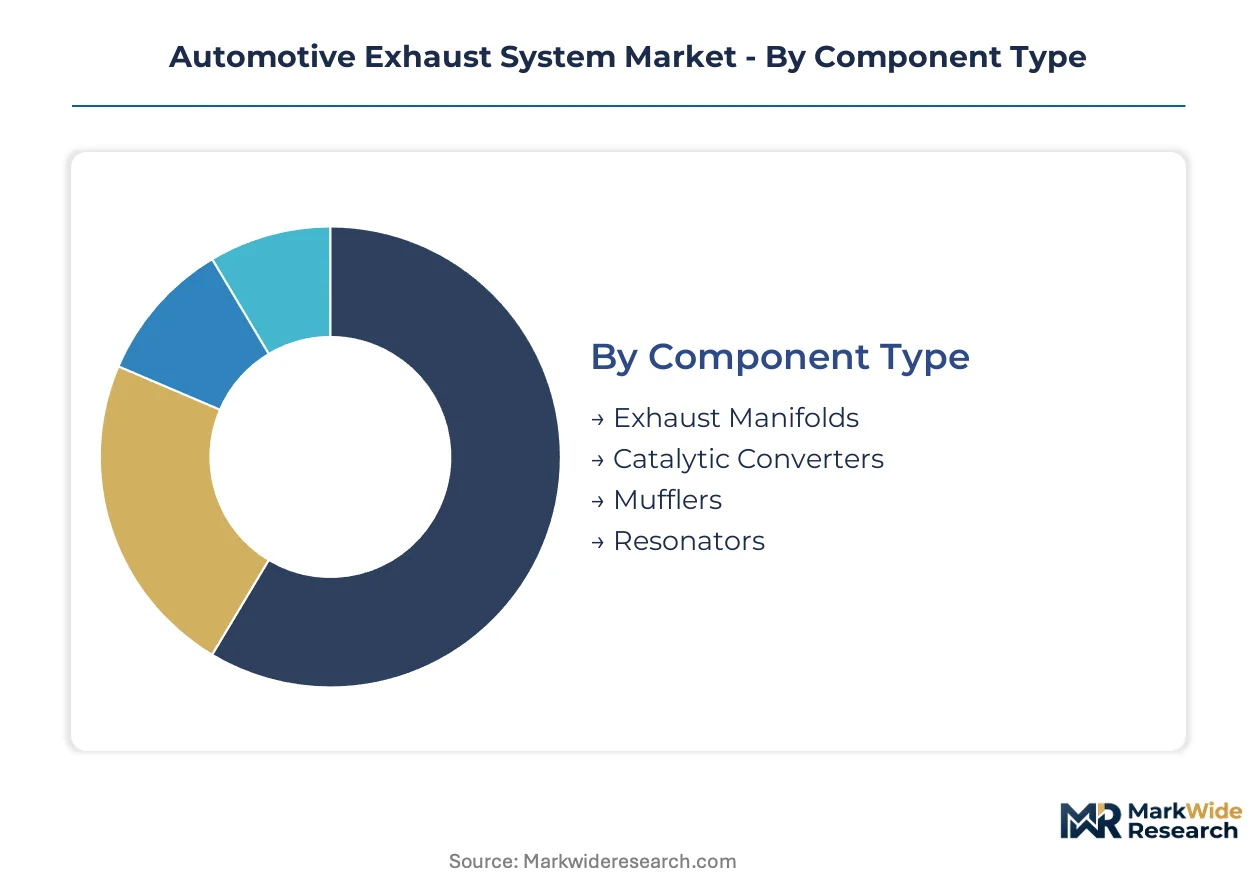
Exhaust system architectures vary dramatically across powertrain configurations and duty cycles, with substrate cell density, catalyst loading, and thermal management requirements diverging by application. Component selection and material specification directly determine compliance margins and platform homologation timelines.
Component Type:
Catalytic substrates and acoustic attenuation hardware anchor system value, with precious-metal washcoat formulations commanding disproportionate margin concentration.
- Catalytic Converters:Ceramic or metallic monolith substrates carry platinum-group-metal washcoats that facilitate reduction and oxidation reactions above 400°C. Heavy trucks in Germany and the United States drive demand for multiplex after-treatment stages with expanded substrate volumes.
- Exhaust Manifolds:Cast iron or stainless steel headers channel combustion gases from cylinder heads into downstream after-treatment. Passenger car platforms concentrate procurement toward integrated turbocharger-manifold castings that reduce thermal mass and improve cold-start response.
- Mufflers:Perforated tube and chamber designs attenuate pressure wave propagation through acoustic impedance matching. Light commercial vehicle fleets specify stainless steel variants for extended service intervals in high-utilization duty cycles.
- Resonators:Helmholtz chamber configurations target specific frequency cancellation without excessive backpressure penalty. Buses and coaches integrate these elements to meet urban noise ordinances in Chinese megacities.
Catalytic converters lead on scale; hybrid thermal management architectures lead on momentum.
Vehicle Type:
Per-unit value and after-treatment complexity scale with vehicle mass and emission certification stringency.
- Passenger Cars:Close-coupled catalyst configurations dominate front-wheel-drive platforms with tunnel packaging constraints. EPA Tier 3 particulate matter standards are mandating gasoline particulate filters across light-duty segments previously exempt from diesel-style after-treatment.
- Heavy Trucks:Selective catalytic reduction and diesel particulate filter combinations generate superior per-unit value through larger substrate volumes and multiplex sensor architectures. Fleet operators in the United States negotiate platform-level agreements directly with coating specialists.
- Light Commercial Vehicles:Modular after-treatment systems balance payload capacity with urban emission zone compliance. Euro 7 cold-start mandates are forcing hardware redesigns that expand substrate volume in European delivery van platforms.
- Buses:Low-floor chassis configurations impose unique packaging constraints on vertically oriented catalyst housings. China's Ministry of Ecology and Environment alignment with European test cycles is qualifying advanced suppliers for municipal procurement.
Passenger cars anchor volume; heavy trucks generate premium value concentration.
Material:
Thermal durability and corrosion resistance specifications determine alloy selection across exhaust system zones.
- Stainless Steel:Austenitic and ferritic grades dominate hot-end applications with cyclic oxidation resistance above 900°C. Turbocharger housings and close-coupled catalyst shells specify 300-series alloys for thermal fatigue resistance.
- Aluminized Steel:Hot-dip aluminum-silicon coatings provide cost-effective corrosion protection for mufflers and tailpipes in moderate-temperature zones. Light commercial vehicle manufacturers specify this material for balance of durability and material cost.
- Titanium:Weight-critical performance applications leverage titanium's strength-to-density ratio and oxide stability. Racing and limited-production platforms specify titanium exhaust systems for mass reduction.
- Cast Iron:High-silicon grades retain dimensional stability through extreme thermal cycling in exhaust manifold applications. Heavy truck engine manufacturers specify compacted graphite iron for integrated turbocharger mounting.
Stainless steel commands specification share; aluminized steel retains cost-sensitive segments.
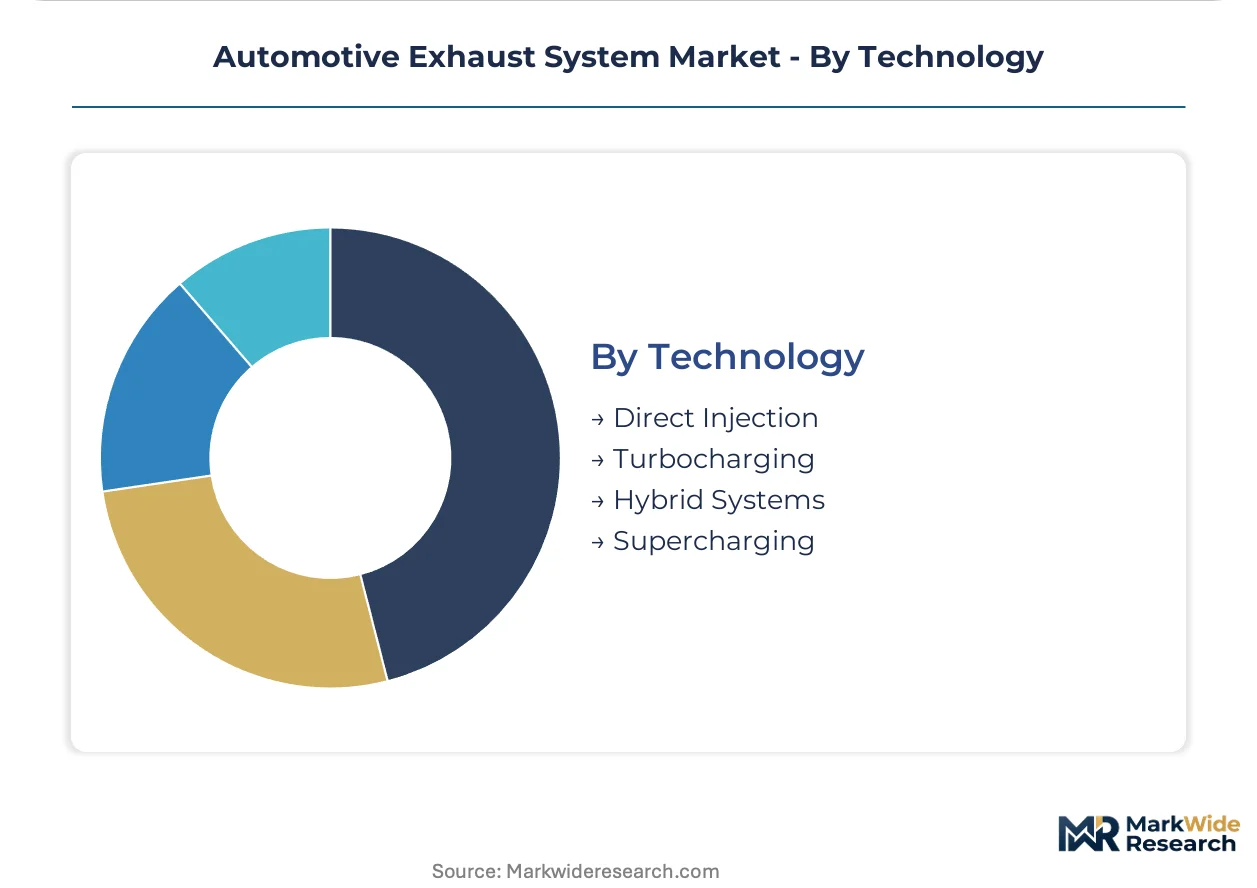
Technology:
Powertrain thermal management requirements are restructuring exhaust system architectures around electrified platforms.
- Hybrid Systems:Dual exhaust stream configurations manage internal combustion thermal output alongside battery and power electronics cooling. European luxury OEMs are adopting electrically heated catalysts for 48-volt mild-hybrid platforms ahead of Euro 7 enforcement.
- Turbocharging:Exhaust gas energy recovery drives compressor boost while imposing transient thermal loading on downstream catalysts. Gasoline direct injection turbo engines require gasoline particulate filters to manage particulate matter emissions.
- Direct Injection:Stratified charge combustion improves thermal efficiency while increasing particulate formation relative to port injection. EPA Tier 3 standards mandate additional after-treatment hardware for GDI platforms.
- Supercharging:Mechanical compression eliminates exhaust gas extraction lag but generates higher steady-state thermal loads. Performance passenger car platforms specify supercharging for linear power delivery.
Hybrid systems are expanding most quickly; turbocharging retains installed base dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's engineering-intensive supplier base contrasts with China's production-scale dominance, while the United States anchors regulatory-driven technology adoption. Each geography imposes distinct compliance architectures and procurement patterns on exhaust system suppliers.
United States
Heavy-truck fleet operators negotiate direct platform agreements with coating specialists for standardized after-treatment modules. The EPA and California Air Resources Board enforce Tier 3 particulate matter standards that mandate gasoline particulate filters across light-duty segments. Detroit's automotive corridor concentrates engineering resources for close-coupled filter-catalyst combinations.
Germany
Commercial vehicle manufacturers drive procurement of multiplex after-treatment stages with expanded substrate volumes. The KBA administers Euro 7 cold-start mandates that force hardware redesigns for real-world emission monitoring. Stuttgart's supplier ecosystem anchors development of electrically heated catalysts for 48-volt mild-hybrid platforms.
China
Domestic vehicle production scale creates procurement windows for suppliers qualified under harmonized European test cycles. The Ministry of Ecology and Environment aligns national standards with European regulatory frameworks. Shanghai's Yangtze River Delta cluster concentrates municipal bus procurement for low-floor chassis with vertically oriented catalyst housings.
India
Commercial vehicle operators expand procurement of heavy-duty after-treatment systems under tightening particulate limits. The Central Pollution Control Board enforces BS-VI Phase II standards for urban emission zone compliance. Tamil Nadu's automotive belt concentrates manufacturing of modular systems for light commercial vehicle platforms.
Japan
Precision substrate manufacturers supply advanced cordierite formulations for cell densities above 600 cpsi. METI oversees alignment with international emission test protocols for export market access. Nagoya's Chubu region anchors production of integrated turbocharger-manifold castings for thermal mass reduction.
Automotive Exhaust System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base concentrates around full-system integrators with captive coating capabilities, compressing margins for component-only suppliers. Three archetypes dominate: diversified automotive suppliers with exhaust divisions, dedicated exhaust system specialists, and substrate manufacturers with downstream integration. Competitive moves center on strategic partnerships for sensor-catalyst convergence and geographic expansion into India's commercial vehicle segment.
Within the specialist tier, Tenneco Inc. and Eberspächer occupy positions as reference points for engineering-intensive platform contracts. Forvia Faurecia represents the diversified conglomerate archetype, while Futaba Industrial Co., Ltd. exemplifies precision manufacturing specialization. These three entities anchor competitive positioning discussions without constituting an exhaustive market map.
| Leading Market Players |
|---|
| Forvia Faurecia |
| Tenneco Inc. |
| Continental AG |
| Eberspächer |
| Futaba Industrial Co., Ltd. |
| BENTELER International |
| BOSAL |
| Sejong Industrial Co., Ltd. |
| Friedrich Boysen |
| Others |
Cost & Logistics Intelligence
Family-owned German coating specialists anchor supply discipline through multi-generational capital structures that resist short-term margin compression. Their captive substrate production insulates platform contract pricing from precious-metal volatility while OEM procurement consolidation squeezes tier-two integrators.
Pricing Analysis
Capacity additions in China are reshaping price floors for cordierite monolith substrates as domestic suppliers qualify under harmonized European test cycles. Contract-based long-term offtake dominates OEM procurement, with price differentiation hinging on ISO-certified coating precision and volume scale commitments. Cost compression in standard-grade exhaust hardware is intensifying because South African rhodium supply constraints feed input volatility. Fleet operators in heavy-truck segments show least price sensitivity due to total cost of ownership calculations, while light commercial vehicle manufacturers in India exhibit highest sensitivity to upfront system costs.
Supply Chain Analysis
Single-source vulnerability sits with South African rhodium mining output and Russian palladium export channels. Manufacturing concentrates in Germany, China, and Japan, with substrate production drawing from cordierite deposits in the United States and silicon carbide processing in Austria. Supply chain risk centers on tariff exposure for platinum-group-metal shipments crossing transatlantic routes. Distribution runs through tier-one integrators with captive coating capabilities, though fleet operators in North America increasingly negotiate direct platform agreements with specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Euro 7 cold-start mandates force hardware redesigns that expand substrate volume and lock in replacement demand cycles.
For Market Incumbents: Extend coating capacity in China to capture Ministry of Ecology and Environment qualification windows before domestic competitors achieve European test cycle alignment. Deepen backward integration into cordierite monolith production to neutralize single-source risk from the three global substrate suppliers. Battery thermal management hiring pools threaten CFD simulation talent retention; secure specialized exhaust system modeling expertise through dedicated R&D center investments in Stuttgart or Nagoya clusters. For New Entrants and Emerging Players: Capture India's BS-VI Phase II enforcement window for heavy-duty commercial vehicle after-treatment, where procurement windows remain open for suppliers with multiplex catalyst expertise. Municipal bus fleets in Chinese megacities present penetrable demand for vertically oriented catalyst housings in low-floor chassis configurations. Partner with European coating specialists for technology licensing rather than greenfield R&D, accelerating homologation timeline compression risks. For Investors and Strategic Acquirers: Diversified automotive suppliers with exhaust divisions are the most active acquirer in this space, consolidating sensor-catalyst convergence capabilities ahead of Euro 7 real-world emission monitoring requirements. Target acquisition archetypes include substrate manufacturers with downstream integration potential and coating specialists holding long-term platform contracts with North American truck manufacturers. Watch for China's Ministry of Ecology and Environment alignment announcements as the inflection signal determining which European suppliers qualify for the world's largest vehicle production base.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM procurement consolidation favors full-system integrators with captive coating capabilities across multiple vehicle architectures. |
| Backward Integration into Substrates | In-house cordierite monolith production neutralizes single-source risk from concentrated global suppliers. |
| Sensor-Catalyst Convergence | Integration of NOx sensors into substrate housings creates value-added architectures for Euro 7 compliance. |
| Geographic Manufacturing Footprint | China qualification under European test cycles opens procurement access to the world's largest vehicle production base. |
| Electrically Heated Catalyst Investment | European luxury OEMs adopt 48-volt mild-hybrid thermal management ahead of Euro 7 enforcement deadlines. |
Research Approach
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each regional production cluster. The analysis combines structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operator specification managers with secondary validation from vehicle production databases, IHS Markit registration data, EPA and CARB regulatory filings, and KBA homologation records. Bottom-up component demand modeling and top-down OEM procurement analysis provide triangulation across the analysis window.
Granularity-level modeling spans vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from segment-level volume projections cross-referenced with per-unit value assumptions for catalytic converter precious-metal loadings and substrate cell density requirements. Industry-specific forecast inputs include Euro 7 implementation timeline assumptions and China's Ministry of Ecology and Environment standard alignment progress.
Platinum-group-metal price volatility, substrate manufacturing yield compression, and hybrid powertrain adoption acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and OEM platform launch schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Lifts Market
Automotive Parts
Oil Filter Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Speed Bump Market
Automotive Parts
United States Automotive Parts Die Casting Market