
 Automotive Hardware Market | 2026-2036
Automotive Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hardware Market Analysis
IATF 16949 certification is bifurcating the supplier base into qualified Tier-1 participants and excluded aspirants. LISI Automotive leverages its forged fastening expertise to sustain long-term OEM contracts. Brembo anchors its position through advanced braking system specialization. Illinois Tool Works competes across diversified fastening and fluid handling portfolios.
Automotive hardware encompasses mechanical fasteners, braking components, electronic control modules, and chassis attachments engineered to tensile strengths exceeding 1,200 MPa, manufactured through cold forging, stamping, and precision machining to ensure vehicle structural integrity and occupant safety. Electronic Control Units command margin concentration due to software-hardware integration complexity, while ADAS technology segments attract accelerated engineering investment. Embedded Systems maintain mature revenue streams in powertrain management, whereas Connectivity Solutions represent an emerging growth vector for Tier-1 suppliers.
NHTSA enforces Federal Motor Vehicle Safety Standards that dictate crashworthiness testing protocols, while EPA tailpipe regulations compel lightweight hardware redesigns to meet corporate average fuel economy thresholds. The EU Green Deal and REACH chemical restrictions are reshaping material selection for European-market components. Stakeholders must monitor how battery electric vehicle platform architectures redefine load-bearing hardware specifications and thermal management attachment requirements.
Market Dynamics
Platform electrification is compressing legacy powertrain hardware demand while multiplying attachment points for battery thermal management and high-voltage safety systems across passenger and commercial vehicle architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:OEMs in the United States are redesigning chassis and body-in-white structures with advanced high-strength steels and aluminum extrusions to shed mass and avoid penalties.
- Battery electric vehicle platform proliferation:Dedicated skateboard architectures from Volkswagen, Hyundai, and Ford are generating specialized fastener and bracket specifications for pack-to-chassis integration.
- Germany's automotive manufacturing corridor:Concentrated OEM and Tier-1 engineering activity around Stuttgart, Munich, and Wolfsburg sustains premium hardware specification development and prototype-to-production velocity.
Market Restraints
- Aluminum and alloy steel price volatility:Cold-forged fastener and stamped bracket producers face margin compression when raw material indices spike without corresponding OEM price adjustment mechanisms.
- Single-source forging capacity in Central Europe:Large-diameter crankshaft and camshaft blank supply concentrates among a handful of German and Austrian suppliers, creating vulnerability to energy cost shocks or labor actions.
- REACH chemical authorization delays:Surface treatment chemistries for corrosion-resistant coatings face prolonged ECHA evaluation timelines, forcing interim substitutions with inferior performance profiles.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized forging and precision machining capacity expansion qualifies for production-linked incentives, attracting joint venture investment from European and Japanese hardware specialists.
- Vehicle-to-everything antenna integration:5G and C-V2X module attachment hardware represents an emerging specification category with limited incumbent supplier penetration.
- EU Green Deal circularity requirements:Design-for-disassembly mandates and recycled content thresholds favor hardware suppliers with closed-loop material recovery and remanufacturing capabilities.
Industry Challenges
- IATF 16949 auditor scarcity:Certified third-party assessors for automotive quality management system surveillance audits face backlog periods exceeding nine months, delaying new supplier qualification.
- Legacy controller integration complexity:Domain-centralized zonal architectures require hardware suppliers to reconcile mechanical attachment specifications with legacy powertrain control module form factors during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hardware Market |
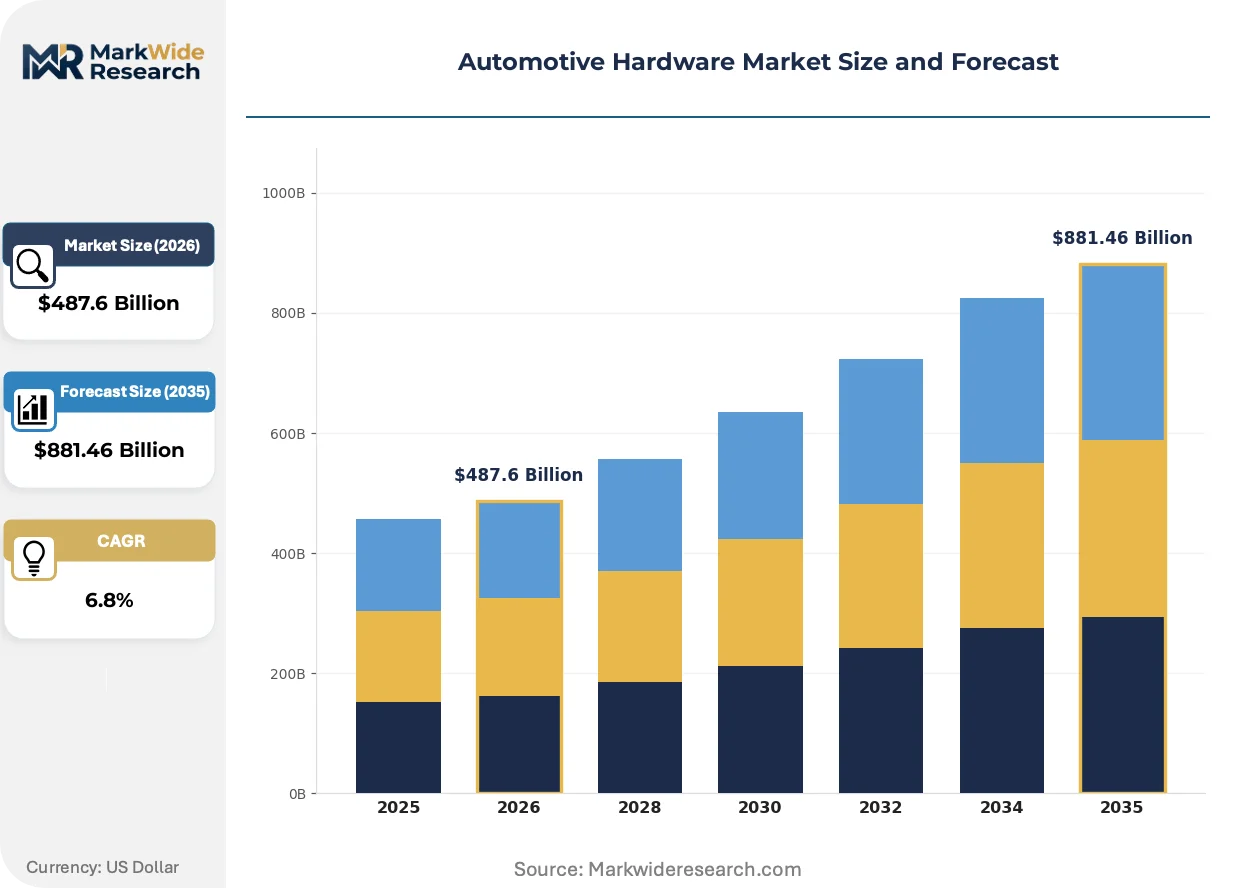
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
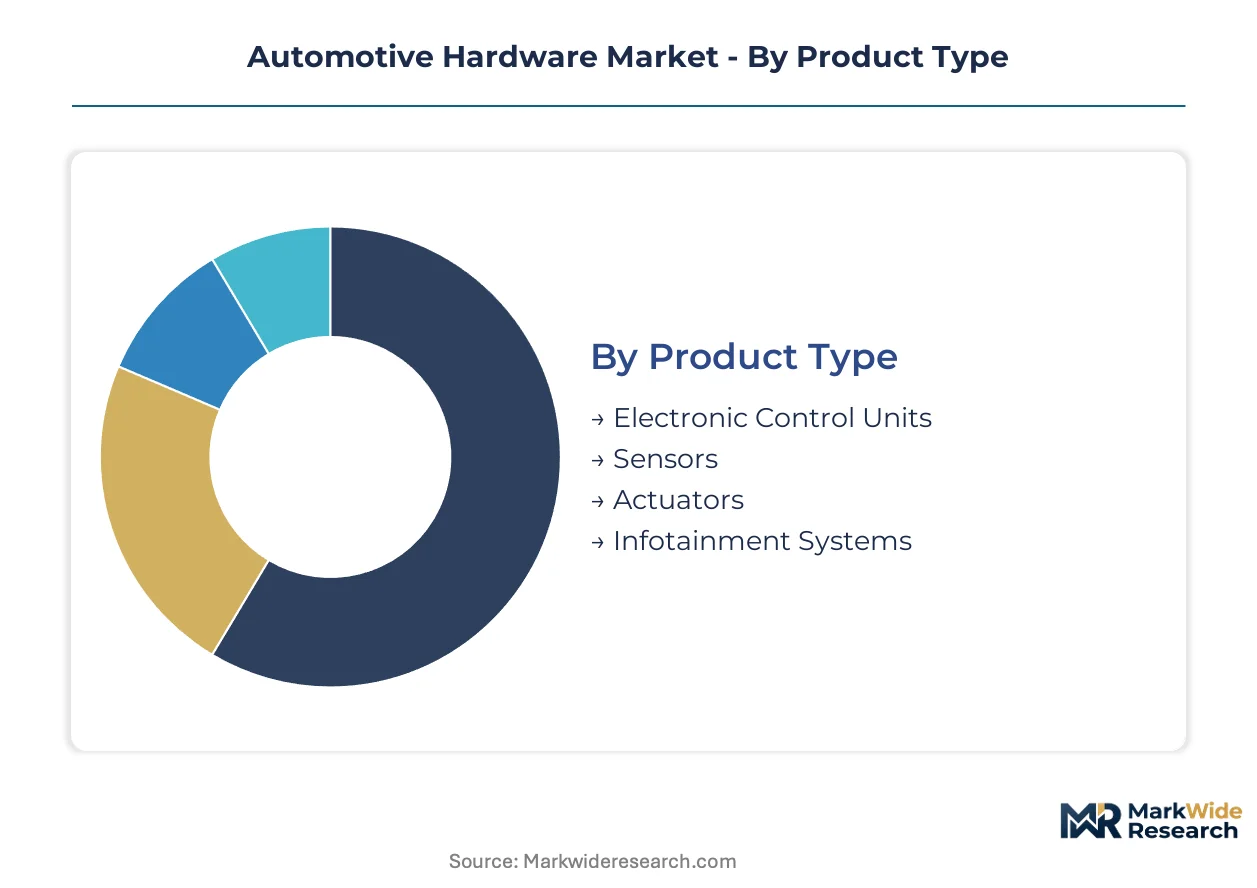
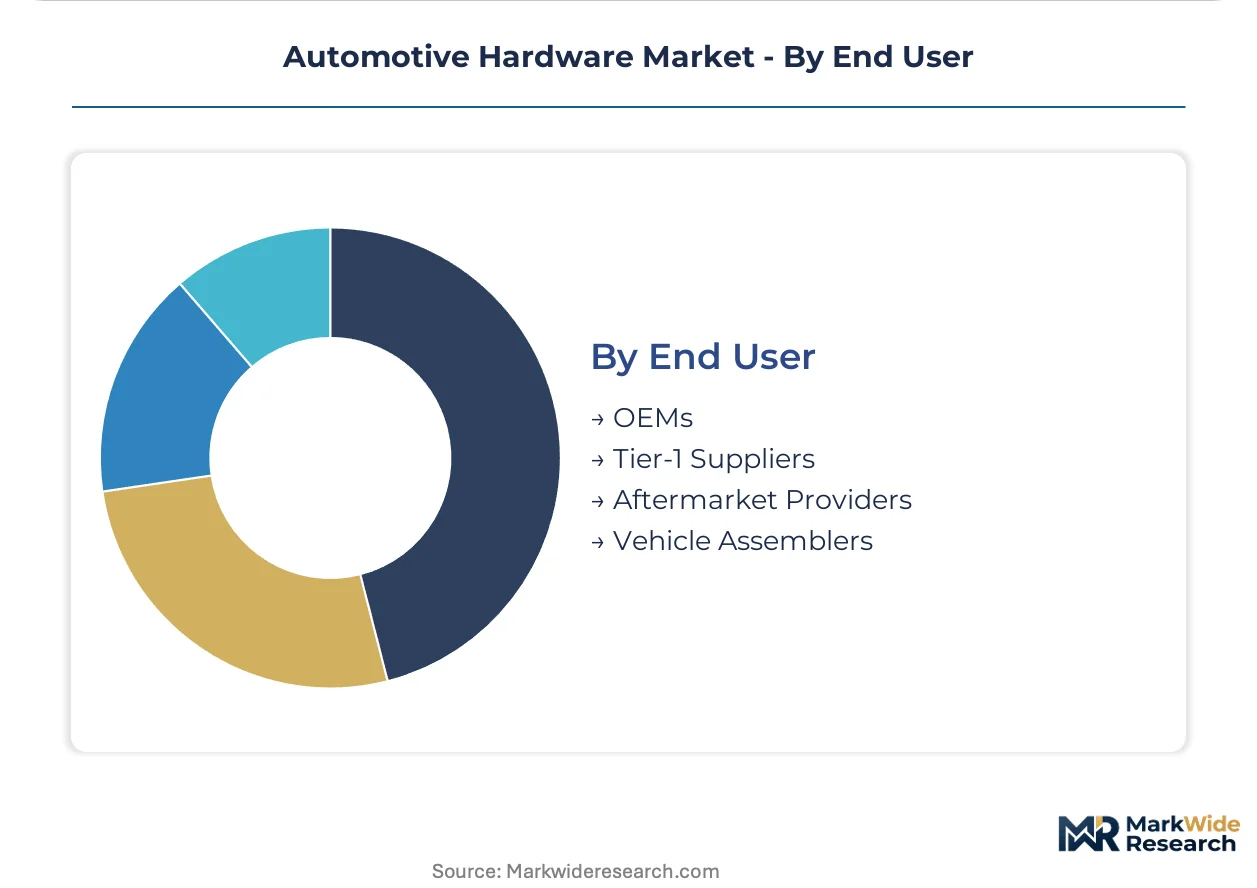
| Segmentation | Product Type: Electronic Control Units, Sensors, Actuators, Infotainment Systems Technology: Embedded Systems, ADAS, Electric Propulsion, Connectivity Solutions Application: Passenger Cars, Commercial Vehicles, Sports Cars, Luxury Cars End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | ARaymond, LISI Automotive, Illinois Tool Works, Bulten, Brembo, Stanley Black & Decker, KAMAX, Nedschroef, Würth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hardware Market Emerging Trajectories
Multi-material vehicle construction is fragmenting traditional fastener portfolios while demanding new joining technologies that accommodate dissimilar material interfaces without galvanic corrosion or thermal expansion mismatch.
Multi-step hot forming of press-hardened steels is bifurcating the structural component supply base. OEMs including Volvo and Mercedes-Benz specify these grades for A-pillar and roof rail reinforcements to meet NHTSA roof crush requirements. The process is bifurcating Tier-2 suppliers into those with continuous roller hearth furnace investments and those excluded from safety-critical body structure contracts.
EU F-Gas Regulation phase-down schedules are accelerating CO2 heat pump adoption in electric vehicle thermal systems. Hardware suppliers must redesign compressor mounts, accumulator brackets, and line attachment points for higher operating pressures and refrigerant compatibility. European HVAC module assemblers are consolidating supplier lists to those with pressure vessel certification and localized stamping capacity.
Consolidated procurement functions at Stellantis, Renault, and BMW are compressing hardware supplier margins through annual price-down mandates and consolidated global sourcing agreements. Tier-1 purchasing organizations are displacing regional buying centers with commodity councils that leverage volume across multiple vehicle platforms. This concentration is most visible in Germany and France, where incumbent suppliers face heightened switching risk without differentiated engineering collaboration.
Automotive Hardware Market Segmentation
Hardware specification divergence across electrified and conventional powertrain architectures demands granular segmentation. Regulatory mandates from NHTSA, EPA, and EU Green Deal reshape component requirements differently across product categories and end-use applications.
Product Type:
EPA emissions thresholds and NHTSA crashworthiness mandates differentiate hardware requirements by functional complexity and software integration depth.
- Electronic Control Units:These modules integrate microcontrollers, power management circuits, and embedded software stacks for powertrain, chassis, and body domain control. Demand concentrates in Germany's Stuttgart-Munich corridor where BMW and Mercedes-Benz specify zonal E/E architectures requiring centralized compute modules with ASIL-D functional safety ratings.
- Sensors:Pressure, temperature, position, and inertial measurement units convert physical parameters to electrical signals with millisecond latency. Passenger car OEMs in the United States source these for NHTSA-mandated tire pressure monitoring and ESC systems, with silicon MEMS designs displacing legacy electromechanical alternatives.
- Actuators:Electromechanical and electrohydraulic devices execute control commands for braking, steering, and thermal management valves.
- Infotainment Systems:Integrated display, audio, and connectivity modules with touchscreen HMI layers.
Electronic Control Units handle the majority of throughput; Sensors are expanding most quickly on share.
Technology:
Cost tier differentiation separates legacy embedded architectures from premium ADAS and connectivity stacks requiring specialized semiconductor content.
- Embedded Systems:Mature microcontroller-based architectures manage engine control, transmission shift logic, and climate regulation through deterministic real-time operating systems. Powertrain applications in commercial vehicle segments across India and Brazil sustain volume demand despite electrification headwinds.
- ADAS:Sensor fusion platforms combining radar, camera, and lidar inputs for automated emergency braking and lane-keeping assistance. German luxury OEMs specify Level 2+ hardware suites with redundant processing chains, creating specification premiums over standard safety systems.
- Electric Propulsion:Inverter control boards, battery management systems, and motor position sensors.
- Connectivity Solutions:5G and C-V2X modules enabling vehicle-to-infrastructure communication.
Embedded Systems retain the largest installed base; Electric Propulsion is climbing the fastest on specification intensity.
Application:
Volume concentration versus margin structure distinguishes mass-market passenger applications from low-volume premium segments.
- Passenger Cars:High-volume compact and mid-size vehicles generate standardized fastener and bracket specifications with annual price-down pressure. Platform consolidation at Volkswagen and Stellantis concentrates procurement leverage, compressing supplier margins across Germany, France, and Italy manufacturing networks.
- Commercial Vehicles:Heavy-duty trucks and buses require fatigue-rated chassis attachments and powertrain hardware with million-cycle durability validation. Fleet electrification in California and EU corridors drives demand for e-axle mounting systems and battery pack structural interfaces.
- Sports Cars:Low-volume performance vehicles with magnesium and carbon fiber attachment challenges.
- Luxury Cars:Premium sedans and SUVs with custom hardware finishes and acoustic isolation requirements.
Passenger Cars absorb the dominant share of unit volume; Commercial Vehicles are gaining specification intensity fastest.
End User:
Supply chain position determines technical interface requirements and qualification burden for hardware suppliers.
- OEMs:Vehicle manufacturers with direct hardware specification authority for safety-critical body structure and powertrain components. Ford and Hyundai maintain captive fastener engineering teams in Detroit and Seoul that release proprietary drawings to approved supplier pools.
- Tier-1 Suppliers:System integrators such as Bosch and Continental sourcing subcomponents for braking, steering, and thermal modules. These entities enforce IATF 16949 and VDA 6.3 process audits, creating qualification barriers for aspirant hardware manufacturers.
- Aftermarket Providers:Independent distributors serving collision repair and vehicle modification channels.
- Vehicle Assemblers:Contract manufacturing operations with limited design authority.
Tier-1 Suppliers channel the majority of component flow; Aftermarket Providers are expanding fastest on electrification-driven part proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM engineering centers and Tier-1 supplier headquarters concentrate hardware specification authority across four manufacturing corridors. Each geography shapes demand through distinct regulatory frameworks and platform electrification timelines.
United States
Detroit-area OEMs and California fleet operators drive demand for lightweight chassis hardware and battery thermal management attachments. NHTSA Federal Motor Vehicle Safety Standards mandate crashworthiness testing that elevates high-strength steel fastener specifications. The Southeast manufacturing corridor spanning Tennessee, South Carolina, and Alabama hosts Volkswagen, BMW, and Mercedes-Benz assembly plants with localized fastener engineering requirements.
Germany
Stuttgart, Munich, and Wolfsburg anchor premium passenger car hardware development with concentrated BMW, Mercedes-Benz, and Volkswagen engineering activity. EU Green Deal circularity requirements and REACH chemical restrictions reshape material selection and surface treatment protocols. The Baden-Württemberg and Bavaria industrial clusters sustain prototype-to-production velocity for safety-critical body structure components.
China
Domestic EV platform proliferation from BYD, NIO, and Xpeng generates specialized battery pack structural interface specifications. MIIT new energy vehicle mandates and GB standards for electromagnetic compatibility constrain controller hardware designs. The Yangtze River Delta and Pearl River Delta manufacturing basins concentrate forging, stamping, and precision machining capacity for both domestic OEMs and export markets.
Japan
Toyota, Honda, and Nissan maintain hybrid powertrain hardware demand alongside dedicated BEV platform development. METI carbon neutrality roadmaps and JIS quality standards enforce rigorous supplier qualification protocols. The Nagoya-Tokyo-Osaka industrial corridor sustains precision fastener and electronic control module production with integrated Tier-1 supply relationships.
India
Maruti Suzuki, Tata Motors, and Mahindra & Mahindra expand domestic and export platform hardware sourcing. PLI scheme production-linked incentives for automotive components attract joint venture forging and machining investments from European and Japanese specialists. The Tamil Nadu and Maharashtra manufacturing clusters concentrate OEM assembly and Tier-1 supplier engineering centers with growing specification authority.
Automotive Hardware Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with automotive divisions alongside specialized fastening and braking system specialists. Market structure exhibits tiered consolidation: a narrow premium tier commands specification-intensive safety-critical contracts, while a broader volume tier competes on scale and logistics integration. Strategic archetypes include forged fastener specialists with IATF 16949 certification depth, diversified industrial manufacturers with cross-sector technology transfer capabilities, and braking system integrators with embedded software-hardware competence. Dominant competitive moves encompass backward integration into cold forging capacity and strategic partnerships for battery electric vehicle platform co-development.
Within the specialized fastener tier, LISI Automotive and Bulten represent European forged fastening expertise with long-term OEM contract structures. Brembo anchors Italian braking system specialization. Illinois Tool Works and Stanley Black & Decker occupy positions as diversified North American industrial manufacturers with automotive hardware portfolios spanning fastening, fluid handling, and power tool adjacent categories. KAMAX and Nedschroef exemplify German and Dutch engineering-driven suppliers with concentrated exposure to European premium OEM specification cycles. ARaymond and Würth Group represent family-owned European structures with global distribution networks and captive customer relationships in assembly and maintenance channels.
| Leading Market Players |
|---|
| ARaymond |
| LISI Automotive |
| Illinois Tool Works |
| Bulten |
| Brembo |
| Stanley Black & Decker |
| KAMAX |
| Nedschroef |
| Würth Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with annual price-down clauses lock in supply access for Tier-1 suppliers while compressing margins across Germany, China, and Japan manufacturing networks. These structures bind OEM procurement to indexed aluminum and alloy steel contracts, stripping price visibility from spot market volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate fastener and stamped bracket procurement. Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified safety-critical suppliers from uncertified volume competitors. Pricing pressure stems from consolidated commodity councils at Stellantis and BMW demanding year-over-year reductions. Mass-market passenger car OEMs exhibit highest price sensitivity; German luxury manufacturers tolerate premium tiers for crashworthiness-rated components.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion elevate landed costs for cold-forged fasteners sourced from Central European mills. Supply concentrates in Germany, China, and Japan for precision forging capacity and electronic control module assembly. Raw material dependencies span aluminum extrusions, high-strength alloy steels, and semiconductor-grade silicon substrates. Single-source vulnerability concentrates in large-diameter crankshaft blank forging among Austrian and German suppliers. Distribution runs through Tier-1 system integrators with direct OEM release authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification constitutes a high-growth disruption as battery electric vehicle architectures multiply attachment point specifications while eliminating legacy powertrain hardware categories. NHTSA and EPA regulatory tightening accelerates specification turnover across North American supply chains.
For Market Incumbents: Consolidate backward integration into cold forging capacity to defend margin position against aluminum price volatility. Deepen IATF 16949 certification depth to exclude aspirant competitors from safety-critical body structure contracts. Expand captive engineering presence in Stuttgart and Detroit to capture prototype-to-production velocity premiums.
For New Entrants and Emerging Players: Aftermarket thermal management hardware for battery electric vehicle retrofits represents an underserved service layer with limited incumbent penetration. Target India's PLI scheme corridors for localized forging joint ventures with Maruti Suzuki and Tata Motors procurement networks. Pursue vehicle-to-everything antenna integration specifications as a greenfield category with nascent supplier competition.
For Investors and Strategic Acquirers: Family-owned European fastener specialists with closed-loop material recovery capabilities offer acquisition targets aligned with EU Green Deal circularity mandates. Long-term viability hinges on battery electric vehicle platform co-development relationships with Volkswagen, Hyundai, and Ford engineering centers. Monitor ECHA REACH authorization timelines for surface treatment chemistry substitutions as an inflection signal for coating technology disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell capacity for electric vehicle thermal management hardware integration. |
| Backward Integration | Captures cold forging capacity to insulate margins from aluminum LME index volatility. |
| Software-Defined Vehicle Investment | Aligns electronic control module specifications with zonal E/E architecture transitions at BMW. |
| Geographic Manufacturing Footprint | Establishes Tamil Nadu presence to qualify for India's PLI scheme production-linked incentives. |
| Charging Infrastructure Partnership | Generates high-voltage connector and bracket specifications for DC fast-charging hardware. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and IATF 16949 certification auditors; and secondary validation against vehicle production databases, SEC filings from diversified industrial manufacturers, customs trade data for aluminum and alloy steel imports, and NHTSA FMVSS regulatory filings. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Across the projection horizon, the analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from regression analysis of historical specification intensity trends and electrification penetration curves. Industry-specific forecast inputs incorporated battery electric vehicle platform launch timelines and REACH chemical authorization pipeline status.
Underlying assumptions cover EPA CAFE mandate enforcement continuity and EU Green Deal circularity implementation timelines, with deviation risk concentrated in aluminum price volatility spikes and IATF 16949 auditor availability bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Towbar Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market