
 Global Automotive Carbon Ceramic Brake Rotors Market | 2026-2036
Global Automotive Carbon Ceramic Brake Rotors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Carbon Ceramic Brake Rotors Market Intelligence
Direct sales channels to original equipment manufacturers (OEMs) is reshaping competitive positioning in the automotive carbon ceramic brake rotor market. Brembo S.p.A. leverages its strong brand and established OEM relationships to secure high-value contracts for flagship vehicle platforms. SGL Group, in contrast, specializes in the underlying carbon fiber material science, providing a critical supply chain advantage. Akebono Brake Industry competes through its extensive presence in the Asian automotive sector, particularly with Japanese automakers.
Automotive carbon ceramic brake rotors are high-performance braking components manufactured by infiltrating a carbon fiber preform with liquid silicon. This process creates a silicon carbide matrix, yielding a lightweight, temperature-resistant disc with exceptional thermal stability under heavy braking. The sports cars application segment continues to be the largest source of demand due to stringent performance requirements. Consequently, original equipment manufacturers (OEMs) represent the dominant end-user channel, procuring rotors for factory installation on premium models.
Market access depends on adherence to stringent safety and performance standards, such as those mandated by the US National Highway Traffic Safety Administration (NHTSA) and encompassed within Europe's CE marking requirements. Additionally, ISO 9001 certification is a baseline for supplier qualification with major automakers. Future profitability hinges on manufacturers' ability to reduce complex production cycle times and lower the high cost of raw carbon fiber materials.
Market Dynamics
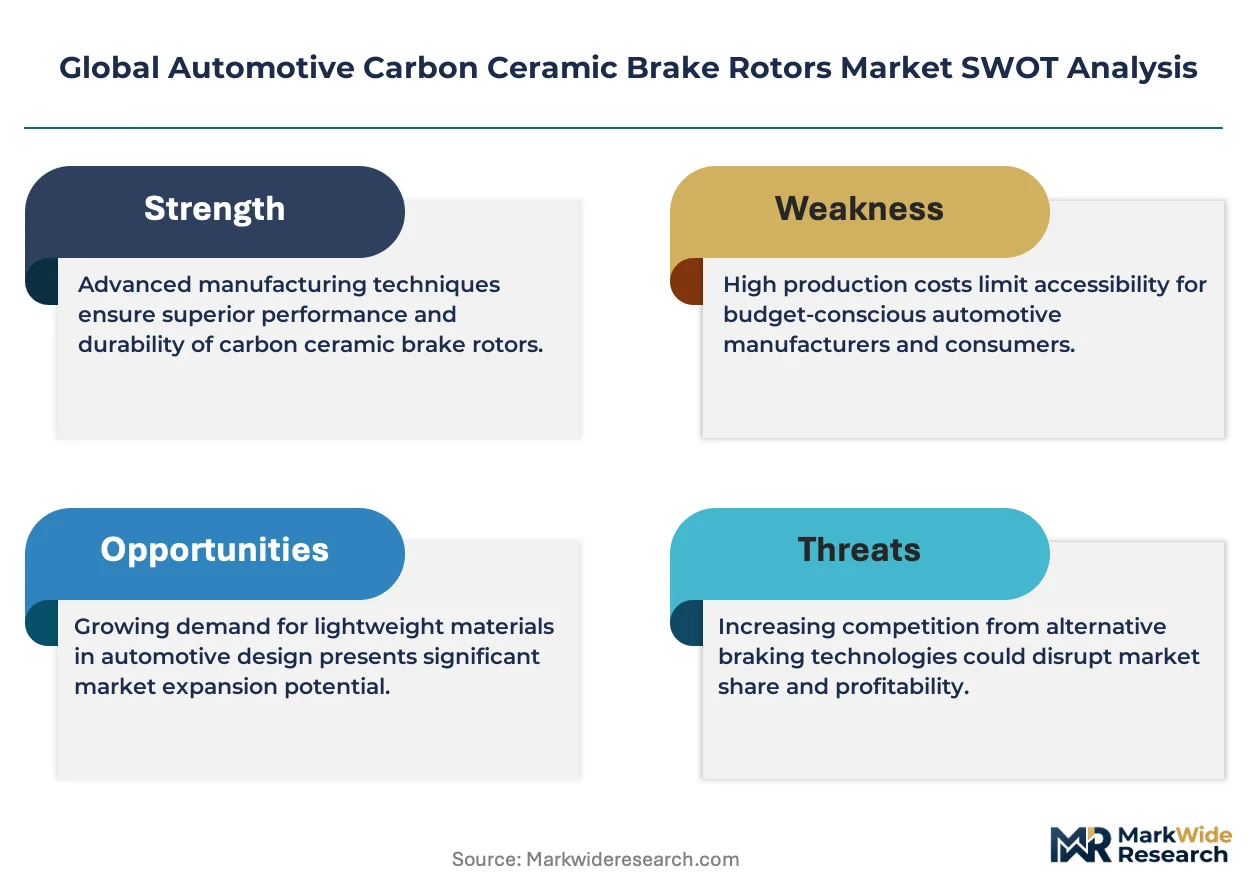
The primary force shaping the market is the dual demand from performance combustion vehicles requiring extreme thermal capacity and electric vehicles demanding lightweight components to maximize battery range. This creates distinct engineering and cost pressures for manufacturers.
Growth Catalysts
- EV Lightweighting:The push for lighter components in electric vehicle design to extend driving range and offset heavy battery packs directly benefits carbon ceramic rotors.
- Performance Segment Demand:Sustained demand from the high-performance sports car segment, especially within Germany's automotive manufacturing clusters, provides a stable, high-margin revenue base.
- Safety Regulations:Stringent performance standards, such as those mandated by the US National Highway Traffic Safety Administration, encourage adoption of advanced braking systems in top-tier vehicle models.
Market Restraints
- Raw Material Costs:High costs for aerospace-grade carbon fiber precursors and high-purity silicon are primary barriers to wider market adoption beyond niche applications.
- Manufacturing Complexity:The energy-intensive silicon infiltration process involves long production cycles, which restricts manufacturing scalability and elevates final component costs.
- Substitution Threat:Advanced coated cast iron rotors offer near-comparable performance in many driving scenarios at a substantially lower price point, limiting penetration.
Strategic Opportunities
- New Vehicle Segments:Application in high-performance electric SUVs and trucks, where high vehicle weight demands superior braking power and heat dissipation, presents a major growth vector.
- Process Innovation:Development of alternative manufacturing techniques, such as using chopped carbon fibers or faster curing cycles, could significantly reduce production costs and open new markets.
- Asian Market Penetration:Expanding into China's burgeoning premium EV market, where consumers show a strong preference for high-specification components, offers significant volume potential.
Industry Challenges
- Production Cycle Time:Reducing the complex manufacturing cycle is a critical hurdle for manufacturers aiming to meet OEM volume and cost-down targets.
- Supplier Qualification:Achieving and maintaining ISO 9001 certification and passing rigorous, automaker-specific audits for supply chain integrity creates a high barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Carbon Ceramic Brake Rotors Market |
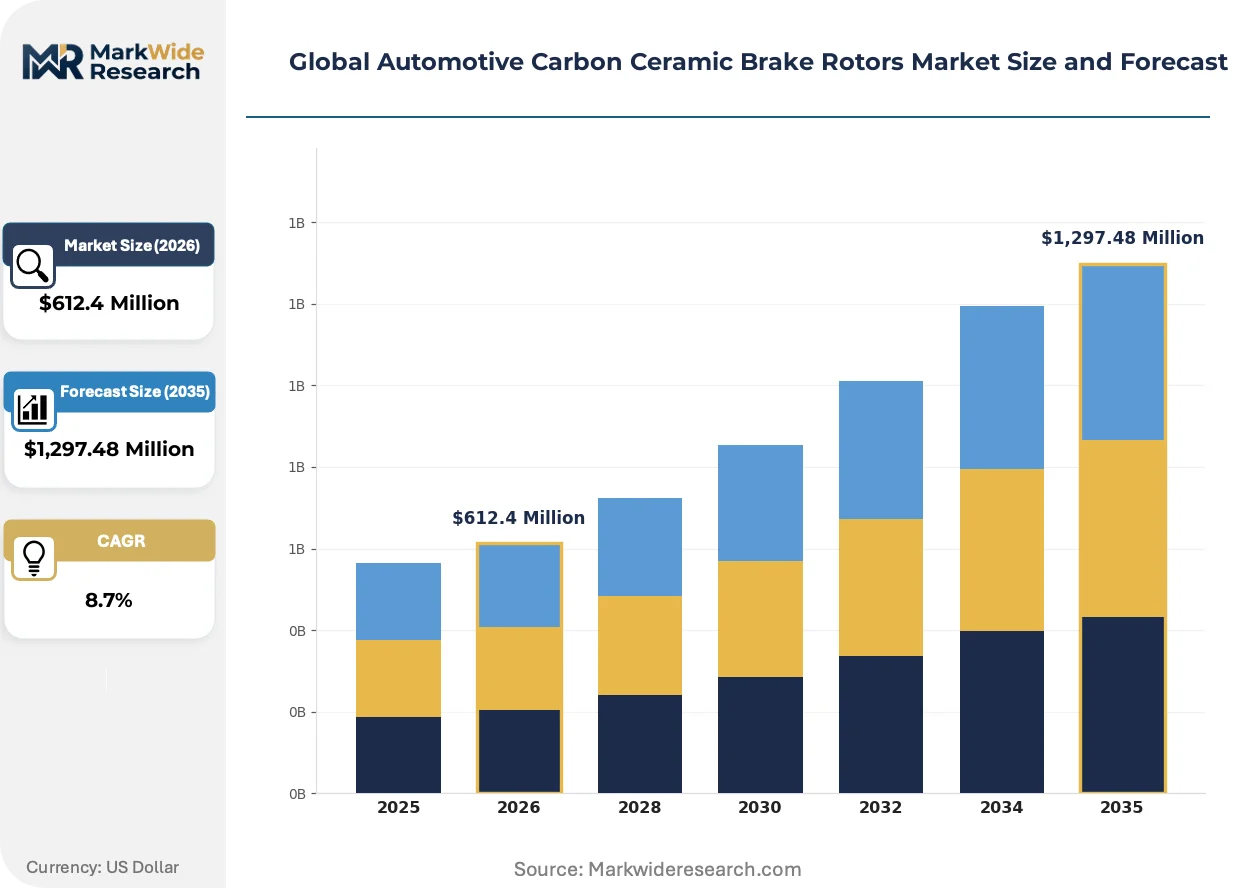
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Ceramic, Carbon Fiber Reinforced, Silicon Carbide, Boron Nitride, Zirconium Oxide, Alumina Application: Sports Cars, Luxury Sedans, Racing Vehicles, Motorcycles, Off-road Vehicles, Heavy-duty Trucks End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Distribution Channel: Authorized Dealers, E-commerce Platforms, Spare Parts Retailers, Specialty Workshops, Direct Sales |
| Companies Covered | Brembo S.p.A., SGL Group, Akebono Brake Industry, Surface Transforms, Fusion Brakes, Federal Mogul, Aisin Seiki, Alcon Components, Wilwood Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Carbon Ceramic Brake Rotors Market Strategic Shifts & Innovations
Material science advancements are enabling new performance characteristics, while demand from vehicle electrification programs is altering fundamental design and procurement requirements. These forces are pushing rotor technology beyond its traditional role in motorsports and supercars.
New-generation discontinuous fiber composites provide enhanced fracture toughness compared to traditional long-fiber preforms. The automotive sector, particularly for high-performance EVs, is adopting this technology to improve rotor durability against thermal shock. This innovation is hybridizing the established silicon carbide matrix with tougher, more resilient fiber structures to overcome historical brittleness concerns.
Europe's upcoming Euro 7 regulation introduces the first-ever limits on non-exhaust particulate matter from brakes. This standard compels automakers to consider the dust-emission profile of braking components during vehicle design. Consequently, the low-dust characteristic of carbon ceramic rotors makes them an attractive compliance solution for premium and performance vehicles sold in the region.
Automakers are increasingly sourcing complete brake-by-wire corner modules rather than individual rotor components. This integrated procurement model favors suppliers with deep systems engineering and software capabilities, disrupting the traditional component-focused supply chain. This shift is most visible within the German OEM landscape for flagship electric vehicle platforms.
Global Automotive Carbon Ceramic Brake Rotors Market Segmentation
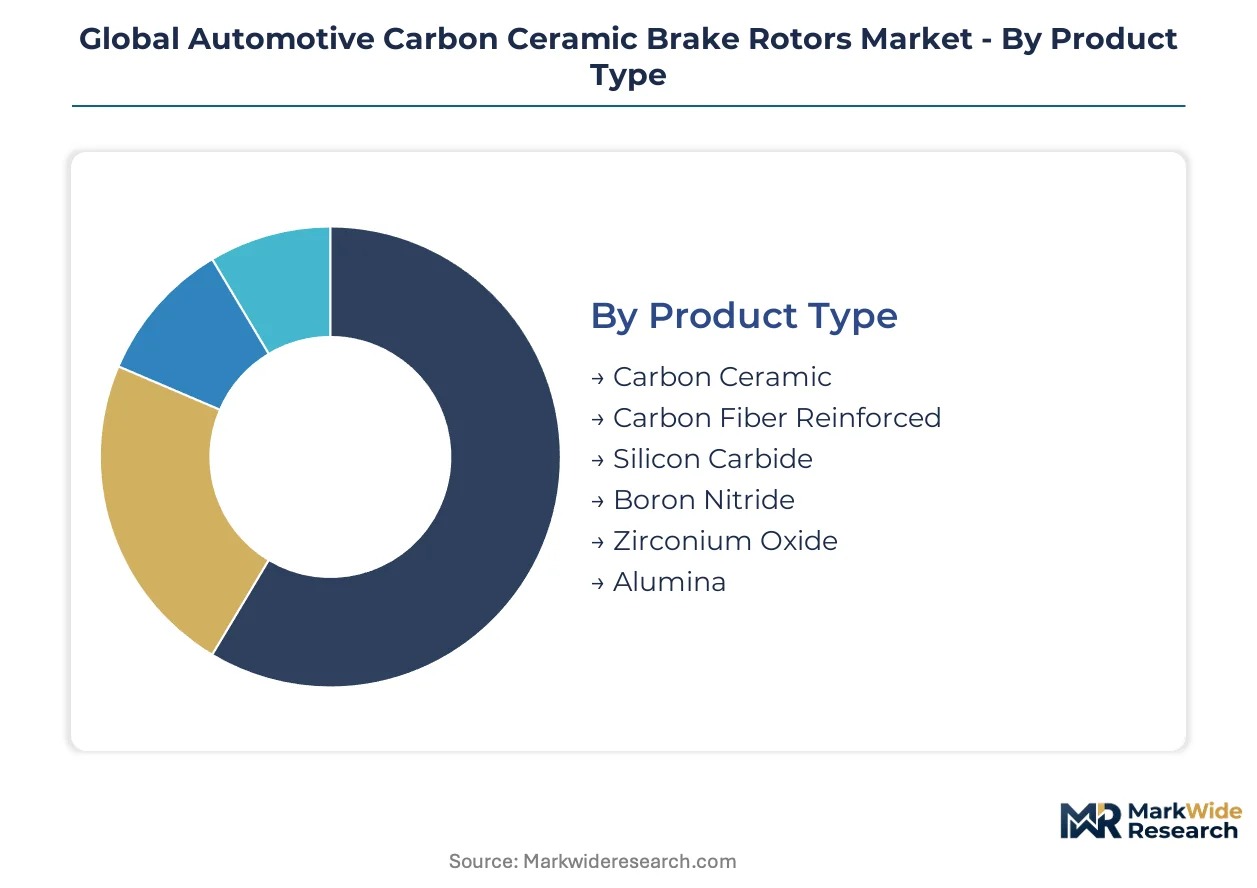
Segmentation analysis for the automotive carbon ceramic brake rotors market provides a granular view of demand drivers and supply chain structures. It clarifies how diverse product types, applications, and end-user requirements shape market dynamics. Understanding these segments is crucial for manufacturers developing targeted product strategies and optimizing distribution channels.
Product Type:
Understanding rotor production cycle times is critical for manufacturers prioritizing output efficiency across diverse material compositions.
- Carbon Ceramic:Formed by infiltrating carbon fiber preforms with liquid silicon, these rotors create a silicon carbide matrix. This delivers exceptional thermal stability and lightweight properties for sports cars.
- Silicon Carbide:Utilizing a silicon carbide composite structure, these rotors offer extreme hardness and wear resistance, crucial for heavy braking. Growing EV adoption seeks to maximize range.
- Carbon Fiber Reinforced:These rotors incorporate advanced carbon fibers to enhance structural integrity and thermal shock resistance in racing vehicles.
- Boron Nitride:Known for high thermal conductivity, boron nitride composites are explored for ultra-high-temperature braking systems in extreme environments.
- Zirconium Oxide:This material offers excellent hardness and corrosion resistance, finding limited use in specific high-end automotive braking components.
- Alumina:Alumina-based composites provide good wear properties and cost-effectiveness for certain braking applications, though less common in premium rotors.
Carbon Ceramic anchors the volume base while Silicon Carbide gains share at the steepest rate.
Application:
Demand concentration varies significantly across vehicle applications, reflecting distinct performance requirements and purchasing power.
- Sports Cars:This largest demand source requires rotors with superior thermal capacity and fade resistance for aggressive driving. German luxury marques integrate these components for flagship models.
- Racing Vehicles:Extreme performance demands in motorsports drive carbon ceramic rotor adoption for unparalleled stopping power and weight savings. Racing series mandate high-performance braking systems.
- Luxury Sedans:Premium luxury sedans adopt carbon ceramic rotors to enhance braking feel, reduce unsprung weight, and improve vehicle dynamics.
- Motorcycles:High-performance motorcycles utilize carbon ceramic rotors for weight reduction and improved braking efficiency in track-focused and premium models.
- Off-road Vehicles:This segment uses carbon ceramic rotors to manage heat build-up during demanding braking maneuvers, especially in heavy off-road trucks.
- Heavy-duty Trucks:Emerging demand from heavy-duty trucks, particularly electric variants, focuses on superior heat dissipation and weight reduction for enhanced efficiency.
Market expansion hinges on sustained demand from Sports Cars and emerging opportunities in Heavy-duty Trucks.
End User:
Procurement patterns among end-users directly influence supply chain design and supplier qualification processes.
- OEMs:Original Equipment Manufacturers represent the dominant end-user channel, procuring rotors for factory installation on premium and high-performance vehicles. Their stringent quality standards drive long-term contracts.
- Tier-1 Suppliers:These suppliers integrate carbon ceramic rotors into complete braking modules and corner assemblies for automakers, requiring robust systems engineering. Critical within the German OEM landscape.
- Aftermarket Providers:This segment supplies replacement carbon ceramic rotors and upgrade kits to vehicle owners and independent service centers.
- Vehicle Assemblers:Specialized vehicle assemblers, often focusing on limited-production or custom models, source carbon ceramic rotors for unique performance requirements.
Strategic engagement with OEMs remains paramount, while Tier-1 Suppliers represent a key channel for system integration.
Distribution Channel:
Each distribution channel offers distinct market access and margin potential for carbon ceramic brake rotor manufacturers.
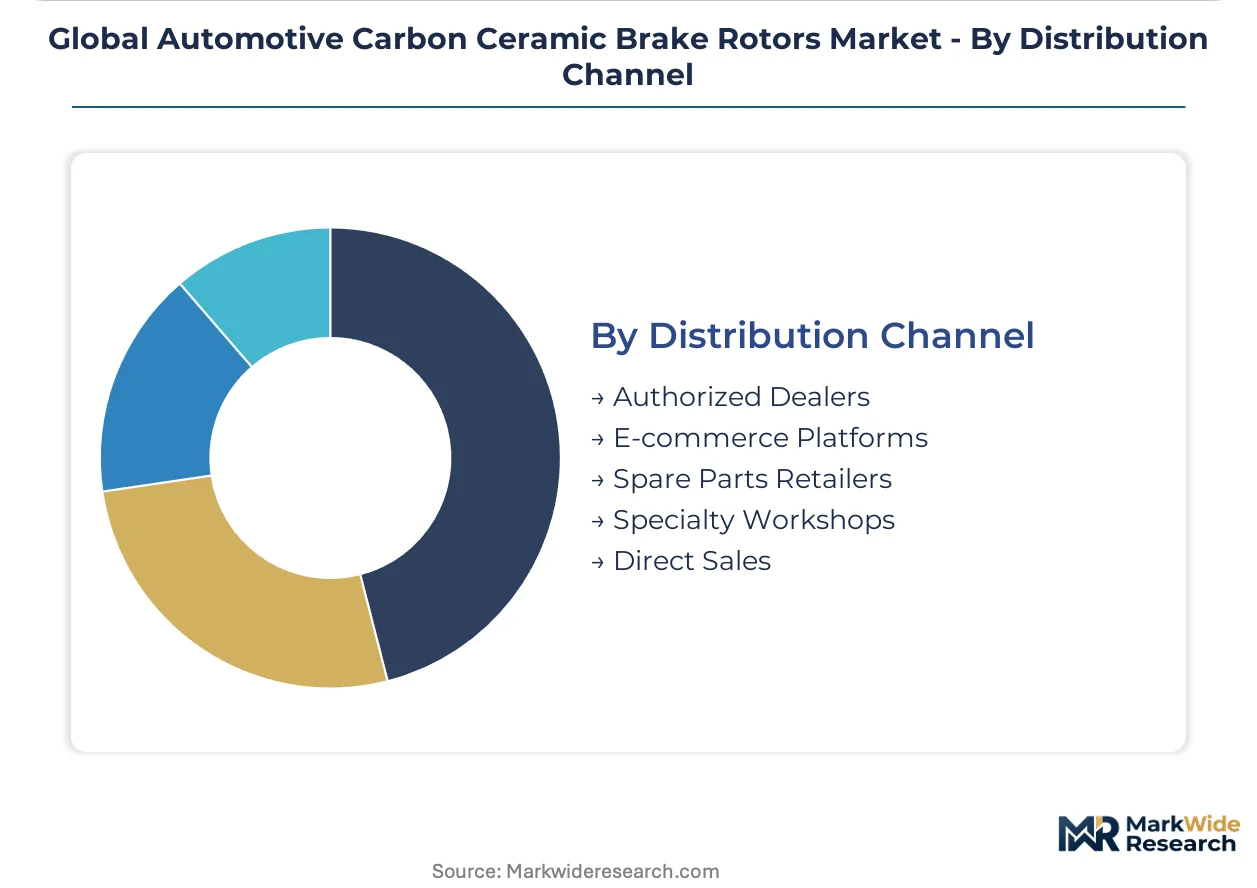
- Direct Sales:This channel involves direct contracts between rotor manufacturers and OEMs, securing high-value, long-term supply agreements for factory-installed components. Brembo S.p.A. leverages this model.
- Authorized Dealers:These channels distribute original equipment replacement parts and performance upgrades through official vehicle dealerships. They cater to premium vehicle owners seeking certified components.
- E-commerce Platforms:Online platforms facilitate sales of aftermarket carbon ceramic rotors and performance upgrades directly to consumers and specialized workshops.
- Spare Parts Retailers:These outlets offer a range of braking components, including carbon ceramic options, to independent repair shops and DIY enthusiasts.
- Specialty Workshops:Performance-oriented workshops procure carbon ceramic rotors for custom builds, track-day preparations, and high-end vehicle servicing.
The shift towards Direct Sales to OEMs optimizes value capture, while E-commerce Platforms offer future growth avenues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive carbon ceramic brake rotors market exhibits a pricing-power asymmetry, with Europe commanding premium pricing for high-performance applications while Asian markets prioritize cost-effectiveness. This geographic divergence influences manufacturing strategies and technology adoption across different regions. Manufacturers adapt product offerings to meet varied regional performance and economic requirements.
Germany
German automakers require high-thermal capacity for performance vehicles and lightweighting for new EV platforms. Europe's upcoming Euro 7 regulation compels manufacturers to consider low-dust braking solutions. Automotive clusters in Bavaria and Baden-Württemberg drive advanced rotor integration for premium models.
China
China's burgeoning premium EV market creates significant volume potential for high-specification braking components. The nation's dual carbon goals accelerate electric vehicle development, increasing demand for lightweight solutions. Automotive production hubs in the Yangtze River Delta integrate advanced rotors into next-generation electric platforms.
United States
United States performance vehicle demand and emerging heavy-duty electric truck segments require superior braking power. The US National Highway Traffic Safety Administration (NHTSA) sets stringent performance standards for advanced braking systems. Automotive R&D centers in Michigan drive the integration of carbon ceramic rotors for high-performance and heavy-duty applications.
Japan
Japanese automakers prioritize performance and weight reduction for their sports car and premium EV lineups. Japanese Industrial Standards (JIS) guide the material quality and performance specifications for braking components. Major automotive manufacturers in the Aichi Prefecture integrate carbon ceramic rotors into their high-end vehicle offerings.
Italy
Italy's luxury sports car manufacturing drives consistent demand for high-performance carbon ceramic brake rotors. European CE marking requirements ensure components meet stringent safety and performance criteria for vehicle integration. The "Motor Valley" in Emilia-Romagna remains a hub for bespoke braking technology development for exclusive models.
Global Automotive Carbon Ceramic Brake Rotors Market Key Industry Players
Material science innovators and integrated system providers split the market for automotive carbon ceramic brake rotors, each leveraging distinct competitive advantages. The market structure favors established players with deep material science expertise and robust OEM relationships, creating high barriers to entry for newcomers. Strategic archetypes include these technology-focused innovators, alongside specialized component manufacturers and regional niche players catering to specific automotive clusters. Dominant competitive moves involve continuous process innovation to reduce complex manufacturing cycle times and strategic partnerships for advanced material co-development.
Within the integrated system provider archetype, Brembo S.p.A., an Italian manufacturer, exemplifies strong brand recognition and established OEM relationships for flagship vehicle platforms. SGL Group, a German entity, anchors the material science segment through its specialization in underlying carbon fiber material science, providing a critical supply chain advantage to the industry. Akebono Brake Industry, a Japanese corporation, represents regional strength with an extensive presence in the Asian automotive sector, particularly with Japanese automakers. These companies collectively illustrate the diverse strategies for market penetration and competitive differentiation in the global carbon ceramic brake rotor landscape.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| SGL Group |
| Akebono Brake Industry |
| Surface Transforms |
| Fusion Brakes |
| Federal Mogul |
| Aisin Seiki |
| Alcon Components |
| Wilwood Engineering |
| Others |
Cost & Logistics Intelligence
German automotive manufacturing clusters' specialized production capacity directly influences downstream pricing power for high-performance brake rotors. This concentration in advanced material processing impacts the cost structure for global premium vehicle platforms.
Pricing Analysis
Configured-to-order pricing for bespoke high-performance applications commands a significant premium over standard offerings. Price differentiation stems from the stringent ISO 9001 certification level required by OEMs and the degree of customization for specific vehicle platforms. Cost compression in the aftermarket segment intensifies due to the availability of alternative braking solutions. OEMs procuring for flagship models demonstrate the least price sensitivity, valuing performance and brand alignment above all else.
Supply Chain Analysis
Extended payment terms for key suppliers and specialized supply-chain finance facilities are common in the capital-intensive carbon ceramic rotor industry. Geographic supply concentration includes Germany for advanced manufacturing, Japan for material science, and China for emerging material precursors. Raw material dependencies include aerospace-grade carbon fiber precursors and high-purity silicon. A structural supply chain risk is the single-source vulnerability for specialized carbon fiber grades. Downstream distribution primarily operates through direct sales channels to original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive carbon ceramic brake rotors market represents a significant service-attach opportunity. The after-sales market for replacement rotors and performance upgrades is expanding faster than initial factory installations.
For Market Incumbents: Pre-empt the threat from advanced coated cast iron rotors by accelerating process innovation to reduce manufacturing complexity. Consolidate market share through strategic partnerships with emerging EV manufacturers, particularly in high-growth Asian markets. Invest in next-generation discontinuous fiber composites to enhance durability against thermal shock, maintaining a technological lead.
For New Entrants and Emerging Players: Pursue niche applications such as high-performance electric SUVs and heavy-duty trucks, where superior braking power and heat dissipation are critical. Target the Asian market, especially China's premium EV segment, with cost-effective manufacturing techniques using alternative materials like chopped carbon fibers. A viable go-to-market angle involves offering integrated brake-by-wire corner modules to Tier-1 suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component manufacturers with strong material science capabilities. Long-term viability hinges on companies that can reduce production cycle times and lower raw material costs for carbon fiber. A signal to watch is the successful commercialization of alternative manufacturing processes for cost-effective, high-volume production.
| Strategic Initiative | Industry Significance |
|---|---|
| Process Innovation Investment | Reduces manufacturing cycle times, enabling higher volume production for OEMs. |
| Advanced Material Co-development | Enhances rotor durability and fracture toughness for new-generation EV applications. |
| Geographic Manufacturing Footprint | Establishes local production capabilities to serve burgeoning premium EV markets in Asia. |
| Systems Engineering Capability Expansion | Positions suppliers for integrated brake-by-wire corner module procurement with OEMs. |
| Supply Chain Resilience Building | Diversifies sourcing for critical carbon fiber precursors to mitigate single-source risks. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and extensive secondary research. Primary research involved conversations with OEM platform engineers, Tier-1 supplier procurement leads, automotive R&D directors, and aftermarket distributors. Secondary validation drew from vehicle production databases, regulatory filings from NHTSA and European bodies, and material science journals. The study employed both bottom-up and top-down triangulation to ensure data accuracy.
Forecast inputs considered include vehicle class, propulsion architecture, content per vehicle, and regional regulatory frameworks across the analysis window. The analytical framework modeled market dynamics by product type, application, end-user, and distribution channel. Compound annual growth rates were derived from historical data trends and projected adoption rates in emerging vehicle segments. Industry-specific forecast inputs included EV lightweighting mandates and performance segment demand.
Macroeconomic conditions sit as an overlay; deviation in global automotive production volumes or raw material commodity prices would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Geopolitical shifts or unforeseen supply chain disruptions could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Resonator Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
US Automotive Composites Market
Automotive Components
Japan Automotive Sunroof Market