
 Automotive Part Cleaners and Degreasers Market | 2026-2036
Automotive Part Cleaners and Degreasers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Part Cleaners and Degreasers Market Analysis
Germany's chemical manufacturing base is reshaping supply dynamics for automotive cleaning formulations. Dow Chemical leverages its integrated surfactant production to sustain cost advantages across European distribution networks. BASF anchors high-performance aqueous cleaner development through specialized R&D facilities near Ludwigshafen. Wurth dominates the direct-to-workshop channel, controlling inventory placement at over 70,000 service bays.
Automotive part cleaners and degreasers are formulated chemical solutions designed to remove lubricants, carbon deposits, and metallic contaminants from engine blocks, brake assemblies, and transmission housings, typically operating at pH ranges from 9 to 14 for alkaline aqueous systems and flash points above 60°C for solvent variants to ensure workshop safety. Their primary industrial purpose centers on restoring component surface integrity prior to reassembly, inspection, or coating adhesion. Aqueous cleaners occupy the largest volume position due to regulatory pressure on volatile organic compound emissions, while biodegradable formulations represent the fastest-expanding margin pool as fleet operators adopt sustainability procurement criteria. Solvent-based cleaners retain entrenched demand in electrical component applications where rapid evaporation and non-conductive residues remain technically essential.
EPA oversight under the Clean Air Act limits perchloroethylene content in aerosol degreasers sold through US retail channels, while REACH registration requirements enforce full substance toxicity documentation for solvent-based products entering European customs territory. Germany's Federal Institute for Risk Assessment evaluates cleaner formulations for worker exposure limits in independent workshop environments. Stakeholders must monitor pending amendments to OSHA hazard communication standards and assess whether reformulation investments align with anticipated state-level restrictions on trichloroethylene.
Market Dynamics
REACH restrictions on chlorinated solvents are redirecting European formulators toward aqueous and bio-based alternatives, compressing legacy solvent margins while elevating R&D intensity across the value chain.
Growth Catalysts
- Aftermarket service chain expansion:Brake and engine maintenance protocols at national service networks are elevating chemical sourcing volumes for high-frequency cleaning operations.
- EU Green Deal alignment:Fleet operators are embedding sustainability procurement criteria that favor biodegradable formulation grades over conventional solvent systems.
- OEM-certified specifications:Procurement standards in Germany's industrial corridor are mandating documented surface integrity restoration prior to component reassembly.
Market Restraints
- Petrochemical feedstock volatility:Surfactant input costs fluctuate with crude derivatives, squeezing aqueous cleaner margins during upstream price spikes.
- Supply concentration in specialty surfactants:European integrated producers dominate key intermediate supply, creating procurement bottlenecks for independent formulators.
- Technical limitation in electrical components:Solvent-based systems retain entrenched demand where rapid evaporation and non-conductive residues remain technically essential, slowing aqueous penetration.
Strategic Opportunities
- Underpenetrated fleet maintenance segment:Commercial vehicle operators in Eastern Europe lack standardized cleaning protocols, presenting white space for specification-grade product introduction.
- Workshop channel digitization:Direct-to-bay inventory placement platforms are compressing traditional distributor layers and capturing real-time consumption data.
- CSRD reporting mandates:Corporate sustainability disclosure requirements are elevating demand for certified biodegradable formulations with documented lifecycle credentials.
Industry Challenges
- Formulation chemist scarcity:Expertise in pH-stable aqueous systems operating between 9 and 14 is concentrating at legacy chemical firms, constraining new entrant R&D velocity.
- Multi-jurisdiction compliance timelines:Parallel OSHA hazard communication amendments and state-level trichloroethylene restrictions are forcing redundant safety data sheet reformulation cycles.
- Flash point certification complexity:Workshop safety protocols demand flash points above 60°C for solvent variants, extending product qualification timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Part Cleaners and Degreasers Market |
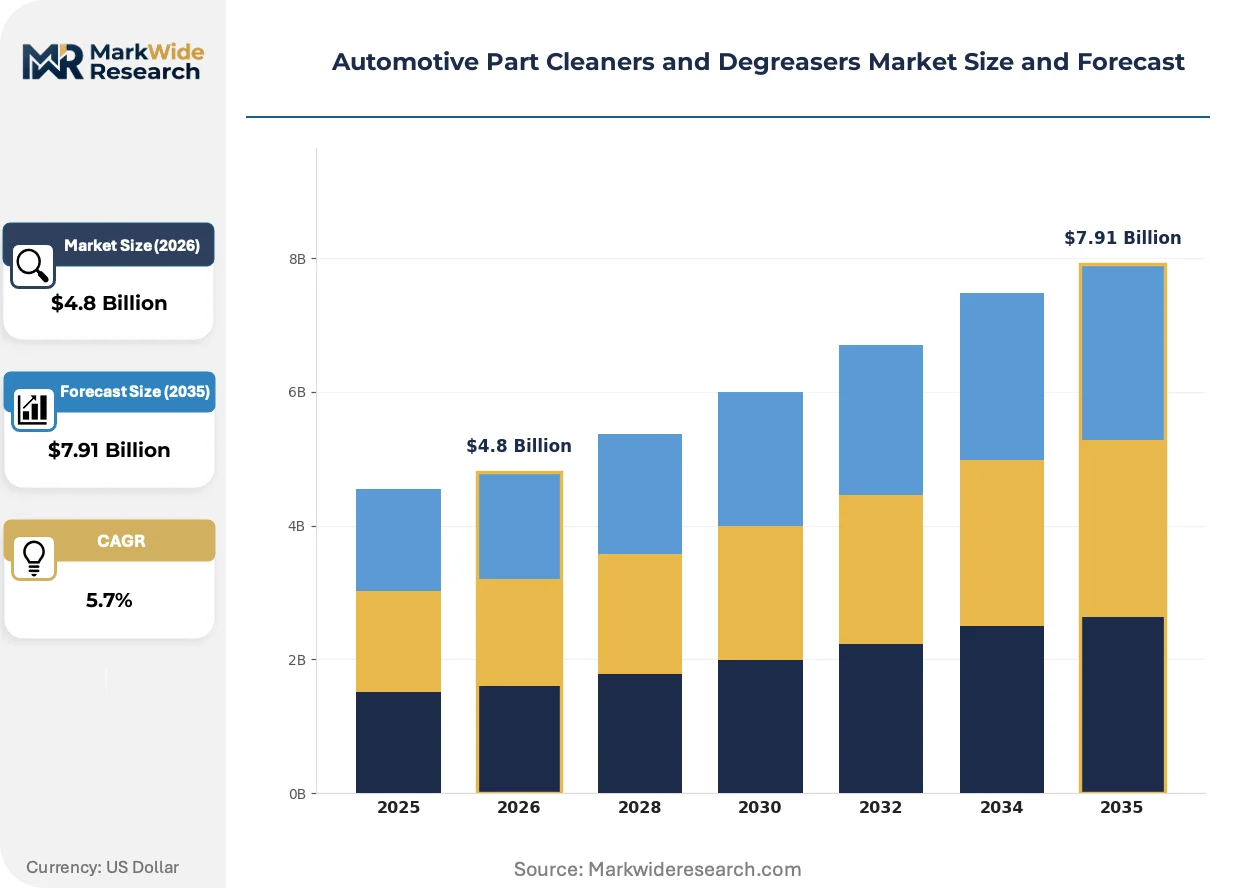
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Cleaners, Solvent-Based Cleaners, Biodegradable Cleaners, Heavy-Duty Degreasers Application: Engine Parts, Chassis Components, Brake Parts, Electrical Components End User: Automotive Manufacturers, Repair Shops, DIY Enthusiasts, Fleet Operators Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Dow Chemical, Wurth, 3M, Penray, Zep, BASF, Fuchs Group, Valvoline, WD-40, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Part Cleaners and Degreasers Market Emerging Trajectories
Formulation chemistry is converging with digital supply chain tools and tightening chemical safety frameworks, compressing product development cycles while elevating transparency requirements across the value chain.
Alkaline aqueous systems with surfactant packages optimized for metallic contaminant removal are hybridizing with bio-based solvent boosters to bridge performance gaps in carbon deposit applications. Tier-1 suppliers are piloting these hybrid chemistries at OEM remanufacturing facilities. The technology is hybridizing traditional aqueous cost structures with solvent-grade cleaning efficacy, forcing incumbent formulators to defend position through accelerated R&D cycles.
REACH registration requirements now enforce full substance toxicity documentation for solvent-based products entering European customs territory. This documentation burden is elevating compliance costs for small-batch importers. Aerosol degreaser categories face the steepest documentation requirements, pushing volume toward pre-registered aqueous concentrate formats.
Fleet procurement departments are consolidating chemical sourcing decisions at regional headquarters, displacing decentralized workshop-level purchasing. National leasing companies are mandating approved vendor lists with certified sustainability credentials. Germany's commercial vehicle operators are the most advanced in this consolidation pattern, compressing supplier counts while elevating contract values for qualified formulators.
Automotive Part Cleaners and Degreasers Market Segmentation
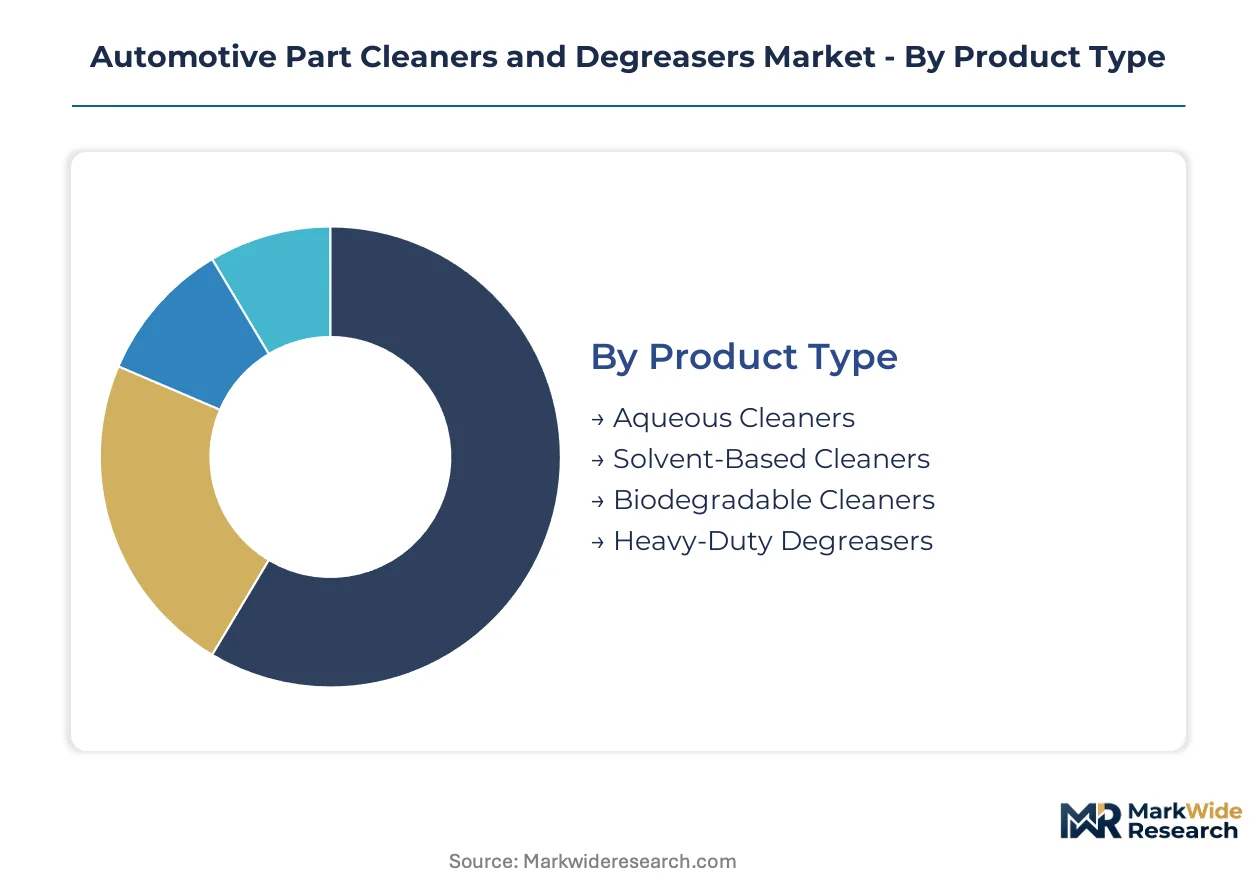
Automotive part cleaners and degreasers serve distinct technical requirements across formulation chemistries and end-use environments. Segmentation reveals where regulatory pressure, performance specifications, and procurement consolidation are reshaping competitive dynamics.
Product Type:
Mature alkaline aqueous systems coexist with emerging bio-based formulations as REACH restrictions compress legacy solvent margins.
- Aqueous Cleaners:Alkaline formulations operating between pH 9 and 14 with optimized surfactant packages for metallic contaminant removal. Procurement at German OEM remanufacturing facilities concentrates volume here as REACH documentation burdens elevate compliance costs for solvent alternatives.
- Solvent-Based Cleaners:Hydrocarbon and chlorinated systems with flash points engineered above 60°C for workshop safety protocols. Demand retains entrenched positioning in electrical component applications where rapid evaporation and non-conductive residues remain technically essential.
- Biodegradable Cleaners:Plant-derived surfactant systems with documented lifecycle credentials for CSRD reporting mandates.
- Heavy-Duty Degreasers:Concentrated formulations targeting carbon deposit removal from engine blocks and transmission housings.
Aqueous cleaners handle the majority of throughput; biodegradable formulations are climbing the fastest on share.
Application:
Cost tier differentiation separates specification-grade OEM protocols from high-volume aftermarket maintenance operations.
- Engine Parts:Cleaning of blocks, heads, and transmission housings prior to reassembly or remanufacturing. Germany's industrial corridor concentrates demand as OEM-certified surface integrity specifications dominate procurement standards.
- Brake Parts:Degreasing of calipers, rotors, and hydraulic assemblies where residue-free surfaces prevent friction coefficient degradation. National service network expansion is elevating chemical sourcing volumes for high-frequency cleaning protocols.
- Chassis Components:Frame and suspension cleaning for corrosion protection and coating adhesion preparation.
- Electrical Components:Precision cleaning of sensors, connectors, and control modules where conductivity preservation is critical.
Engine parts cleaning commands the largest contract values; brake maintenance applications are expanding most quickly as service chains proliferate.
End User:
Customer type fragmentation spans centralized fleet procurement and decentralized workshop purchasing with diverging specification requirements.
- Automotive Manufacturers:OEM production lines and remanufacturing facilities with documented surface integrity protocols. Integrated chemical supply agreements at Ludwigshafen-area production clusters concentrate volume for specification-grade formulations.
- Fleet Operators:Commercial vehicle and leasing company procurement departments consolidating chemical sourcing at regional headquarters. Germany's national leasing companies are mandating approved vendor lists with certified sustainability credentials.
- Repair Shops:Independent and national chain service bays requiring inventory placement flexibility.
- DIY Enthusiasts:Consumer retail channels with aerosol and ready-to-use format preferences.
Fleet operators are capturing the steepest expansion trajectory as procurement centralization accelerates; automotive manufacturers retain the highest per-unit specification intensity.
Distribution Channel:
Supply concentration in specialty surfactant intermediates shapes channel economics for independent formulators versus integrated producers.
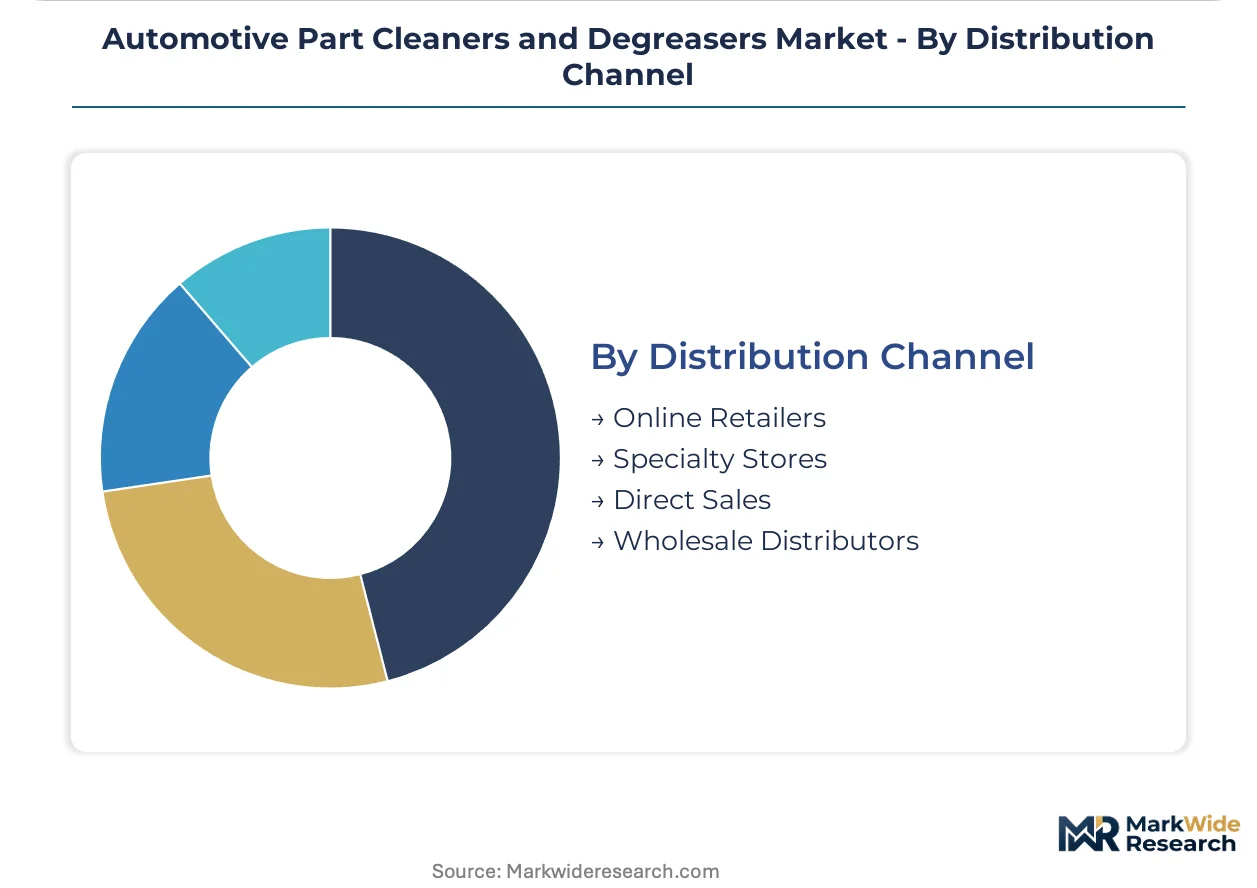
- Direct Sales:Formulator-to-fleet and formulator-to-OEM contracts with technical service support. Wurth controls inventory placement at over 70,000 service bays through direct-to-workshop channel dominance.
- Wholesale Distributors:Regional chemical distributors serving independent repair shops and smaller fleet operators.
- Specialty Stores:Automotive aftermarket retailers with branded product placement.
- Online Retailers:E-commerce platforms capturing real-time consumption data and compressing traditional distributor layers.
Direct sales channels handle the majority of specification-grade volume; online retail is gaining share fastest as workshop digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement through ECHA anchors European formulation standards, redirecting chlorinated solvent demand toward aqueous alternatives and compressing legacy margins across the value chain.
Germany
OEM-certified cleaning specifications dominate procurement at remanufacturing facilities in the Ludwigshafen industrial corridor. The Federal Institute for Risk Assessment evaluates workshop exposure limits for independent service environments. BASF's specialized R&D facilities near Ludwigshafen anchor high-performance aqueous cleaner development for specification-grade contracts.
United States
EPA oversight under the Clean Air Act limits perchloroethylene content in aerosol degreasers sold through retail channels. OSHA hazard communication standards govern safety data sheet requirements for solvent-based products. National service network expansion elevates chemical sourcing volumes for brake and engine maintenance protocols at high-frequency operations.
China
Dual carbon goals under MEE direction accelerate demand for biodegradable formulations at fleet procurement departments. GB standards establish technical benchmarks for cleaner efficacy in automotive remanufacturing applications. Yangtze River Delta production clusters concentrate aqueous cleaner manufacturing capacity for domestic OEM supply agreements.
Japan
METI industrial policy supports transition toward low-VOC cleaning systems at precision component manufacturers. JIS standards define surface integrity requirements for electrical component applications where rapid evaporation remains technically essential. Kansai-region automotive suppliers maintain entrenched solvent demand for sensor and connector cleaning operations.
India
BIS certification requirements create entry barriers for imported solvent formulations at organized workshop chains. The PLI scheme for automotive components indirectly elevates cleaning protocol standardization at OEM supplier parks. Maharashtra-based fleet operators are consolidating chemical sourcing decisions at regional headquarters with emerging sustainability criteria.
Automotive Part Cleaners and Degreasers Market Vendor Landscape
Integrated chemical majors and specialized distribution networks split the market between specification-grade formulation and direct-to-workshop channel control. The vendor base concentrates around legacy surfactant producers with captive intermediate supply and national service chains with inventory placement scale. Three archetypes dominate: petrochemical-integrated formulators with backward control over surfactant inputs, specialized chemical distributors with technical service capabilities, and direct-channel operators with bay-level inventory access. Competitive moves center on R&D acceleration for REACH-compliant aqueous systems and digitization of workshop replenishment platforms.
Within the integrated formulator tier, Dow Chemical and BASF exemplify petrochemical-backed aqueous cleaner development. Wurth occupies a distinct position in direct-channel distribution. These three anchors span the value chain from surfactant production through specification-grade formulation to bay-level inventory placement, representing the structural concentration that constrains new entrant procurement access and elevates contract values for qualified suppliers.
| Leading Market Players |
|---|
| Dow Chemical |
| Wurth |
| 3M |
| Penray |
| Zep |
| BASF |
| Fuchs Group |
| Valvoline |
| WD-40 |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European surfactant intermediates is elevating input costs for independent formulators while compressing margins across aqueous cleaner tiers. German integrated producers leverage captive ethylene oxide supply to sustain pricing power against distributors sourcing spot market feedstock.
Pricing Analysis
German specification-grade aqueous cleaners command substantial premiums over Eastern European economy formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with OEM-certified products bearing REACH documentation costs passed through contract values. Pricing pressure stems from petrochemical feedstock volatility squeezing aqueous cleaner margins during upstream crude derivative spikes. Fleet operators exhibit lowest price sensitivity due to consolidated procurement at regional headquarters, while independent repair shops face acute cost pressure from inventory placement fees.
Supply Chain Analysis
Export-control restrictions on specialty surfactant technology limit technology transfer to non-integrated formulators outside Germany and the United States. Supply concentrates in Germany's Ludwigshafen corridor, China's Yangtze River Delta, and US Gulf Coast petrochemical complexes. Formulation chemistry draws from ethylene oxide derivatives, bio-based solvent precursors, and pH-stabilizing additives. Single-source vulnerability in European specialty surfactant intermediates creates procurement bottlenecks for independent formulators. Distribution runs through direct-to-workshop platforms compressing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as REACH enforcement accelerates solvent-to-aqueous conversion across European fleet procurement departments. Biodegradable formulation adoption at national leasing companies provides the clearest penetration tailwind.
For Market Incumbents: Insulate specification-grade margins by deepening backward integration into surfactant intermediates at Ludwigshafen-area production clusters. Accelerate REACH-compliant aqueous R&D to defend position against hybrid bio-solvent entrants targeting carbon deposit applications. Channel control through direct-to-bay inventory placement remains the critical lever against distributor disintermediation. For New Entrants and Emerging Players: Eastern European fleet maintenance operations represent the most penetrable entry point given absence of standardized cleaning protocols and limited incumbent specification-grade presence. Workshop digitization platforms in Poland and Czech Republic offer channel access without legacy distributor relationships. Lead with certified biodegradable formulations carrying CSRD-compliant lifecycle documentation to bypass entrenched solvent supply agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-channel operators with bay-level inventory placement contracts spanning 70,000-plus service locations. Long-term viability favors integrated formulators with captive surfactant supply and REACH registration portfolios. Monitor fleet procurement centralization velocity at German national leasing companies as the primary inflection signal for contract value expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Intermediates | Captive ethylene oxide supply at Ludwigshafen facilities neutralizes feedstock volatility for BASF and Dow Chemical. |
| Biodegradable Formulation Certification | CSRD-compliant lifecycle credentials unlock fleet procurement contracts at Germany's national leasing companies. |
| Direct-to-Workshop Channel Digitization | Wurth's bay-level inventory placement platform captures real-time consumption data compressing distributor margins. |
| REACH-Compliant Aqueous R&D Acceleration | Hybrid bio-solvent development at OEM remanufacturing facilities bridges performance gaps in carbon deposit removal. |
| Eastern European Fleet Market Entry | Specification-grade product introduction targets underpenetrated commercial vehicle operators lacking standardized protocols. |
Methodological Framework
The analysis maps aqueous cleaner formulations, solvent-based systems, biodegradable alternatives, and heavy-duty degreaser categories, each validated through formulation chemists, fleet procurement directors, aftermarket distributor executives, and OEM technical specification leads. Primary fieldwork combined structured interviews with secondary validation against ECHA REACH registration databases, German Federal Institute for Risk Assessment exposure guidelines, EPA Clean Air Act enforcement records, and customs trade flow data. Bottom-up segment sizing triangulated against top-down chemical industry production statistics.
Forecast assumptions held regulatory enforcement timelines and crude derivative price corridors fixed while varying fleet procurement centralization rates and workshop digitization penetration. The analytical framework modeled formulation chemistry, application intensity, end-user procurement structure, and distribution channel evolution across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by specification-grade contract values and economy-tier spot pricing. Industry-specific inputs included REACH registration cost burdens and flash point certification timelines.
Practitioners should monitor ECHA enforcement intensity and petrochemical feedstock volatility for early signals of margin compression or formulation cost shifts. Forecasts reflect assumptions around sustained REACH compliance timelines and stable fleet sustainability procurement criteria. Material shifts in chlorinated solvent restriction scope or surfactant intermediate supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Silencer Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market