
 Hydrogen-Powered Yacht Market | 2026-2036
Hydrogen-Powered Yacht Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen-Powered Yacht Market Analysis
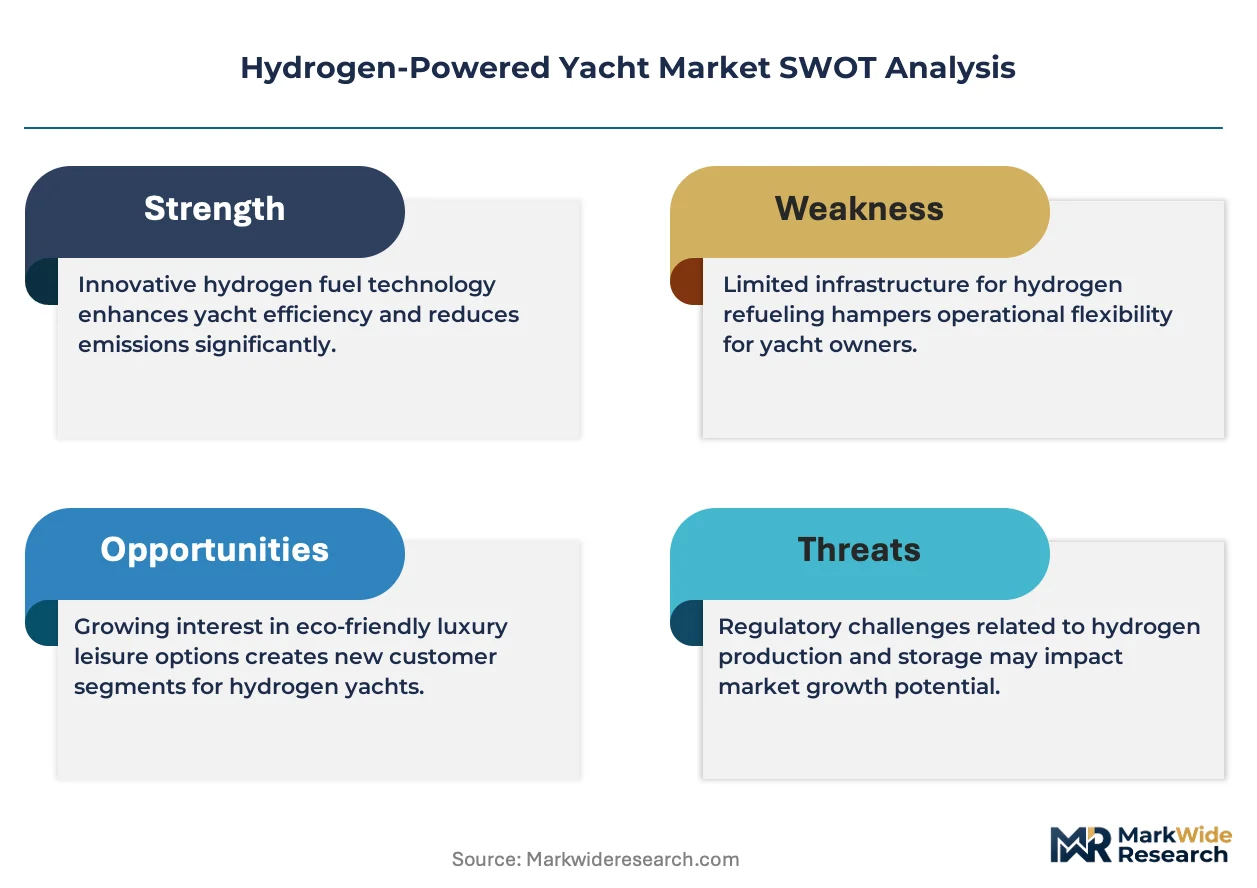
The buyer base for hydrogen-powered yachts is broadening from a narrow ultra-wealthy collector pool toward diversified charter operators and research institutions. Feadship anchors its position through bespoke superyacht construction with integrated fuel-cell systems. Oceanco differentiates via hydrogen-ready hull architecture and Dutch shipbuilding heritage. Golden Gate Zero Emission Marine specializes in commercial ferry-to-yacht technology transfer for the North American market.
A hydrogen-powered yacht employs proton-exchange membrane fuel cells or liquid hydrogen combustion to generate propulsion, typically storing H2 at 350-700 bar in Type IV composite tanks for ranges exceeding 1,000 nautical miles. Motor yachts dominate current order books due to simpler hull integration and larger powertrain envelopes. Luxury yachts capture premium margin pools as owners absorb early fuel-cell costs. The charter application segment is expanding fastest as operators seek differentiated sustainability credentials for corporate clientele.
The International Maritime Organization, EU Green Deal framework, and US EPA marine engine standards collectively mandate carbon-intensity reductions that push shipyards toward hydrogen pathways. Classification societies including Lloyd's Register and DNV now publish provisional rules for hydrogen-fueled pleasure craft, creating compliance benchmarks that shape design investment. Stakeholders must monitor fuel-cell durability in salt-air environments and bunkering infrastructure commitments before committing capital to newbuild programs.
Market Dynamics
The International Maritime Organization's carbon-intensity reduction mandates are compressing design timelines for zero-emission propulsion systems. Shipyards now face binding compliance deadlines that favor hydrogen pathways over incremental efficiency gains.
Growth Catalysts
- IMO Decarbonization Targets:The International Maritime Organization's carbon-intensity indicators mandate absolute emission reductions for vessels over 400 gross tons. Superyacht builders must demonstrate compliance through hydrogen fuel-cell certification.
- EU Green Deal Marine Fuel Standards:The European Union's Green Deal framework tightens marine fuel sulfur and carbon specifications. Dutch and Monegasque shipyards secure competitive positioning by integrating hydrogen storage systems early.
- Charter Operator Differentiation:Corporate charter clients demand verifiable sustainability credentials for executive retreats and board meetings. Operators in the United Arab Emirates and Netherlands convert hydrogen-powered vessels into premium booking categories.
Market Restraints
- Liquid Hydrogen Storage Costs:Type IV composite tanks rated for 700 bar pressure require carbon-fiber winding and multi-layer vacuum insulation. Material costs for these tanks exceed conventional diesel storage by an order of magnitude.
- Bunkering Infrastructure Gaps:Hydrogen refueling stations for maritime use concentrate in Rotterdam, Singapore, and select Norwegian ports. Yacht operators face range anxiety on transoceanic itineraries without guaranteed fuel availability.
- Fuel-Cell Salt-Air Degradation:Proton-exchange membrane stacks suffer accelerated catalyst corrosion in marine environments. Replacement intervals for maritime fuel cells remain unproven at commercial scale.
Strategic Opportunities
- Research Institution Charters:Oceanographic institutes and climate research programs seek zero-emission platforms for sensitive marine ecosystems. Hydrogen yachts enable acoustic-quiet operations impossible with diesel-electric hybrids.
- US EPA Marine Engine Standards:The Environmental Protection Agency's Tier 4 and emerging Tier 5 standards tighten nitrogen oxide and particulate limits for recreational vessels. California and Florida operators gain compliance advantages through hydrogen adoption.
- Hybrid Architecture Convergence:Integration of solid-oxide fuel cells with battery-electric buffers enables variable load optimization. This pairing reduces hydrogen consumption during harbor maneuvering and anchorage.
Industry Challenges
- Marine Hydrogen Systems Engineering:Shipyards lack personnel trained in high-pressure gas containment, cryogenic handling, and fuel-cell thermal management. Recruitment from aerospace and automotive sectors drains talent pools.
- Classification Society Certification Timelines:Lloyd's Register and DNV provisional rules for hydrogen-fueled pleasure craft require extensive prototype testing. Newbuild programs face 18-24 month approval cycles before keel laying.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen-Powered Yacht Market |
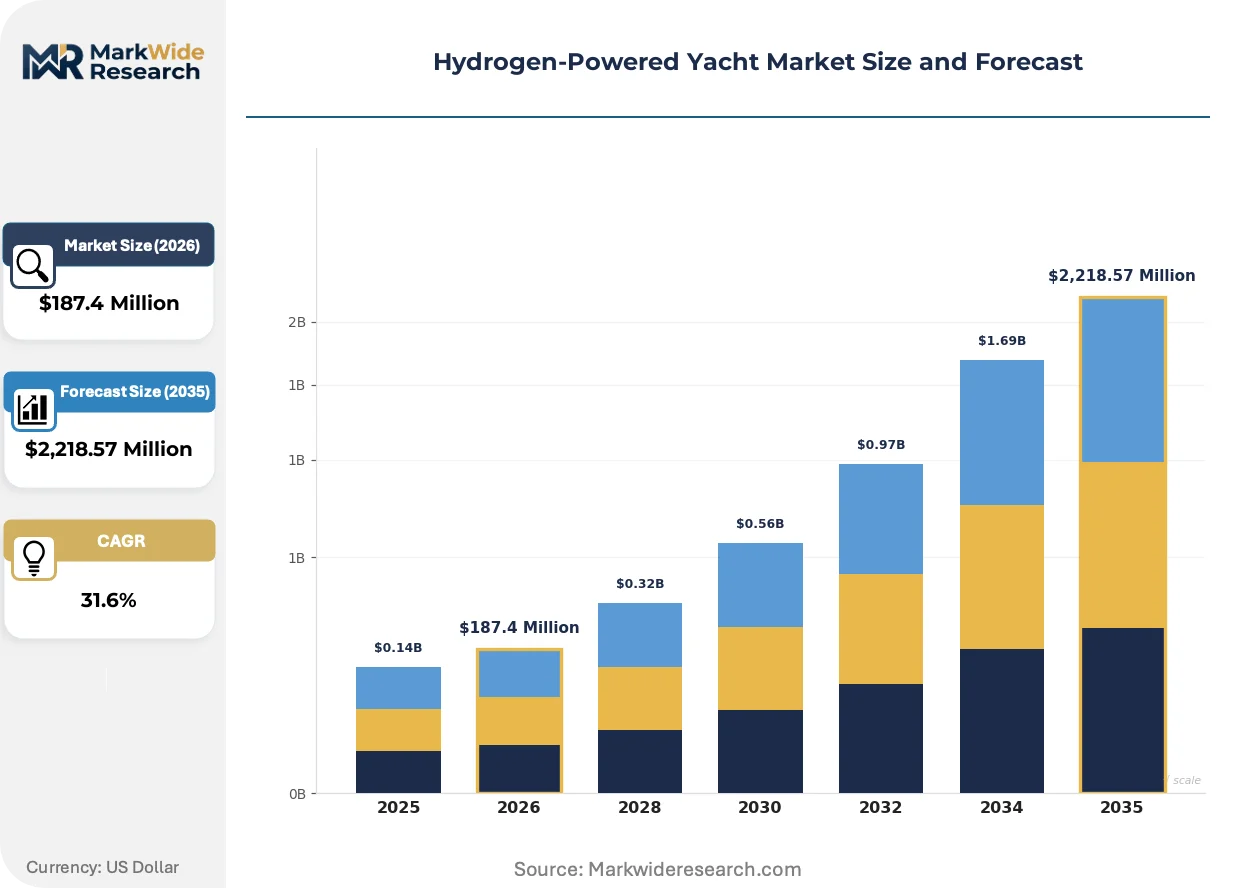
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sailing Yachts, Motor Yachts, Luxury Yachts, Commercial Vessels Application: Leisure, Charters, Research, Commercial Activities Size: Small Yachts, Medium Yachts, Large Yachts, Mega Yachts End User: Private Owners, Charter Companies, Research Institutions, Maritime Organizations |
| Companies Covered | Golden Gate Zero Emission Marine, Oceanco, Feadship, Overmarine Group, Sanlorenzo, SW/TCH Maritime, Lurssen, Pershing, All American Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen-Powered Yacht Market Emerging Trajectories
Solid-state hydrogen storage and advanced fuel-cell architectures are compressing the performance gap between zero-emission and conventional marine propulsion. Shipyards now compete on integrated system efficiency rather than hull aesthetics alone.
Proton-exchange membrane fuel-cell stacks paired with lithium-titanate battery buffers are electrifying auxiliary power architectures on motor yachts above 50 meters. Charter operators in Monaco and the Netherlands specify these configurations for silent overnight anchorage without generator noise. The technology is electrifying competitive bidding for corporate sustainability mandates that exclude diesel-dependent vessels.
The EU Green Deal's FuelEU Maritime initiative imposes well-to-wake greenhouse gas intensity limits on commercial and recreational vessels calling at European ports. Shipyards serving Dutch and German clients must document renewable hydrogen provenance through certified supply chains. Superyacht projects with delivery schedules after 2030 now specify green hydrogen offtake agreements as contract conditions.
Corporate charter procurement now requires third-party verified carbon accounting for entire voyage footprints. Operators in the United Arab Emirates and United States respond with blockchain-tracked fuel certificates and real-time emission dashboards. This behavioral shift concentrates demand on shipyards offering integrated digital transparency tools rather than standalone vessel specifications.
Hydrogen-Powered Yacht Market Segmentation
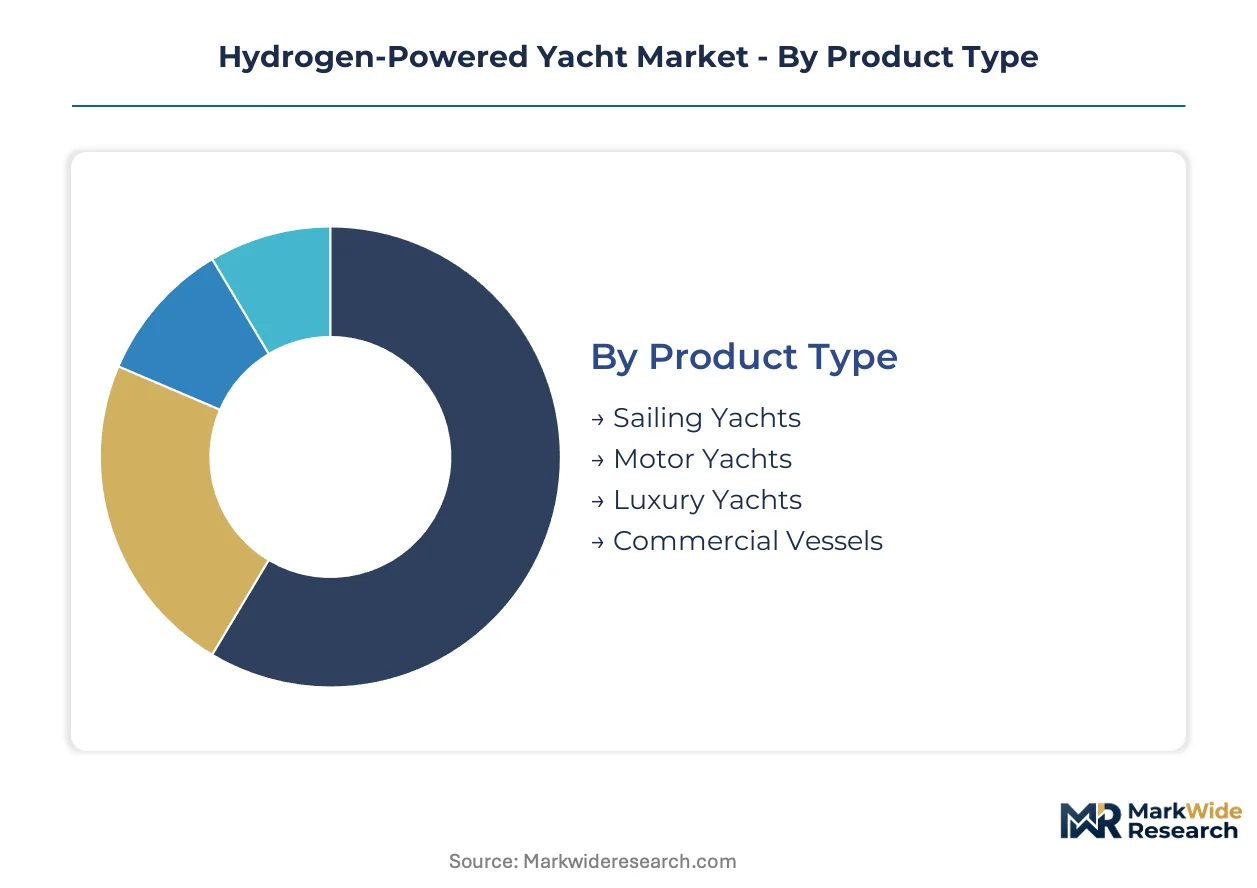
Hydrogen propulsion architectures diverge sharply across hull configurations and operational profiles. Shipyards configure fuel-cell systems, tank geometries, and power management differently for each segment, creating distinct engineering pathways and margin structures.
Product Type:
Buyers in this category separate by hull complexity tolerance and integration budget for hydrogen systems.
- Motor Yachts:Flat deck surfaces and generous engine room volumes accommodate 350-700 bar Type IV composite tanks with minimal structural modification. Dutch shipyards in the Netherlands dominate current order books as charter operators seek straightforward diesel displacement for coastal itineraries.
- Luxury Yachts:Bespoke construction absorbs premium fuel-cell costs through owner-funded sustainability mandates. Monaco-based builders integrate hydrogen systems as signature engineering statements for ultra-high-net-worth clients prioritizing emission-free credentials over operational simplicity.
- Sailing Yachts:Limited auxiliary power demand suits smaller proton-exchange membrane stacks for harbor maneuvering and hotel loads. Rigging interference constrains tank placement to hull extremities.
- Commercial Vessels:Ferry and workboat operators transfer proven fuel-cell architectures from public transit applications. North American yards leverage Golden Gate Zero Emission Marine technology for harbor craft conversions.
Volume sits with Motor Yachts; growth tilts toward Luxury Yachts.
Application:
Operational intensity and emission scrutiny levels differentiate procurement priorities across use cases.
- Charters:Corporate clients demand blockchain-verified carbon accounting for executive retreats. United Arab Emirates operators convert hydrogen credentials into premium booking categories with 40-60% rate premiums over conventional diesel vessels.
- Research:Oceanographic institutes require acoustic-quiet propulsion for marine mammal studies. Fuel-cell systems eliminate diesel generator noise signatures impossible with hybrid alternatives.
- Leisure:Private owners balance range anxiety against marina prestige. Mediterranean home-porting patterns favor vessels with 1,000+ nautical mile hydrogen reserves.
- Commercial Activities:Harbor pilot boats and offshore service craft face binding EU Green Deal compliance deadlines at European ports. Operators specify dual-fuel architectures as transitional risk mitigation.
Deployment frequency concentrates in Charters; steepest expansion trajectory belongs to Research.
Size:
Hull displacement determines tank volume scalability and fuel-cell stack modularity.
- Mega Yachts:Exceeding 80 meters LOA, these vessels integrate multiple 700 bar tank arrays and redundant fuel-cell systems without compromising guest accommodation. German and Dutch yards specialize in cryogenic handling infrastructure at this scale.
- Large Yachts:50-80 meter envelopes force trade-offs between hydrogen range and tender garage capacity. Owners accept 800-1,200 nautical mile operational radii to preserve waterline aesthetics.
- Medium Yachts:24-50 meter hulls represent the technical frontier where fuel-cell power density challenges conventional diesel-electric performance. Classification society certification timelines extend 18-24 months for prototypes in this bracket.
- Small Yachts:Below 24 meters, compressed hydrogen storage volume fractions exceed practical limits for transoceanic use. Day-boat and coastal configurations dominate with shore-power hydrogen refueling.
Order value aggregates in Mega Yachts; technology maturation focuses on Medium Yachts.
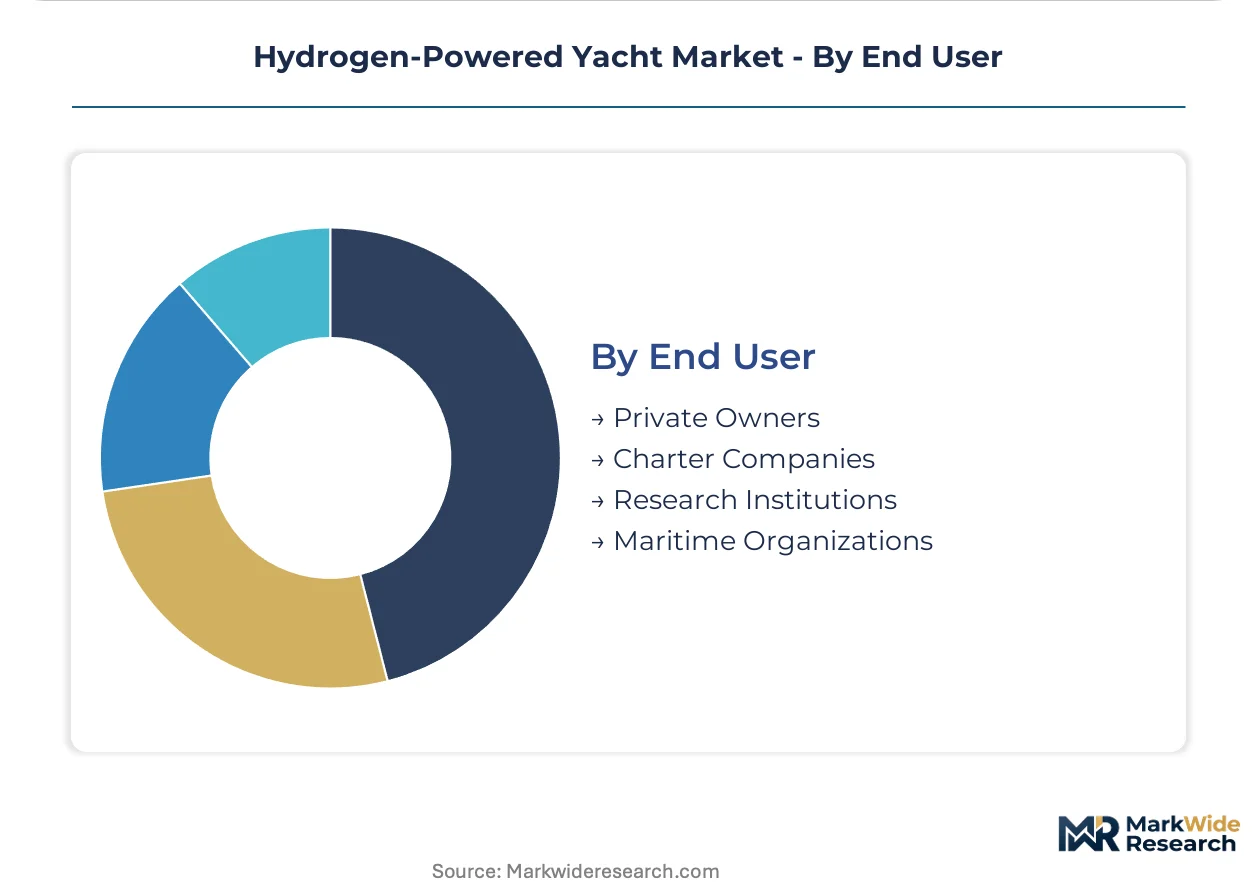
End User:
Capital structure and compliance pressure shape procurement velocity and specification stringency.
- Private Owners:Balance sheet capacity absorbs first-mover technology risk. Monaco and Dubai registrants specify integrated fuel-cell systems as depreciation-resistant asset features.
- Charter Companies:Fleet standardization pressures drive repeat orders from single shipyards. Netherlands-based operators achieve economies of scale in crew training and maintenance protocols.
- Research Institutions:Grant-funded acquisition cycles favor demonstrator vessels with public co-investment. Norwegian and German oceanographic programs anchor early adoption.
- Maritime Organizations:Pilotage and harbor authorities face regulatory mandates without commercial revenue buffers. EU Green Deal enforcement accelerates replacement timelines for aging diesel fleets.
Contract flow concentrates with Private Owners; policy leverage favors Maritime Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's hydrogen bunkering terminals anchor European maritime decarbonization infrastructure. Dutch shipyards leverage this feedstock proximity to secure early-mover contracts. Monaco and Dubai superyacht registries compete for zero-emission vessel flagging.
Netherlands
Amsterdam-Rotterdam-Antwerp corridor operators demand FuelEU Maritime compliance for charter fleets. The EU Green Deal mandates renewable hydrogen provenance documentation. Dutch shipyards in Alblasserdam and Zwijndrecht integrate 700 bar Type IV tank arrays into 50-80 meter motor yacht hulls.
United Arab Emirates
Dubai International Marine Club registers hydrogen-powered vessels for corporate charter premiums. MOHAP and federal maritime authorities draft emission standards for pleasure craft. Abu Dhabi National Oil Company hydrogen pilots supply Jebel Ali bunkering trials for superyacht operators.
Germany
Bavarian fuel-cell manufacturers supply PEM stacks to northern shipyards. The country's national hydrogen strategy funds maritime demonstrator programs. Hamburg and Bremen harbor authorities mandate zero-emission pilot boats by 2030, accelerating ferry-to-yacht technology transfer.
United States
California Air Resources Board rules push San Francisco Bay operators toward hydrogen harbor craft. EPA Tier 4 standards tighten recreational vessel engine limits. Florida charter companies in Fort Lauderdale specify hydrogen-ready hulls to attract sustainability-mandated corporate retreats.
Monaco
Yacht Club de Monaco requires carbon-intensity disclosures for regatta participation. The principality's flag registry offers expedited certification for fuel-cell vessels. Shipyards serving Monegasque clients integrate hydrogen systems as signature engineering statements for ultra-high-net-worth owners.
Hydrogen-Powered Yacht Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrogen-ready architecture and commercial ferry technology transfer. Dutch and German shipyards anchor the premium segment through bespoke construction capabilities. Three archetypes dominate: heritage superyacht builders with integrated fuel-cell divisions, commercial marine specialists applying ferry technology to leisure vessels, and hybrid-electric system integrators. Consolidation pressures favor shipyards with in-house hydrogen engineering teams; strategic partnerships with fuel-cell manufacturers accelerate certification timelines.
Within the heritage builder tier, Feadship and Oceanco exemplify European premium positioning through Dutch shipbuilding lineage. Golden Gate Zero Emission Marine represents the commercial-to-leisure technology transfer archetype, applying North American ferry fuel-cell expertise to yacht-scale applications. These three entities occupy distinct competitive spaces: bespoke superyacht construction, hydrogen-ready hull architecture, and maritime fuel-cell system integration respectively.
| Leading Market Players |
|---|
| Golden Gate Zero Emission Marine |
| Oceanco |
| Feadship |
| Overmarine Group |
| Sanlorenzo |
| SW/TCH Maritime |
| Lurssen |
| Pershing |
| All American Marine |
| Others |
Supply Flow & Price Mechanics
Carbon-fiber composite pricing indices cascade through hydrogen-powered yacht manufacturing into three distinct procurement tiers. Shipyards absorb Type IV tank material premiums through owner-funded sustainability mandates or charter rate markups, while classification society certification costs stratify final vessel positioning.
Pricing Analysis
Warranty and fuel-cell stack replacement bundling separates premium contracts from unbundled base configurations. Three-tier pricing structure across bespoke superyacht, series-production motor yacht, and commercial ferry-conversion levels reflects certification grade and after-sales service depth. Price differentiation hinges on Lloyd's Register or DNV certification tier and geographic delivery cost from Dutch or German shipyards. Cost compression in the medium-yacht segment intensifies because fuel-cell power density challenges diesel-electric benchmarks. Charter operators exhibit highest price sensitivity due to fleet standardization pressures, while ultra-high-net-worth private owners absorb premiums for emission-free credentials.
Supply Chain Analysis
Refurbishment flows for proton-exchange membrane stacks and tank recertification create reverse-logistics networks anchored in Rotterdam and Hamburg service hubs. Manufacturing concentration centers on the Netherlands, Germany, and Norway for hull construction and fuel-cell integration. The supply chain draws from Japanese carbon-fiber suppliers, South Korean battery buffer manufacturers, and Bavarian fuel-cell stack producers. Single-source vulnerability in 700 bar valve and pressure-regulator components exposes newbuild programs to extended lead times. Distribution runs through shipyard-direct commissioning with classification society oversight at each fabrication stage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen-powered yacht sector sits in a technology-transition phase where solid-oxide fuel-cell architectures displace first-generation proton-exchange membrane systems. This substitution dynamic rewards shipyards with in-house hydrogen engineering capabilities and penalizes diesel-dependent legacy builders.
For Market Incumbents: Acquire specialized fuel-cell integration teams from automotive and aerospace sectors to close talent gaps. Feadship and Oceanco should expand certification investment at Lloyd's Register and DNV to compress 18-24 month approval cycles. Backward integration into tank manufacturing mitigates carbon-fiber supply volatility from Japanese suppliers.
For New Entrants and Emerging Players: Begin with research institution charters in Norway and Germany where grant-funded acquisition cycles favor demonstrator vessels. The medium-yacht segment offers lowest competitive density for hydrogen-ready hull architecture. Partner with Golden Gate Zero Emission Marine for ferry-to-yacht technology transfer to accelerate time-to-certification.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Dutch shipyards with provisional classification society rules already in place. The five-to-ten-year viability window hinges on bunker infrastructure buildout at Jebel Ali and Singapore. Monitor IMO carbon-intensity enforcement timelines as the primary inflection signal for charter operator fleet replacement urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Fuel-Cell Stack Supply Agreement | Long-term offtake contracts with Bavarian PEM manufacturers secure stack availability for series production. |
| Classification Society Pre-Certification | Prototype testing under Lloyd's Register provisional rules compresses newbuild approval timelines. |
| Green Hydrogen Offtake Partnership | Renewable hydrogen supply contracts with Rotterdam terminal operators satisfy EU Green Deal documentation. |
| Battery Buffer Integration | Lithium-titanate pairing with fuel-cell systems enables silent anchorage operations for Monaco charter clients. |
| Crew Training Academy Investment | In-house certification programs for high-pressure gas containment reduce reliance on aerospace talent poaching. |
Methodological Framework
Classification society filings, EU Green Deal regulatory databases, and shipyard order book disclosures formed the secondary backbone for this analysis. Primary interviews with superyacht project managers, fuel-cell procurement leads at Dutch shipyards, charter fleet operators in Dubai, and DNV certification engineers validated segment sizing. The research combined bottom-up vessel-by-vessel order analysis with top-down marine decarbonization spending projections.
Historical trendline analysis of superyacht newbuild contracts and hydrogen infrastructure deployment informed the forecast framework. Segmentation modeling covered hull configuration, operational application, displacement tier, and end-user capital structure across the projection horizon. CAGRs were derived from shipyard capacity expansion announcements and FuelEU Maritime compliance deadline clustering. Fuel-cell durability data in salt-air environments and bunkering terminal commissioning schedules served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; mega-yacht and charter operator categories carry tighter precision than small-yacht and leisure applications. Forecasts reflect assumptions about IMO enforcement consistency and renewable hydrogen supply chain maturation. Practitioners should monitor Rotterdam and Singapore bunkering terminal utilization rates and Lloyd's Register certification timeline updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Seats Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Airboats Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Sea-Based Vehicle Carrier Market