
 Global Automotive Mats Market | 2026-2036
Global Automotive Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Mats Market Analysis
Aftermarket service revenue is rewriting how value accrues across the automotive mats supply chain, pulling margin pools away from basic OEM supply toward branded replacement and upgrade channels. WeatherTech leverages proprietary digital-fit technology to dominate the direct-to-consumer premium segment. Husky Liners anchors its position through deep channel control in North American auto parts retail. Suminoe Textile Co., Ltd. competes on manufacturing scale, supplying woven carpet solutions to Japanese and Southeast Asian OEM programs.
Automotive mats are floor-covering assemblies engineered from rubber compounds, thermoplastic polymers, or textile substrates, typically featuring anti-slip backing, retention clips, and perimeter containment ridges to trap debris and moisture. Manufacturing employs injection molding for thermoplastic variants and needle-punch or tufting processes for textile grades, with thickness tolerances and density specifications calibrated to vehicle platform requirements. Rubber and polypropylene material categories lead volume production due to cost efficiency and durability performance, while nylon formulations command premium positioning in luxury vehicle fitments. The aftermarket provider end-user segment captures the fastest margin expansion as vehicle age profiles lengthen replacement cycles.
FDA indirect food-contact guidelines, EPA volatile organic compound emissions rules, and REACH substance restrictions collectively constrain polymer formulation choices and adhesive selection for automotive mat producers serving multiple geographies. China's SAMR enforces GB standards for interior material flammability and VOC release, creating divergent testing burdens for suppliers operating across regulatory jurisdictions. Stakeholders must monitor how evolving electric vehicle platform architectures—with flat floor pans and relocated battery thermal management—reshape dimensional specifications and attachment hardware standards.
Market Dynamics
Fleet electrification is compressing replacement cycles and flattening floor architectures, forcing mat producers to redesign retention systems and thermal barrier integration for battery-protected cabin spaces.
Growth Catalysts
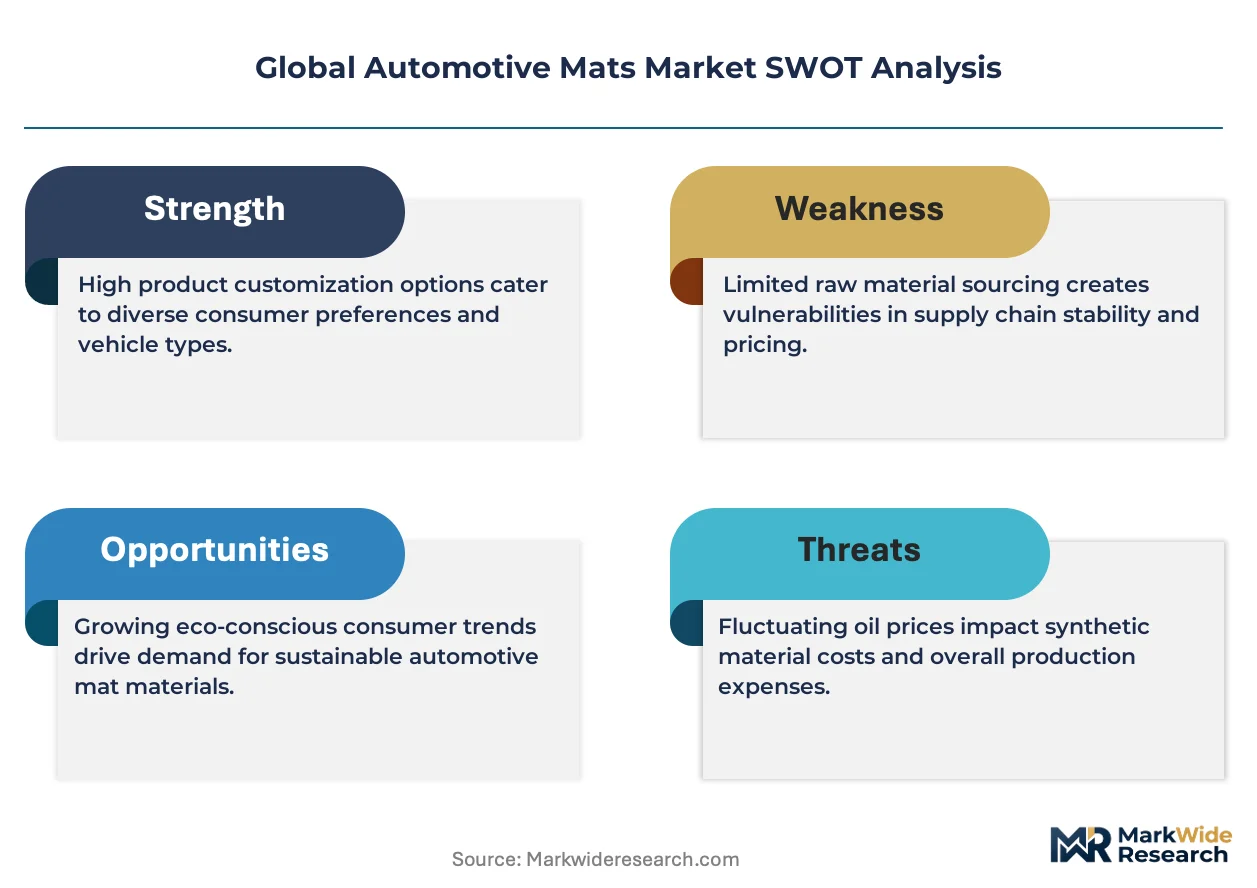
- REACH substance restrictions:European ECHA mandates on phthalate-free polymer formulations accelerate bio-based TPE adoption across premium OEM programs.
- Flat-floor EV architectures:Battery thermal management systems in electric vehicles demand repositioned attachment hardware and extended perimeter sealing.
- China's SAMR GB standards:Interior material flammability and VOC release thresholds tighten compliance requirements for rubber compound suppliers serving domestic OEMs.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and synthetic rubber input costs fluctuate with crude oil indices, compressing margin stability for volume manufacturers.
- Southeast Asian supply concentration:Needle-punch textile substrate production clusters in Vietnam and Indonesia create single-source vulnerability for woven carpet programs.
- Recyclability technical limits:Multi-layer bonded constructions with TPO backing and nylon face prevent closed-loop material recovery under current mechanical recycling processes.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives attract foreign mat producers to establish localized TPE compounding and molding capacity.
- Digital-fit configurators:Direct-to-consumer channels using vehicle VIN-based pattern matching bypass traditional auto parts retail markup structures.
- ISO 14001 environmental management:Certification-driven procurement preferences among German fleet operators create premium positioning for verified sustainable material sourcing.
Industry Challenges
- Tooling amortization timelines:Platform-specific injection molds for custom-fit mats require 18-24 month payback periods against uncertain EV model longevity.
- Cross-jurisdiction testing burdens:Divergent EPA VOC, REACH SVHC, and SAMR GB standards force parallel certification tracks for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Mats Market |
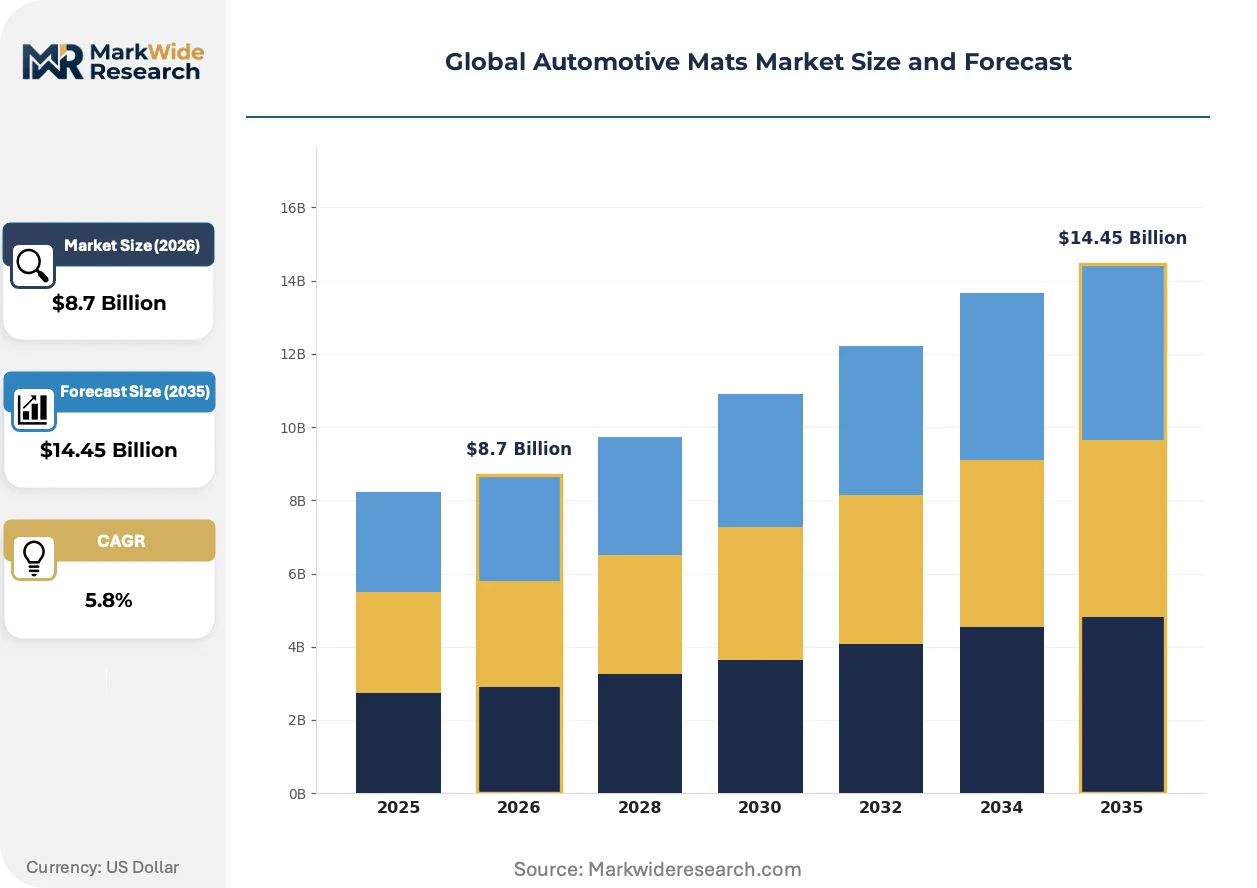
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Car Mats, Truck Mats, SUV Mats, Motorcycle Mats Material: Rubber, Nylon, Polypropylene, Vinyl End User: OEMs, Aftermarket Providers, Dealerships, Retail Consumers Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | WeatherTech, Husky Liners, 3M, Lloyd Mats, Auto Custom Carpet Inc., Toyota Boshoku Corporation, Suminoe Textile Co., Ltd., Lear Corporation, Walser GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Mats Market Emerging Trajectories
Material science convergence with digital manufacturing is collapsing traditional lead times while regulatory pressure on interior air quality redefines acceptable chemical thresholds across major automotive markets.
3D laser scanning paired with AI-generated pattern libraries is virtualizing the entire fitment development cycle. Tier 1 seating suppliers now commission mat programs without physical vehicle buck sessions. The technology compresses prototype iterations from twelve weeks to seventy-two hours, enabling faster platform matching for low-volume electric vehicle variants.
EPA volatile organic compound emissions rules now extend to cabin interior materials, capturing mat adhesives and backing foams under federal testing protocols. Manufacturers serving the US market reformulate solvent-based bonding agents to waterborne alternatives. The regulatory expansion most impacts all-weather rubber mat producers whose traditional neoprene compounds face compliance recertification.
Subscription-based vehicle protection packages are unbundling mat replacement from traditional ownership models. Fleet management platforms and mobility-as-a-service operators in Germany now specify wear-rated flooring with guaranteed replacement intervals. The shift transfers inventory risk from end-users to suppliers while locking in multi-year volume commitments through outcome-based service structures.
Global Automotive Mats Market Segmentation
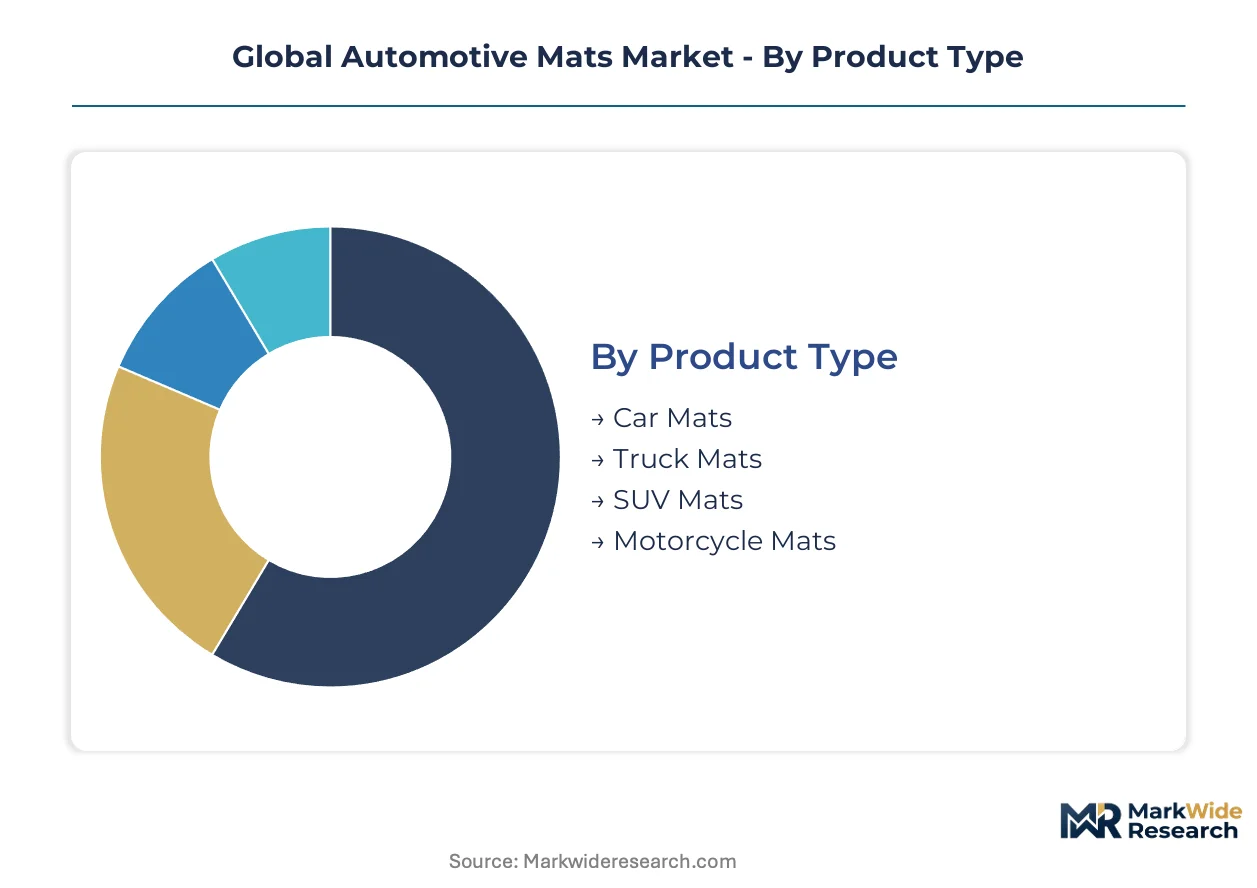
Automotive mat producers calibrate tooling investments and material formulations against distinct performance requirements across vehicle platforms, sales channels, and buyer types. Segmentation discipline separates volume-driven commodity supply from premium custom-fit programs that command superior margin structures.
Product Type:
Vehicle platform geometry dictates mat dimensions, retention hardware placement, and perimeter containment specifications across passenger and commercial applications.
- Car Mats:Precision-molded thermoplastic or tufted carpet assemblies sized for sedan, hatchback, and coupe footwell configurations. Demand clusters in Germany and Japan where OEMs specify integrated retention clip systems for premium cabin fitments.
- Truck Mats:Heavy-gauge rubber or TPO constructions with extended wear surfaces and debris containment ridges for commercial duty cycles. Fleet operators in the United States absorb the majority of volume, specifying molded floor liners with integrated thermal barriers for battery-protected cabin spaces.
- SUV Mats:Multi-piece configurations accommodating third-row seating and cargo area coverage. Family vehicle ownership patterns in suburban China drive replacement cycle frequency.
- Motorcycle Mats:Compact rubber or coir formulations for garage and workshop protection. Enthusiast retail channels in Italy and the United Kingdom capture specialized demand.
Car Mats hold installed capacity. Truck Mats is rotating up the share rankings.
Material:
Raw material selection trades off durability performance, regulatory compliance burden, and manufacturing process compatibility against target price positioning.
- Rubber:SBR and natural rubber compounds deliver all-weather durability and chemical resistance for commercial and severe-climate applications. EPA VOC emissions protocols now capture neoprene adhesive systems, forcing waterborne reformulation investments for US-market suppliers.
- Nylon:Solution-dyed 6,6 fiber constructions offer premium aesthetic grades and stain resistance for luxury OEM fitments. German automakers specify REACH-compliant phthalate-free backing systems for nylon carpet programs.
- Polypropylene:Injection-molded or needle-punch variants dominate volume production through cost efficiency and recyclability. China's SAMR GB standards restrict flammability ratings for polypropylene substrates in domestic OEM supply.
- Vinyl:Calendered PVC sheets with embossed textures serve economy aftermarket replacement. Regulatory pressure from ECHA SVHC listings accelerates displacement by TPE alternatives in European distribution.
Rubber commands the deepest supplier relationships. Nylon is climbing the fastest among premium positioning tiers.
End User:
Buyer type determines specification authority, volume predictability, and margin structure across the value chain.
- OEMs:Tier 1 seating and interior suppliers commission platform-specific mat programs with 3-5 year production commitments. Japanese and South Korean automakers integrate mat specifications into comprehensive cabin air quality certification protocols.
- Aftermarket Providers:Independent distributors and digital-fit specialists capture replacement and upgrade demand outside dealer networks. Digital vehicle identification pattern matching now enables direct-to-consumer fulfillment without physical inventory risk.
- Dealerships:Franchise networks bundle mat replacement into service retention programs and certified pre-owned reconditioning. German dealer groups specify wear-rated flooring with guaranteed replacement intervals under subscription structures.
- Retail Consumers:Individual purchasers through auto parts retailers or e-commerce platforms drive seasonal demand spikes. United States consumers show highest penetration of premium custom-fit digital configurators.
OEMs hold installed capacity. Aftermarket Providers is rotating up the share rankings.
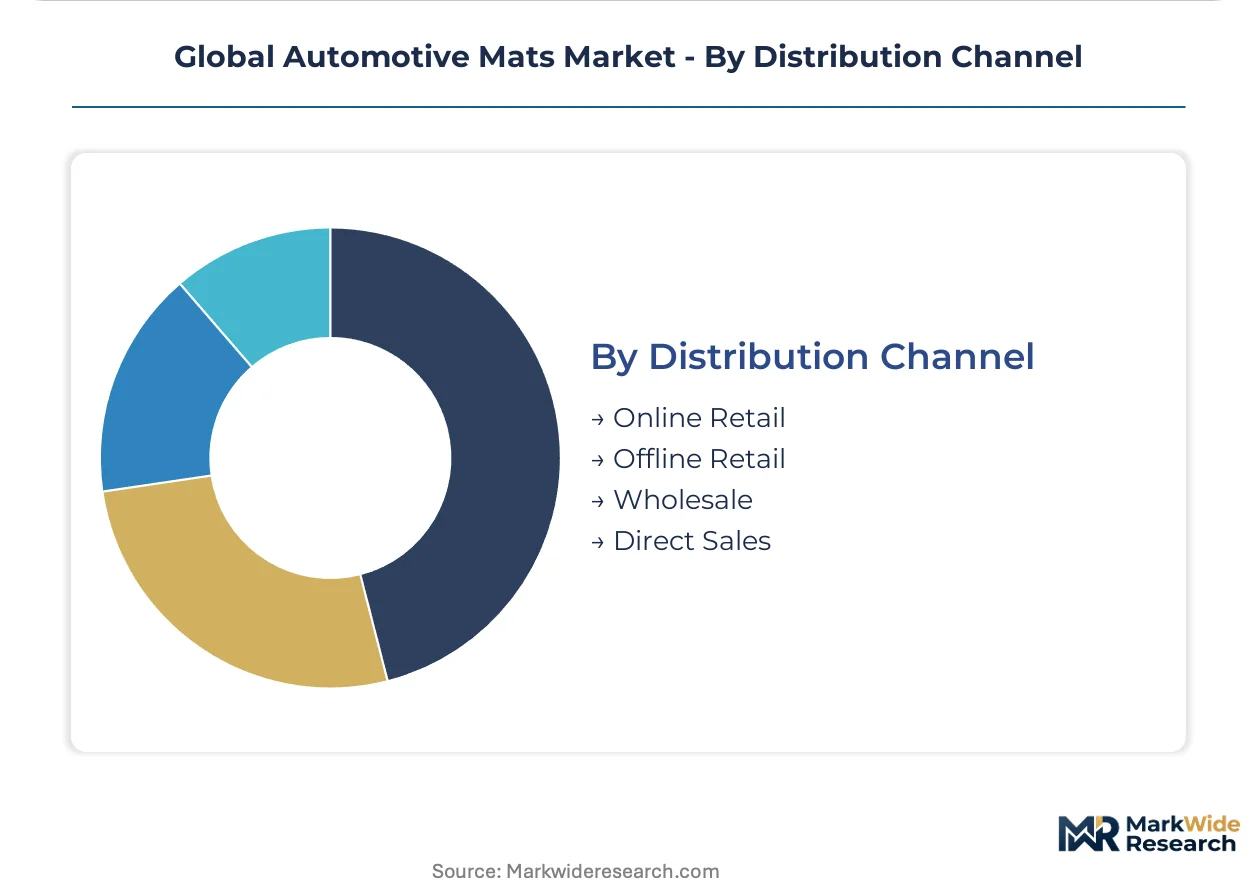
Distribution Channel:
Channel structure determines working capital intensity, customer acquisition economics, and brand control positioning.
- Online Retail:E-commerce platforms and proprietary digital-fit configurators bypass traditional wholesale markups. Vehicle VIN-based pattern libraries enable 72-hour fulfillment cycles for low-volume electric vehicle variants.
- Offline Retail:Auto parts chains and independent stores maintain immediate availability for emergency replacement. Physical inspection remains preferred for texture and color matching among older vehicle owners.
- Wholesale:Distributor networks aggregate fragmented demand for independent repair shops and smaller retailers. Inventory pooling across regional warehouses reduces stockout risk for slow-moving SKUs.
- Direct Sales:Manufacturer-owned channels capture full margin for premium branded programs. Fleet management platforms in Germany negotiate direct multi-year volume commitments with outcome-based service structures.
Offline Retail holds installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States show low price elasticity for premium custom-fit solutions, while procurement in India and Southeast Asia remains highly sensitive to unit cost differentials. This demand-elasticity contrast shapes where margin pools accumulate versus where volume scales.
United States
Fleet operators and direct-to-consumer channels absorb premium digital-fit mat solutions with extended replacement cycles. EPA volatile organic compound emissions rules now capture mat adhesives and backing foams under federal testing protocols. Detroit-area automotive suppliers coordinate with WeatherTech and Husky Liners on platform-specific retention hardware for electric vehicle flat-floor architectures.
Germany
OEM procurement specifications integrate REACH-compliant phthalate-free polymer formulations into premium cabin fitments. ECHA substance restrictions on SVHC listings accelerate displacement of vinyl alternatives by bio-based TPE compounds. Stuttgart and Wolfsburg industrial clusters host Tier 1 seating suppliers commissioning mat programs through 3D laser scanning and AI-generated pattern libraries.
China
Domestic OEMs specify GB-standard compliant rubber compounds with tightened interior material flammability and VOC release thresholds. SAMR enforcement creates divergent testing burdens for multi-market suppliers operating across regulatory jurisdictions. Yangtze River Delta manufacturing hubs concentrate needle-punch textile substrate production for woven carpet programs serving Japanese and Southeast Asian export markets.
Japan
Automakers integrate mat specifications into comprehensive cabin air quality certification protocols with 3-5 year production commitments. METI industrial standards guide material selection for luxury vehicle fitments. Toyota City and Nagoya metropolitan areas anchor Suminoe Textile Co., Ltd. manufacturing scale for OEM supply programs.
India
Domestic manufacturing incentives under the PLI scheme for auto components attract foreign mat producers to establish localized TPE compounding capacity. BIS certification requirements for automotive interior materials create compliance entry barriers for unverified imports. Chennai and Pune automotive clusters concentrate injection molding operations for cost-efficient polypropylene variants serving commercial vehicle platforms.
Global Automotive Mats Market Vendor Landscape
Capability concentration sits with digital-fit technology specialists; scale advantage sits with textile substrate manufacturers serving multi-OEM programs. The vendor base organizes into three strategic archetypes: proprietary pattern-technology providers, deep-channel aftermarket distributors, and integrated Tier 1 interior suppliers. Dominant competitive moves include geographic expansion through India's PLI manufacturing incentives and technology licensing partnerships for VIN-based digital configurators.
Among North American technology-focused providers, WeatherTech exemplifies the proprietary digital-fit archetype, while Husky Liners occupies a position within deep-channel aftermarket control. Suminoe Textile Co., Ltd. represents the scale-driven textile manufacturing tier supplying woven carpet solutions to regional OEM programs.
| Leading Market Players |
|---|
| WeatherTech |
| Husky Liners |
| 3M |
| Lloyd Mats |
| Auto Custom Carpet Inc. |
| Toyota Boshoku Corporation |
| Suminoe Textile Co., Ltd. |
| Lear Corporation |
| Walser GmbH |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility between crude-indexed polypropylene contracts and synthetic rubber spot markets compresses margin stability while simultaneously widening spreads between commodity-grade volume supply and REACH-certified premium tiers. This input-cost uncertainty forces manufacturers to dual-source compound formulations across Asian and European supply bases, reshaping inventory positioning and contract structures.
Pricing Analysis
Aftermarket service revenue tiers anchored by subscription-based vehicle protection packages now capture lifetime value that exceeds original equipment supply by multiples. Three-tier pricing structure across premium custom-fit, standard molded, and economy universal levels separates WeatherTech's digital-fit configurators from mass-market polypropylene alternatives. Cost compression in economy-grade vinyl segments is intensifying because ECHA SVHC listings accelerate displacement by bio-based TPE compounds. Fleet operators in Germany show lowest price sensitivity for wear-rated flooring with guaranteed replacement intervals, while retail consumers in India remain most responsive to unit cost differentials.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic planning for multi-market suppliers serving both EPA VOC and SAMR GB compliance jurisdictions. Raw material sourcing draws from Vietnamese needle-punch textile clusters, German TPE compounding facilities, and Chinese injection molding operations. Single-source vulnerability concentrates in Southeast Asian substrate production for woven carpet programs. Distribution runs through auto parts retail chains in North America, direct-to-consumer digital channels for premium fitments, and wholesale distributor networks aggregating fragmented repair shop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. REACH substance restrictions and divergent EPA-SAMR testing protocols lock in compliance investments that new entrants cannot replicate without 18-24 month certification timelines.
For Market Incumbents: Insulate platform-specific mold investments by extending digital-fit pattern libraries to low-volume electric vehicle variants before tooling amortization timelines expire. Deepen channel control in North American auto parts retail to defend against direct-to-consumer entrants leveraging VIN-based configurators. Prioritize backward integration into TPE compounding capacity under India's PLI scheme to capture localized cost advantages. For New Entrants and Emerging Players: India's underpenetrated premium aftermarket offers white-space opportunity where BIS certification requirements create compliance barriers for unverified imports. Target commercial fleet operators in Germany with outcome-based service structures that transfer inventory risk from end-users. Deploy AI-generated pattern matching to bypass traditional wholesale markup structures and establish direct fulfillment relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive digital-fit technology and multi-jurisdiction certification capabilities. Long-term viability rests on acquiring pattern-technology assets that compress prototype development from twelve weeks to seventy-two hours. Monitor EV platform longevity announcements as the inflection signal for tooling amortization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Digital-Fit Technology Licensing | VIN-based pattern libraries enable 72-hour fulfillment for low-volume EV variants without physical inventory. |
| Backward Integration into TPE Compounding | India's PLI manufacturing incentives attract localized production to serve domestic OEM and export programs. |
| REACH-Compliant Material Certification | ECHA phthalate-free mandates lock in premium positioning for bio-based polymer formulations across European supply. |
| Subscription-Based Fleet Contracts | German fleet management platforms specify wear-rated flooring with guaranteed replacement intervals under multi-year structures. |
| 3D Laser Scanning Pattern Development | AI-generated libraries virtualize fitment cycles and eliminate physical vehicle buck sessions for Tier 1 seating suppliers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs trade records, and OEM procurement disclosures across the analysis window. Interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations specialists informed demand-side assumptions. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators and regional automotive production forecasts.
Forecast inputs include vehicle class segmentation, propulsion architecture shifts, content-per-vehicle trajectories, OEM tier positioning, and regional production cluster dynamics across the projection horizon. CAGRs derive from modeled volume and value outputs calibrated to platform-specific mat program commitments and replacement cycle elasticity. Electric vehicle flat-floor architectures and battery thermal management repositioning serve as primary demand-side modifiers.
Practitioners should monitor petrochemical feedstock indices, EV platform longevity announcements, and regulatory harmonization efforts between EPA, ECHA, and SAMR jurisdictions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Resonator Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Fender Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Automotive Backing Plate Market