
 Automotive Active Suspension System Market | 2026-2036
Automotive Active Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Suspension System Market Analysis
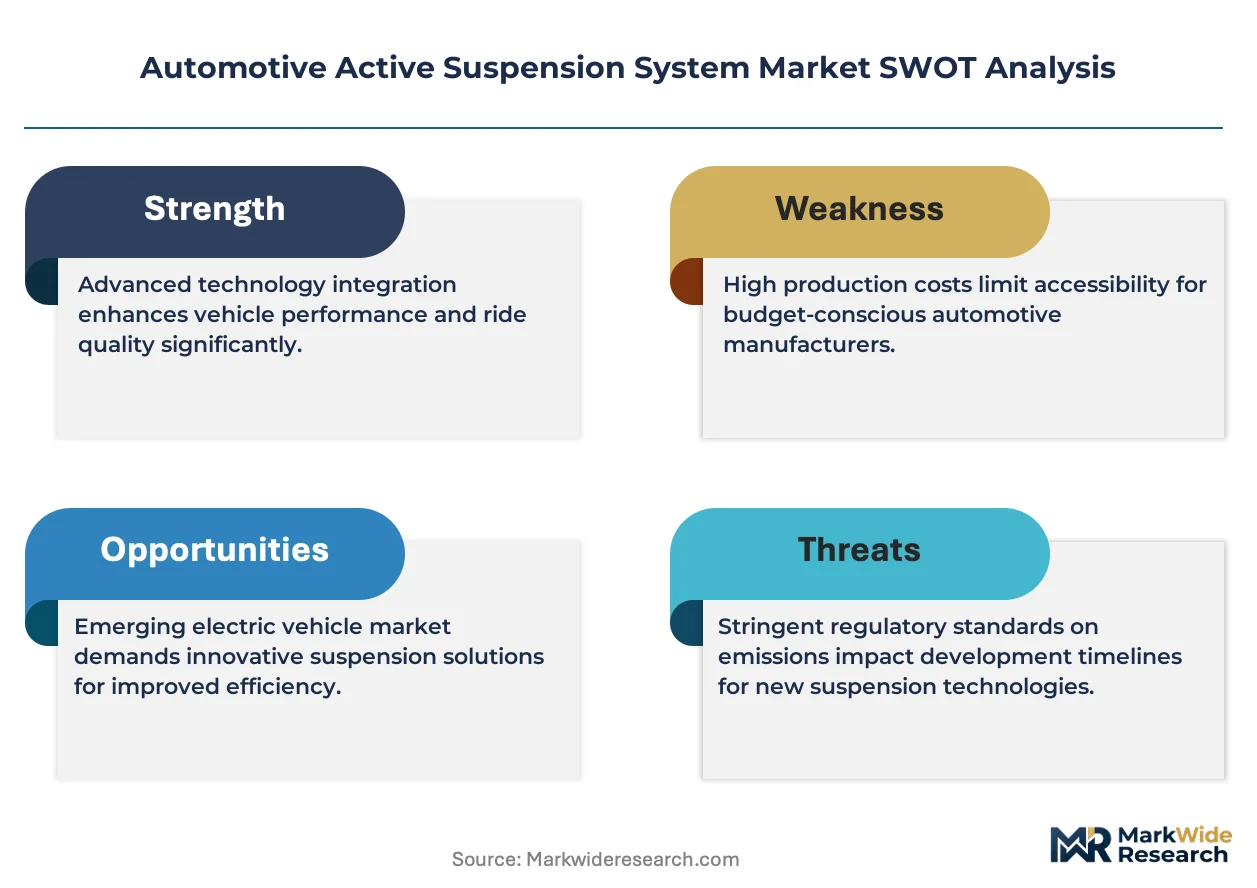
A widening capital-intensity gap between sensor-integrated platform developers and component assemblers is rotating competitive advantage toward full-stack suppliers. Continental AG leverages its in-house production of control electronics and actuator modules to sustain margin capture across the value chain. ZF Friedrichshafen AG anchors its position through manufacturing scale in electromechanical systems for premium OEM platforms. Bosch competes by extending its cross-domain expertise from braking and steering into integrated chassis control architectures.
Automotive active suspension systems are electromechanical or hydraulic assemblies that use real-time sensor feedback to modulate damping force, ride height, and wheel kinematics, typically operating at frequencies above 20 Hz to counteract road disturbances and vehicle dynamics. Their primary purpose is to optimize tire contact patch consistency, occupant comfort, and handling stability across varying load and surface conditions. Electromechanical architectures are capturing the fastest expansion as automakers seek weight reduction and energy recuperation over hydraulic alternatives. Adaptive damping technology dominates current revenue pools, while semi-active systems occupy the largest installation base due to their cost-positioning between passive and fully active configurations. Electric vehicles represent a concentrated demand node where suspension integration with battery pack protection and regenerative braking coordination creates premium pricing power.
The EPA enforces fuel economy standards that incentivize lightweight suspension designs, while NHTSA crashworthiness protocols shape actuator redundancy and fail-safe requirements for U.S. market access. Germany's KBA administers type-approval testing that validates active system interoperability with ESC and ADAS platforms under UN-ECE regulations. Stakeholders must monitor how software-defined vehicle architectures are consolidating chassis control domains and whether Tier-1 suppliers can defend their hardware-software integration role against OEM in-sourcing strategies.
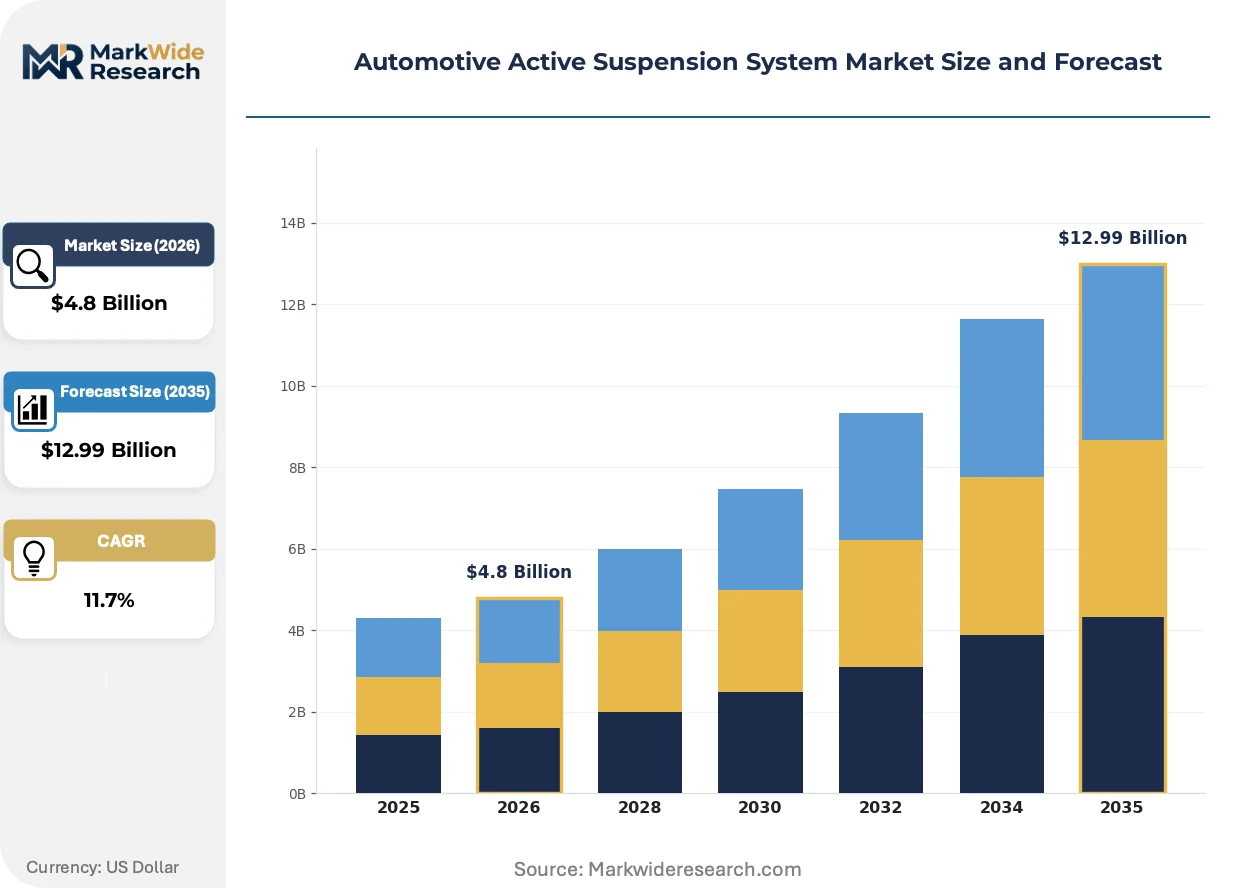
Market Dynamics
The automotive active suspension system market is being fundamentally restructured by the consolidation of chassis control domains into software-defined vehicle architectures. OEMs are pushing electromechanical actuators and sensor-integrated platforms to capture energy recuperation benefits while reducing unsprung mass, forcing suppliers to defend their hardware-software integration role against in-sourcing strategies.
Growth Catalysts
- EU Green Deal:The regulation mandates lighter vehicle architectures, accelerating OEM preference for electromechanical suspension over hydraulic alternatives to achieve emissions targets.
- Electric vehicle platforms:Battery pack protection requirements and regenerative braking coordination create concentrated demand for integrated active damping systems in premium EV architectures.
- ADAS interoperability:UN-ECE regulations under Germany's KBA type-approval framework validate active suspension integration with electronic stability control and automated driving platforms.
Market Restraints
- Rare earth magnet supply:Electromechanical actuators depend on neodymium and dysprosium, with processing concentrated in China, exposing Tier-1 suppliers to input cost volatility and supply security risks.
- Capital intensity gap:Full-stack development of control electronics, sensor fusion, and actuator modules requires sustained R&D investment that component assemblers cannot match, compressing mid-tier supplier margins.
- Hydraulic system legacy:Established service infrastructure and technician familiarity with hydraulic architectures create switching friction for aftermarket replacement demand in commercial vehicle segments.
Strategic Opportunities
- India passenger vehicle segment:Underpenetrated active suspension adoption among domestic OEMs creates white space for technology transfer partnerships as premium vehicle production scales.
- Sensor-actuator convergence:Integration of LiDAR and radar data streams with predictive damping algorithms enables pre-emptive road disturbance compensation, opening premium pricing tiers.
- US IRA clean vehicle credits:Domestic content requirements for battery electric vehicles incentivize localized electromechanical suspension production to qualify for consumer tax incentives.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for chassis control algorithms extends development timelines and requires specialized automotive safety engineer talent pools.
- Cross-domain integration complexity:Active suspension coordination with braking, steering, and powertrain systems demands systems engineering capabilities that span historically siloed supplier organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Suspension System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Magnetic Technology: Active Control, Adaptive Damping, Self-Leveling, Semi-Active End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Performance Cars Installation: OEM Installation, Aftermarket Upgrade, Retrofit Solutions, Custom Builds |
| Companies Covered | KYB Corporation, BWI Group, Continental AG, Magna International, ThyssenKrupp AG, ZF Friedrichshafen AG, Magneti Marelli S.p.A., Bosch, Tenneco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Suspension System Market Emerging Trajectories
Electromechanical architectures are actively displacing hydraulic systems across premium and mass-market vehicle segments. Three interconnected developments are compressing technology adoption cycles and reshaping supplier competitive positioning.
Predictive damping algorithms leveraging camera and navigation data streams are bifurcating the market between reactive and anticipatory suspension control. Luxury OEMs in Germany are deploying road-scanning systems that adjust damping force before wheel contact. This capability is compressing the performance gap between semi-active and fully active configurations.
EPA fuel economy standards are tightening enforcement of lightweight design incentives for chassis components. The regulation is forcing suspension suppliers to redesign actuator housings and optimize motor efficiency to maintain OEM platform qualification. Electromechanical architectures in the US market are responding with aluminum-intensive structures and regenerative damping modes.
Fleet operators and premium leasing channels are unbundling active suspension maintenance from traditional powertrain service contracts. Specialized diagnostic equipment requirements and proprietary calibration protocols are creating captive aftermarket revenue streams for integrated system suppliers. This pattern is most visible in Germany's corporate fleet segment where total cost of ownership calculations dominate procurement decisions.
Automotive Active Suspension System Market Segmentation
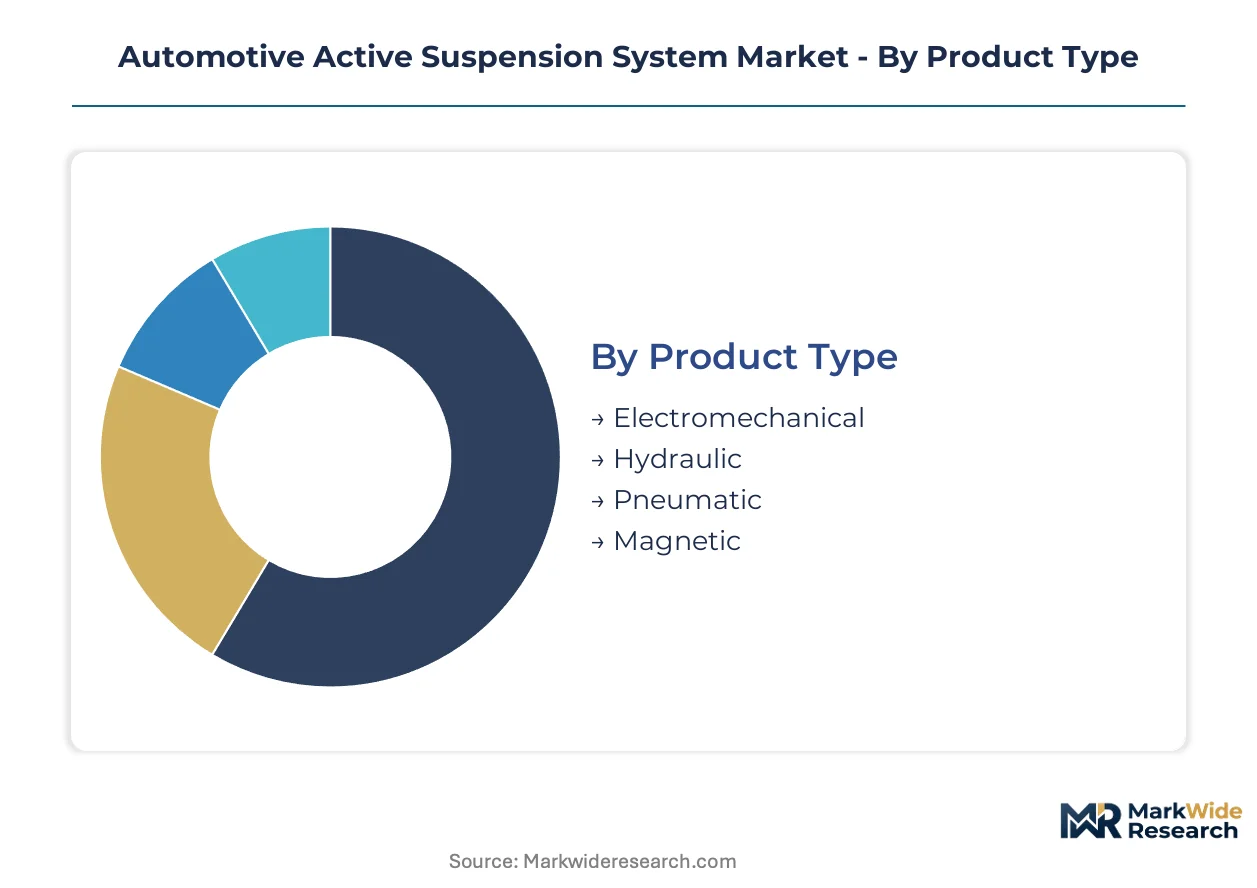
Active suspension architectures fragment across actuator physics, control intelligence, and vehicle integration depth. Margin capture concentrates where electromechanical platforms intersect with predictive software and premium OEM qualification protocols.
Product Type:
Margin pools sit heaviest with electromechanical architectures that combine motor-inverter integration with regenerative energy recovery, while hydraulic legacy systems defend aftermarket service revenue streams.
- Electromechanical:Brushless DC motors and ball-screw mechanisms deliver sub-10 millisecond response times with 40% weight reduction versus hydraulic equivalents. Battery electric vehicle platforms in Germany anchor demand as BMW and Mercedes-Benz mandate energy recuperation from damper motion. The EU Green Deal emissions targets force aluminum-intensive housing designs that compress supplier tooling amortization cycles.
- Hydraulic:Pressurized fluid circuits with servo-valve modulation dominate commercial vehicle duty cycles above 7.5 tonnes gross vehicle weight. Established service infrastructure across North American long-haul fleets creates switching friction for electromechanical alternatives. Technician certification pools and proprietary diagnostic equipment lock in incumbent supplier aftermarket revenue.
- Pneumatic:Air spring assemblies with height-leveling compressors serve luxury SUV segments requiring variable ride height for off-road clearance and aerodynamic highway modes.
- Magnetic:Magnetorheological fluid dampers with real-time viscosity modulation enable continuous force adjustment without mechanical valve actuation.
Electromechanical holds installed capacity. Magnetic is rotating up the share rankings.
Technology:
Control sophistication determines pricing tiers, with full-state feedback architectures commanding 3-4x semi-active hardware premiums while adaptive damping dominates current production volumes.
- Adaptive Damping:Continuously variable valve systems adjust damping force across 16-32 discrete settings based on accelerometer and wheel speed sensor inputs. Luxury passenger vehicles in Germany's corporate fleet segment standardize this configuration for lease residual value optimization. KBA type-approval protocols validate interoperability with ESC platforms under UN-ECE regulations.
- Semi-Active:Switchable damper modes (comfort/sport/track) operate without external power input beyond sensor and valve energization. Mass-market OEMs in the United States deploy this architecture to meet NHTSA rollover resistance targets while containing bill-of-material costs. The technology bridges passive suspension replacement cycles and full active system adoption curves.
- Active Control:Fully powered actuators with skyhook and groundhook algorithms eliminate compromise between ride and handling through independent wheel force generation.
- Self-Leveling:Height sensors with compressor-fed air springs maintain constant chassis attitude under variable payload and trailer tongue weight conditions.
Adaptive Damping commands current revenue. Active Control is climbing the fastest.
End User:
Vehicle electrification status reshapes suspension integration requirements, with battery pack protection and regenerative braking coordination creating concentrated demand nodes in premium electric architectures.
- Electric Vehicles:Battery enclosure mounting stiffness and thermal management integration demand active damping coordination with vehicle dynamics controllers. Tesla and Lucid Motors platforms in the United States specify electromechanical systems with predictive road scanning to protect high-voltage components from shock loading. EPA lightweighting incentives accelerate aluminum actuator housing adoption.
- Passenger Vehicles:Mid-size sedans and crossovers deploy semi-active configurations as optional equipment packages. German premium OEMs bundle adaptive damping with ADAS Level 2+ platforms to differentiate lease offerings. UN-ECE regulation harmonization enables single specification across EU, UK, and EFTA markets.
- Performance Cars:Track-focused applications prioritize lateral load transfer control and brake dive mitigation through active anti-roll and heave compensation.
- Commercial Vehicles:Cab suspension and seat damping systems address driver fatigue regulations while tractor-trailer combinations require fifth-wheel height management.
Passenger Vehicles holds installed capacity. Electric Vehicles is gaining share fastest.
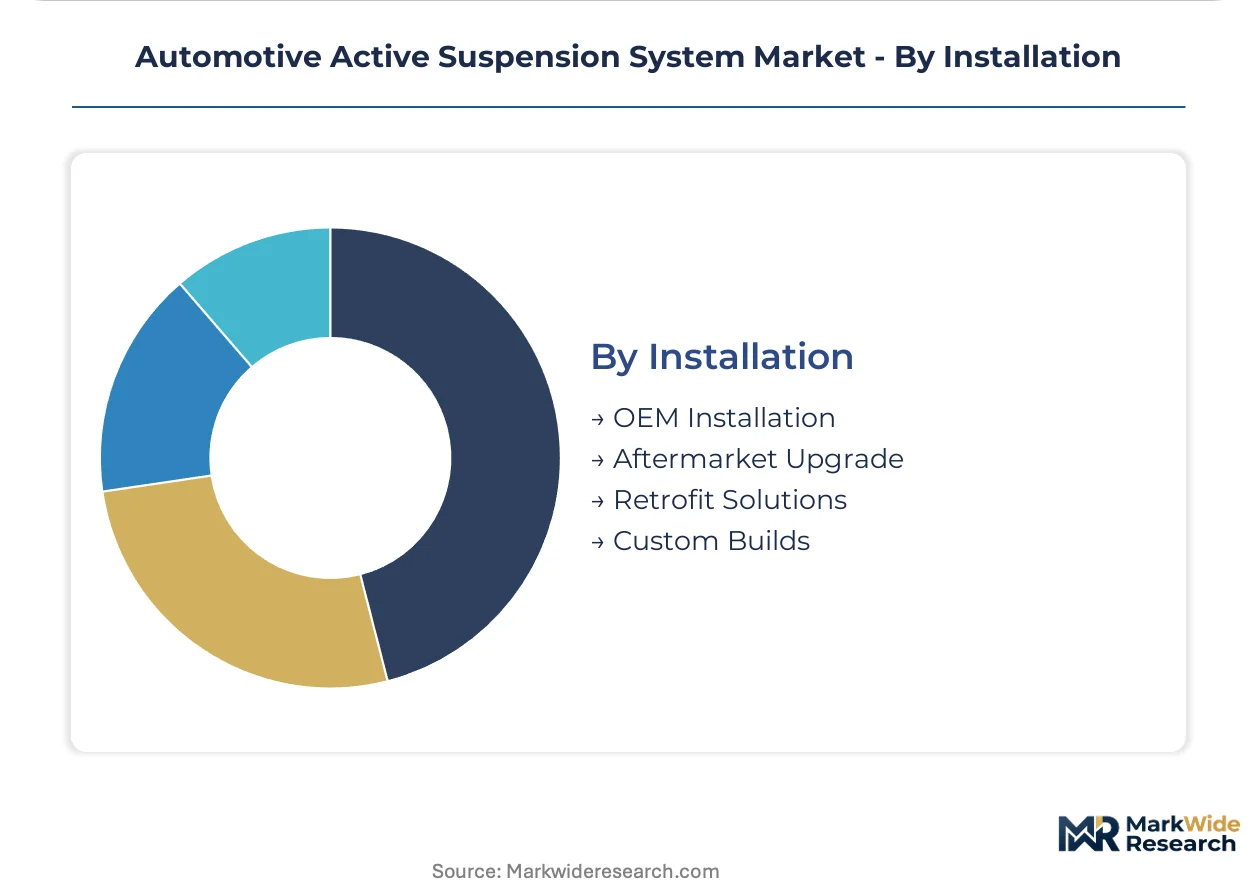
Installation:
Channel economics diverge sharply between OEM line-fit qualification cycles and aftermarket diagnostic complexity, with retrofit solutions capturing niche demand from classic vehicle electrification projects.
- OEM Installation:Line-fit qualification requires 24-36 month validation cycles including ISO 26262 functional safety certification and electromagnetic compatibility testing. Continental AG and ZF Friedrichshafen AG compete for platform awards through integrated chassis domain controller architectures. Germany's KBA administers type-approval for ESC interoperability.
- Aftermarket Upgrade:Plug-and-play semi-active damper kits target enthusiast segments with CAN bus integration for drive mode selection. United States specialty equipment manufacturers leverage SEMA certification to access EPA compliance pathways. Proprietary calibration tools create recurring software subscription revenue.
- Retrofit Solutions:Classic vehicle restomod applications combine modern active suspension with vintage chassis architectures.
- Custom Builds:Low-volume coachbuilders and motorsport constructors specify bespoke actuator geometries for unique packaging constraints.
OEM Installation holds installed capacity. Aftermarket Upgrade is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in active suspension systems reflect a structural deficit in electromechanical actuator manufacturing outside Germany, China, and the United States. Component trade flows concentrate where premium OEM platforms anchor supplier ecosystems, with finished system exports trailing subassembly shipments by value.
United States
NHTSA crashworthiness protocols and EPA fuel economy standards shape electromechanical system qualification for Detroit Three platforms. The IRA clean vehicle credits incentivize domestic content in battery electric vehicle supply chains. Michigan and Ohio anchor supplier engineering centers serving Tesla, Lucid Motors, and legacy OEM electrification programs.
Germany
KBA type-approval under UN-ECE regulations validates active suspension interoperability with ESC and ADAS platforms for BMW, Mercedes-Benz, and Audi architectures. The EU Green Deal emissions targets accelerate aluminum-intensive electromechanical designs over hydraulic alternatives. Stuttgart and Munich concentrate Continental AG and ZF Friedrichshafen AG development campuses.
China
MIIT new energy vehicle mandates and GB standards for intelligent chassis systems drive domestic electromechanical actuator capacity expansion. NMPA automotive safety regulations align with UN-ECE frameworks for export-bound platforms. Shanghai and Beijing-Tianjin-Hebei clusters host joint ventures supplying NIO, Li Auto, and BYD premium EV architectures.
Japan
METI carbon neutrality roadmaps and JIS standards for automotive electronics govern active damper development for Toyota, Honda, and Nissan electrification platforms. KYB Corporation anchors domestic production of hydraulic and electromechanical systems. Kanto and Kansai industrial corridors concentrate precision actuator manufacturing for export to ASEAN markets.
India
BIS automotive component standards and PLI scheme incentives for advanced automotive technology attract electromechanical suspension localization proposals from German and Japanese Tier-1 suppliers. Domestic OEM premium vehicle programs at Tata Motors and Mahindra & Mahindra create technology transfer opportunities. Tamil Nadu and Maharashtra anchor emerging supplier engineering presence.
Automotive Active Suspension System Market Vendor Landscape
Concentration sits with diversified chassis system integrators that combine electromechanical actuator manufacturing with embedded control software development. The vendor base stratifies between full-stack platform developers and component assemblers dependent on external electronics sourcing. Two strategic archetypes dominate: integrated chassis domain suppliers capturing OEM line-fit awards, and specialized damper manufacturers defending aftermarket service revenue. Competitive moves center on cross-domain integration partnerships and captive production of rare earth magnet motors to secure input cost stability.
Within the integrated chassis domain tier, Continental AG and ZF Friedrichshafen AG exemplify full-stack positioning through in-house control electronics and actuator module production. Bosch occupies a position spanning braking, steering, and suspension integration. KYB Corporation represents the specialized damper manufacturing archetype with established hydraulic system aftermarket infrastructure. These three anchors illustrate the structural divide between electromechanical platform developers and legacy hydraulic defenders.
| Leading Market Players |
|---|
| KYB Corporation |
| BWI Group |
| Continental AG |
| Magna International |
| ThyssenKrupp AG |
| ZF Friedrichshafen AG |
| Magneti Marelli S.p.A. |
| Bosch |
| Tenneco Inc. |
| Others |
Supply Flow & Price Mechanics
KBA type-approval under UN-ECE regulations gates both supplier qualification and price differentiation in active suspension markets, forcing Tier-1 developers to absorb ISO 26262 certification costs that component assemblers cannot shoulder. This regulatory threshold compresses mid-tier margins while concentrating pricing power with full-stack integrators who control electromechanical actuator and embedded software production.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with full-state feedback architectures commanding premiums against semi-active configurations. Price differentiation rests on ISO 26262 certification tier and volume scale commitments, though cost compression in mid-market segments is intensifying because rare earth magnet input volatility feeds through to actuator module costs. Fleet procurement teams exhibit highest price sensitivity, while luxury OEM platform engineers prioritize performance integration over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate electromechanical actuator procurement, though strategic stockpiling of neodymium and dysprosium concentrates among German and Chinese suppliers hedges against processing bottlenecks. Manufacturing draws from Germany, China, and Japan, with rare earth magnet dependencies and semiconductor content creating single-source vulnerability in motor-inverter subassemblies. Distribution runs through captive OEM line-fit channels rather than open aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active suspension incumbents face substitution pressure from predictive road-scanning systems that compress the performance gap between semi-active and fully active configurations. Defense requires securing control over electromechanical actuator production and embedded software development before OEM in-sourcing strategies erode Tier-1 integration roles.
For Market Incumbents: Secure captive supply of rare earth magnet motors through backward integration into neodymium processing partnerships, insulating margin capture against Chinese supply concentration. Deepen chassis domain controller architectures that bundle active suspension with braking and steering coordination, raising switching costs for OEM platform engineers evaluating in-house development.
For New Entrants and Emerging Players: ISO 26262 certification fast-tracks access to German premium OEM supplier lists, opening white space in India passenger vehicle programs where domestic OEMs lack electromechanical system partnerships. Target technology transfer arrangements with Tata Motors and Mahindra & Mahindra as their premium vehicle production scales, leveraging SEMA certification pathways for aftermarket upgrade kits as a beachhead revenue stream.
For Investors and Strategic Acquirers: EPA fuel economy standard tightening reshapes the acquisition landscape toward electromechanical platform developers with aluminum-intensive housing capabilities and regenerative damping IP. Long-term viability favors full-stack suppliers with in-house control electronics production over hydraulic legacy defenders. The signal to watch is OEM announcements of vertical integration into chassis domain software, which would compress independent Tier-1 valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Platform Standardization | BMW and Mercedes-Benz consolidate actuator specifications across EV architectures, reducing supplier qualification overhead. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors secure input cost stability for Continental AG and ZF production. |
| Software-Defined Vehicle Investment | Chassis domain controller development defends Tier-1 integration role against Tesla and Lucid in-sourcing strategies. |
| Geographic Manufacturing Footprint | Localized electromechanical suspension production in Michigan and Ohio qualifies suppliers for IRA clean vehicle credits. |
| ADAS Interoperability Partnership | Integration with Bosch braking systems and ZF steering platforms creates bundled chassis control offerings for OEMs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of UN-ECE regulatory filings, vehicle production databases, and Tier-1 supplier SEC disclosures. Primary interviews with OEM platform engineers, Tier-1 procurement directors, aftermarket distributors, and dealership service operations combined with bottom-up and top-down triangulation. Secondary validation drew from KBA type-approval records, EPA fuel economy certification data, and IHS Markit registration statistics.
Segmentation dimensions modeled span actuator physics, control intelligence tier, vehicle electrification status, and installation channel across the projection horizon. CAGRs derived from regression analysis against vehicle production forecasts and content-per-vehicle assumptions, with electromechanical adoption curves and rare earth magnet price indices as automotive-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable rare earth supply chains; material deviation would warrant model refresh. Revision becomes warranted when OEM in-sourcing announcements or trade policy shifts cross thresholds that restructure supplier competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Silencer Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Actuators Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Automotive Buffers Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Global Automotive Plastic Compounding Market