
 Automotive Engineering Services Market | 2026-2036
Automotive Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engineering Services Market Intelligence
Specialist engineering service provider capacity in Germany is expanding to meet OEM demand for outsourced vehicle platform development. Bertrandt AG leverages its deep relationships with German automakers to secure long-term contracts. L&T Technology Services differentiates through its scale in embedded software and connectivity services from its India delivery centers. AVL List GmbH specializes in powertrain development and testing, a critical niche for internal combustion and electric vehicle programs.
Automotive engineering services encompass the outsourced design, development, and testing functions traditionally performed by vehicle manufacturers. These services utilize computer-aided design (CAD) and computer-aided engineering (CAE) software for simulation and analysis of vehicle components and systems. Within service types, simulation & analysis and validation & testing are high-value segments, driven by the complexity of electric powertrain and autonomous driving technologies. OEMs remain the primary end-user, but demand from Tier-1 suppliers for subsystem engineering is growing rapidly.
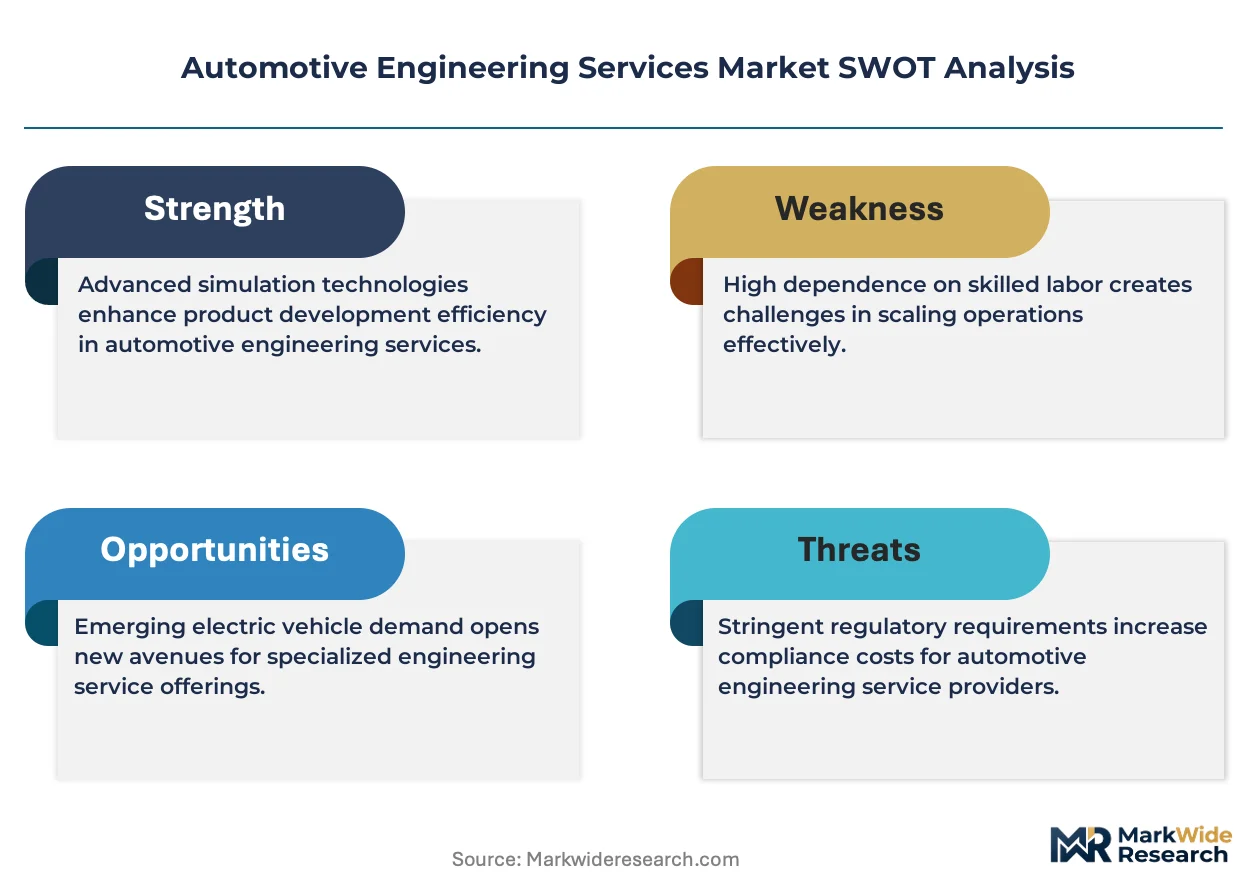
Regulations from bodies like the US EPA on emissions and the EU's GDPR on data privacy directly shape engineering service requirements. Adherence to China's GB standards for vehicle safety and performance is mandatory for market access, influencing testing protocols. Service providers must now decide whether to specialize in niche domains like battery management systems or build broad-based platform integration capabilities.
Market Dynamics
The dual pressures of vehicle electrification and the transition to software-defined architectures represent the central structural force shaping the automotive engineering services market. This shift compels original equipment manufacturers to outsource complex, non-core engineering functions to specialized providers to manage costs and accelerate development timelines.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU Green Deal and China's dual carbon goals require extensive re-engineering of powertrains and vehicle systems for emissions compliance, directly fueling demand for specialized validation and testing services.
- ADAS Proliferation:The integration of Advanced Driver-Assistance Systems (ADAS) and autonomous driving features necessitates complex sensor fusion, software validation, and simulation services, creating a high-value demand stream from OEMs and Tier-1 suppliers.
- Electric Powertrain Shift:OEMs are outsourcing significant portions of electric powertrain development, including battery management systems, electric motor design, and thermal management, to external engineering specialists to speed market entry.
Market Restraints
- High Software Licensing Costs:The substantial cost associated with licensing essential CAD and CAE software from a concentrated pool of vendors creates a significant financial barrier for smaller engineering service providers.
- Data Security and IP Concerns:OEMs are hesitant to share sensitive intellectual property and vehicle data with third-party providers, which can limit the scope of outsourced projects, particularly in core platform architecture and software development.
- Divergent Regional Standards:Conflicting safety and data regulations, such as US EPA rules versus EU-specific mandates, force service providers to invest in region-specific testing protocols, increasing operational complexity and cost.
Strategic Opportunities
- Battery Lifecycle Services:The expansion of the electric vehicle market opens opportunities for engineering services focused on battery second-life applications, recycling processes, and lifecycle management analytics.
- Digitalization of Testing:Developing virtual and simulation-based testing environments that can secure certification from bodies like Germany's KBA or the US NHTSA offers a path to displace costly physical validation.
- Cybersecurity as a Service:The rise of connected and autonomous vehicles creates a critical need for specialized engineering services dedicated to vehicle cybersecurity, from initial design to post-production vulnerability management.
Industry Challenges
- Talent Scarcity:A persistent shortage of engineers with dual expertise in traditional automotive mechanical systems and modern software development disciplines, such as embedded systems and AI, constrains service provider capacity.
- Legacy System Integration:Integrating new software-defined vehicle architectures and EV platforms with OEMs' existing legacy IT and manufacturing systems presents a major technical and operational hurdle for service providers.
- Capital-Intensive Infrastructure:Significant capital investment is required to build and maintain state-of-the-art testing facilities for EV batteries, high-voltage systems, and advanced autonomous driving sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engineering Services Market |
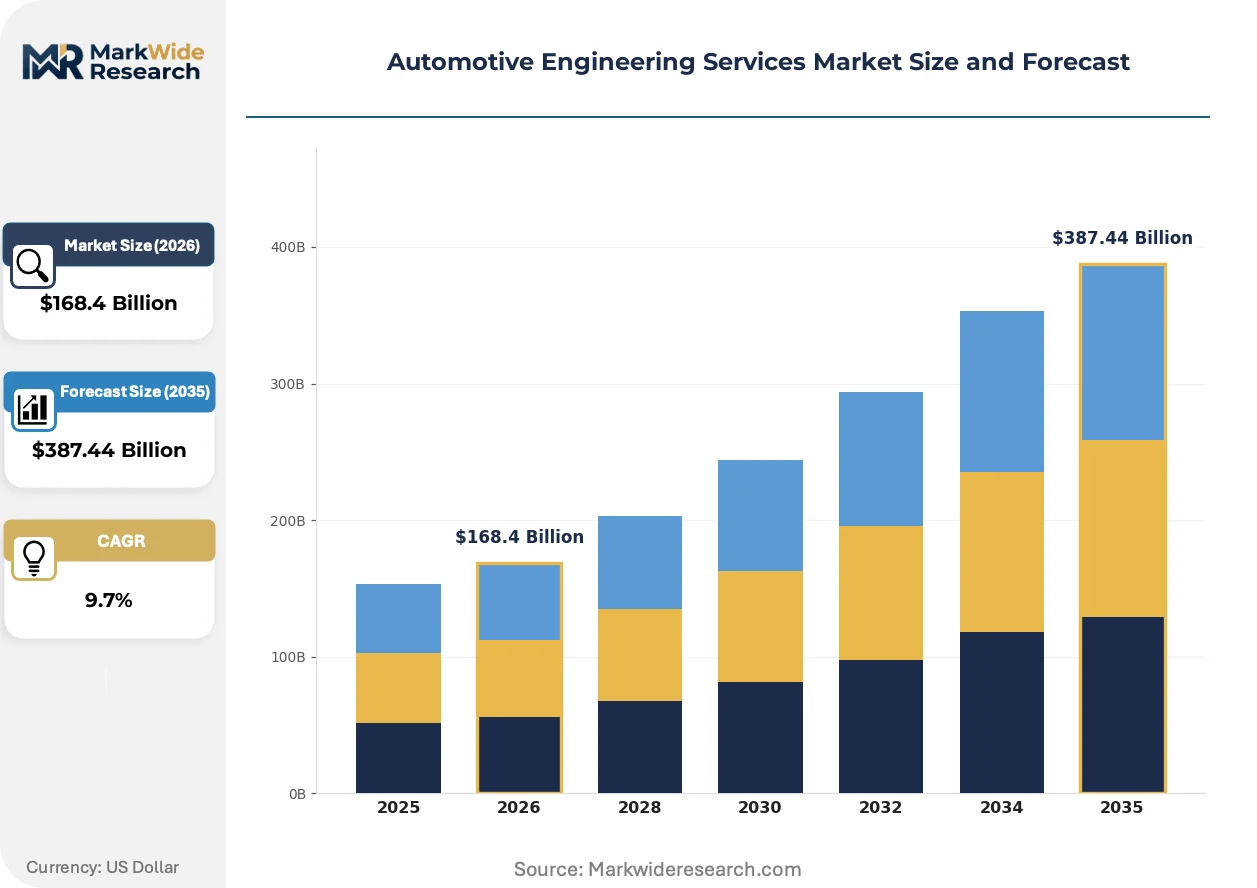
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $387.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design & Prototyping, Simulation & Analysis, Validation & Testing, Engineering Consulting, Manufacturing Support Technology: Embedded Systems, Autonomous Driving, Electric Powertrain, Connectivity, Vehicle Dynamics, Infotainment Application: Passenger Vehicles, Commercial Transport, Specialty Vehicles, Heavy Machinery, Two-Wheelers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Parts Manufacturers |
| Companies Covered | Capgemini Engineering, Bertrandt AG, IAV GmbH, AVL List GmbH, EDAG Engineering GmbH, FEV Group, L&T Technology Services, HCL Technologies, Tech Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engineering Services Market Strategic Shifts & Innovations
Digitalization is fundamentally altering the vehicle development lifecycle, shifting the emphasis from physical prototyping to virtual simulation and validation. This transformation pressures service providers to invest in high-performance computing and advanced software capabilities to meet OEM demands for accelerated, cost-effective engineering programs.
The application of digital twin technology, which creates a virtual replica of a vehicle or its subsystems, is a defining innovation. OEMs and Tier-1 suppliers are adopting this for continuous, end-to-end simulation, from initial design to in-service performance monitoring. This approach is electrifying the development process by enabling constant virtual testing and software updates, significantly reducing reliance on expensive and time-consuming physical prototypes.
Regulatory frameworks focused on data are shaping service requirements for connected vehicles. The EU's GDPR, for example, imposes strict rules on how personal data generated by vehicle systems is collected, stored, and processed. This directly impacts the engineering of telematics, infotainment, and autonomous systems. Service providers must now build data privacy and compliance expertise directly into their software development and validation processes.
A notable shift in engagement models is occurring as OEMs move from traditional time-and-materials contracts to outcome-based and fixed-scope work packages. This model displaces open-ended engagements, placing greater risk and project management responsibility on the engineering service provider to deliver a defined subsystem or platform module. This trend is most visible in Germany, where automakers are outsourcing entire functional domains to strategic engineering partners.
Automotive Engineering Services Market Segmentation
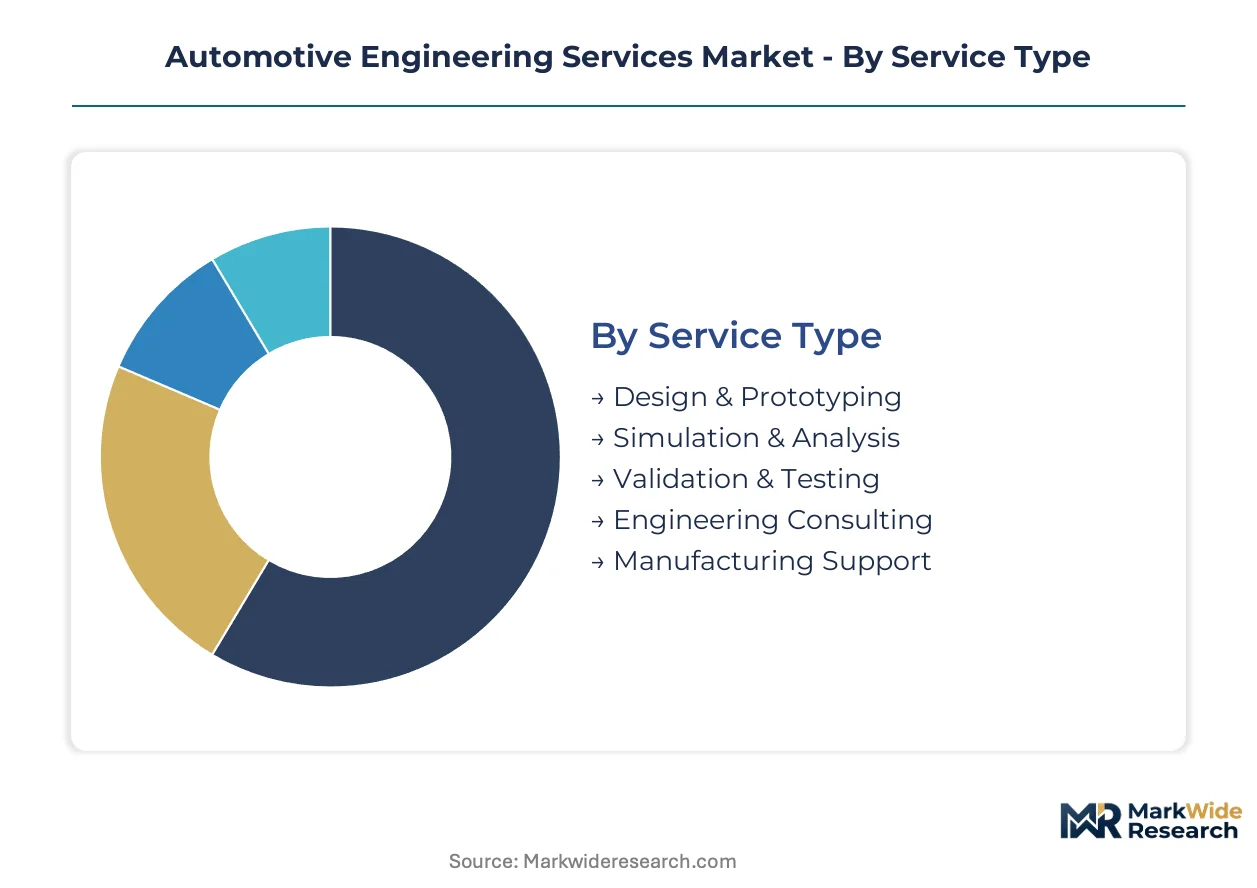
The automotive engineering services market segments reflect the diverse technical requirements and strategic outsourcing decisions across the vehicle development lifecycle. Understanding these distinctions is crucial for service providers to align specialized capabilities with OEM and Tier-1 supplier needs.
Service Type:
The integration depth of engineering services varies, from standalone project-based work to deeply embedded long-term partnerships supporting core vehicle development programs.
- Simulation & Analysis:This segment utilizes advanced computer-aided engineering (CAE) tools for virtual testing of vehicle performance, crashworthiness, and aerodynamics. Demand concentrates in Germany and India, driven by the need to accelerate electric powertrain and autonomous driving system development.
- Validation & Testing:Services here encompass rigorous physical and virtual verification to ensure components and systems meet performance, safety, and regulatory standards. The EU Green Deal and US EPA emissions rules compel significant validation efforts, particularly for new EV architectures.
- Design & Prototyping:This involves conceptualization, detailed design, and initial physical model creation for vehicle components and systems.
- Engineering Consulting:Expert advisory services guide OEMs and suppliers on technology roadmaps, process optimization, and regulatory compliance, particularly with GB standards in China.
- Manufacturing Support:Services assist in optimizing production processes, tooling design, and quality control for vehicle assembly lines.
Volume placements concentrate in Validation & Testing; the faster expansion belongs to Simulation & Analysis.
Technology:
The technological focus of engineering services directly impacts vehicle architecture and functionality, ranging from foundational electronic systems to cutting-edge autonomous capabilities.
- Electric Powertrain:Engineering services for electric powertrains include battery management systems, e-motor design, and thermal management solutions. OEMs outsource these functions to accelerate market entry and manage the complexity of new EV platforms.
- Autonomous Driving:This segment involves complex sensor integration, algorithm development, and software validation for advanced driver-assistance systems (ADAS) and self-driving functions. Demand is high from major automakers in the US and Europe seeking to deploy Level 2+ autonomy.
- Embedded Systems:These services focus on developing and integrating software and hardware for vehicle control units and electronic systems.
- Connectivity:Engineering services in connectivity enable in-vehicle communication, telematics, and over-the-air (OTA) updates for modern vehicles.
- Infotainment:This segment develops user interfaces, navigation systems, and entertainment features for the vehicle cabin.
- Vehicle Dynamics:Services optimize handling, ride comfort, and stability through chassis design and suspension tuning.
Autonomous Driving technology services are expanding most quickly, while Electric Powertrain services also show significant growth.
Application:
The application segment distinguishes engineering service requirements based on vehicle type, reflecting varying design priorities, regulatory frameworks, and use cases.
- Passenger Vehicles:This segment covers engineering services for cars, SUVs, and other light-duty vehicles, driven by consumer demand for advanced features and electrification. OEMs like Volkswagen and Toyota heavily utilize these services for new model development.
- Commercial Transport:Services here focus on trucks, buses, and vans, emphasizing efficiency, durability, and telematics for fleet management. Regulatory mandates for emissions reduction, such as those from the US EPA, drive engineering demand in this area.
- Specialty Vehicles:This includes engineering for emergency vehicles, recreational vehicles, and bespoke automotive projects, often requiring customized solutions.
- Heavy Machinery:Services for construction equipment, agricultural machinery, and mining vehicles prioritize ruggedness and operational efficiency.
- Two-Wheelers:Engineering support for motorcycles and scooters addresses design, performance, and safety standards specific to this vehicle category.
Passenger Vehicles maintain the largest share of engineering service demand, with Commercial Transport experiencing rapid expansion.
End User:
The end-user segment highlights the primary purchasers of automotive engineering services, indicating different strategic motivations and project scopes.
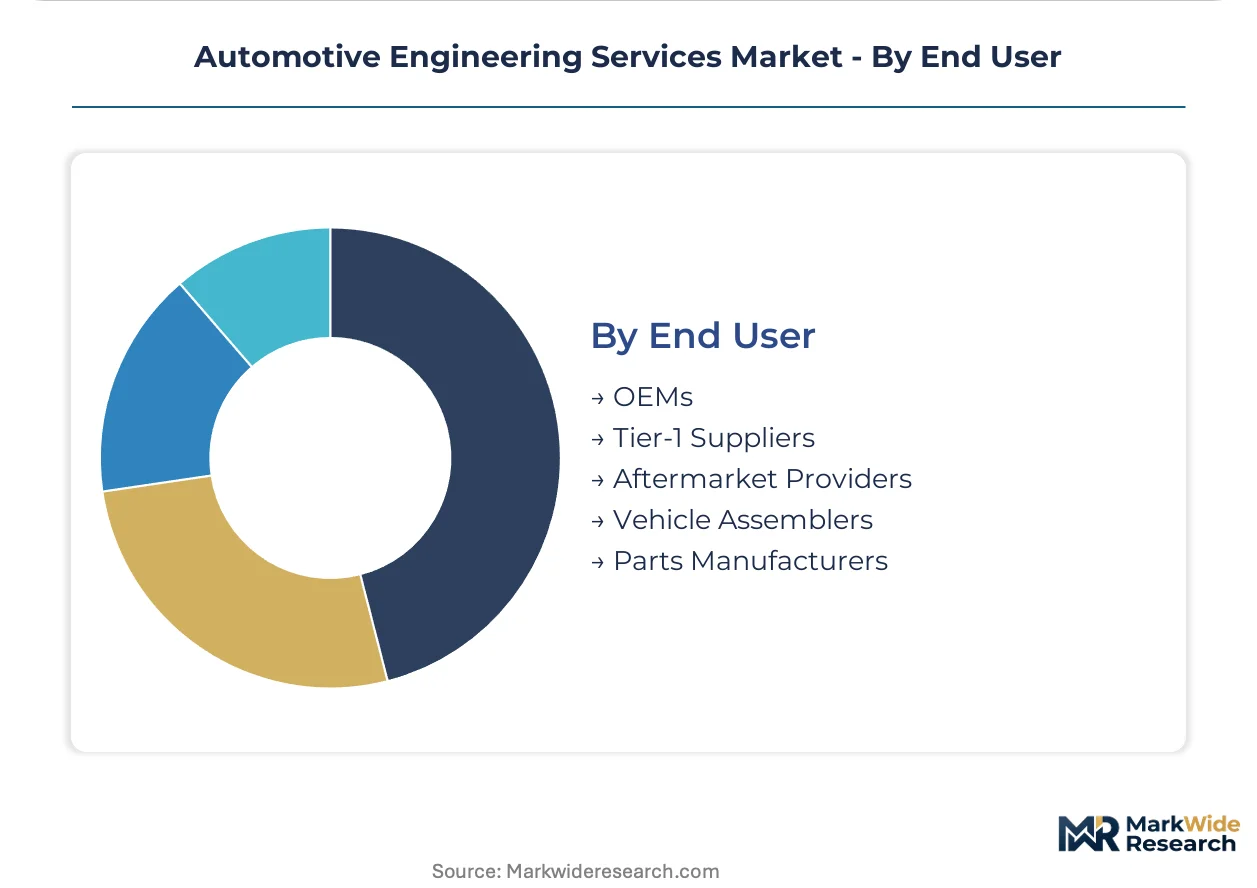
- OEMs:Original Equipment Manufacturers are the largest end-users, outsourcing complex engineering functions to manage costs and accelerate product development cycles. German automakers frequently engage specialist providers for platform development.
- Tier-1 Suppliers:These suppliers demand engineering services for subsystem development, software integration, and component validation to meet OEM specifications. L&T Technology Services supports many Tier-1 suppliers from its India delivery centers.
- Aftermarket Providers:This segment utilizes engineering services for parts design, performance upgrades, and accessory development for vehicles already in service.
- Vehicle Assemblers:Engineering support for vehicle assemblers focuses on optimizing manufacturing processes and quality control at the production stage.
- Parts Manufacturers:These companies engage engineering services for component design, material selection, and production process refinement.
OEMs represent the largest end-user group, while demand from Tier-1 Suppliers is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany anchors the global automotive engineering services market, driven by its established OEM base and specialized technical expertise. This concentration supports complex vehicle platform development and advanced powertrain solutions. Diverse regulatory landscapes across key regions further shape service requirements and delivery models.
Germany
OEM demand for outsourced vehicle platform development and advanced electric powertrain engineering propels the German market. The EU Green Deal mandates extensive re-engineering for emissions compliance, directly fueling validation and testing services. Automotive clusters in Stuttgart and Munich are expanding specialist engineering capacity, focusing on software-defined architectures.
United States
The US market experiences significant demand for ADAS proliferation and electric powertrain development from major automakers. US EPA emissions standards and NHTSA safety requirements necessitate rigorous validation and testing protocols. Silicon Valley and Detroit are becoming hubs for autonomous driving software and EV battery management system engineering.
China
China's automotive engineering services market is driven by rapid EV adoption and the need for compliance with local GB standards. The nation's dual carbon goals compel extensive re-engineering for efficiency and emissions reduction. Automotive development zones in Shanghai and Shenzhen are attracting investment in battery lifecycle services and digital testing solutions.
India
India serves as a crucial hub for embedded software development and connectivity services, supporting global OEMs and Tier-1 suppliers. The country's PLI scheme encourages local manufacturing, indirectly boosting demand for design and validation services. Technology centers in Bengaluru and Pune specialize in cost-effective simulation and analysis for complex vehicle systems.
Japan
Japan's engineering services market focuses on advanced materials research and autonomous driving system integration for its established automotive industry. METI initiatives promote innovation in next-generation vehicle technologies and sustainable mobility solutions. Nagoya and Tokyo remain vital centers for vehicle dynamics and infotainment system development.
Automotive Engineering Services Market Key Industry Players
Global majors compete with regional champions across specialized technical capabilities and market access within the automotive engineering services market. The market structure exhibits a tiered consolidation, with large-scale providers offering broad portfolios and niche players focusing on specific technologies. Strategic archetypes include full-service engineering partners, embedded software specialists, and dedicated powertrain experts. Competitive moves center on strategic partnerships for technology integration and capacity expansion in high-demand areas like electrification.
Specialists in powertrain development and embedded software solutions include Germany-based AVL List GmbH, which exemplifies expertise in critical internal combustion and electric vehicle programs, particularly in validation and testing. Bertrandt AG, also headquartered in Germany, represents full-service engineering partners with deep relationships across the European automotive sector. India-based L&T Technology Services exemplifies a global delivery model, leveraging its scale in embedded software and connectivity services for OEMs and Tier-1 suppliers worldwide.
| Leading Market Players |
|---|
| Capgemini Engineering |
| Bertrandt AG |
| IAV GmbH |
| AVL List GmbH |
| EDAG Engineering GmbH |
| FEV Group |
| L&T Technology Services |
| HCL Technologies |
| Tech Mahindra |
| Others |
Cost & Logistics Intelligence
Outsourced engineering services, a prevalent integration pattern for vehicle manufacturers, anchor both supply position and pricing power within the automotive sector. This model enables OEMs to manage development costs and accelerate market entry for complex vehicle platforms.
Pricing Analysis
Service-level agreements, often bundling long-term contracts with defined deliverables, govern pricing within the automotive engineering services market. Outcome-based and fixed-scope work packages are increasingly common, displacing traditional time-and-materials contracts. Price differentiation stems from specialized expertise in areas like ADAS validation or electric powertrain design, alongside geographic delivery capabilities from Germany or India. Pricing softness reflects the competitive landscape for standardized services, while high software licensing costs exert upward pressure on provider overheads. Tier-1 suppliers exhibit higher price sensitivity compared to OEMs seeking full platform integration.
Supply Chain Analysis
Direct engagement channels connect specialized engineering service providers with OEMs and Tier-1 suppliers globally. Geographic supply concentration centers on Germany for advanced vehicle platform development and India for embedded software and connectivity services. The industry draws from critical inputs such as high-performance computing infrastructure and advanced CAD/CAE software licenses. Talent scarcity, particularly for engineers with dual expertise in mechanical systems and modern software, represents a structural supply chain risk. Distribution runs through dedicated project teams collaborating closely with client R&D departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive engineering services market is evolving into a consolidation play. Talent scarcity and capital-intensive infrastructure requirements are forcing smaller, less specialized providers out of core development areas.
For Market Incumbents: Deploy strategic partnerships for technology integration to defend market position against niche specialists. Invest in advanced virtual testing environments to reduce reliance on costly physical prototyping and mitigate high software licensing costs. Expand capacity in high-demand areas like electric powertrain and software-defined vehicle architectures, particularly in established automotive clusters. Focus on securing long-term, outcome-based contracts with major OEMs.
For New Entrants and Emerging Players: Technology consultancies focused on niche software domains represent a viable entry point into the automotive engineering services market. Target specialized areas like vehicle cybersecurity or battery lifecycle services, which require less capital-intensive infrastructure than physical testing. Develop capabilities for compliance with specific regional regulatory frameworks, such as China's GB standards, to penetrate local markets. A go-to-market angle emphasizing rapid, agile software validation for Tier-1 suppliers offers market access.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized engineering firms with deep expertise in electric powertrain and autonomous driving systems. The long-term viability of this market remains strong, driven by the persistent OEM need for outsourced development in electrification and digitalization. Target companies with proven capabilities in embedded software, ADAS validation, or digital twin technology. The signal to watch is the increasing allocation of OEM R&D budgets towards external engineering partners.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | OEMs prioritize internal software capabilities for future vehicle platforms. |
| Platform Standardization | Engineering firms develop modular architectures to reduce OEM development costs. |
| Battery Supply Agreement | Securing critical EV components supports long-term electric powertrain projects. |
| Acquisition of Specialist Firm | Large providers integrate niche expertise in ADAS or cybersecurity. |
| Digitalization of Testing | Virtual validation environments accelerate compliance with US NHTSA standards. |
Research Approach
Multi-period observation of vehicle production data and R&D spending anchored the trend analysis, supplemented by interviews with OEM platform engineers and engineering service CTOs. This primary research engaged regulatory compliance officers and Tier-1 procurement leads across key automotive regions. Secondary validation drew from SEC 10-K filings, IHS Markit registration data, EU Green Deal impact assessments, and US EPA regulations, triangulated using both bottom-up and top-down approaches.
An input-output matrix framework modeled market dynamics across the forecast period, dissecting growth drivers and restraints. Segmentation dimensions included service type, technology, application, end-user, and regional regulatory frameworks for automotive engineering. Compound Annual Growth Rates were derived from historical performance and projected technology shifts, integrating forecast inputs such as EV adoption rates and autonomous driving penetration levels.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions or rapid shifts in consumer preference for vehicle types. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Vehicle Subscription Market
Automotive Services
France Car Rental Market
Automotive Services
Global Car Wash Market
Automotive Services
Driver's License Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
GCC Car Rental Market
Automotive Services
Automotive Digital Services Market