
 Global Car Wash Market | 2026-2036
Global Car Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Wash Market Analysis
Fleet operator demand is pivoting toward automated express tunnel formats over full-service bays. Mister Car Wash leverages its national scale to dominate high-throughput suburban corridors. Driven Brands sustains a multi-format portfolio spanning express tunnels and flex-service sites. Zips Car Wash anchors growth through aggressive franchise expansion in mid-market metros.
A car wash system comprises automated conveyor tunnels, in-bay automatic units, self-service bays, and mobile pressure-wash rigs engineered to remove road film, brake dust, and environmental contaminants using controlled water pressure, chemical detergents, and soft-cloth or touchless media. Automatic service formats lead volume throughput while water recycling technology captures the fastest-growing investment pool as drought-prone jurisdictions mandate reclaim thresholds. Fleet end-user contracts concentrate margin pools through guaranteed utilization and negotiated chemical supply terms.
The EPA enforces Clean Water Act discharge limits on commercial wash runoff, while California's State Water Resources Control Board imposes stricter reclaim mandates than federal baselines. The EU Green Deal's water-efficiency directives shape equipment standards for suppliers serving European operators. Stakeholders must monitor regulatory divergence between jurisdictions when selecting equipment platforms and site formats.
Market Dynamics
Water recycling mandates from the EPA and California's State Water Resources Control Board are compressing capital deployment timelines for new site development while favoring operators with proven reclaim technology.
Growth Catalysts
- Fleet contract standardization:Commercial vehicle operators now require guaranteed wash utilization through multi-year service agreements, locking in volume commitments that stabilize operator cash flows.
- California SB 606 reclaim thresholds:The state's water efficiency mandates accelerate equipment replacement cycles as legacy sites face permit non-compliance.
- Touchless sensor arrays:Lidar-guided chemical dosing systems reduce per-vehicle water consumption while maintaining finish quality, attracting drought-conscious municipal fleet managers.
Market Restraints
- Stainless steel supply concentration:Conveyor tunnel fabricators depend on specialized alloy suppliers concentrated in Germany and South Korea, exposing equipment procurement to input volatility.
- Permit timeline friction:EPA Clean Water Act discharge permits require 18-24 month approval cycles in jurisdictions with backlogged environmental review boards.
- Mobile pressure-wash substitution:On-demand fleet cleaning services bypass fixed infrastructure entirely, capturing intermittent demand from small commercial operators.
Strategic Opportunities
- India urban corridor penetration:Metro Delhi and Bangalore exhibit car ownership density without express tunnel saturation, creating first-mover positioning for reclaim-equipped formats.
- EU Green Deal water-efficiency directives:Equipment suppliers certifying to the bloc's reclaim standards gain preferential access to municipal procurement frameworks.
- Subscription membership convergence:RFID-enabled unlimited wash plans integrate with fleet telematics platforms, converting transactional revenue to recurring contracted streams.
Industry Challenges
- Reclaim system integration complexity:Retrofitting existing bay configurations with closed-loop water processing requires extended site downtime and specialized plumbing contractors.
- Chemical handler certification delays:OSHA Hazard Communication Standard compliance training creates bottlenecks in technician onboarding across multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Wash Market |
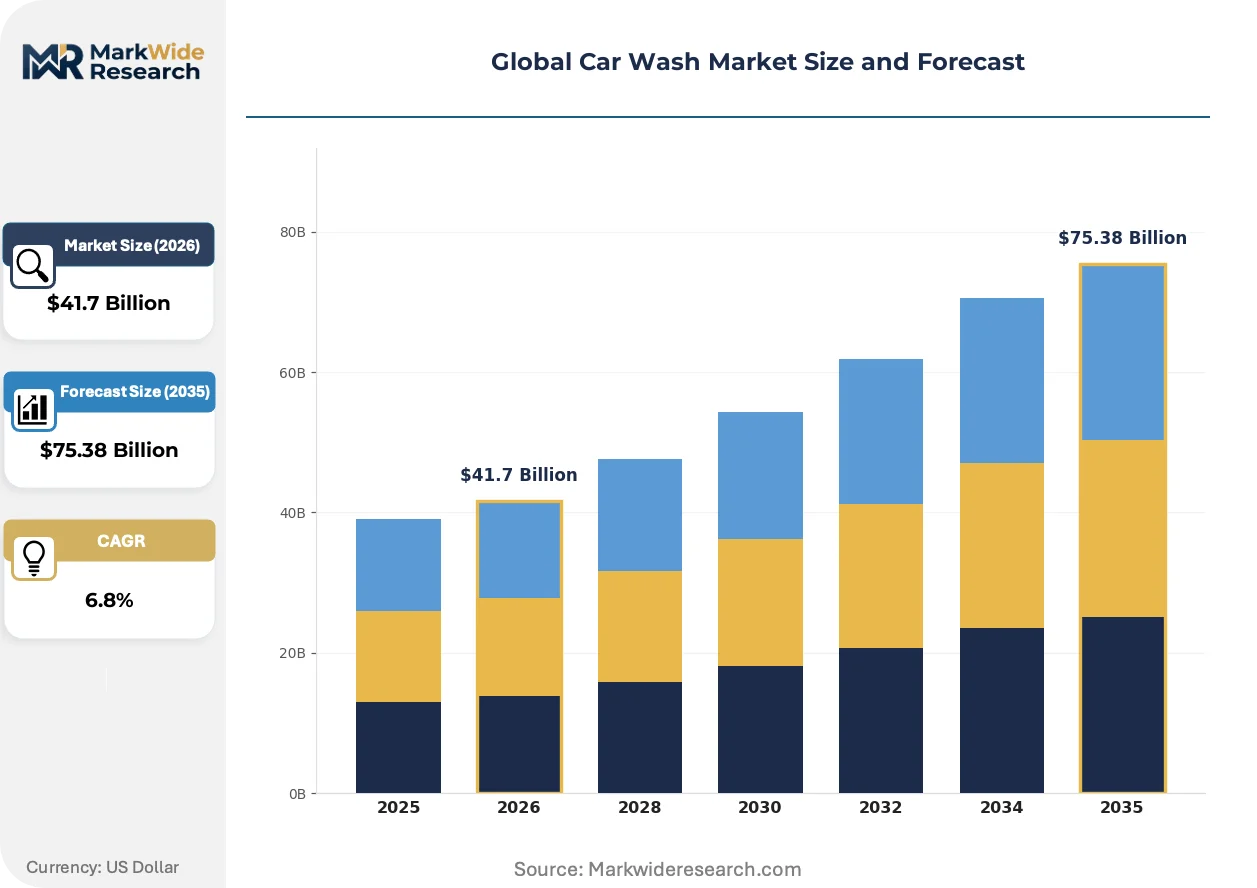
| Market Size in 2026 | $41.7 Billion |
| Market Size in 2035 | $75.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Service, Automatic, Full-Service, Mobile Wash Type: Soft Cloth, Touchless, Hand Wash, Rollover End User: Individual Customers, Fleet Operators, Dealerships, Rental Services Technology: Water Recycling, Eco-Friendly Products, Ozone Treatment, Robotic Systems |
| Companies Covered | Mister Car Wash, Driven Brands, Zips Car Wash, Quick Quack Car Wash, Autobell Car Wash, Splash Car Wash, Tommy's Express Car Wash, Wash Depot Holdings Inc., International Car Wash Group (ICWG), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Wash Market Emerging Trajectories
Automation is compressing labor dependency while regulatory water accounting forces hardware architecture redesigns across both tunnel and in-bay formats.
Closed-loop water reclamation is consolidating equipment vendor differentiation as drought-prone municipalities mandate 80%+ reclaim thresholds for new permits. Fleet operators with ESG reporting obligations now specify reclaim-equipped sites exclusively, forcing smaller operators into capital-intensive retrofits or exit. The technology is consolidating market share around vendors with integrated chemical-neutralization and membrane-filtration stacks.
REACH chemical restriction updates are expanding the list of prohibited surfactants in European wash formulations, compelling detergent suppliers to reformulate around bio-based alternatives. The industrial consequence is a 12-18 month product recertification cycle that favors larger chemical houses with dedicated regulatory affairs teams. Tunnel operators in Germany and France face the steepest compliance costs as national regulators enforce stricter interpretation than EU baselines.
Fleet procurement teams now unbundle wash services from bundled maintenance contracts, creating direct supplier relationships that bypass traditional fleet management intermediaries. Large logistics operators issue RFPs with chemical disclosure requirements and carbon-accounting attachments that smaller regional wash chains cannot fulfill. This pattern concentrates contract awards among operators with documented water reclaim rates and third-party sustainability audits, visible most acutely in California's Central Valley trucking corridors.
Global Car Wash Market Segmentation
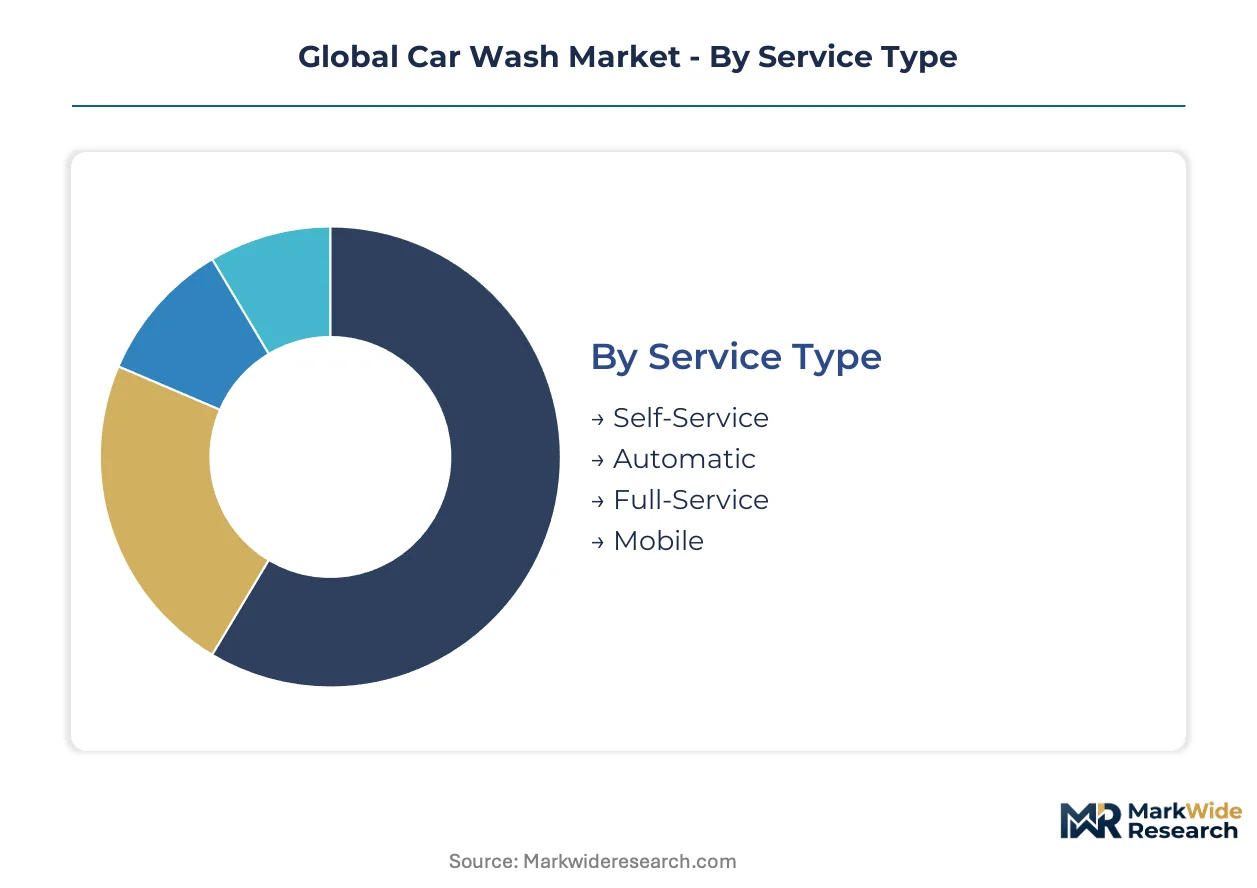
Car wash market segmentation reveals how regulatory pressure and fleet procurement standards fragment demand across service formats and technology tiers. Understanding these divisions exposes where capital deployment concentrates and which segments carry compliance burdens that reshape competitive positioning.
Service Type:
Automatic formats require EPA Clean Water Act discharge permits for commercial runoff, while self-service bays face lighter municipal oversight. Mobile operations bypass fixed-site permitting entirely but encounter OSHA Hazard Communication Standard compliance for chemical transport.
- Self-Service:Coin-operated wand systems with user-controlled pressure and chemical selection. Demand concentrates in rural United States corridors where labor costs exceed automated alternatives and water scarcity is less acute.
- Automatic:Conveyor tunnel or in-bay rollover systems with programmed wash cycles. Fleet operators in California's Central Valley specify these exclusively for ESG reporting compliance, locking in volume through multi-year contracts.
- Full-Service:Interior detailing and exterior washing performed by attendants. Labor intensity limits expansion in jurisdictions with rising minimum wage mandates.
- Mobile:Pressure-wash rigs deployed to fleet depots or residential locations. Small commercial operators in India urban corridors favor this for intermittent demand without infrastructure investment.
Automatic sits at the top of the volume ranking, with Mobile climbing the fastest.
Wash Type:
Cost tier differentiation separates premium touchless sensor arrays from standard soft-cloth configurations, with hand wash commanding labor-intensive pricing premiums.
- Soft Cloth:Friction-based cleaning with rotating fabric strips contacting vehicle surfaces. Suburban United States express tunnels deploy this for throughput speed, though finish quality risks rise with contaminated cloth.
- Touchless:High-pressure water and chemical application without mechanical contact. Lidar-guided dosing systems reduce per-vehicle consumption, attracting drought-conscious municipal fleet managers in Germany and France.
- Hand Wash:Manual cleaning with mitts and controlled pressure wands. Luxury vehicle owners in metro Delhi and Bangalore specify this for paint protection, sustaining premium pricing.
- Rollover:Stationary vehicle with moving wash gantry. Compact footprint suits retrofit installations in constrained European urban sites.
Soft Cloth retains the dominant share position, though Touchless gains share fastest on regulatory water accounting.
End User:
Customer type determines contract structure, with fleet procurement teams now unbundling wash services from bundled maintenance agreements to enforce direct supplier accountability.
- Individual Customers:Retail consumers purchasing single washes or subscription memberships. RFID-enabled unlimited plans in the United States convert transactional demand to recurring revenue streams.
- Fleet Operators:Commercial vehicle managers with guaranteed utilization requirements. These contracts specify reclaim-equipped sites exclusively, concentrating awards among operators with third-party sustainability audits.
- Dealerships:New and used vehicle preparation services. Volume fluctuates with automotive sales cycles, creating demand volatility.
- Rental Services:Turnaround cleaning for daily rental fleets. Standardized vehicle configurations allow automated processing, favoring express tunnel formats.
Fleet Operators anchor contract value, with Rental Services expanding most quickly on fleet standardization.
Technology:
Maturity divides established water recycling systems from emerging robotic architectures, with eco-friendly formulations facing REACH-driven recertification cycles in European markets.
- Water Recycling:Closed-loop reclaim systems with membrane filtration and chemical neutralization. California SB 606 mandates accelerate replacement cycles as legacy sites face permit non-compliance.
- Eco-Friendly Products:Bio-based surfactants replacing prohibited formulations. Detergent suppliers in Germany and France absorb steepest compliance costs as national regulators enforce stricter interpretation than EU Green Deal baselines.
- Ozone Treatment:Oxidation-based sanitization for interior spaces. Adoption concentrates in fleet contracts with hygiene specifications.
- Robotic Systems:Automated interior cleaning with articulated arms. Integration complexity extends site downtime during retrofit deployment.
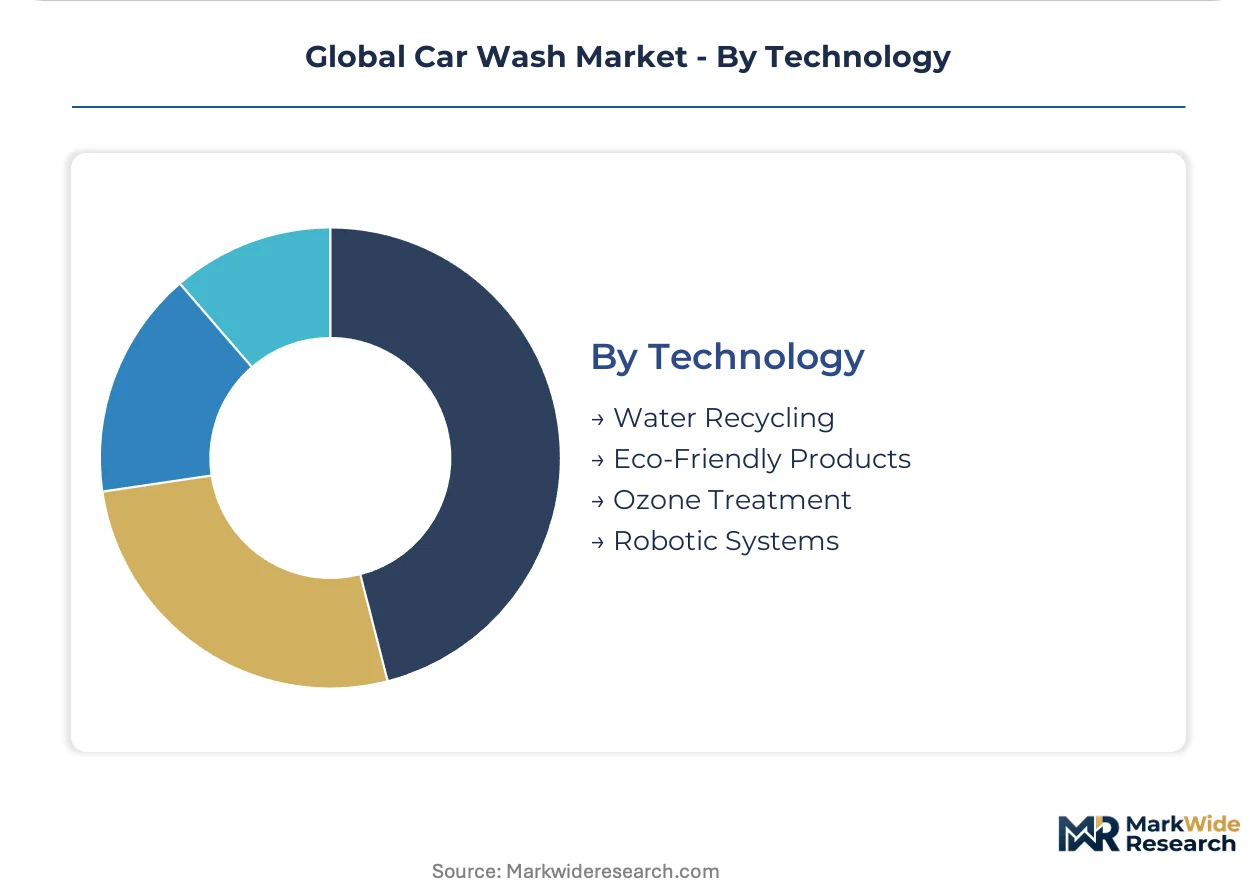
Water Recycling dominates capital allocation, with Robotic Systems tracing the steepest expansion trajectory on labor compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment in car wash infrastructure migrates toward jurisdictions where water-reclaim mandates remain less punitive than California's SB 606 thresholds, creating arbitrage windows for operators with transferable technology platforms.
United States
Express tunnel formats dominate new site development across suburban corridors, with fleet procurement teams unbundling wash services from bundled maintenance contracts. The EPA enforces Clean Water Act discharge limits on commercial runoff, compressing permit timelines in backlogged environmental review districts. Dallas-Fort Worth anchors the fastest expansion corridor, where reclaim-equipped tunnels capture multi-year fleet agreements.
Germany
Touchless sensor arrays with lidar-guided chemical dosing attract drought-conscious municipal fleet managers seeking reduced per-vehicle water consumption. REACH chemical restrictions expand prohibited surfactant lists, compelling detergent suppliers into 12-18 month product recertification cycles. The Stuttgart industrial cluster concentrates equipment fabricators supplying membrane-filtration stacks to tunnel operators across the Rhine-Ruhr metropolitan region.
India
Metro Delhi and Bangalore exhibit car ownership density without express tunnel saturation, creating first-mover positioning for reclaim-equipped formats. The country's national water efficiency directives tighten municipal permitting for commercial discharge, though enforcement variance persists across state jurisdictions. Mobile pressure-wash rigs capture intermittent demand from small commercial operators in Hyderabad's logistics corridors, bypassing fixed infrastructure requirements entirely.
France
National regulators enforce stricter REACH interpretation than EU Green Deal baselines, absorbing steepest compliance costs among European detergent suppliers. Automated interior cleaning with articulated arms traces expansion trajectories on labor compression in Paris-Saclay technology clusters. The Lyon-Grenoble corridor anchors equipment testing facilities for ozone-based sanitization systems specified in fleet hygiene contracts.
United Arab Emirates
Water scarcity mandates drive reclaim threshold specifications for new commercial permits in Dubai and Abu Dhabi municipal frameworks. Fleet operators with ESG reporting obligations specify reclaim-equipped sites exclusively, concentrating contract awards among operators with third-party sustainability audits. The Jebel Ali industrial zone hosts fabrication facilities supplying closed-loop processing systems to operators across the Gulf Cooperation Council states.
Global Car Wash Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with national-scale operators commanding suburban corridor positioning while regional chains defend mid-market metros through franchise density. The vendor base organizes around three strategic archetypes: throughput-optimized express tunnel networks, multi-format portfolio operators spanning flex-service and automatic configurations, and aggressive franchise expanders anchoring growth in underserved secondary cities. Competitive dynamics center on M&A consolidation of regional wash chains and technology licensing partnerships that accelerate reclaim system deployment without captive R&D investment.
Within the national-scale tier, Mister Car Wash and Driven Brands exemplify divergent format strategies, with the former concentrating express tunnel density in high-throughput corridors and the latter sustaining multi-format coverage across suburban and urban site configurations. Zips Car Wash occupies a position within the franchise-expansion archetype, anchoring growth through mid-market metro penetration rather than coastal primary markets. These three operators collectively represent the competitive tension between scale-driven standardization and format flexibility that shapes capital allocation across the sector.
| Leading Market Players |
|---|
| Mister Car Wash |
| Driven Brands |
| Zips Car Wash |
| Quick Quack Car Wash |
| Autobell Car Wash |
| Splash Car Wash |
| Tommy's Express Car Wash |
| Wash Depot Holdings Inc. |
| International Car Wash Group (ICWG) |
| Others |
Supply Flow & Price Mechanics
California SB 606 reclaim thresholds gate qualified supply for premium-tier wash equipment, concentrating pricing power among membrane-filtration vendors while excluding legacy operators from municipal fleet contracts. Equipment buyers face tiered access based on water-recycling certification tiers, with drought-prone jurisdictions commanding 15-20% procurement premiums for compliant systems.
Pricing Analysis
Distributor margins on tunnel equipment compress as direct-to-fleet contracting expands, bypassing traditional equipment resellers. Pricing stratifies across premium touchless sensor arrays, standard soft-cloth configurations, and economy-grade rollover units, with lidar-guided dosing systems commanding certification premiums. Cost compression in mid-tier equipment intensifies as Chinese fabricators enter membrane-filtration component markets. Fleet procurement teams exhibit lowest price sensitivity due to ESG-mandated supplier qualification, while independent single-site operators face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from major US fleet operators mandate qualified suppliers in both Germany and South Korea for specialized stainless-steel conveyor alloys. Raw material dependencies center on nickel-bearing alloys, membrane filtration media, and precision sensor arrays sourced from East Asian fabrication clusters. Single-source vulnerability concentrates in German pump assembly specialists serving reclaim system integrators. Distribution runs through regional equipment distributors with certified installation networks, though direct OEM-fleet relationships are displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA Clean Water Act enforcement tightening discharge thresholds and accelerating equipment replacement cycles among non-compliant operators.
For Market Incumbents: Cement suburban corridor density through reclaim-equipped express tunnel rollouts before California-style mandates spread to Texas and Florida markets. Prioritize backward integration into membrane-filtration component production to defend margin position against Korean alloy suppliers. Mobile pressure-wash substitution threatens intermittent-demand segments; lock multi-year fleet agreements with chemical-disclosure riders to neutralize entrant access. For New Entrants and Emerging Players: Launch via franchise partnerships in India's Bangalore and Hyderabad corridors where express tunnel saturation remains low and national water-efficiency directives are tightening. Target dealership prep services as the most penetrable segment, where volume volatility deters incumbent investment. Pursue municipal fleet RFPs with ozone-treatment hygiene specifications as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional wash chains with 8-15 site footprints because fragmented ownership prevents capital access for SB 606 retrofits. Long-term viability hinges on water-reclaim technology transferability across jurisdictions. Watch California State Water Resources Control Board permit denial rates as the signal for accelerated consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Reclaim Technology Licensing | Equipment vendors with membrane-filtration IP gain preferential access to Dubai and Abu Dhabi municipal procurement frameworks. |
| Fleet Telematics Integration | RFID-enabled subscription platforms convert transactional wash revenue to recurring contracted streams with logistics operators. |
| Franchise Network Expansion | Mid-market metro penetration in underserved US secondary cities captures volume before express tunnel saturation peaks. |
| Chemical Formulation Recertification | Detergent suppliers with dedicated regulatory affairs teams absorb REACH compliance costs that eliminate smaller competitors. |
| Retrofit Service Capability | Specialized plumbing contractors with reclaim system expertise command premium installation rates during California SB 606 compliance windows. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet procurement managers, tunnel equipment fabricators, chemical supply technical directors, and municipal permitting officers with secondary validation against EPA discharge permit databases, California State Water Resources Control Board filings, and EU ECHA REACH registration data. Bottom-up site deployment tracking and top-down equipment shipment analysis provided cross-verification.
Segment-weighting applied service format splits, technology tier distributions, and end-user contract structures across the projection horizon. Modeled dimensions included automatic versus self-service versus mobile format shares, reclaim-equipped versus standard water-use technology penetration, and fleet versus retail versus rental customer concentration. CAGRs derived from equipment replacement cycle analysis and regulatory mandate phase-in schedules, with water scarcity indices and fleet ESG adoption curves as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt drought emergency declarations, tariff disruptions on German and South Korean alloy imports, and technological substitution by autonomous vehicle self-cleaning systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Mobility Scooters Market
Automotive Services
GCC Car Rental Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Parking Services Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
United States Automotive Service Market
Automotive Services
Car Wash System Market
Automotive Services
Car Rental Business Market
Automotive Services
Automotive Retail Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
North America Car Wash Market
Automotive Services
Automotive Register Market
Automotive Services
Vehicle Roadside Assistance Market