
 France Car Rental Market | 2026-2036
France Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
France Car Rental Market Analysis
Connected vehicle telematics and AI-powered demand forecasting is reshaping fleet allocation across French metropolitan hubs. Europcar Mobility Group leverages its domestic station density to sustain coverage advantages in secondary cities. Virtuo anchors its position through app-native operations that eliminate physical counter interactions. Enterprise Holdings competes via integrated business travel programs serving multinational accounts headquartered in Paris and Lyon.
Car rental denotes the short-to-medium-term commercial provision of motorized passenger vehicles, typically governed by daily or weekly rate structures with specified mileage allowances and insurance conditions, serving mobility needs when personal vehicle ownership is impractical or undesirable. The France market operates through four service type categories where airport rentals capture premium inbound traffic while long-term rentals generate predictable recurring revenue from corporate subscribers. Vehicle type segmentation shows electric vehicles commanding higher per-day rates despite elevated capital costs, with SUVs occupying the largest share of leisure-oriented summer demand along the Côte d'Azur.
France's national regulator ANSM oversees commercial vehicle safety standards while EU-wide GDPR frameworks govern customer data collection through mobile booking channels, and the national low-emission mobility framework progressively restricts internal combustion engine fleet composition in urban access zones. The DGCCRF monitors pricing transparency and contract fairness in consumer-facing rental agreements. Stakeholders must evaluate how Paris's expanding ZFE-m (Zone à Faibles Émissions) boundaries will force accelerated fleet electrification timelines and reshape station economics across the capital region.
Market Dynamics
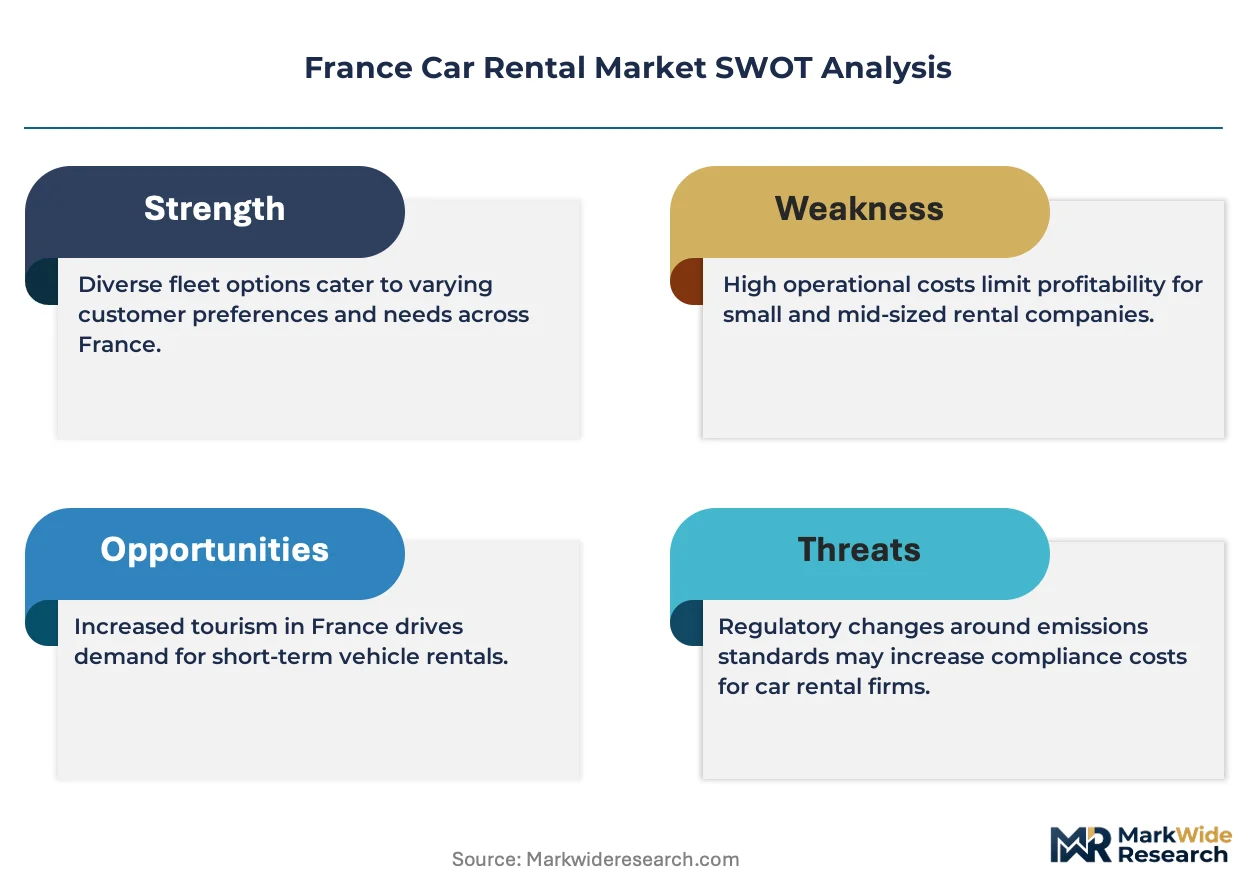
Fleet electrification mandates under France's national low-emission mobility framework are compressing capital deployment cycles and forcing station-level profitability recalculations across Paris, Lyon, and Marseille metropolitan zones.
Growth Catalysts
- ZFE-m Zone Expansion:Paris's tightening low-emission boundaries accelerate electric vehicle procurement among airport and downtown station operators seeking urban access compliance.
- Corporate Subscription Models:Lyon and Bordeaux-based multinational headquarters are consolidating vendor relationships into flexible long-term contracts with embedded telematics reporting.
- AI-Powered Fleet Allocation:Predictive demand algorithms reduce vehicle idle time at Provence-Alpes-Côte d'Azur summer peak locations.
Market Restraints
- EV Capital Intensity:Battery-electric vehicle acquisition costs strain balance sheets before residual value curves stabilize in secondary French markets.
- Charging Infrastructure Gaps:Rural Auvergne-Rhône-Alpes and Nouvelle-Aquitaine regions lack sufficient fast-charging density for profitable electric fleet deployment.
- GDPR Data Friction:EU-wide customer data collection restrictions through mobile booking channels increase compliance overhead for app-native rental platforms.
Strategic Opportunities
- Intercity Rail Integration:TGV station-adjacent micro-rental hubs capture modal shift demand from Paris-Lyon and Paris-Marseille corridor travelers.
- Last-Mile Logistics Crossover:Commercial van rental pools serve e-commerce delivery contractors in Ile-de-France urban peripheries.
- Carbon Accounting Services:Corporate travel departments seek rental partners offering Scope 3 emissions reporting aligned with CSRD disclosure requirements.
Industry Challenges
- Technician Training Bottlenecks:High-voltage electric vehicle maintenance certification programs have not scaled to match fleet electrification timelines.
- Legacy Reservation System Migration:Established operators face integration complexity connecting proprietary platforms with third-party mobility-as-a-service aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Car Rental Market |
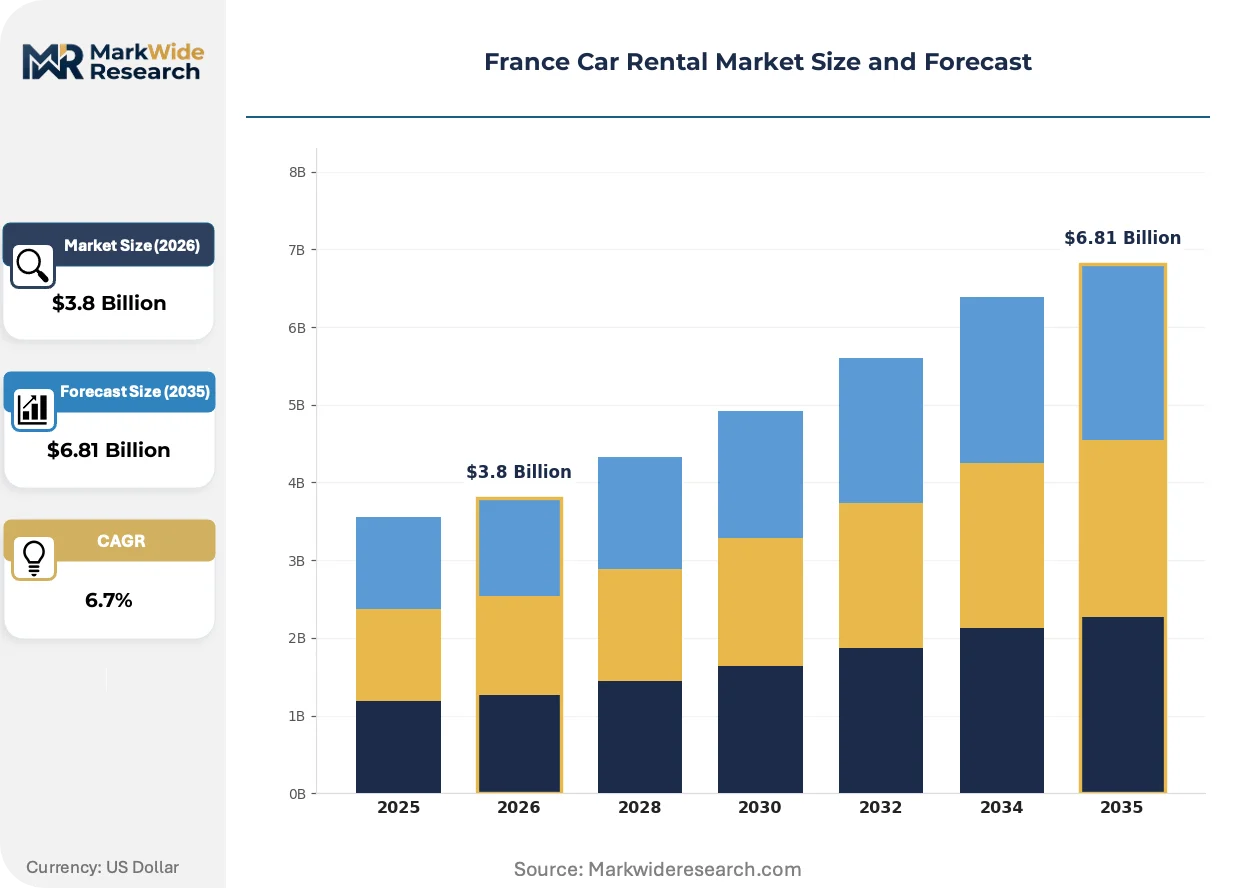
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airport Rentals, City Rentals, Long-Term Rentals, Luxury Rentals Vehicle Type: Economy Cars, SUVs, Vans, Electric Vehicles Customer Type: Business Travelers, Tourists, Local Residents, International Visitors Booking Channel: Online Booking, Travel Agents, Mobile Apps, Phone Reservations |
| Companies Covered | Europcar Mobility Group, Virtuo, Enterprise Holdings, Getaround France, Keddy by Europcar, Avis Budget Group, Sixt SE, Drivy, Hertz Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Car Rental Market Emerging Trajectories
Digital-native operational models and embedded vehicle connectivity are compressing traditional counter-based rental economics while creating new data monetization pathways across French urban mobility networks.
Telematics-enabled usage-based insurance is hybridizing risk pricing models in the commercial rental segment. Fleet operators serving corporate accounts in Paris and Lyon now embed real-time driving behavior data into dynamic premium calculations. This convergence is compressing traditional annual policy structures into per-rental micro-pricing frameworks.
France's national low-emission mobility framework progressively restricts internal combustion engine fleet composition in urban access zones. The DGCCRF monitors pricing transparency while ANSM oversees vehicle safety standards. Corporate rental segments face accelerated compliance timelines as ZFE-m boundaries expand beyond Paris into Grenoble and Strasbourg.
App-native booking behavior has displaced phone and walk-in reservation channels among leisure travelers under 45. Physical counter elimination reduces station labor costs but increases customer service automation investment requirements. This shift concentrates most visibly in Ile-de-France and Côte d'Azur tourism corridors where inbound travelers expect seamless mobile pickup.
France Car Rental Market Segmentation
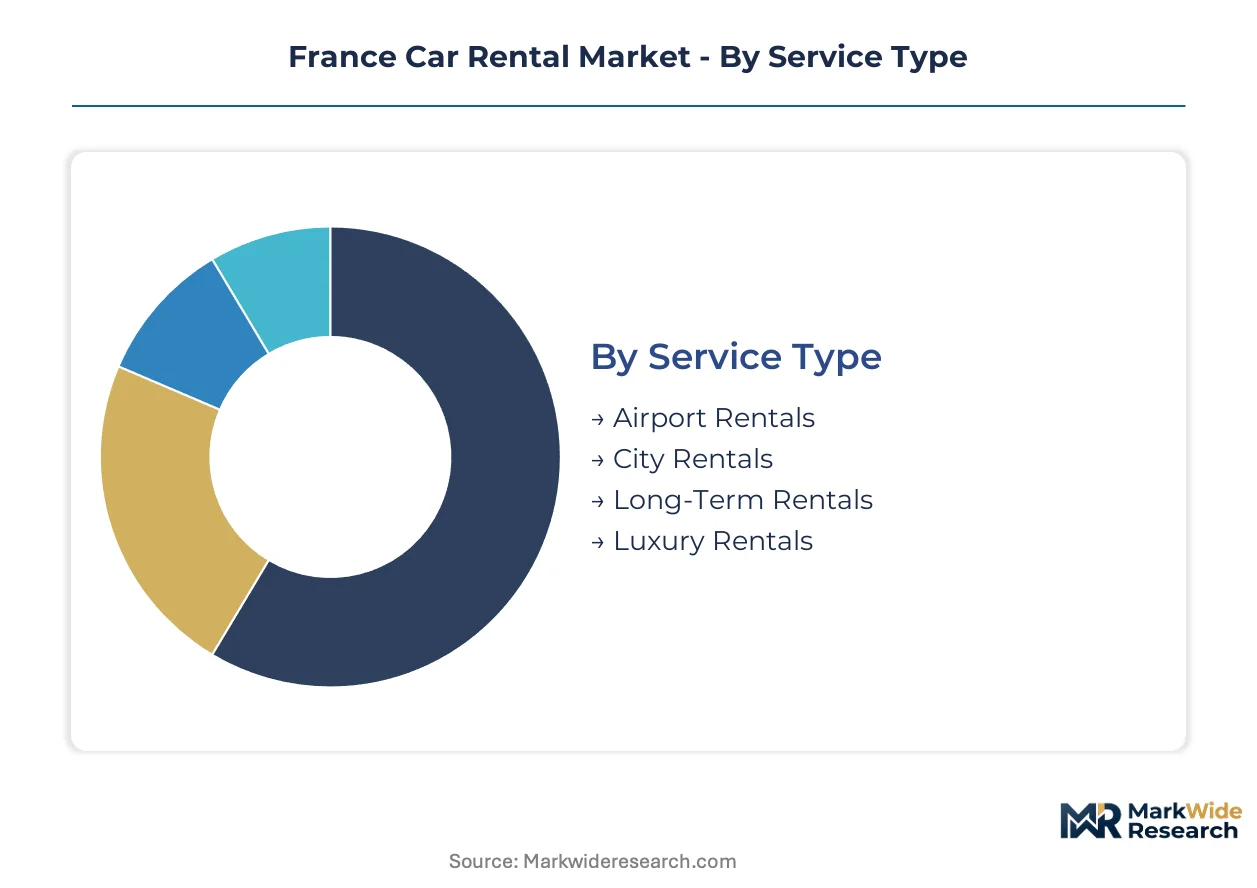
Segmentation in the France car rental market determines capital allocation across station networks and shapes how operators balance fixed infrastructure against flexible demand. Each dimension carries distinct margin profiles and regulatory exposure that influence fleet procurement cycles.
Service Type:
After-sales service intensity varies sharply across service formats, with airport and long-term rentals demanding dedicated account management while city and luxury segments require concierge-level incident response capabilities.
- Airport Rentals:These operations handle high-turnover, short-duration contracts with inbound travelers arriving at Charles de Gaulle, Nice Côte d'Azur, and Lyon-Saint-Exupéry. Fleet utilization peaks track flight arrival patterns, with ANSM safety inspections concentrated at these high-volume hubs where vehicle turnover stress accelerates maintenance cycles.
- Long-Term Rentals:Corporate subscribers in Lyon and Bordeaux headquarters favor these flexible contracts with embedded telematics reporting and predictable monthly billing. The segment generates recurring revenue streams that stabilize cash flow against seasonal leisure volatility, though contract renegotiation cycles demand sustained relationship management.
- City Rentals:Downtown Paris, Marseille, and Toulouse stations serve mixed business-leisure demand with higher parking cost absorption and ZFE-m compliance requirements driving electric vehicle concentration.
- Luxury Rentals:Côte d'Azur and Alpine resort corridors concentrate ultra-premium vehicle deployment where summer tourism and winter ski seasons create concentrated high-value demand windows.
By volume, airport rentals lead. By growth pace, long-term rentals are expanding most quickly.
Vehicle Type:
Cost tier differentiation separates economy fleet procurement from premium electrified segments, with capital intensity and residual value risk stratifying operator balance sheet exposure.
- Electric Vehicles:Battery-electric models command elevated per-day rates despite higher acquisition costs, with Paris ZFE-m compliance creating captive urban demand. Charging infrastructure gaps in rural Auvergne-Rhône-Alpes constrain profitable deployment outside metropolitan cores, while technician training bottlenecks extend maintenance turnaround times.
- SUVs:These vehicles occupy the largest share of leisure-oriented summer demand along the Provence-Alpes-Côte d'Azur coastline, where family tourism and luggage capacity requirements drive preference. Fleet planners concentrate SUV inventory at Mediterranean stations during peak season, rotating units to Alpine locations for winter ski demand.
- Economy Cars:Compact internal combustion models face accelerating displacement by electric alternatives in Paris, Lyon, and Marseille access zones, with residual value curves compressing as ZFE-m boundaries tighten.
- Vans:Commercial utility demand from Ile-de-France e-commerce delivery contractors and small business logistics users creates year-round utilization stability distinct from leisure seasonality.
By volume, SUVs lead. By growth pace, electric vehicles are climbing the fastest.
Customer Type:
Application focus distinguishes mobility substitution patterns, with business travel demanding seamless expense integration while tourism segments prioritize price transparency and pickup convenience.
- Business Travelers:Corporate accounts headquartered in Paris and Lyon consolidate vendor relationships around integrated travel programs with centralized billing and carbon accounting alignment. These travelers require guaranteed availability and minimal pickup friction, accepting rate premiums for service reliability.
- Tourists:Domestic and inbound leisure visitors concentrate demand in Ile-de-France and Côte d'Azur corridors during peak seasons, with app-native booking behavior displacing traditional reservation channels among travelers under 45.
- Local Residents:Urban households without vehicle ownership access rentals for intermittent suburban or rural trips, with TGV station-adjacent micro-hubs capturing modal shift demand from rail corridors.
- International Visitors:Non-EU inbound travelers arriving at major airports generate premium rate capture opportunities, though GDPR data friction increases compliance overhead for mobile booking verification.
By volume, tourists lead. By growth pace, business travelers are gaining share fastest.
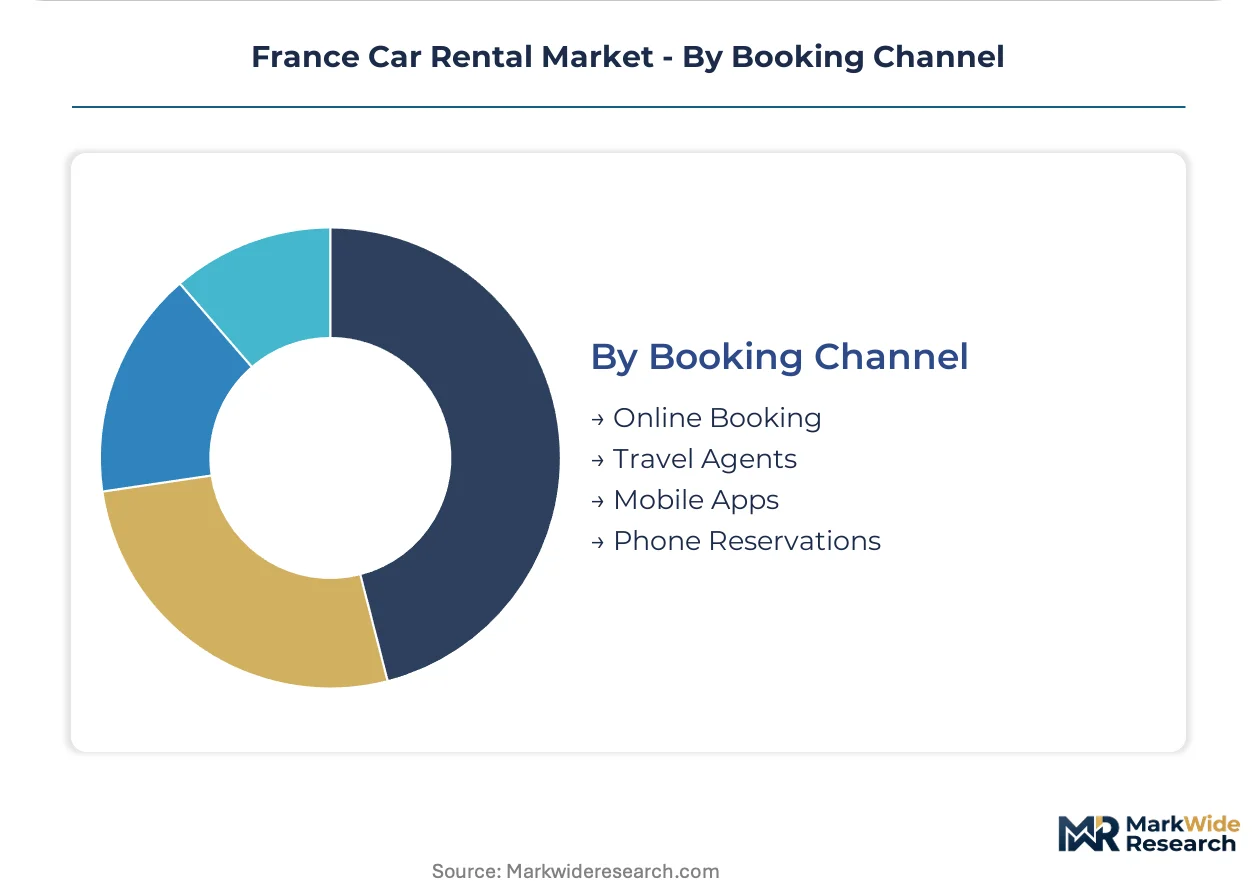
Booking Channel:
Customer type and technology adoption intersect to reshape reservation economics, with digital-native platforms compressing traditional intermediary margins while physical channels retain specific demographic segments.
- Mobile Apps:App-native operations eliminate physical counter interactions, reducing station labor costs while increasing automation investment requirements. Virtuo and similar platforms anchor positioning through seamless smartphone-based pickup and return workflows concentrated in metropolitan tourism corridors.
- Online Booking:Web-based direct reservations maintain relevance for corporate travel departments managing centralized procurement, with embedded telematics and carbon reporting features differentiating B2B platforms.
- Travel Agents:Traditional intermediaries retain share among older demographic segments and complex multi-leg itineraries where human assistance offsets digital friction.
- Phone Reservations:Voice channels now serve primarily last-minute contingency bookings and customer service resolution rather than primary acquisition, with call center economics challenged by automation alternatives.
By volume, online booking leads. By growth pace, mobile apps show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's car rental market operates as a net service exporter, with inbound tourism driving fleet utilization at major transport hubs while domestic operators source vehicles from German and Spanish manufacturing corridors. The national low-emission mobility framework creates regulatory harmonization pressures that reshape regional station economics unevenly across metropolitan and peripheral zones.
Île-de-France
Corporate headquarters concentration in Paris and La Défense generates sustained business travel demand for flexible long-term contracts. The ZFE-m low-emission zone expansion mandates electric vehicle integration at Charles de Gaulle and Orly airport stations. Fleet operators concentrate premium electrified inventory along the A4 and A6 autoroute corridors serving Greater Paris commuter belts.
Provence-Alpes-Côte d'Azur
Seasonal tourism peaks at Nice Côte d'Azur Airport drive summer fleet utilization rates significantly above annual averages. The DGCCRF monitors pricing transparency at Mediterranean coastal stations where international visitor concentration is highest. Luxury vehicle deployment concentrates in Cannes and Saint-Tropez during festival and yachting seasons.
Auvergne-Rhône-Alpes
Lyon-Saint-Exupéry Airport anchors corporate subscription demand from pharmaceutical and banking headquarters in the Rhône corridor. ANSM vehicle safety inspection protocols apply intensively at this hub given high-turnover business rental volumes. Alpine ski resort stations in Chambéry and Grenoble rotate SUV inventory between summer hiking and winter tourism demand cycles.
Nouvelle-Aquitaine
Bordeaux Mérignac Airport serves wine tourism and aerospace industry travel with mixed leisure-business customer profiles. Charging infrastructure gaps in rural Dordogne and Landes regions constrain profitable electric fleet deployment outside the metropolitan core. Station operators balance seasonal vineyard tourism spikes against year-round corporate contract stability.
Hauts-de-France
Lille-Europe TGV station-adjacent micro-rental hubs capture cross-border demand from Belgian and UK travelers via Eurostar connections. The region's logistics corridor concentration generates commercial van rental demand from e-commerce distribution contractors. Fleet planners position compact economy vehicles for short-duration urban access trips.
France Car Rental Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: legacy station-network operators with dense metropolitan coverage, app-native digital platforms eliminating physical counters, and integrated mobility providers bundling rental with rail and ride-hailing services. Dominant competitive moves include fleet electrification acceleration to meet ZFE-m compliance deadlines and telematics-enabled corporate subscription model expansion.
Within the legacy network tier, Europcar Mobility Group and Avis Budget Group exemplify station-density advantages through established airport and downtown presence. Virtuo and Getaround France occupy the digital-native archetype with smartphone-centric operations. Enterprise Holdings represents the integrated business travel segment serving multinational account consolidation needs. Sixt SE and Hertz Corporation anchor premium-tier positioning at major tourism and corporate corridors.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| Virtuo |
| Enterprise Holdings |
| Getaround France |
| Keddy by Europcar |
| Avis Budget Group |
| Sixt SE |
| Drivy |
| Hertz Corporation |
| Others |
Supply Flow & Price Mechanics
The A1 autoroute freight corridor linking Paris to Lille compresses logistics costs for vehicle procurement while amplifying price differentiation between Île-de-France metropolitan stations and peripheral Auvergne-Rhône-Alpes locations. Supply concentration around German and Spanish manufacturing hubs interacts with ZFE-m compliance timelines to reshape fleet acquisition economics across French rental networks.
Pricing Analysis
Corporate travel departments anchor rate structures around long-term subscription contracts with embedded telematics reporting and carbon accounting alignment. Three-tier pricing structure across premium electrified SUVs, standard hybrid fleets, and economy internal combustion tiers reflects ZFE-m access compliance premiums alongside residual value risk stratification. Pricing pressure stems from battery-electric vehicle capital intensity before secondary market value curves stabilize, with inbound tourists at Nice Côte d'Azur Airport showing least price sensitivity while local residents accessing city stations demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from German OEMs and supply-chain finance facilities through French banking consortia structure working capital requirements for fleet operators. Vehicle procurement draws from Germany, Spain, and Czech Republic manufacturing corridors, with lithium-ion battery packs and semiconductor components creating input dependencies. Single-source vulnerability around EV powertrain modules concentrates risk, while distribution runs through airport-adjacent station networks and downtown micro-hubs serving TGV corridor travelers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's car rental market fragments around electrification compliance timelines and app-native operational models, with ZFE-m boundary expansion creating distinct competitive niches for specialized station operators and digital platforms.
For Market Incumbents: Harden station-network advantages by accelerating technician certification programs for high-voltage electric vehicle maintenance before compliance deadlines compress service capacity. Consolidate vendor relationships with Lyon and Bordeaux corporate headquarters through integrated telematics reporting that locks in long-term contract renewals against digital-native competitors.
For New Entrants and Emerging Players: Rural Nouvelle-Aquitaine charging infrastructure gaps present white-space capture opportunities for van rental pools serving e-commerce logistics contractors. TGV station-adjacent micro-hubs along Paris-Lyon and Paris-Marseille corridors offer penetrable entry points with lower capital intensity than airport station establishment, with rail-integration marketing anchoring go-to-market positioning.
For Investors and Strategic Acquirers: ZFE-m boundary expansion beyond Paris into Grenoble and Strasbourg reshapes the acquisition landscape toward electrified fleet operators with proven urban access compliance. Long-term viability centers on platforms combining vehicle rental with embedded carbon accounting services aligned with CSRD disclosure requirements, with technician training throughput serving as the critical inflection signal for scalable electrification.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | ZFE-m compliance deadlines at Paris, Lyon, and Marseille stations force battery-electric procurement ahead of residual value stabilization. |
| Telematics-Enabled Subscription Models | Corporate accounts in La Défense and Lyon-Saint-Exupéry corridor demand embedded usage reporting with predictable monthly billing structures. |
| TGV Station Micro-Hub Expansion | Modal shift capture along Paris-Lyon and Paris-Marseille rail corridors reduces parking cost absorption versus downtown station economics. |
| Technician Certification Scaling | ANSM safety protocols and high-voltage EV maintenance requirements create bottleneck risk without accelerated training program investment. |
| Carbon Accounting Service Integration | CSRD-aligned Scope 3 emissions reporting differentiates corporate travel programs serving multinational headquarters procurement departments. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet operations directors, corporate travel procurement managers, station network planners, and automotive OEM account executives and refined through secondary validation against DGCCRF pricing transparency filings, ANSM vehicle safety inspection records, EU transport statistics, and airport authority passenger flow data. Bottom-up station-level utilization modeling triangulated with top-down tourism arrival patterns and corporate contract disclosure patterns.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, vehicle propulsion architecture, customer application focus, and regional regulatory cluster. CAGRs were derived from fleet turnover velocity, electrification mandate compliance timelines, and inbound tourism recovery trajectories, with ZFE-m boundary expansion schedules and charging infrastructure deployment curves serving as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification acceleration by Europcar Mobility Group or Enterprise Holdings would shift outcomes beyond modeled parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Auto Leasing Services Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Car Vending Machine Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Motorsports Market
Automotive Services
North America Car Wash Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
United States Automotive Service Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Global Car Wash Market