
 Sub Saharan Africa Automotive Market | 2026-2036
Sub Saharan Africa Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Sub Saharan Africa Automotive Market Analytics
Market Dynamics
Skilled automotive technician availability is rotating toward assembly and aftermarket service hubs in Kenya, Nigeria, and Ghana, unlocking localized production capacity. Toyota Motor Corporation leverages its extensive dealer network and parts distribution infrastructure across East and West Africa. Volkswagen AG anchors its regional strategy through the Rwanda assembly facility and pan-African mobility platforms. Hyundai Motor Company competes aggressively in the compact SUV and light commercial segments through South African manufacturing exports.
Segmentation Analysis
The Sub Saharan Africa Automotive sector encompasses the design, assembly, distribution, and after-sales servicing of motorized vehicles tailored to diverse terrain, climate, and income conditions across the region, with powertrain configurations ranging from internal combustion engines rated for low-octane fuels to emerging battery-electric architectures optimized for grid intermittency. Its primary purpose is to enable personal mobility, goods transport, and commercial logistics across infrastructure-constrained environments. The pickup vehicle type dominates commercial applications across agricultural and mining sectors, while the hybrid fuel type captures expanding interest among urban fleet operators seeking fuel cost insulation. The economy vehicles market segment sustains the highest unit volumes, though luxury vehicles concentrate margin pools in select metropolitan centers.
Regulatory Environment
Kenya's Energy Regulatory Authority and South Africa's National Regulator for Compulsory Specifications shape powertrain standards and vehicle safety compliance across their respective markets, while the African Continental Free Trade Area rules of origin framework reconfigures cross-border assembly and component sourcing economics. Nigeria's Standards Organisation mandates local content thresholds that influence OEM localization decisions. Stakeholders must monitor harmonization gaps between national automotive policies and the AfCFTA automotive protocol to anticipate tariff and investment incentive shifts.
Market Dynamics
Diesel-to-hybrid powertrain transitions are compressing fleet replacement cycles across East African logistics corridors as Kenya's Energy Regulatory Authority clean mobility guidelines reshape procurement specifications for commercial vehicle operators.
Growth Catalysts
- AfCFTA Rules of Origin:The African Continental Free Trade Area automotive protocol is reconfiguring cross-border assembly economics, incentivizing component localization across Nigeria, Kenya, and Ghana assembly corridors.
- Urban Fleet Electrification:Kenya's Energy Regulatory Authority clean mobility guidelines are mandating hybrid powertrain adoption for commercial logistics operators serving the Northern Corridor.
- Aftermarket Service Hubs:Skilled technician migration toward assembly and service clusters in Lagos-Abuja, Nairobi-Mombasa, and Accra-Tema corridors is unlocking localized maintenance capacity.
Market Restraints
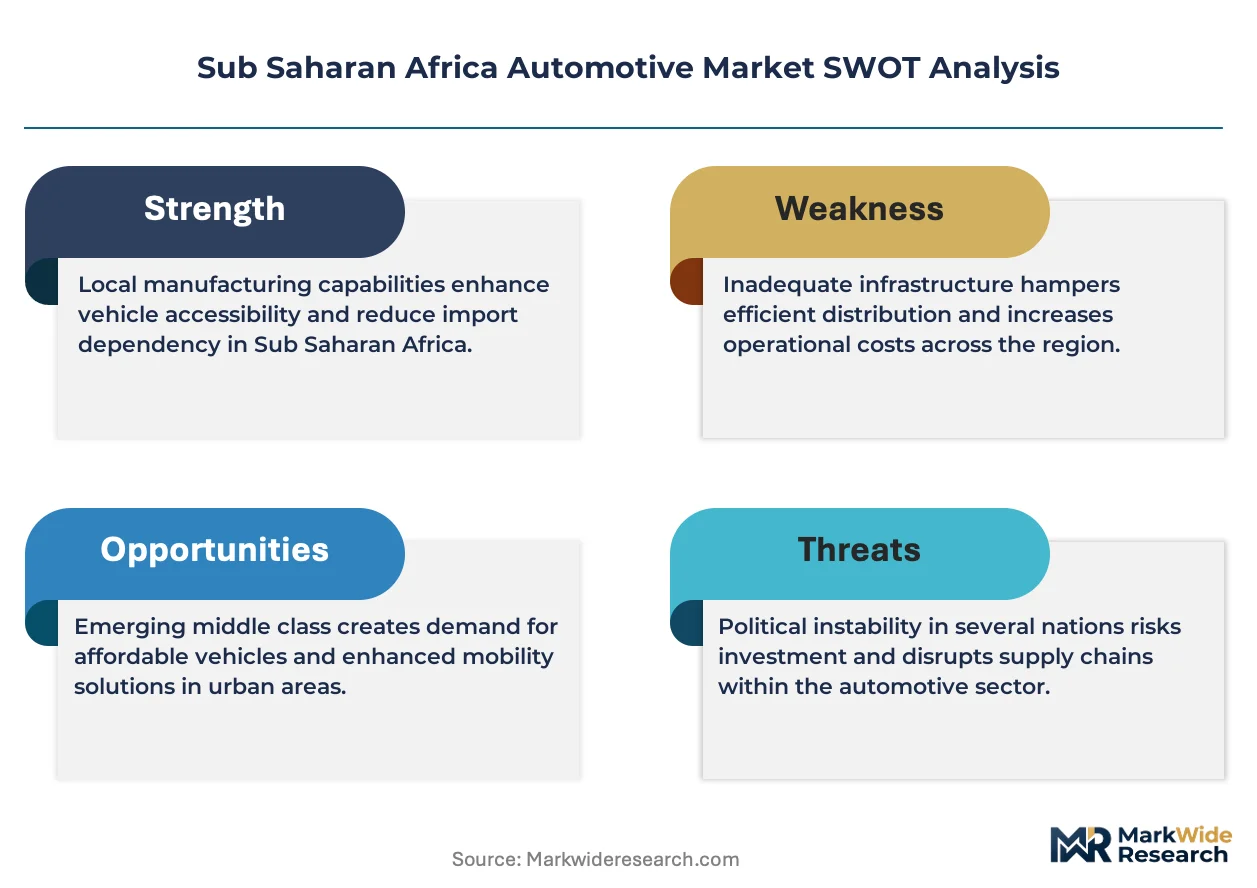
- Low-Octane Fuel Infrastructure:Widespread availability of sub-standard fuels across rural distribution networks forces continued internal combustion engine calibration compromises that limit advanced powertrain deployment.
- Grid Intermittency:Unreliable electricity supply in secondary cities constrains battery-electric vehicle charging infrastructure rollout, particularly outside South Africa's urban cores.
- Import Tariff Cascades:Nigeria's Standards Organisation local content thresholds create compliance friction for OEMs seeking to balance fully-knocked-down assembly against semi-knocked-down cost structures.
Strategic Opportunities
- Rwanda Assembly Platform:Volkswagen AG's Kigali facility demonstrates scalable pan-African mobility platform potential for compact vehicle categories serving landlocked East African markets.
- Used Vehicle Reconditioning:Ghana's emerging automotive service export corridor offers aftermarket value capture from European and Asian pre-owned vehicle inflows.
- Hybrid Retrofit Kits:Conversion technology convergence between mild-hybrid systems and existing diesel fleets presents aftermarket revenue streams for Lagos-based commercial vehicle workshops.
Industry Challenges
- Technician Certification Gaps:Battery-electric and hybrid powertrain diagnostic competency remains concentrated in South African training institutions, creating skills bottlenecks for East and West African service networks.
- Harmonization Delays:Divergent national automotive policies across Kenya, Nigeria, and South Africa complicate pan-regional platform standardization for OEMs operating under AfCFTA protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sub Saharan Africa Automotive Market |
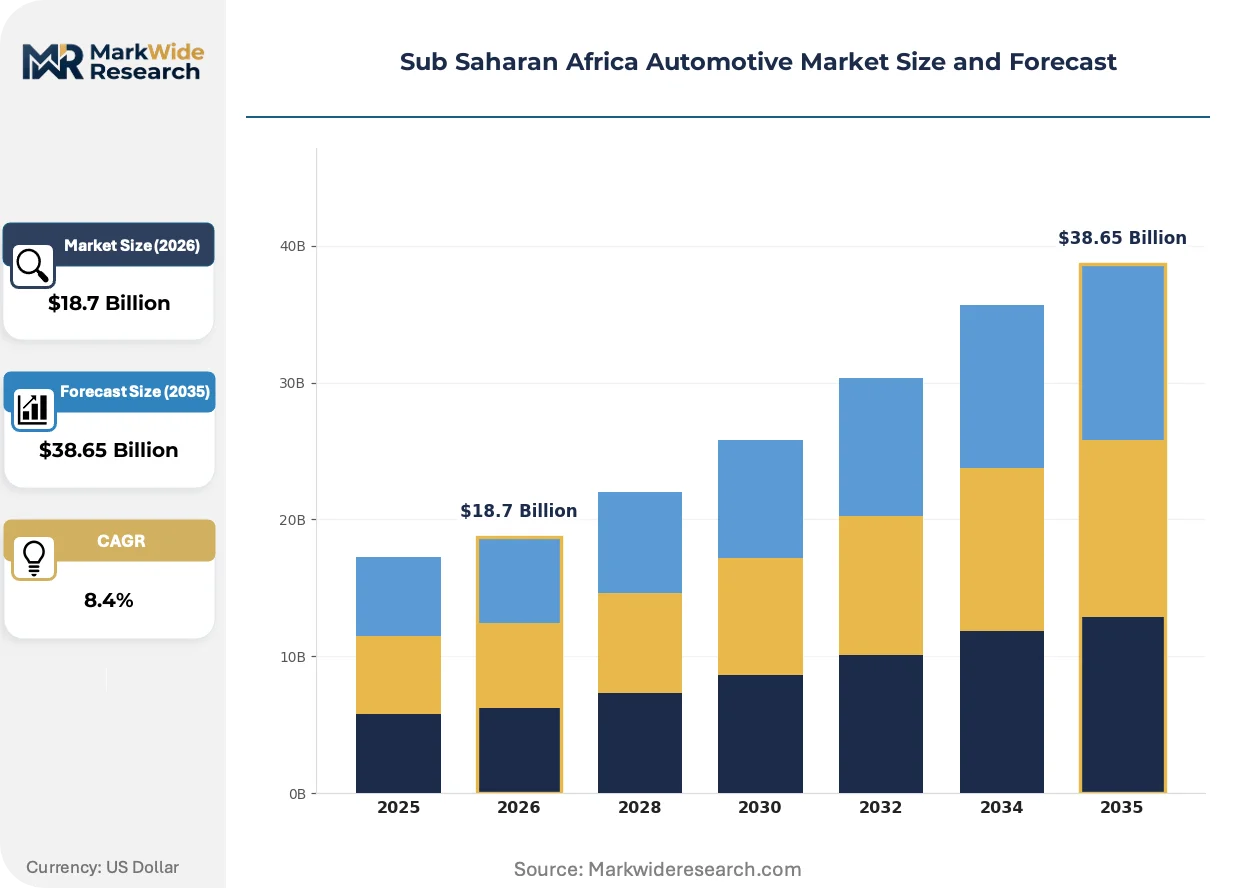
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Pickup Fuel Type: Petrol, Diesel, Electric, Hybrid Market Segment: Commercial Vehicles, Passenger Vehicles, Luxury Vehicles, Economy Vehicles Sales Channel: Direct Sales, Dealerships, Online Platforms, Auctions |
| Companies Covered | Toyota Motor Corporation, Volkswagen AG, Hyundai Motor Company, Nissan Motor Corporation, Isuzu Motors Ltd., Stellantis N.V., Daimler AG, Ford Motor Company, Innoson Vehicle Manufacturing, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sub Saharan Africa Automotive Market Evolving Landscape
Powertrain diversification and digital distribution channels are fragmenting traditional vehicle procurement patterns across Sub Saharan Africa, compressing legacy dealer network dominance while elevating fleet-direct and platform-based acquisition models.
Mild-hybrid architectures optimized for low-octane fuel compatibility are supplanting conventional diesel powertrains in commercial vehicle segments. Kenyan logistics operators along the Northern Corridor are adopting these systems at accelerated replacement cycles. The technology is compressing total cost of ownership differentials between hybrid and conventional drivetrains in high-mileage applications.
Kenya's Energy Regulatory Authority clean mobility guidelines and South Africa's National Regulator for Compulsory Specifications are tightening emissions compliance windows for imported vehicles. These frameworks are forcing OEMs to pre-certify hybrid and electric variants before market entry. Commercial fleet segments in Nairobi and Johannesburg are responding with accelerated procurement of compliant powertrains ahead of enforcement deadlines.
Fleet operators are consolidating vehicle acquisition through direct manufacturer relationships, bypassing traditional dealer intermediaries. Large logistics and mining companies in Nigeria and South Africa are negotiating volume frameworks with assembly plants. This channel compression is most visible in the Lagos-Abuja manufacturing corridor where enterprise procurement teams manage specification and delivery directly.
Sub Saharan Africa Automotive Market Segmentation
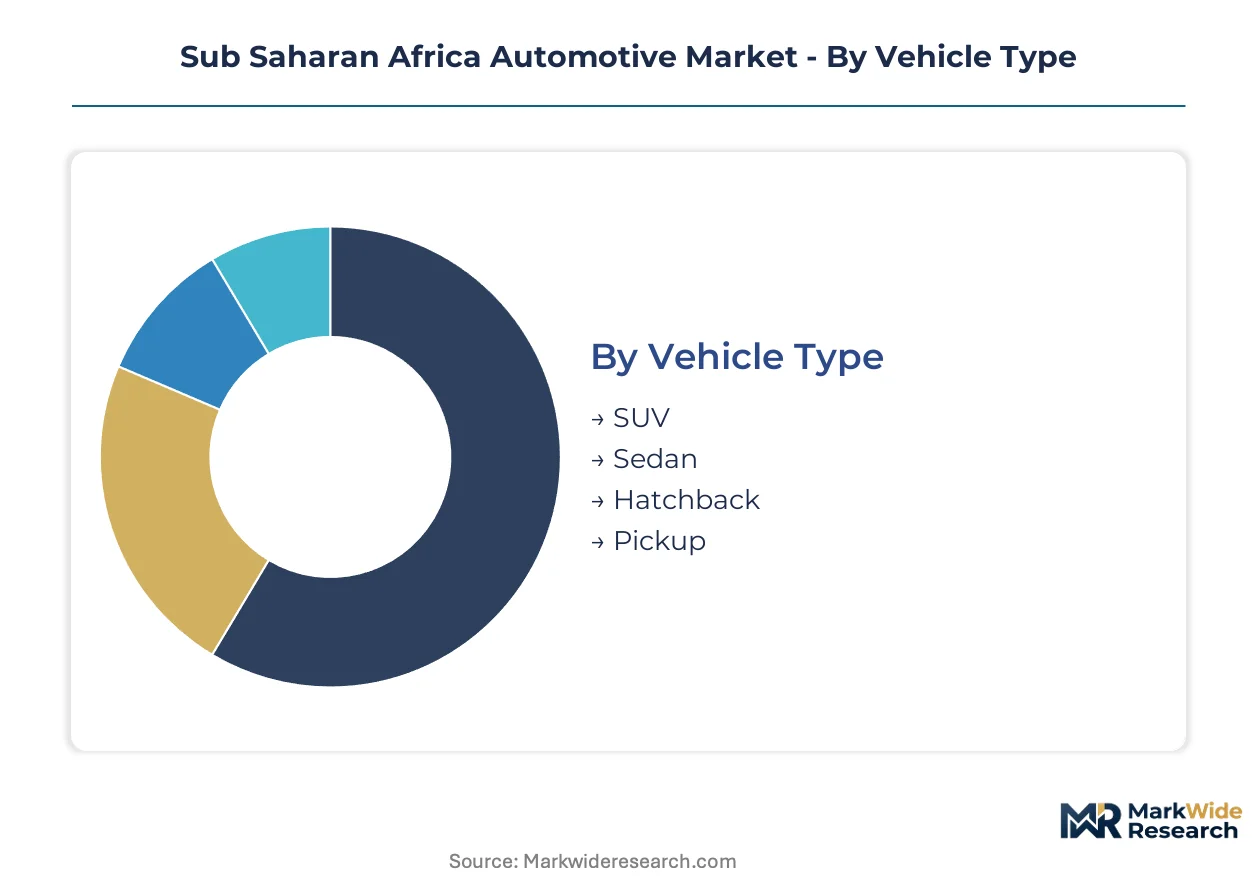
Segmentation in Sub Saharan Africa Automotive Market reveals how infrastructure constraints, income stratification, and regulatory fragmentation create distinct demand pockets across vehicle categories and procurement channels. Understanding these divides enables targeted platform development for terrain-specific applications and price-sensitive customer bases.
Vehicle Type:
Domestic assembly concentrates on pickup and SUV platforms serving agricultural and mining corridors, while sedan and hatchback supply depends heavily on South African manufacturing exports and used vehicle imports from European markets.
- Pickup:Body-on-frame construction with reinforced suspension systems handles unpaved road conditions across Nigeria's agricultural belts and Kenya's Northern Corridor logistics routes. Mining operators in Ghana's Ashanti region and construction fleets in Tanzania's Dar es Salaam periphery drive replacement demand for double-cab configurations with enhanced payload ratings.
- SUV:Ladder-frame and monocoque architectures optimized for ground clearance dominate family transportation and executive mobility across Lagos-Abuja and Nairobi-Mombasa corridors. Kenyan Energy Regulatory Authority clean mobility guidelines are accelerating hybrid SUV procurement among corporate fleet managers seeking fuel cost predictability.
- Sedan:Three-box passenger configurations sustain volume in urban taxi and ride-hailing applications across Abidjan and Dakar.
- Hatchback:Compact two-box designs serve first-time buyers and small urban households in Accra-Tema and Kigali assembly catchment areas.
Pickup holds the largest share; momentum sits with SUV as hybrid powertrains penetrate fleet procurement specifications.
Fuel Type:
Cost tier stratification separates premium hybrid and electric offerings from mass-market internal combustion, with infrastructure availability determining viable powertrain deployment across rural-urban divides.
- Hybrid:Mild-hybrid and full-hybrid systems calibrated for low-octane fuel compatibility are gaining fleet adoption along Kenya's Northern Corridor under Energy Regulatory Authority procurement mandates. Total cost of ownership compression in high-mileage commercial applications is displacing conventional diesel in Lagos-Abuja logistics operations.
- Diesel:Compression-ignition engines rated for high-sulfur fuel grades continue serving heavy commercial and mining applications across Nigeria's manufacturing corridor and South Africa's industrial hubs. Grid intermittency outside major urban centers preserves diesel's viability for long-haul routes lacking charging infrastructure.
- Petrol:Spark-ignition powertrains dominate entry-level passenger vehicle segments across Ghana and Senegal where refueling infrastructure remains more developed than electric charging networks.
- Electric:Battery-electric architectures face deployment constraints from electricity reliability gaps in secondary cities outside Johannesburg and Cape Town metropolitan areas.
Diesel retains volume leadership; hybrid platforms are climbing the fastest as regulatory compliance windows tighten.
Market Segment:
Customer type fragmentation separates enterprise fleet procurement from individual ownership, with distinct margin structures and service requirements across commercial, luxury, and economy tiers.
- Commercial Vehicles:Light, medium, and heavy-duty configurations serve goods transport, construction, and mining operations across Nigeria's Lagos-Abuja corridor and Kenya's Mombasa port hinterland. Fleet operators are consolidating direct manufacturer relationships to bypass traditional dealer markups.
- Economy Vehicles:Entry-price-point cars and light commercial vehicles sustain highest unit volumes across Ghana, Senegal, and Ethiopia's emerging assembly markets. Used vehicle reconditioning hubs in Tema and Mombasa feed affordable mobility demand.
- Passenger Vehicles:Private ownership segments span middle-class family transportation in Nairobi and Lagos metropolitan areas.
- Luxury Vehicles:Premium sedans and SUVs concentrate margin pools in Johannesburg, Lagos, and Nairobi executive markets with specialized after-sales service requirements.
Economy vehicles command unit leadership; commercial vehicles are gaining share fastest through fleet electrification mandates.
Sales Channel:
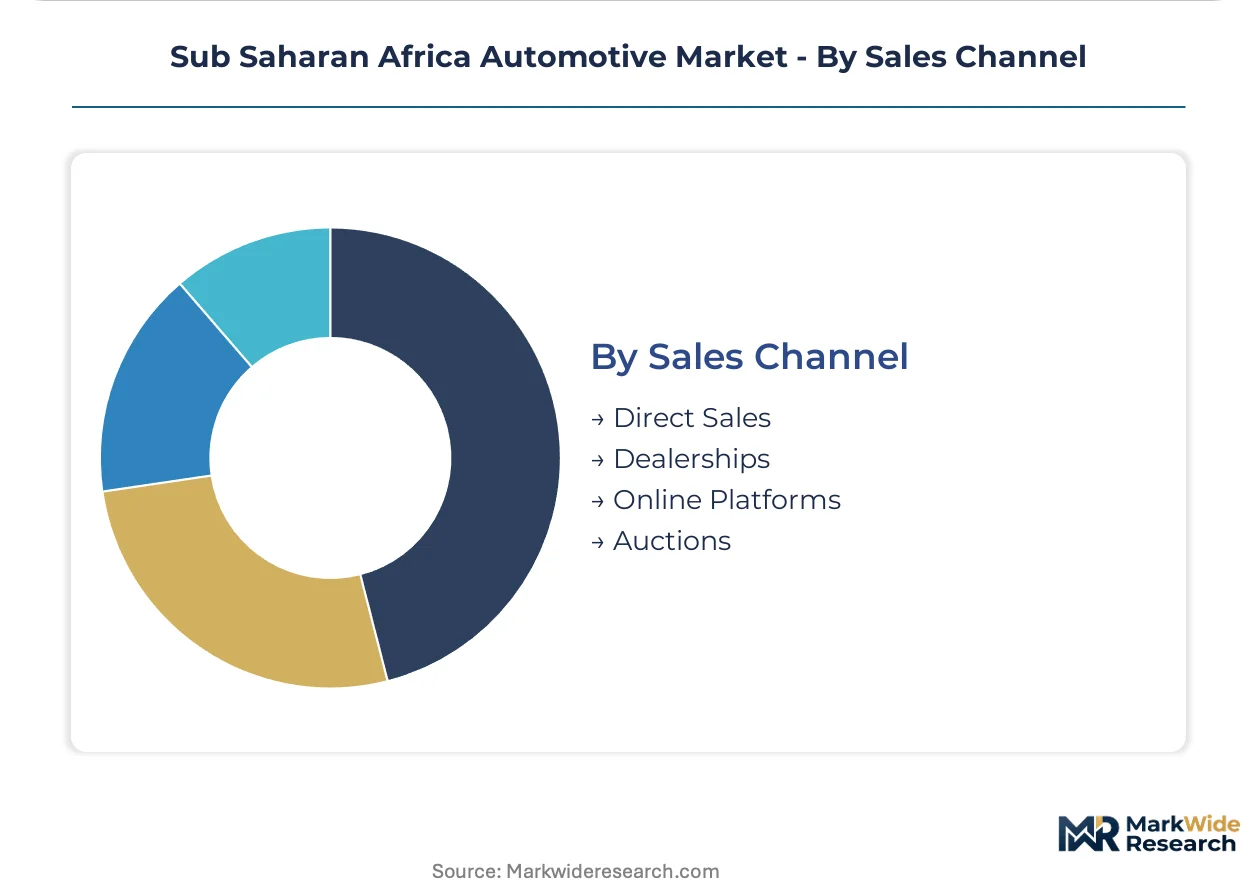
Supply concentration varies between established dealer networks, emerging digital platforms, and direct enterprise procurement reshaping distribution economics.
- Dealerships:Branded retail networks anchored by Toyota, Volkswagen, and Hyundai maintain parts distribution and service infrastructure across East and West African capitals. These physical touchpoints handle warranty fulfillment and financing arrangements for individual buyers.
- Direct Sales:Enterprise procurement teams at mining and logistics companies negotiate volume frameworks directly with assembly plants in Nigeria and South Africa. Channel compression eliminates intermediary margins for large fleet operators.
- Online Platforms:Digital marketplaces for new and used vehicle listings are emerging in Kenya and Nigeria's urban centers.
- Auctions:Bulk disposal channels for fleet renewals and insurance salvage operate primarily in South Africa with cross-border buyer participation.
Dealerships retain structural dominance; direct sales are expanding most quickly among enterprise fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vehicle utilization patterns diverge sharply across Sub Saharan Africa. Nigeria and South Africa concentrate on heavy commercial logistics and mining fleets. Kenya and Ghana prioritize hybrid urban mobility and agricultural light commercial transport.
Nigeria
Lagos-Abuja manufacturing corridor drives demand for pickup and heavy-duty trucks serving agricultural belts and construction sites. The Standards Organisation mandates local content thresholds that shape OEM assembly decisions. Assembly plant investments in Lagos Free Trade Zone are expanding domestic production capacity for commercial vehicle categories.
South Africa
Industrial hubs around Johannesburg and Cape Town sustain premium passenger and luxury vehicle demand alongside mining fleet procurement. The National Regulator for Compulsory Specifications enforces vehicle safety and emissions compliance standards. Manufacturing exports from Eastern Cape and Gauteng provinces supply neighboring SADC markets with assembled vehicles.
Kenya
Northern Corridor logistics operators are accelerating hybrid powertrain adoption under clean mobility procurement mandates. The Energy Regulatory Authority guidelines require commercial fleets to meet escalating emissions thresholds. Nairobi-Mombasa corridor hosts expanding assembly and aftermarket service clusters attracting skilled technician migration.
Ghana
Accra-Tema corridor serves as an emerging reconditioning hub for European and Asian pre-owned vehicle inflows. National automotive development policies incentivize assembly plant establishment through tariff relief mechanisms. Tema industrial zone is developing specialized automotive service export capacity for regional West African markets.
Rwanda
Landlocked East African positioning drives demand for compact vehicle platforms optimized for regional trade routes. Government mobility platform initiatives support assembly facility development in Kigali. The Kigali Special Economic Zone hosts Volkswagen AG's regional assembly operations serving Burundi and eastern DRC transit corridors.
Sub Saharan Africa Automotive Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Sub Saharan Africa automotive market. Toyota Motor Corporation and Volkswagen AG anchor the integrated tier through extensive distribution infrastructure and regional assembly platforms. Hyundai Motor Company and Nissan Motor Corporation occupy the scale-driven specialist tier competing on compact SUV and light commercial segments. Dominant competitive moves include direct fleet procurement relationships that bypass traditional dealer networks and hybrid powertrain pre-certification ahead of regulatory enforcement windows.
Among Japan-based integrated manufacturers, Toyota Motor Corporation represents the distribution-architecture archetype through its dealer network and parts infrastructure spanning East and West Africa. Volkswagen AG, a German AG-structured OEM, exemplifies the regional-assembly-platform model through its Rwanda facility and pan-African mobility initiatives. Hyundai Motor Company, a Korean fabricator, occupies the export-manufacturing position leveraging South African production for compact SUV and light commercial supply across the region.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volkswagen AG |
| Hyundai Motor Company |
| Nissan Motor Corporation |
| Isuzu Motors Ltd. |
| Stellantis N.V. |
| Daimler AG |
| Ford Motor Company |
| Innoson Vehicle Manufacturing |
| Others |
Value Network & Pricing Analysis
Kenya's Energy Regulatory Authority clean mobility guidelines and Nigeria's Standards Organisation local content thresholds simultaneously gate supplier qualification and stratify price tiers across the Sub Saharan Africa Automotive Market. OEMs must pre-certify hybrid powertrains and meet domestic assembly thresholds to access fleet procurement channels, compressing margin structures for non-compliant entrants while rewarding localized production with premium pricing power.
Pricing Analysis
Long-term offtake contracts dominate enterprise fleet procurement across Nigeria's Lagos-Abuja corridor and Kenya's Northern Corridor logistics networks. Three-tier pricing structure across premium, standard, and economy levels separates hybrid-compliant commercial vehicles from conventional diesel units and used vehicle imports. Cost compression in economy segments is intensifying because used vehicle reconditioning hubs in Ghana and Kenya expand affordable supply. Mining and logistics fleets demonstrate lowest price sensitivity due to total cost of ownership calculations, while individual first-time buyers in Accra and Dakar exhibit highest sensitivity to upfront acquisition costs.
Supply Chain Analysis
Extended inventory cycles and unpredictable lead times characterize component flows from South Africa, Japan, and Germany into East and West African assembly plants. Powertrain systems, stamped body panels, and electronic control modules draw from these manufacturing centers, with logistics chokepoints at Mombasa and Lagos ports creating delivery volatility. Distribution runs through branded dealer networks for individual buyers and direct manufacturer relationships for consolidated fleet operators. Single-source vulnerability persists for hybrid battery packs and advanced driver assistance sensors, constraining supply security for compliant vehicle variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sub Saharan Africa Automotive Market sits in early-cycle expansion as AfCFTA rules of origin reconfigure cross-border assembly economics and accelerate localized production capacity. Hybrid powertrain adoption mandates across Kenya and impending emissions compliance windows in South Africa create durable tailwinds for OEMs with certified platform offerings.
For Market Incumbents: Fortify dealer network control in Nairobi-Mombasa and Lagos-Abuja corridors against direct fleet procurement trends by embedding after-sales service contracts into vehicle financing packages. Invest in battery-electric and hybrid diagnostic certification programs at regional training hubs to close technician competency gaps threatening service revenue retention. Prioritize backward integration into component stamping and powertrain assembly within Nigeria's Free Trade Zone to satisfy Standards Organisation local content thresholds and secure tariff-advantaged positioning.
For New Entrants and Emerging Players: Lead with used vehicle reconditioning and hybrid retrofit kit offerings targeting Lagos-based commercial workshops and Accra-Tema service exporters. Ghana's emerging automotive service corridor presents the most penetrable entry point, with lower capital requirements than greenfield assembly and established demand from European pre-owned vehicle inflows. Deploy digital platform-based procurement tools to capture fragmented individual buyer segments bypassed by incumbent dealer networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid powertrain assembly as modular platform designs reduce tooling requirements for multi-vehicle production. Target acquisition candidates include mid-scale assembly operations with established AfCFTA rules of origin compliance and captive distribution in landlocked East African markets. Monitor harmonization progress between Kenya's Energy Regulatory Authority and South Africa's National Regulator for Compulsory Specifications as the signal indicating pan-regional platform standardization feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Pre-Certification | Energy Regulatory Authority compliance gates access to Nairobi fleet procurement channels. |
| Local Content Threshold Achievement | Standards Organisation mandates determine tariff treatment for Lagos-Abuja assembly plants. |
| Aftermarket Service Hub Expansion | Skilled technician clusters in Accra-Tema unlock maintenance revenue from regional vehicle parc. |
| Direct Fleet Procurement Relationships | Enterprise volume frameworks with mining operators bypass dealer margins and secure replacement demand. |
| Pan-African Mobility Platform Development | Volkswagen's Kigali facility demonstrates scalable compact vehicle supply for landlocked corridors. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers converged on the working assumptions underpinning this analysis. Primary fieldwork across Nairobi, Lagos, Johannesburg, and Accra was cross-referenced with vehicle production databases, IHS Markit registration data, customs and trade flow records, and national automotive policy filings. Bottom-up segmentation modeling was triangulated against top-down macroeconomic indicators to ensure consistency across volume and value outputs.
Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs were derived from trend extrapolation of historical assembly volumes, fleet replacement cycle compression rates, and regulatory compliance deadline impacts. Forecast inputs incorporated powertrain mix assumptions, AfCFTA tariff phase-in schedules, and grid reliability projections affecting electric vehicle deployment feasibility.
The analysis sits within stated boundaries; outcomes outside sustained AfCFTA implementation, stable low-octane fuel availability, and continued hybrid technology cost reduction would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and infrastructure investment commitments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Armored Transportation Services Market
Automotive Services
Global Car Wash Market
Automotive Services
North America MRO Distribution Market
Automotive Services
GCC Car Wash Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Car Subscription Market
Automotive Services
Cab Services Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Car Wash Services Market
Automotive Services
Singapore Car Rental Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Car Vending Machine Market