
 Automotive Digital Services Market | 2026-2036
Automotive Digital Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Services Market Analysis
Subscription-based vehicle data monetization is tilting competitive dynamics toward asset-light platform operators. Bosch leverages its embedded sensor ecosystem to sustain dominance in remote diagnostics hardware. Continental differentiates through edge-computing modules that process telematics data at the vehicle level. Ford anchors its position via proprietary fleet management software integrated with commercial vehicle lines.
Automotive digital services encompass software-driven solutions that extract, transmit, and analyze vehicle-generated data through onboard communication modules, cloud APIs, and mobile interfaces to enable predictive maintenance, navigation optimization, and usage-based insurance. Telematics and infotainment currently occupy the largest revenue pools, though edge computing deployment is expanding fastest as latency-sensitive applications proliferate. Fleet operators and OEMs represent the most concentrated end-user segments, with dealerships lagging in digital service adoption due to fragmented legacy IT infrastructure.
The EU AI Act, GDPR, and ISO 26262 functional safety standards collectively shape product development roadmaps and market access conditions for European automotive digital service providers. The US NHTSA and EPA impose parallel requirements on data logging and emissions reporting that influence platform architecture decisions. Stakeholders must evaluate which regulatory jurisdiction's compliance burden will determine their competitive viability before committing to fixed platform investments.
Market Dynamics
Connected fleet operators are forcing a platform architecture redesign as real-time vehicle data becomes the primary input for logistics optimization, compressing margins for hardware-centric suppliers while elevating software-defined service providers.
Growth Catalysts
- EU AI Act compliance mandates:Functional safety requirements for in-vehicle AI systems are accelerating OEM investment in certified data governance architectures.
- Edge computing deployment:Latency-sensitive applications including predictive maintenance and collision avoidance are driving module installation across commercial vehicle fleets.
- Germany's emissions monitoring pressure:Regulatory enforcement on commercial fleets is expanding telematics deployment to satisfy real-time reporting obligations.
Market Restraints
- Semiconductor supply concentration:Dependence on Taiwan and South Korea for automotive-grade chips creates vulnerability in telematics module production.
- GDPR data localization costs:EU-mandated data residency requirements force redundant cloud infrastructure investment, raising operational overhead for cross-border service providers.
- Legacy fleet IT fragmentation:Heterogeneous vehicle ages and proprietary OEM data protocols impede unified platform integration for mixed fleet operators.
Strategic Opportunities
- Usage-based insurance penetration:Underdeveloped markets in Eastern Europe present expansion potential for telematics-linked premium pricing models.
- ISO 26262 certification services:Functional safety consulting for autonomous driving systems represents a high-margin adjacent revenue stream.
- 5G-V2X convergence:Integration of cellular vehicle-to-everything communication with edge analytics enables new traffic management service categories.
Industry Challenges
- Embedded systems cybersecurity talent scarcity:Shortage of engineers with combined automotive and information security expertise delays product development cycles.
- Multi-jurisdiction compliance synchronization:Divergent requirements between EU AI Act, US NHTSA data logging rules, and emerging national standards fragment R&D roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Services Market |
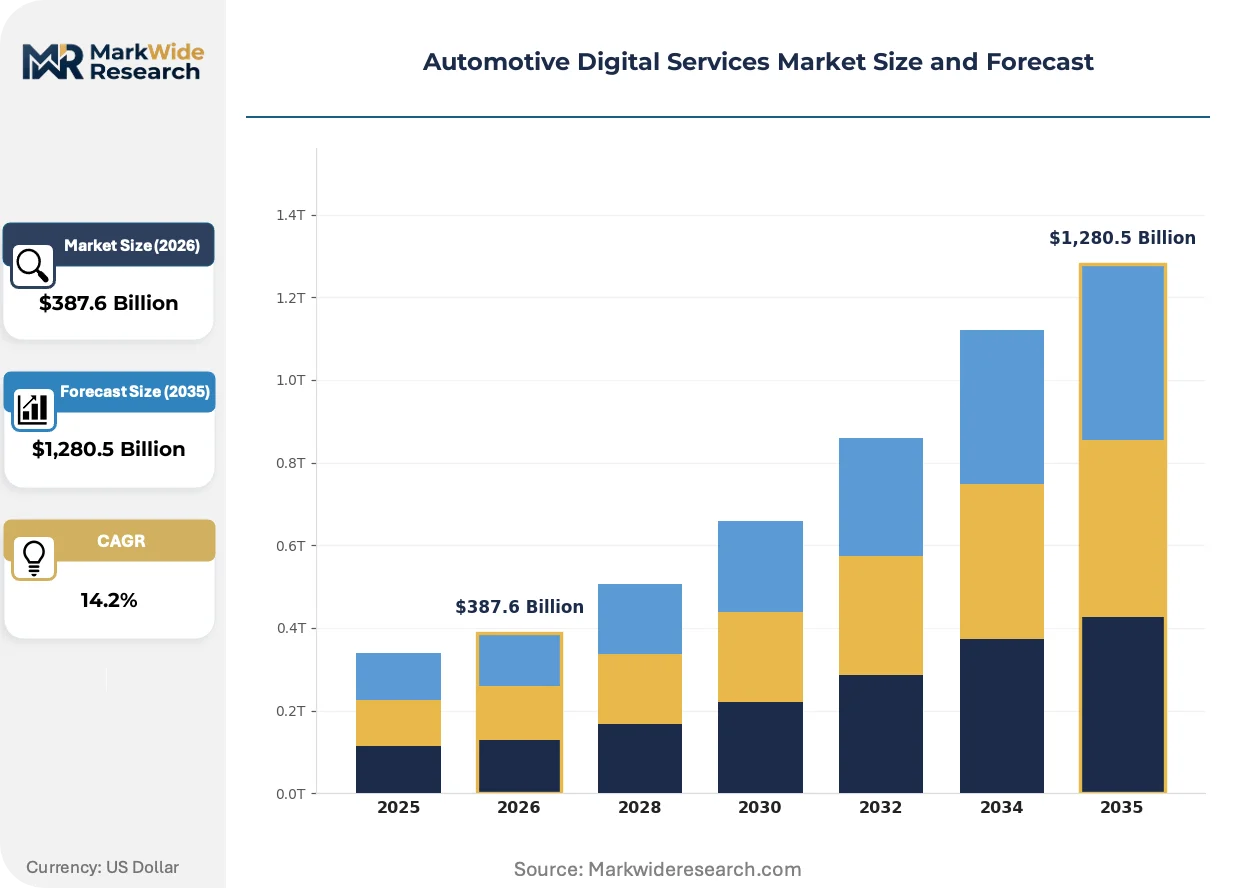
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telematics, Infotainment, Fleet Management, Remote Diagnostics Deployment: Cloud-based, On-premises, Hybrid, Edge Computing End User: OEMs, Dealerships, Fleet Operators, Service Providers Technology: Machine Learning, IoT, Big Data, Mobile Applications |
| Companies Covered | Bosch, Continental, Daimler, Volkswagen, BMW Group, Uber Technologies, Ford, General Motors, TomTom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Services Market Emerging Trajectories
Software-defined vehicle architectures are dissolving traditional hardware-software boundaries, enabling continuous feature deployment and reshaping how automotive value is captured and monetized across the service lifecycle.
Edge computing is hybridizing vehicle data processing by distributing inference workloads between onboard modules and cloud infrastructure. Fleet operators with latency-sensitive routing applications are adopting these architectures fastest. The technology is hybridizing supplier business models, compressing pure hardware margins while expanding recurring software revenue pools.
The EU AI Act's risk-based classification system for automated driving functions is mandating explainability and human oversight protocols. OEMs must now document training data provenance and model decision logic for type approval. This regulatory shift most affects Level 2+ and Level 3 automation systems, forcing German and French engineering clusters to restructure development workflows.
Fleet procurement is consolidating around integrated platform contracts rather than point solutions for telematics, maintenance, and navigation. Large logistics operators are disintermediating traditional dealership service networks in favor of direct OEM digital relationships. This pattern concentrates in Germany's Ruhr industrial corridor, where major freight operators command sufficient scale to dictate API standardization and data ownership terms.
Automotive Digital Services Market Segmentation
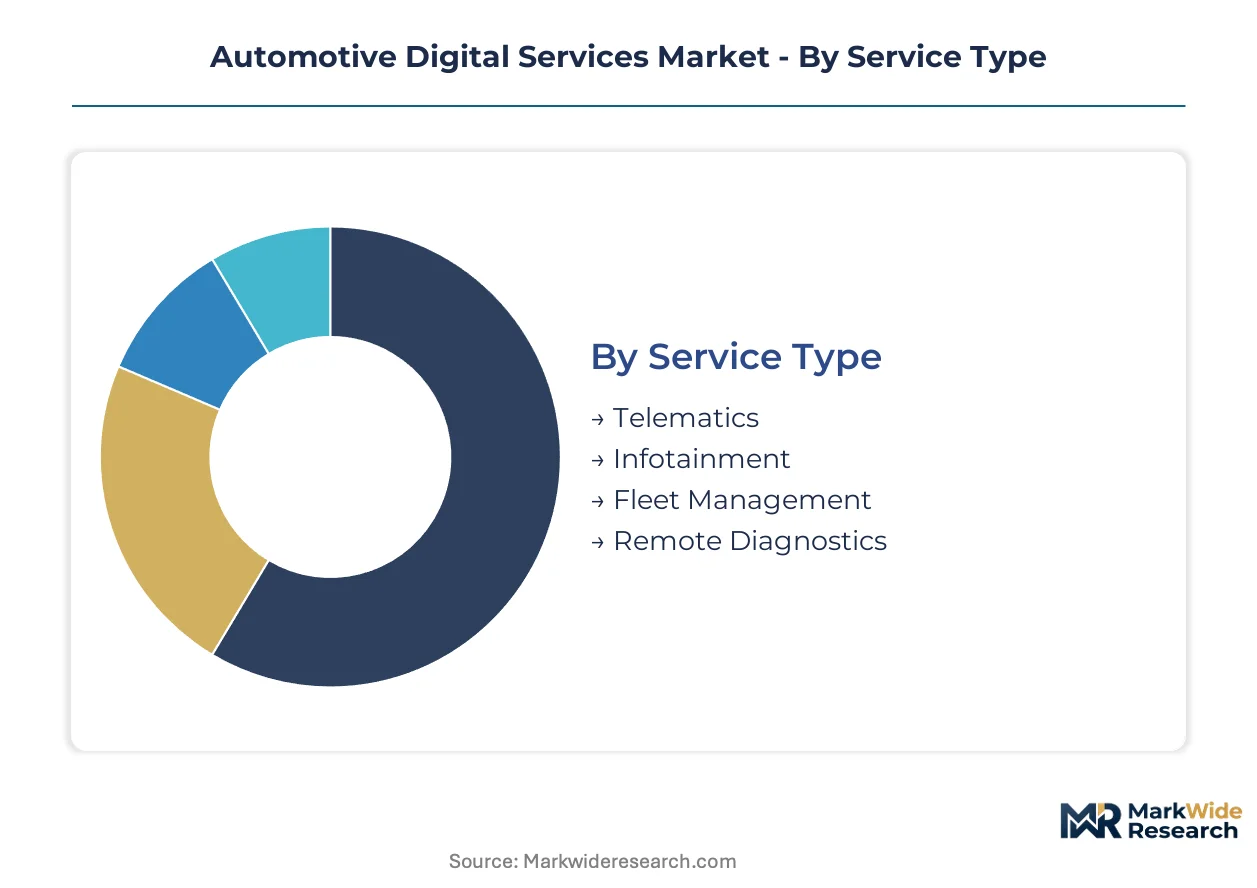
Segmentation reveals how value migrates between hardware-intensive and software-defined service models in automotive digital services. Understanding these divisions exposes where margin compression and expansion occur across the value chain.
Service Type:
After-sales-service intensity varies dramatically across service types, with predictive maintenance models requiring continuous algorithmic refinement versus one-time infotainment deployments.
- Telematics:Real-time vehicle data transmission through cellular and satellite networks enables location tracking, driver behavior monitoring, and emergency response. German commercial fleets under emissions reporting mandates from KBA drive concentrated demand for certified telematics systems. The EU AI Act's data governance requirements are forcing architecture redesigns for cross-border fleet operators.
- Infotainment:In-vehicle entertainment and information systems integrate navigation, media streaming, and voice interfaces through centralized head units. Consumer preference for seamless smartphone integration is displacing proprietary OEM platforms. Revenue concentrates in premium vehicle segments where subscription content services generate recurring income.
- Fleet Management:Integrated platforms combining vehicle tracking, maintenance scheduling, and route optimization for commercial operators.
- Remote Diagnostics:Over-the-air health monitoring and fault prediction systems reducing unplanned vehicle downtime.
By volume, Telematics leads. By growth pace, Fleet Management is ahead.
Deployment:
Cost tier differentiation separates capital-intensive on-premises installations from operational-expense cloud models, with hybrid architectures commanding premium positioning.
- Cloud-based:Centralized data processing through third-party infrastructure enables rapid scaling and reduced upfront investment. GDPR data localization requirements are fragmenting cloud strategies, forcing EU-dedicated infrastructure investments that raise operational overhead for multi-national providers.
- Edge Computing:Distributed processing at the vehicle level reduces latency for collision avoidance and predictive maintenance applications. Commercial fleets with real-time routing optimization needs are adopting these architectures fastest, compressing pure hardware margins while expanding software revenue pools.
- On-premises:Dedicated infrastructure deployment for data-sensitive operators requiring full sovereignty over vehicle information.
- Hybrid:Architectures splitting workloads between vehicle-level processing and cloud aggregation based on latency and security requirements.
By maturity, Cloud-based dominates. By expansion trajectory, Edge Computing is climbing the fastest.
End User:
Customer type determines platform complexity, with integrated fleet operators demanding API standardization that fragmented dealership networks cannot match.
- Fleet Operators:Large-scale commercial vehicle owners integrating real-time data into logistics optimization systems. Germany's Ruhr industrial corridor freight operators command sufficient scale to dictate data ownership terms and disintermediate traditional service networks. Procurement is consolidating around integrated platform contracts rather than point solutions.
- OEMs:Vehicle manufacturers embedding digital services into new vehicle architectures and monetizing through subscription models. Software-defined vehicle strategies are dissolving traditional hardware-software boundaries and enabling continuous feature deployment across the service lifecycle.
- Dealerships:Fragmented legacy IT infrastructure impedes unified platform adoption for service and sales operations.
- Service Providers:Third-party specialists delivering maintenance, insurance, and mobility services through vehicle data access.
By revenue concentration, Fleet Operators capture the largest share. By platform influence, OEMs retain structural control.
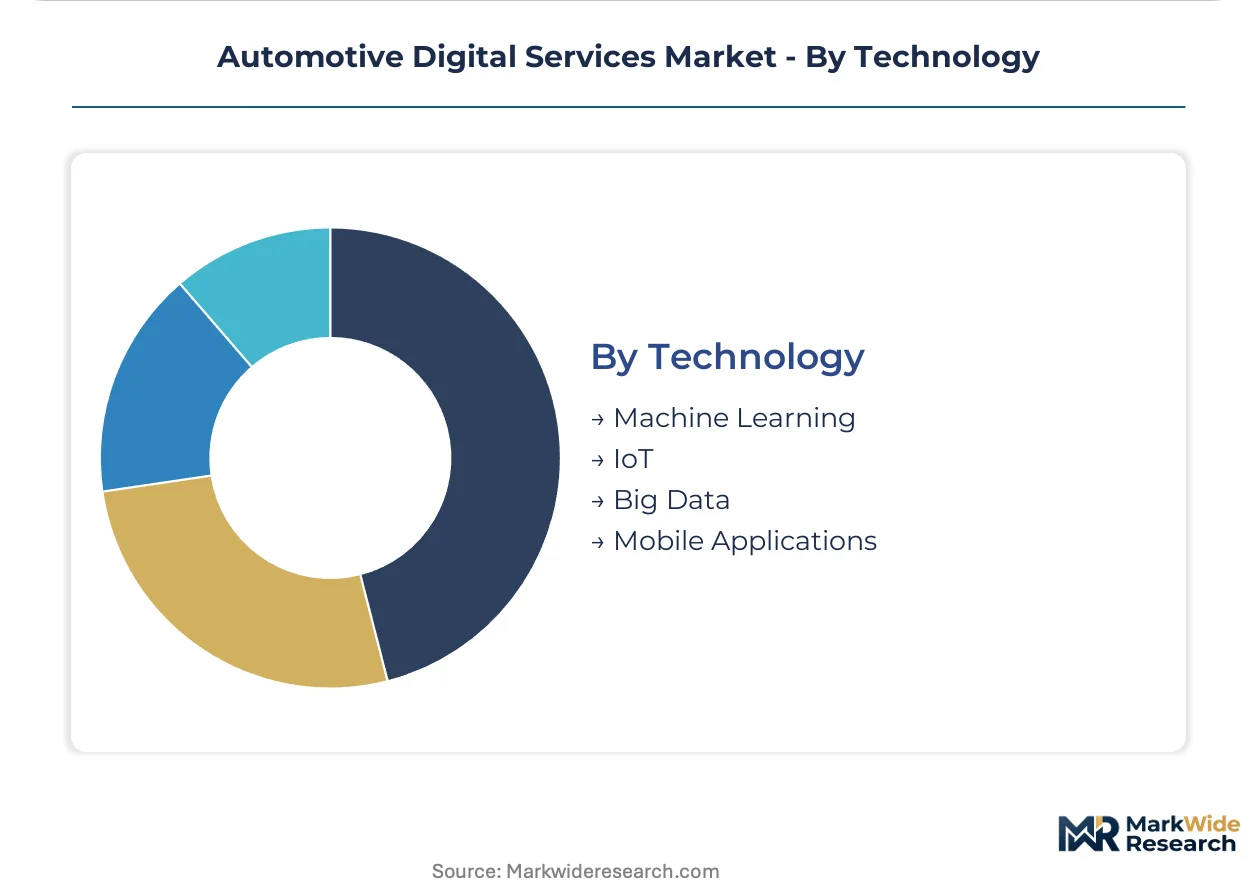
Technology:
Application intensity separates inference-heavy machine learning workloads from connectivity-focused IoT deployments, with talent scarcity constraining advanced analytics adoption.
- Machine Learning:Predictive algorithms processing vehicle sensor data for maintenance forecasting and autonomous driving functions. The EU AI Act's risk-based classification mandates explainability protocols and training data provenance documentation, restructuring development workflows for German and French engineering clusters.
- IoT:Networked sensors and communication modules enabling vehicle-to-infrastructure and vehicle-to-vehicle connectivity. 5G-V2X convergence with edge analytics is enabling new traffic management service categories for municipal and highway operators.
- Big Data:Aggregation and analysis of fleet-scale vehicle information for pattern recognition and operational optimization.
- Mobile Applications:Driver-facing interfaces for service access, vehicle control, and data visualization on personal devices.
By implementation breadth, IoT leads. By capability premium, Machine Learning commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in automotive digital services favor net exporters with embedded sensor manufacturing depth over service-importing markets dependent on foreign telematics platforms. Capital flows concentrate where regulatory harmonization reduces cross-border data friction.
Germany
Commercial fleet operators in the Ruhr industrial corridor drive concentrated demand for emissions-compliant telematics systems under KBA enforcement mandates. The EU AI Act forces OEMs to restructure data governance architectures for cross-border fleet operations. Engineering clusters in Stuttgart and Munich anchor development of certified edge-computing modules for predictive maintenance applications.
United States
NHTSA data logging requirements and EPA emissions reporting rules shape platform architecture decisions for connected vehicle fleets. The IRA's commercial vehicle electrification incentives accelerate telematics deployment for battery monitoring and charging optimization. Detroit's automotive engineering base and Silicon Valley's software talent pools split development activity between hardware-integrated and cloud-native service models.
China
MIIT's connected vehicle data security regulations mandate localized data processing infrastructure for foreign-operated fleets. Dual carbon goals and GB standards for intelligent transportation accelerate domestic telematics module production. The Yangtze River Delta manufacturing corridor concentrates edge-computing hardware output for both domestic consumption and export assembly.
Japan
METI's Society 5.0 initiative funds V2X communication infrastructure deployment for automated logistics corridors. JIS standards for vehicle data interoperability reduce integration costs for mixed-fleet operators. The Nagoya-Tokyo industrial belt hosts concentrated R&D activity in sensor fusion and predictive algorithms for commercial vehicle applications.
India
PLI scheme incentives for automotive electronics manufacturing attract telematics module assembly investments from multinational suppliers. BIS certification requirements for connected vehicle components create compliance barriers for unstandardized imports. Tamil Nadu and Maharashtra's automotive clusters emerge as export-oriented production bases for ASEAN-bound digital service hardware.
Automotive Digital Services Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor modules and communication hardware. Market structure tilts toward consolidated OEM-controlled ecosystems in premium segments while fragmenting across aftermarket service providers. Three archetypes dominate: embedded hardware suppliers with sensor manufacturing depth, software-defined platform operators monetizing recurring data services, and fleet-facing integrators consolidating point solutions into unified contracts. Competitive moves center on strategic partnerships bridging hardware-software boundaries and geographic expansion into underpenetrated Eastern European insurance-linked telematics markets.
Within the embedded hardware tier, Bosch and Continental anchor supplier positions through manufacturing scale and certification depth. Ford occupies a distinct platform-integrator position via proprietary fleet management software tied to commercial vehicle lines. These three exemplify how competitive viability now depends on spanning the hardware-software boundary rather than defending pure-component margins.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Daimler |
| Volkswagen |
| BMW Group |
| Uber Technologies |
| Ford |
| General Motors |
| TomTom |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwanese automotive-grade semiconductor foundries is compressing module supplier margins while forcing tier-one telematics vendors toward software-centric pricing models. Fleet operators exploit this buyer's market to demand extended payment terms and API standardization guarantees.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across telematics platforms. Pricing stratifies across premium-certified, standard-compliant, and economy-unbundled tiers based on ISO 26262 certification depth and data sovereignty architecture. Cost compression in hardware modules is intensifying because edge-computing commoditization erodes sensor-margin premiums. Small fleet operators exhibit acute price sensitivity, whereas integrated logistics platforms prioritize interoperability over unit cost.
Supply Chain Analysis
Extended payment terms from German OEMs now stretch to 120 days, forcing tier-two suppliers into supply-chain finance facilities. Manufacturing concentrates in Taiwan, South Korea, and China's Yangtze River Delta for automotive-grade chips and communication modules. Production rests on silicon wafers, rare-earth magnets for sensors, and specialized automotive resins. Single-source vulnerability around EUV lithography equipment creates systemic exposure. Distribution runs through OEM captive channels, aftermarket distributors, and direct fleet procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive digital services are crossing a platform-economics inflection as API standardization dissolves proprietary OEM data silos. The shift toward software-defined vehicle architectures restructures value capture from hardware lifecycle to recurring service monetization.
For Market Incumbents: Entrench control over edge-computing module certification to defend against cloud-native platform entrants. Deepen backward integration into sensor manufacturing to secure supply continuity amid Taiwan semiconductor concentration. Prioritize ISO 26262 consulting capabilities as regulatory complexity escalates under EU AI Act enforcement. For New Entrants and Emerging Players: Establish a beachhead in Eastern European usage-based insurance telematics where regulatory frameworks remain underdeveloped. Target mid-sized commercial fleets with hybrid edge-cloud architectures that incumbent hardware suppliers underserve. Lead with 5G-V2X integration expertise to differentiate from legacy cellular platform vendors. For Investors and Strategic Acquirers: Long-term, this sits as a data-sovereignty infrastructure play because GDPR localization mandates and cross-border fleet operations create durable demand for compliant platform operators. Acquisition targets should display embedded systems cybersecurity talent depth and multi-jurisdiction certification track records. Monitor EU AI Act enforcement patterns as the signal for regulatory-complexity premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables continuous feature deployment and recurring revenue capture across vehicle lifecycles. |
| Edge-Computing Module Certification | Secures regulatory compliance positioning under EU AI Act functional safety requirements. |
| 5G-V2X Infrastructure Partnership | Unlocks traffic management service categories for municipal and highway operators. |
| GDPR-Compliant Cloud Architecture | Reduces operational overhead for cross-border fleet operators facing data localization mandates. |
| Predictive Maintenance Algorithm Development | Captures high-margin aftermarket service contracts from commercial fleet operators. |
Methodological Framework
Operator-level perspectives from fleet procurement directors, OEM platform engineers, Tier 1 supplier strategy leads, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings, IHS Markit vehicle registration databases, EU regulatory filings, and automotive production statistics. Bottom-up service-type modeling and top-down macroeconomic triangulation cross-checked volume and value estimates.
Scenario-bracketing around semiconductor supply disruption and regulatory enforcement intensity bounded the projection range across the analysis window. Segmentation dimensions included service type, deployment architecture, end-user category, and technology stack. CAGRs derived from fitted growth curves adjusted for adoption S-cycles and replacement dynamics. Forecast inputs incorporated fleet electrification timelines and 5G-V2X infrastructure deployment schedules.
Sensitivities concentrate around EU AI Act implementation timing, Taiwan semiconductor supply continuity, and fleet operator consolidation patterns. Forecasts reflect documented assumptions about technology adoption rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Vehicle Conversion Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Car Wash System Market
Automotive Services
Automotive Retail Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
US Car Wash Services Market
Automotive Services
Automotive Register Market
Automotive Services
Car Washing Service Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Cab Services Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Armored Transportation Services Market