
 Vehicle Roadside Assistance Market | 2026-2036
Vehicle Roadside Assistance Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Roadside Assistance Market Intelligence
The digital dispatch channel is reshaping how roadside assistance reaches stranded motorists. AAA leverages its century-old membership infrastructure to sustain recurring revenue across North America. Agero, Inc. competes through proprietary automated dispatch algorithms that compress response windows. Allianz Global Assistance anchors European market penetration via insurance bundling partnerships with major underwriters.
Vehicle roadside assistance encompasses emergency mechanical and logistical support delivered to immobilized vehicles, typically incorporating GPS triangulation below three-meter accuracy and mobile-app-triggered service requests to achieve sub-thirty-minute average response times. Its primary commercial purpose is reducing driver downtime and liability exposure for fleet operators and insurers. Towing and battery jump start services dominate transaction volume, while automated dispatch technology captures expanding margin pools through software licensing and data monetization. Fleet operators represent the fastest-growing end user segment as logistics companies internalize total cost of ownership calculations.
NHTSA in the United States, Germany's KBA, and Japan's METI each enforce vehicle safety and telematics standards that directly shape roadside assistance platform requirements and data handling protocols. These regulators mandate emergency response capabilities and connected vehicle communications that expand addressable market scope for technology-enabled providers. Stakeholders must monitor evolving data privacy frameworks and telematics certification standards to maintain platform compliance and service eligibility across jurisdictions.
Market Dynamics
Fleet operators now treat roadside assistance as embedded operational infrastructure rather than discretionary insurance add-on, compressing procurement cycles and forcing providers to integrate telematics APIs directly into logistics management platforms.
Growth Catalysts
- NHTSA Connected Vehicle Mandate:Emergency communication requirements in the United States are compelling automakers to pre-install eCall-compatible systems, expanding the addressable base for technology-enabled dispatch services.
- Total Cost of Ownership Analytics:Logistics companies are internalizing downtime cost models that quantify stranded-vehicle losses, converting historically reactive fleet managers into proactive assistance contract purchasers.
- Telematics-Insurance Bundling:Usage-based insurance frameworks in Germany are creating structural pull for integrated roadside assistance as a policy differentiator among underwriters.
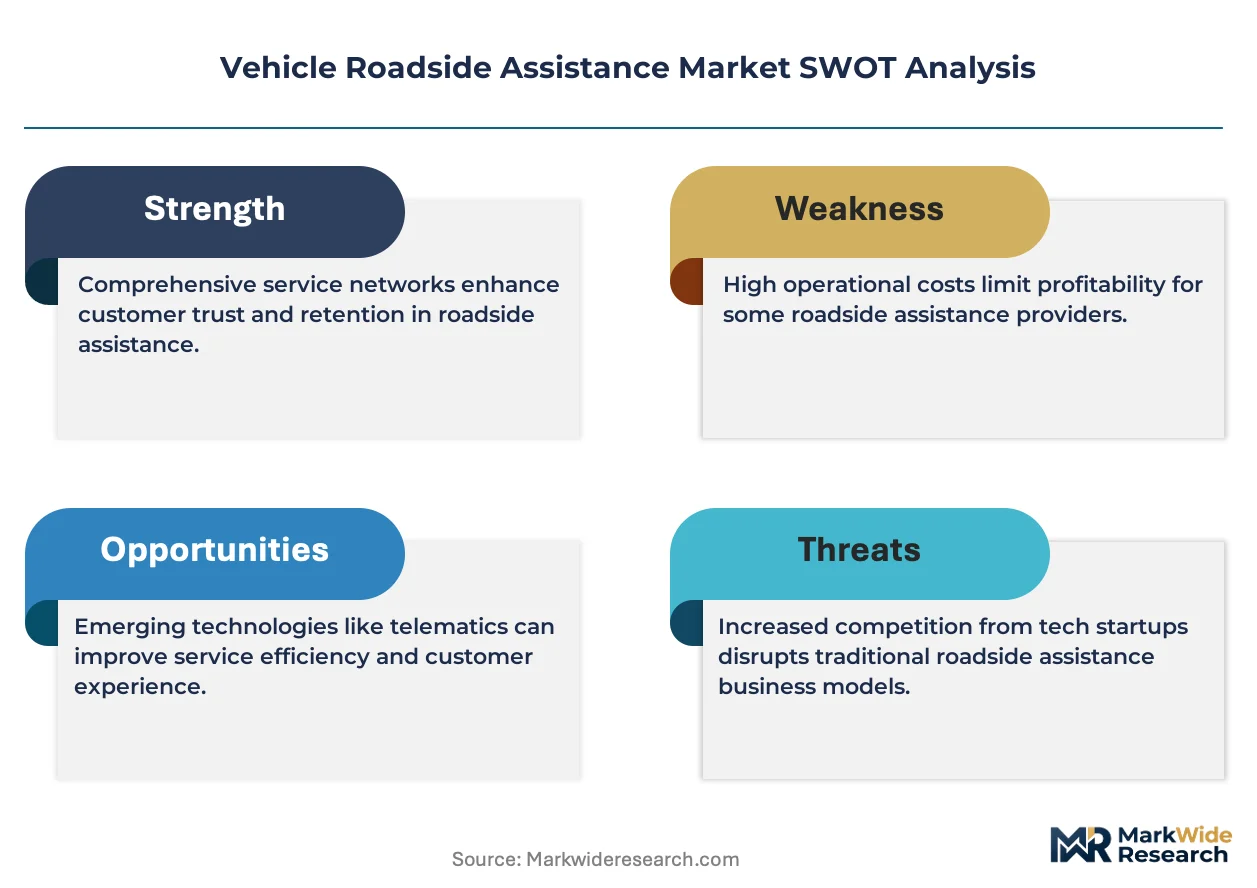
Market Restraints
- Skilled Technician Scarcity:EV high-voltage certification requirements are constraining qualified responder availability in rural United States counties where training infrastructure remains underdeveloped.
- Dispatch Platform Concentration:Proprietary algorithms from dominant software vendors are creating vendor lock-in that elevates switching costs for mid-sized assistance networks.
- Cellular Coverage Gaps:Remote highway corridors in western China and the Australian Outback limit GPS triangulation reliability below the three-meter threshold required for automated dispatch.
Strategic Opportunities
- India Fleet Formalization:Commercial vehicle aggregation platforms in Maharashtra and Gujarat are creating concentrated demand pools previously served by fragmented informal tow networks.
- Vehicle-to-Grid Integration:Bidirectional charging infrastructure convergence with roadside assistance is enabling mobile power delivery as a premium service tier for stranded EVs.
- GDPR-Aligned Data Monetization:European breakdown pattern datasets, anonymized under EU privacy frameworks, are becoming licensable inputs for predictive maintenance AI developers.
Industry Challenges
- Legacy Fleet Management Integration:SAP and Oracle ERP systems at major logistics operators require custom API development that extends deployment timelines.
- Responder Certification Lags:EV battery thermal runaway protocols are outpacing regional training curriculum updates, creating liability exposure during high-voltage extrication events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Roadside Assistance Market |
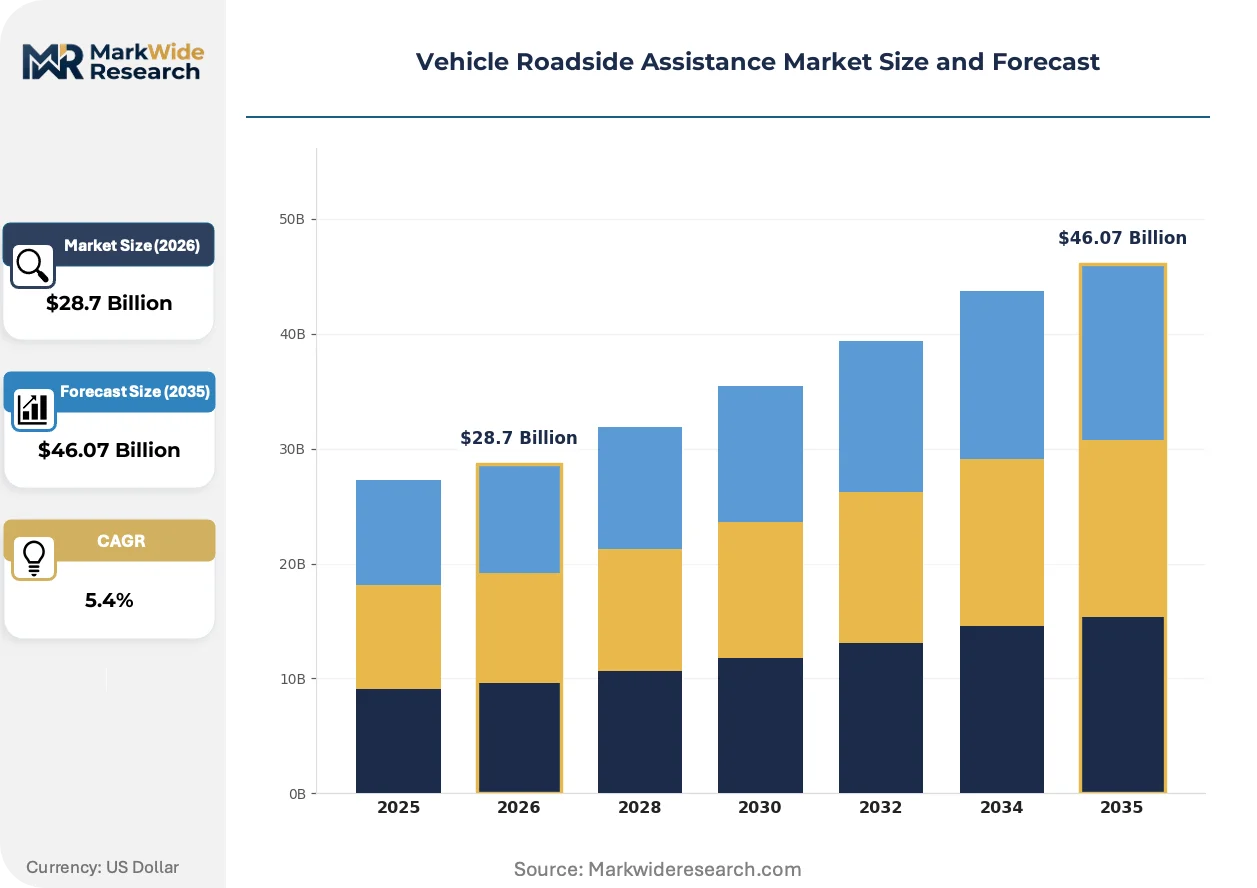
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Towing, Tire Change, Battery Jump Start, Fuel Delivery End User: Individual Drivers, Fleet Operators, Rental Companies, Motorcycle Owners Technology: GPS Tracking, Mobile Apps, Automated Dispatch, Onboard Diagnostics Subscription Model: Pay-Per-Use, Monthly Subscription, Annual Membership, Bundled Services |
| Companies Covered | Good Sam Enterprise, LLC, Paragon Motor Club, AAA, Better World Club, National General Insurance, Allstate Insurance Company, Best Roadside Service, Allianz Global Assistance, Agero, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Roadside Assistance Market Strategic Shifts & Innovations
Dispatch infrastructure is migrating from human-staffed call centers to API-driven orchestration layers that ingest vehicle telemetry directly, compressing request-to-dispatch intervals and eliminating voice-channel bottlenecks during peak incident windows.
Cloud-native dispatch platforms are virtualizing the entire assistance coordination workflow. Tier-1 fleet operators in Germany and the United States are deploying these systems across 80% of new contract acquisitions. This virtualization is collapsing the traditional dispatcher-to-tow-truck hierarchy into algorithmic matching that optimizes for proximity, equipment compatibility, and real-time traffic conditions.
Japan's METI has issued connected vehicle data governance guidelines that mandate encrypted transmission standards for emergency service handshakes. Automakers serving the Japanese domestic market must now certify telematics modules against these protocols to maintain type approval. Tier-2 assistance providers lacking cybersecurity certification infrastructure are exiting the market or partnering with compliant technology vendors.
Fleet procurement departments are consolidating vendor relationships under master service agreements that bundle roadside assistance with telematics hardware and predictive maintenance subscriptions. Third-party assistance brokers in North America are losing share to direct OEM and insurer channels that capture the full vehicle lifecycle revenue stream. This concentration is most pronounced among logistics operators with 500-plus vehicle fleets in the United States and Germany.
Vehicle Roadside Assistance Market Segmentation
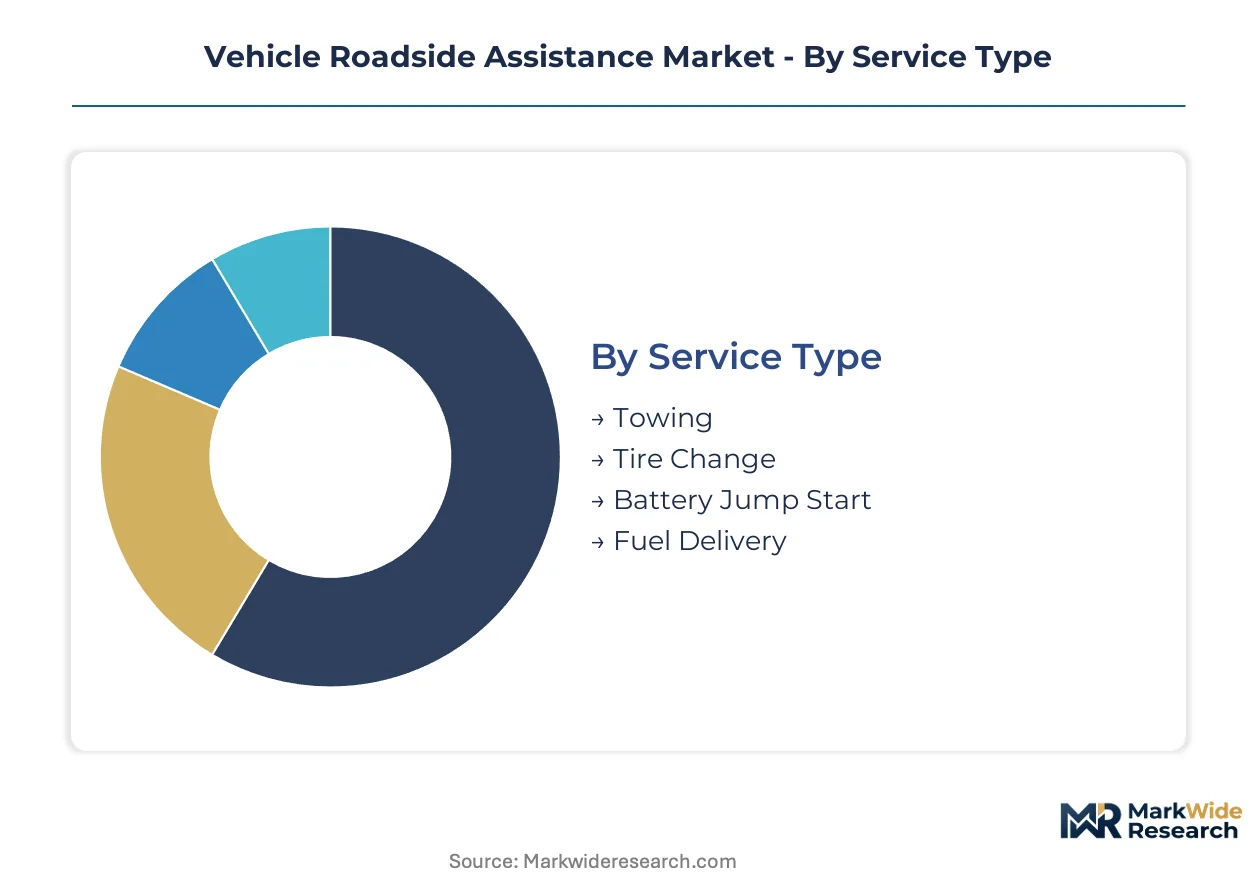
Roadside assistance providers structure their portfolios around four distinct dimensions that shape pricing architecture, technology deployment, and customer acquisition economics. Service type determines equipment and labor specialization. End user segmentation drives contract terms and response-time guarantees. Technology integration separates legacy call-center operators from platform-native competitors. Subscription model selection reflects regional insurance penetration and consumer payment preferences.
Service Type:
Cost tier stratification separates commodity mechanical interventions from specialized recovery operations requiring certified equipment and trained responders.
- Towing:Flatbed and wheel-lift configurations handle vehicle recovery across mechanical failure, collision damage, and impound scenarios. Demand concentrates among fleet operators in Germany and the United States where liability protocols mandate documented chain-of-custody during transport. Insurance bundling in these markets converts towing from discretionary purchase to embedded coverage.
- Battery Jump Start:Portable lithium booster packs and traditional jumper cable services address the dominant failure mode in temperate climates. Cold-weather states in the US Northeast and Scandinavian markets generate seasonal volume spikes that strain responder availability during winter storm windows.
- Tire Change:Spare tire installation and temporary repair services target puncture and blowout incidents. Run-flat tire penetration in premium vehicle segments is compressing addressable volume in Western European markets.
- Fuel Delivery:Emergency gasoline and diesel supply resolves out-of-fuel immobilizations, primarily serving individual drivers in rural corridor markets where station density falls below metropolitan thresholds.
Towing commands the established base. The steepest expansion runs through battery jump start as EV adoption multiplies low-charge incidents requiring mobile power delivery.
End User:
Customer type segmentation separates transactional individual relationships from enterprise contracts with negotiated service-level agreements and telematics integration requirements.
- Fleet Operators:Logistics companies and commercial vehicle aggregators procure roadside assistance as operational infrastructure tied to total cost of ownership analytics. Contracts specify maximum allowable downtime per incident and direct API integration with fleet management platforms. Demand is concentrating in the United States and Germany where 500-plus vehicle fleets are consolidating vendor relationships under master service agreements.
- Individual Drivers:Private vehicle owners access assistance through auto club memberships, insurer add-ons, or pay-per-use arrangements. AAA's century-old membership infrastructure sustains recurring revenue across North America through annual renewal cycles.
- Rental Companies:Vehicle rental fleets require coverage that travels with the vehicle regardless of driver identity, creating demand for transferable service entitlements. Airport-centric operations in the United States and Germany generate concentrated incident volume from unfamiliar-driver error patterns.
- Motorcycle Owners:Two-wheel assistance requires specialized flatbed equipment and responder training for secure transport. Demand clusters in Mediterranean markets and coastal US states where motorcycle tourism creates seasonal exposure.
Individual drivers command the established base. Fleet operators are gaining share fastest as logistics companies internalize downtime cost models.
Technology:
Application maturity separates legacy voice-channel dispatch from telemetry-native platforms that compress request-to-responder intervals.
- Automated Dispatch:Algorithmic orchestration layers ingest vehicle telemetry and traffic data to match incidents with optimal responder resources. Cloud-native deployments in Germany and the United States are capturing 80% of new fleet contract acquisitions by eliminating human dispatcher bottlenecks.
- Mobile Apps:Smartphone-triggered service requests with photo documentation and GPS coordinates are displacing voice calls among younger driver demographics. NHTSA connected vehicle mandates are accelerating pre-installation of eCall-compatible systems that feed directly into these platforms.
- GPS Tracking:Sub-three-meter accuracy triangulation enables precise responder routing and arrival time prediction. Coverage gaps in western China and remote Australian corridors limit reliability below automated dispatch thresholds.
- Onboard Diagnostics:Direct vehicle system integration enables predictive failure alerts and automatic incident detection. METI guidelines in Japan mandate encrypted transmission standards that shape platform compliance requirements.
GPS tracking commands the established base. Automated dispatch is climbing the fastest as tier-1 fleet operators virtualize coordination workflows.
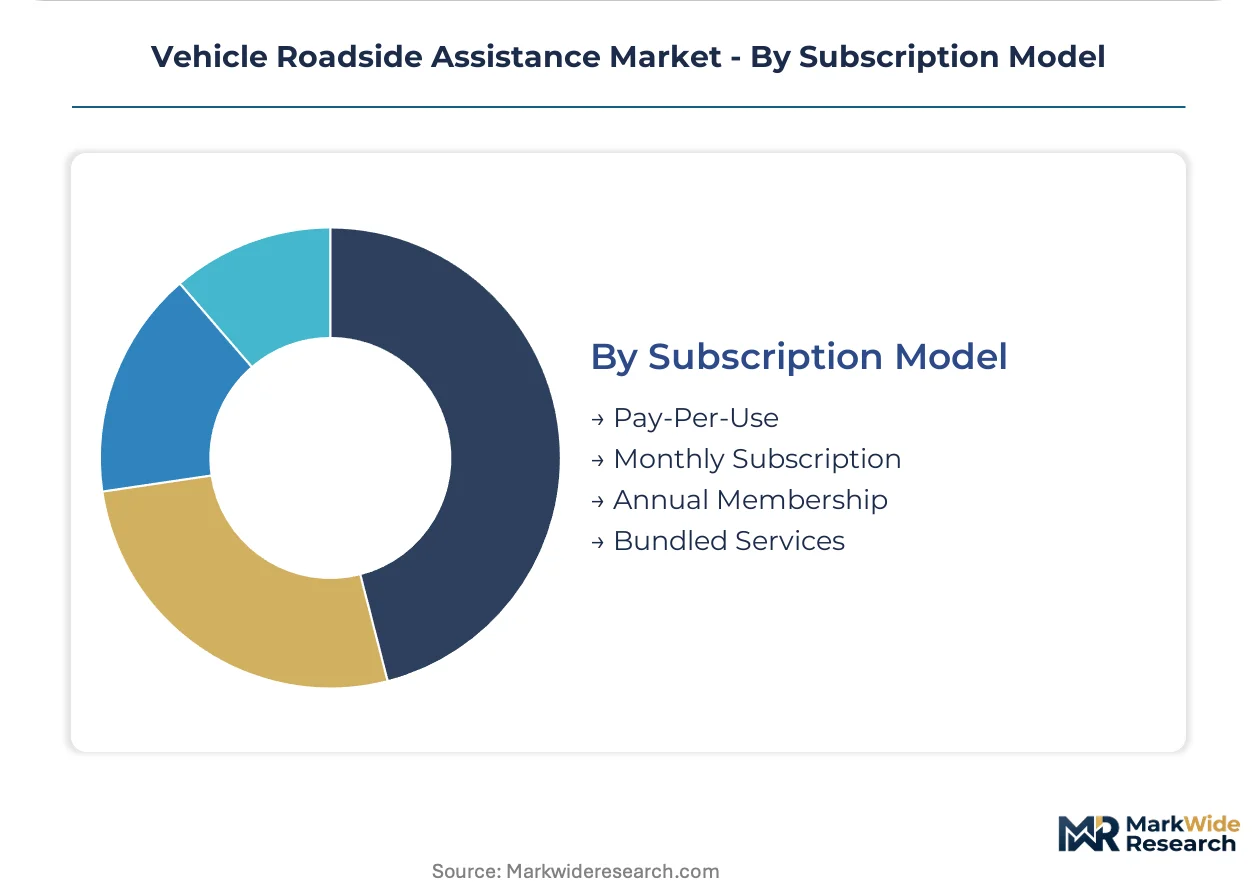
Subscription Model:
Payment structure reflects regional insurance market development and consumer willingness to pre-commit versus transact at point of need.
- Annual Membership:Prepaid entitlements with unlimited service calls dominate in markets with mature auto club infrastructure. AAA's North American membership base demonstrates the recurring revenue stability of this model.
- Bundled Services:Insurance policy integration packages roadside assistance with comprehensive coverage, prevalent in Germany where usage-based frameworks create structural pull for assistance as a policy differentiator.
- Monthly Subscription:Flexible recurring payments target gig economy drivers and seasonal vehicle owners seeking commitment minimization.
- Pay-Per-Use:Transactional pricing serves unbanked populations and infrequent drivers in emerging markets where formal insurance penetration remains limited.
Annual membership commands the established base. Bundled services are expanding most quickly as insurers capture full vehicle lifecycle revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System underwrites United States market leadership, enabling sub-thirty-minute response time guarantees across dense vehicle corridors. NHTSA connected vehicle mandates and insurance bundling penetration create structural demand pull.
United States
Fleet operators with 500-plus vehicle counts drive enterprise contract growth, internalizing downtime cost models as core procurement criteria. NHTSA mandates eCall-compatible telematics installation, expanding technology-enabled dispatch addressability. Texas and California logistics clusters concentrate demand where API integration with fleet management platforms dominates new acquisitions.
Germany
Usage-based insurance frameworks generate structural pull for assistance bundling as policy differentiators among underwriters. KBA enforces connected vehicle data standards that shape platform compliance requirements. Bavaria and Baden-Württemberg automotive manufacturing corridors anchor European technology development for automated dispatch systems.
China
Commercial vehicle aggregation platforms in eastern provinces create concentrated demand pools previously served by fragmented informal networks. MIIT issues telematics certification standards for connected vehicle emergency communications. Yangtze River Delta logistics hubs deploy cloud-native dispatch infrastructure across expanding fleet operator contracts.
Japan
Domestic automakers integrate emergency response capabilities as type approval requirements under METI connected vehicle guidelines. Encrypted transmission standards for emergency service handshakes reshape platform cybersecurity certification. Kanto and Kansai manufacturing clusters drive telematics module development for export-compatible systems.
India
Fleet formalization in Maharashtra and Gujarat generates enterprise-grade demand from commercial vehicle aggregation platforms. Central transport authorities mandate GPS tracking for commercial fleets, expanding addressable market scope. Delhi-NCR and Bengaluru technology corridors incubate mobile-app dispatch startups targeting informal tow network displacement.
Vehicle Roadside Assistance Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in equipment and responder certification. The vendor base stratifies between membership-based auto clubs, insurer-embedded assistance networks, and technology-native dispatch platforms. Three archetypes dominate: legacy membership organizations with century-old recurring revenue infrastructure, insurer-affiliated assistance networks leveraging policy bundling, and algorithmic dispatch platforms monetizing software licensing. Competitive moves concentrate on telematics API integration and master service agreement consolidation with tier-1 fleet operators.
Among North American membership organizations, AAA exemplifies recurring revenue stability through annual renewal cycles. Agero, Inc. occupies a position within the algorithmic dispatch tier, while Allianz Global Assistance anchors European insurer-affiliated assistance networks.
| Leading Market Players |
|---|
| Good Sam Enterprise, LLC |
| Paragon Motor Club |
| AAA |
| Better World Club |
| National General Insurance |
| Allstate Insurance Company |
| Best Roadside Service |
| Allianz Global Assistance |
| Agero, Inc. |
| Others |
Cost & Logistics Intelligence
Telematics software licensing concentrates in Germany and the United States, anchoring margin pools in algorithmic dispatch platforms rather than commodity towing services. Fleet operators with 500-plus vehicle counts leverage master service agreements to extract volume discounts that compress responder network margins.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet contracts from individual membership arrangements. Three-tier pricing structure across premium, standard, and economy levels differentiates by response-time guarantees and telematics integration depth. Price differentiation rests on certification grade and geographic coverage density. Cost compression in the economy tier is intensifying because informal tow networks in emerging markets undercut formal provider rates. Individual drivers show highest price sensitivity, while logistics operators prioritize uptime guarantees over per-incident cost.
Supply Chain Analysis
Upstream feedstock for dispatch platforms draws from cloud infrastructure providers and GPS chipset manufacturers concentrated in the United States, Taiwan, and South Korea. Lithium-ion booster packs, flatbed chassis components, and encrypted telematics modules constitute critical inputs. Single-source vulnerability sits with proprietary algorithm vendors whose APIs create switching costs for mid-sized assistance networks. Distribution runs through direct OEM partnerships, insurer-embedded channels, and third-party assistance brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around connected vehicle mandates creates durable barriers to unlicensed competitors.
For Market Incumbents: Build switching-cost moats through deeper telematics API integration with SAP and Oracle ERP systems at major logistics operators. Incumbents should secure master service agreements with 500-plus vehicle fleets before cloud-native dispatch platforms achieve critical mass. Threat from algorithmic dispatch vendors elevates urgency around responder certification infrastructure for EV high-voltage protocols. For New Entrants and Emerging Players: Establish a beachhead in India's commercial vehicle aggregation platforms across Maharashtra and Gujarat, where fleet formalization displaces fragmented informal tow networks. White-space opportunity concentrates in mobile power delivery for stranded EVs via vehicle-to-grid integration. Go-to-market should emphasize GDPR-aligned data monetization partnerships with predictive maintenance AI developers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed auto club membership organizations facing technology displacement from platform-native competitors. Long-term viability hinges on successful ERP integration and cybersecurity certification against METI guidelines. Acquisition targets should demonstrate established responder networks with EV thermal runaway training. Watch for NHTSA mandate expansion into heavy-duty commercial vehicles as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics API Integration | Direct ERP connectivity with SAP and Oracle systems compresses procurement cycles for tier-1 fleet operators. |
| EV Responder Certification Program | NHTSA-aligned high-voltage training addresses liability exposure during battery thermal runaway extrication events. |
| Cloud-Native Dispatch Platform | Algorithmic orchestration eliminates human dispatcher bottlenecks during peak incident windows across Germany and the United States. |
| GDP-Aligned Data Monetization | Anonymized European breakdown pattern datasets generate licensable revenue streams for predictive maintenance AI developers. |
| Master Service Agreement Consolidation | Bundle roadside assistance with telematics hardware and predictive maintenance subscriptions to capture full vehicle lifecycle revenue. |
Research Approach
Desk research of SEC filings, customs records, and NHTSA regulatory databases preceded structured interviews with fleet operations directors, telematics platform engineers, insurer product managers, and roadside assistance network coordinators. Primary fieldwork combined with secondary validation from vehicle production databases and IHS Markit registration data. Bottom-up responder network sizing triangulated against top-down fleet operator contract value estimates.
Assumptions held fixed include NHTSA connected vehicle mandate enforcement timelines and current EV penetration trajectories, while fuel price volatility and cellular coverage expansion rates were varied across sensitivity scenarios. Segmentation modeling spanned service type, end user archetype, technology integration level, and subscription model across the projection horizon. CAGRs derived from logistic adoption curves fitted to telematics installation rates and fleet operator procurement cycle data.
Sensitivities concentrate around NHTSA mandate expansion scope, EV responder certification curriculum rollout speed, and informal tow network displacement rates in emerging markets. Forecasts embed assumptions about regulatory compliance maintenance and cybersecurity certification infrastructure availability. Cross-checking against commercial vehicle registration data and insurer policy bundling disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
GCC Car Wash Market
Automotive Services
Automotive Retail Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Mobility Scooters Market
Automotive Services
Car Wash System Market
Automotive Services
France Car Rental Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Malaysia Car Wash Service Market