
 Mobile Car Wash Service Market | 2026-2036
Mobile Car Wash Service Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Car Wash Service Market Analytics
Biodegradable surfactant chemistry is consolidating around plant-derived foaming agents that cut discharge costs versus petroleum-based predecessors. Washe leverages its app-based dispatch density to sustain route efficiency across metropolitan zones. DetailXPerts anchors its franchise model on steam-based cleaning that eliminates runoff permitting hurdles. Spiffy competes through controlled fleet partnerships with corporate park operators, while GreenSteam differentiates via proprietary waterless formulations.
Mobile car wash service denotes on-demand vehicle cleaning performed at customer locations using self-contained equipment, typically employing pressure systems operating between 1,200 and 3,000 PSI alongside portable water tanks and reclamation units. The primary commercial purpose centers on eliminating fixed-site infrastructure while reducing customer time expenditure and water consumption versus tunnel wash alternatives. Exterior cleaning and interior detailing represent the dominant revenue pair, with exterior work commanding higher frequency and interior detailing capturing superior per-visit margins. Fleet managers constitute the fastest-expanding customer type as centralized billing and scheduled rotation programs replace ad hoc individual bookings.
The EPA enforces Clean Water Act discharge standards that constrain graywater release from mobile operations, while OSHA mandates chemical handling protocols for concentrated detergents used in confined van spaces. California's State Water Resources Control Board imposes supplemental permitting for mobile wash operators in drought-designated zones, directly shaping equipment investment requirements. Stakeholders must monitor how municipal franchise ordinances and evolving water-rights allocations reshape territorial licensing economics.
Market Dynamics
Water reclamation mandates from the EPA and state-level environmental agencies are compressing capital deployment timelines, forcing operators toward closed-loop wash systems that eliminate discharge permitting exposure.
Growth Catalysts
- Fleet centralization:Corporate vehicle managers are consolidating vendor relationships under scheduled rotation programs that replace fragmented individual bookings with predictable recurring revenue.
- California State Water Resources Control Board drought permitting:Supplemental water-use restrictions in designated zones are accelerating equipment upgrade cycles among incumbent operators.
- Steam-based cleaning chemistry:Thermal sanitization methods eliminate graywater generation entirely, removing regulatory friction for operators in water-stressed municipalities.
Market Restraints
- Van-mounted equipment capex:Self-contained pressure systems, portable tanks, and reclamation units require upfront investment that barriers entry for independent operators.
- Texas municipal franchise ordinances:Territorial licensing requirements in high-density suburban corridors limit route density expansion for new market entrants.
- Tunnel wash substitution:Fixed-site automated alternatives retain cost advantages for price-sensitive consumers in non-drought regions with abundant water supply.
Strategic Opportunities
- Florida suburban corridor penetration:Vehicle density in exurban zones around Orlando and Tampa remains underserved by scheduled mobile detailing relative to customer willingness to pay.
- OSHA chemical handling protocol convergence:Standardized safety training frameworks reduce compliance friction for multi-state operators expanding across jurisdictions.
- App-based dispatch and route optimization:Real-time scheduling algorithms paired with customer location data compress deadhead miles and improve technician utilization rates.
Industry Challenges
- Technician certification timelines:OSHA-mandated chemical handling credentials and equipment operation licenses create onboarding bottlenecks during seasonal demand spikes.
- Reclamation unit maintenance complexity:Closed-loop filtration systems require specialized servicing knowledge that concentrates repair capacity among limited regional providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Car Wash Service Market |
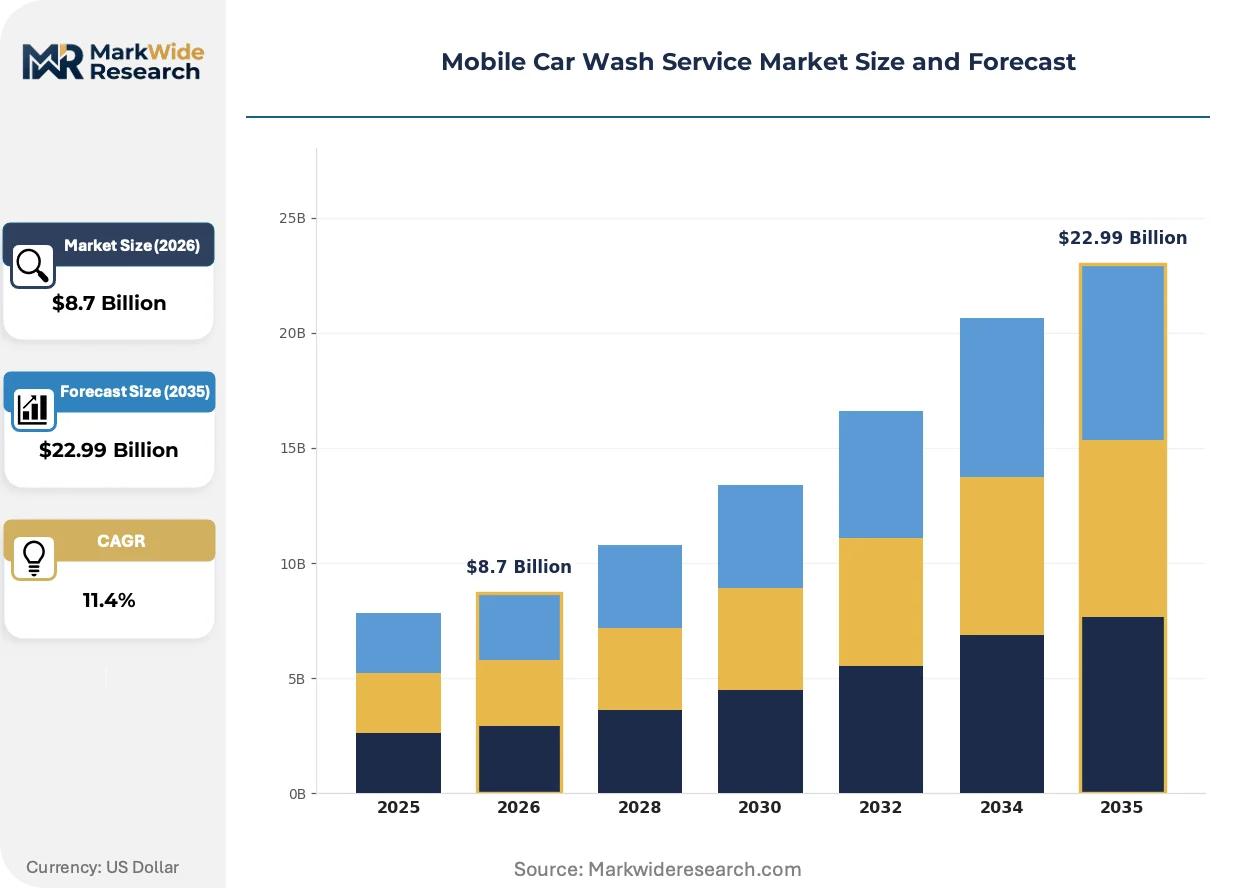
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exterior Cleaning, Interior Detailing, Waxing, Engine Cleaning Customer Type: Individual Owners, Fleet Managers, Commercial Businesses, Dealerships Technology: Pressure Wash Systems, Eco-Friendly Products, Waterless Washing, Mobile Apps Pricing Model: Subscription Plans, Pay-Per-Service, Package Deals, Seasonal Discounts |
| Companies Covered | Washe, DetailXPerts, Spiffy, Wype, GreenSteam, MobileWash, Get Spiffy, Ecoclean, Washos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Car Wash Service Market Evolving Landscape
Equipment miniaturization and sensor integration are redefining operational boundaries for mobile operators, compressing the trade-off between service quality and geographic reach that previously constrained market expansion.
Steam-based cleaning technology is electrifying the competitive landscape for operators serving drought-designated zones. Fleet managers at corporate park installations are specifying thermal methods in vendor qualification requirements. The elimination of water hauling and discharge compliance is compressing per-visit operational overhead while expanding serviceable territory.
The EPA's Clean Water Act discharge standard enforcement is tightening allowable graywater release thresholds for mobile wash runoff. Operators in Texas, Florida, and California face escalating monitoring and reporting obligations. Equipment suppliers are responding with integrated filtration modules that automate compliance documentation.
Subscription billing models are displacing transactional appointment booking among repeat-use customers. Fleet managers and residential subscribers are locking in monthly rates that guarantee technician availability during peak demand windows. This shift is most visible in California's suburban corridors where drought-induced water restrictions have normalized premium pricing for guaranteed service access.
Mobile Car Wash Service Market Segmentation
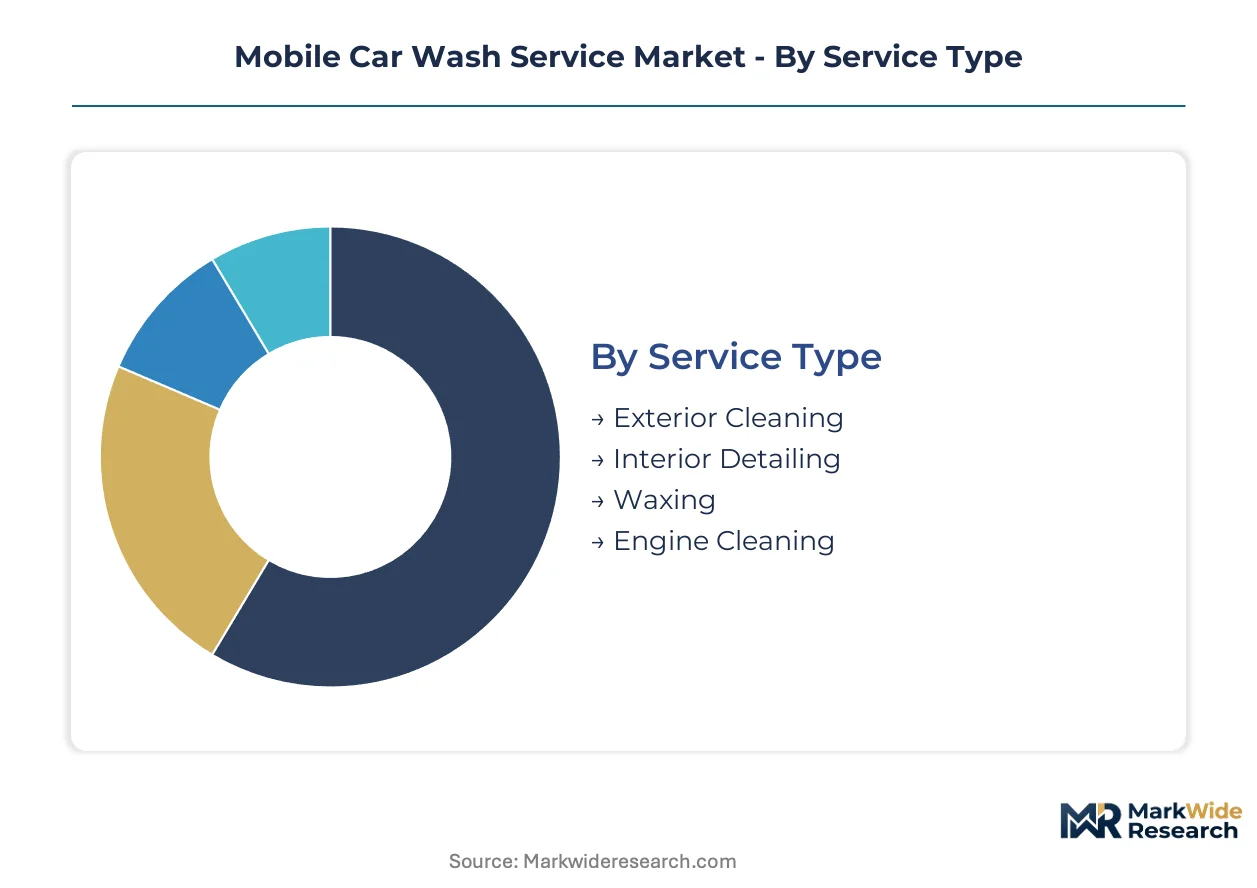
Service differentiation in mobile car washing determines equipment configuration, technician skill requirements, and regulatory exposure. Understanding segment boundaries clarifies where capital deployment yields sustainable returns versus commoditized pressure.
Service Type:
Equipment replacement cycles vary dramatically across service tiers, with high-frequency exterior work demanding more frequent pressure system refurbishment than occasional specialty treatments.
- Exterior Cleaning:Pressure systems operating between 1,200 and 3,000 PSI remove surface contaminants without paint damage. Demand clusters in Texas, Florida, and California suburban corridors where drought restrictions elevate waterless and reclaimed-water alternatives above tunnel wash competition.
- Interior Detailing:Steam-based thermal sanitization penetrates upholstery and ventilation systems without chemical residue. Fleet managers at corporate park installations increasingly specify this method in vendor qualification requirements, eliminating graywater compliance burdens entirely.
- Waxing:Protective coating applications extend paint longevity and command premium pricing during seasonal demand windows.
- Engine Cleaning:Degreasing services require specialized containment and disposal protocols that limit operator participation.
Volume placements concentrate in Exterior Cleaning; the faster expansion belongs to Interior Detailing.
Customer Type:
Margin profiles diverge sharply between fragmented individual purchasers and consolidated institutional accounts with centralized billing infrastructure.
- Fleet Managers:Scheduled rotation programs replace ad hoc individual bookings with predictable recurring revenue streams. Corporate vehicle managers consolidate vendor relationships under multi-year agreements that guarantee technician availability during peak demand windows.
- Individual Owners:Residential subscribers lock in monthly rates through app-based platforms, compressing deadhead miles via route optimization algorithms.
- Commercial Businesses:Facility maintenance contracts bundle vehicle cleaning with property services, creating cross-selling opportunities for multi-service operators.
- Dealerships:Pre-delivery preparation and trade-in reconditioning require rapid turnaround capabilities that favor operators with dedicated capacity allocation.
Revenue concentration sits with Fleet Managers; Individual Owners are climbing the fastest toward parity through subscription model normalization.
Technology:
Capital intensity and regulatory compliance exposure separate technology tiers, with water-handling approaches determining territorial licensing economics.
- Pressure Wash Systems:Self-contained van-mounted configurations integrate portable tanks with reclamation units. EPA Clean Water Act discharge standards constrain graywater release, pushing operators toward closed-loop filtration that automates compliance documentation.
- Eco-Friendly Products:Plant-derived foaming agents cut discharge costs versus petroleum-based predecessors. Biodegradable surfactant chemistry consolidation favors suppliers with vertically integrated raw material sourcing.
- Waterless Washing:Proprietary formulations eliminate hauling and discharge requirements entirely, expanding serviceable territory into drought-designated zones.
- Mobile Apps:Real-time dispatch density sustains route efficiency across metropolitan zones, matching technician location with customer proximity.
Deployment scale favors Pressure Wash Systems; Waterless Washing shows the steepest expansion trajectory as drought conditions intensify.
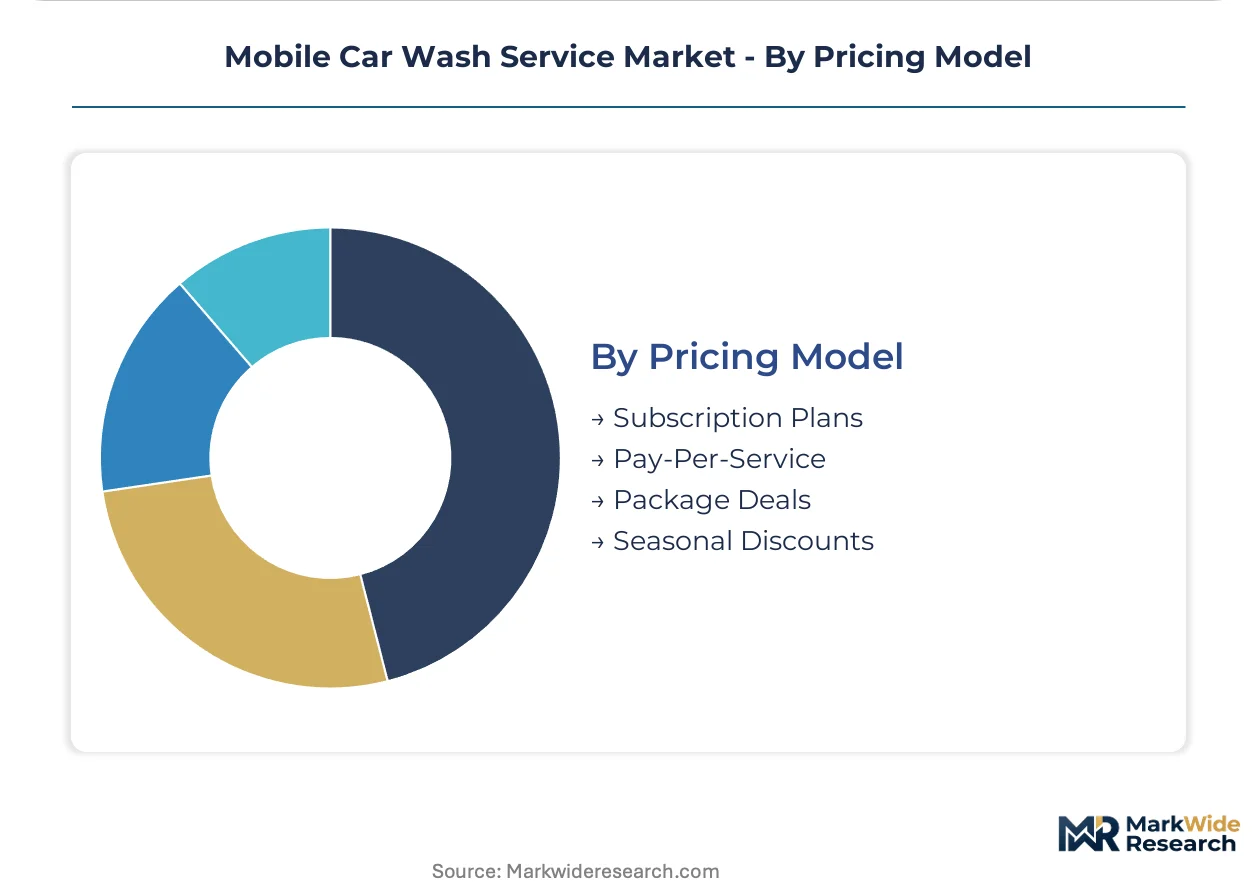
Pricing Model:
Cash flow predictability and customer lifetime value differentiate pricing architectures, with subscription structures capturing superior retention metrics.
- Subscription Plans:Monthly rate locks guarantee service access during restricted water windows. California's State Water Resources Control Board drought permitting has normalized premium pricing for guaranteed availability.
- Pay-Per-Service:Transactional appointment booking persists among price-sensitive consumers in non-drought regions with abundant water supply.
- Package Deals:Bundled exterior-interior combinations improve per-visit revenue while encouraging trial of higher-margin specialty services.
- Seasonal Discounts:Demand smoothing incentives concentrate in winter months when frequency naturally declines.
Customer retention economics favor Subscription Plans; Package Deals are gaining share fastest among operators seeking to elevate average transaction value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in suburban Texas corridors concentrate mobile wash fleet deployment through accelerated depreciation allowances for van-mounted equipment investments.
United States
Vehicle density across Dallas-Fort Worth and Houston suburbs drives scheduled fleet detailing adoption. EPA Clean Water Act discharge standards tighten graywater release thresholds for mobile operators. California's State Water Resources Control Board imposes supplemental permitting in drought-designated zones, accelerating closed-loop system upgrades among Los Angeles and San Diego operators.
Germany
Corporate fleet managers in Munich and Stuttgart specify vendor qualification requirements favoring thermal sanitization methods. REACH chemical registration requirements constrain surfactant formulation choices for operators serving industrial zones. The Bavarian environmental agency enforces stricter water reclamation protocols than federal baselines, concentrating compliant operators around Nuremberg manufacturing corridors.
United Arab Emirates
Dubai's commercial vehicle density and water scarcity create premium pricing tolerance for guaranteed service access. MOHAP guidelines on chemical handling in confined commercial spaces shape technician training requirements. Abu Dhabi's corporate park installations drive fleet centralization contracts with scheduled rotation programs replacing fragmented bookings.
Australia
Drought conditions across New South Wales and Victoria elevate waterless washing alternatives above conventional pressure systems. State-level environmental protection agencies mandate discharge permits for graywater release in Sydney and Melbourne metropolitan zones. Queensland's mining fleet operators contract mobile detailing for heavy equipment maintenance in remote corridor locations.
Canada
Winter demand smoothing challenges concentrate subscription model adoption in Toronto and Vancouver metropolitan areas. Health Canada guidelines on chemical residue in vehicle interiors influence steam-based service specifications. Alberta's oil sector fleet managers negotiate centralized vendor relationships for remote site vehicle upkeep.
Mobile Car Wash Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with app-based dispatch platforms capturing residential subscribers while franchise networks secure corporate fleet accounts. The vendor base organizes around three strategic archetypes: technology-integrated aggregators, equipment-heavy franchise operators, and chemistry-focused waterless specialists. Consolidation pressure concentrates among mid-scale regional players lacking route optimization software or proprietary formulation IP. Dominant competitive moves include vertical integration into equipment supply chains and exclusive territory licensing agreements with municipal franchise authorities.
Among app-based dispatch platforms, Washe and MobileWash exemplify the technology-integrated aggregator archetype, leveraging real-time scheduling algorithms to compress deadhead miles across metropolitan zones. DetailXPerts anchors the equipment-heavy franchise tier with steam-based thermal systems that eliminate graywater compliance burdens. GreenSteam occupies a position within the chemistry-focused specialist segment through proprietary waterless formulations that expand serviceable territory into drought-designated jurisdictions.
| Leading Market Players |
|---|
| Washe |
| DetailXPerts |
| Spiffy |
| Wype |
| GreenSteam |
| MobileWash |
| Get Spiffy |
| Ecoclean |
| Washos |
| Others |
Value Network & Pricing Analysis
Certified technician concentration in California's Los Angeles-San Diego corridor compresses labor-cost differentials that separate premium steam-based detailing from economy pressure-wash tiers. Fleet managers absorb elevated rates for OSHA-credentialed crews while residential subscribers in water-abundant regions trade service frequency for per-visit savings.
Pricing Analysis
Volume placements concentrate in exterior cleaning while interior detailing captures superior per-visit margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by water-handling approach—steam and waterless command premiums, conventional reclamation systems anchor mid-market, basic pressure-wash competes on spot pricing. Cost compression in the economy tier intensifies as tunnel wash operators extend mobile satellite units. Individual owners in Texas and Florida exhibit highest price sensitivity; fleet managers in California drought zones demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from fleet procurement departments mandate multi-supplier qualification for reclamation unit components and biodegradable surfactant chemistry. Manufacturing concentrates in the United States, Germany, and China for pressure systems; plant-derived foaming agents draw from Brazilian and Southeast Asian agricultural feedstocks. Single-source vulnerability concentrates in specialized filtration membrane supply. Distribution runs through regional equipment distributors serving franchise networks and direct-to-operator e-commerce for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician certification timelines constitute the binding capacity constraint, propping pricing for qualified crews as fleet demand outstrips credentialed labor supply.
For Market Incumbents: Acquire route optimization software capabilities to defend density economics against app-based dispatch entrants. Consolidate exclusive territory licensing agreements with Texas municipal franchise authorities before ordinance expansion. Backward integration into reclamation unit maintenance training reduces repair bottlenecks during seasonal demand spikes.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Florida's Orlando-Tampa suburban corridors offers white-space entry for mid-tier scheduled detailing. Waterless washing penetration remains underdeveloped in non-drought southeastern states. Target corporate park installations with bundled exterior-interior subscription pitches to bypass individual customer acquisition costs.
For Investors and Strategic Acquirers: Re-rating potential sits with chemistry-focused specialists given EPA discharge standard tightening as the catalyst. Five-to-ten year viability favors operators with proprietary formulation IP or captive steam-based equipment supply. Watch California State Water Resources Control Board drought designation expansions as the inflection signal for waterless washing demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop System Upgrade | Eliminates EPA Clean Water Act discharge permitting exposure for operators in regulated zones. |
| Steam Equipment Franchise Expansion | DetailXPerts model removes graywater compliance burdens entirely from drought-designated territories. |
| Biodegradable Chemistry Backward Integration | Plant-derived surfactant sourcing cuts input cost volatility versus petroleum-based alternatives. |
| Corporate Fleet Subscription Lock-In | Scheduled rotation programs guarantee technician utilization through California water restriction windows. |
| OSHA Credential Training Program | Standardized safety frameworks reduce onboarding bottlenecks during seasonal demand spikes. |
Research Methodology
Document review covered EPA enforcement actions, state water board permitting databases, and franchise disclosure documents, complemented by interviews with mobile wash fleet operators, equipment distributors, and biodegradable surfactant suppliers. Secondary validation drew from OSHA training records, municipal franchise ordinance filings, and customs data for pressure system imports. Bottom-up technician deployment estimates triangulated against top-down fleet service contract values.
Segment-level projections across service type, customer archetype, water-handling technology, and pricing model fed into aggregate market sizing over the projection horizon. CAGRs derived from equipment replacement cycle analysis and fleet centralization adoption curves. Key inputs included California drought designation timelines, Texas municipal licensing expansion plans, and steam-based cleaning chemistry penetration rates.
Inputs from EPA discharge enforcement records and state-level permitting databases were available through the study window; gaps in real-time fleet operator financial disclosures introduce uncertainty bands around subscription revenue estimates. Forecasts reflect assumptions regarding drought condition persistence and municipal franchise ordinance evolution. A model refresh is warranted upon material change in EPA Clean Water Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
GCC Car Rental Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Automotive Register Market
Automotive Services
Mobility Scooters Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Car Subscription Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Automatic Tire Changer Market